
 Middle East Chocolate Market | 2026-2036
Middle East Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Chocolate Market Insights
The gap between premium and commodity chocolate tiers is broadening as Gulf consumers develop sharper preferences for origin-labeled cocoa and artisanal craftsmanship versus mass-market formulations. Patchi leverages its Beirut heritage and regional boutique network to dominate the luxury gifting segment across the Levant and Gulf states. Ferrero International S.A. anchors its position through controlled hazelnut supply chains and distinctive packaging formats tailored to Eid and Ramadan occasions. Al Nassma Chocolate LLC differentiates as the only large-scale producer using camel milk, occupying a defensible niche in UAE duty-free and hospitality channels.
Chocolate comprises roasted and ground cacao seeds combined with cocoa butter, sugar, and emulsifiers, typically specified at minimum cocoa solids thresholds that determine legal category classification. The manufacturing process involves conching for particle size reduction below 20 microns to achieve smooth mouthfeel, followed by tempering to stabilize cocoa butter polymorphs for shelf stability and snap. Milk Chocolate leads volume throughput across supermarkets and convenience stores, though Dark Chocolate captures expanding margin pools as health-positioned products gain traction in specialty shops. The Price Tier dimension stratifies sharply, with Luxury and Premium tiers commanding disproportionate profitability through seasonal gifting peaks while Economy products compete on volume in hypermarket private-label programs.
SFDA in Saudi Arabia and ESMA in the UAE enforce halal compliance, labeling accuracy, and maximum contaminant limits that govern import clearance and domestic production licensing. FSSAI-aligned standards in some Gulf states create additional testing requirements for microbial thresholds and additive permissibility. Stakeholders must monitor evolving national sweetened product tax frameworks and sugar reduction mandates that could reformulate standard recipes across mid-range and economy portfolios.
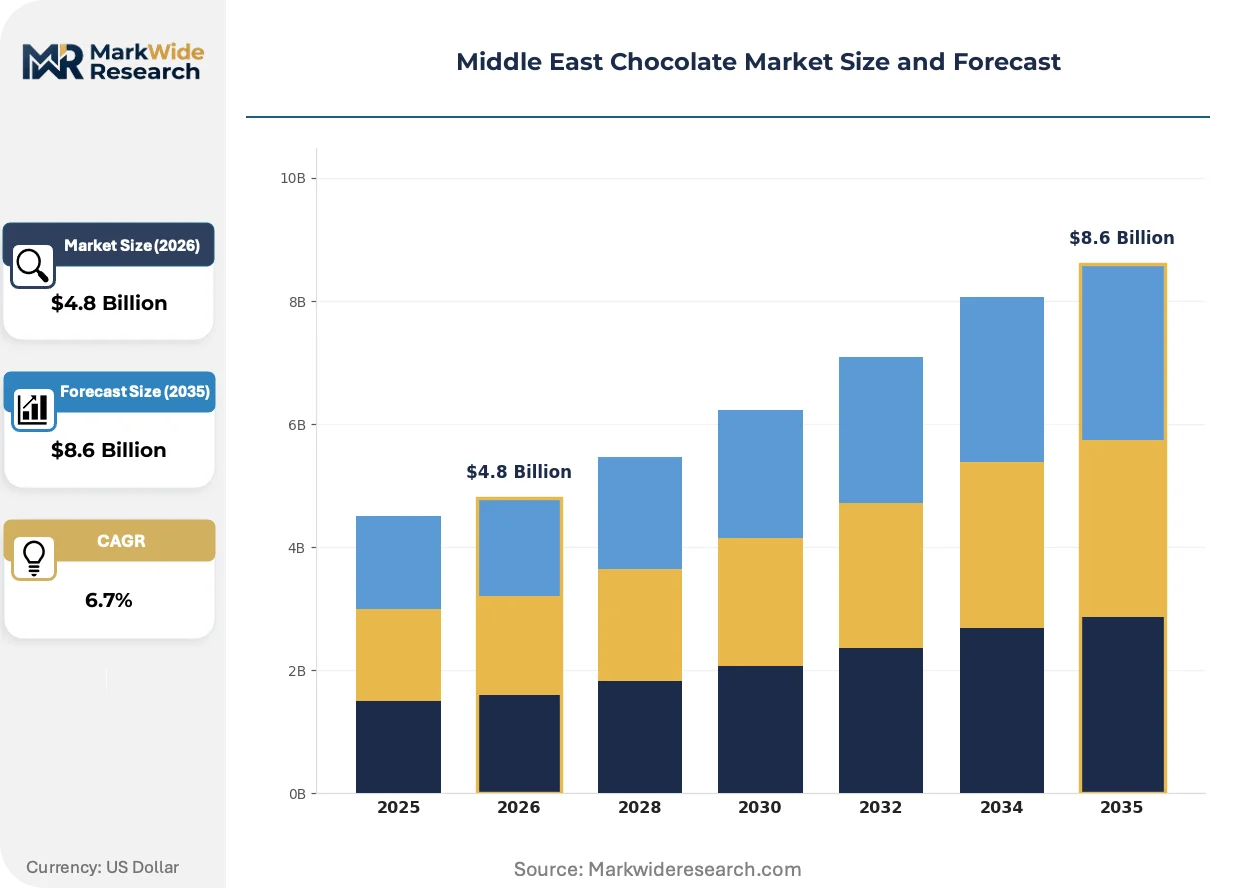
Market Dynamics
Halal certification mandates from SFDA and ESMA are forcing ingredient traceability upgrades across Middle East chocolate supply chains, while premium gifting traditions in Gulf states intensify tiered product stratification between artisanal and mass-market formulations.
Growth Catalysts
- SFDA Halal Enforcement:Saudi Arabia's food regulator mandates segregated production lines and certified ingredient sourcing, compelling manufacturers to invest in dedicated facilities that lock in compliant supply relationships.
- Duty-Free Channel Expansion:Dubai International Airport and Abu Dhabi International Airport are prioritizing confectionery retail space, creating captive audience access for premium chocolate positioned as cultural souvenirs.
- Camel Milk Processing Advances:UAE-based producers have scaled lyophilization and UHT techniques that stabilize camel milk proteins for industrial chocolate applications without flavor degradation.
Market Restraints
- Cocoa Butter Price Volatility:West African supply concentration exposes Middle East converters to ICE futures swings that compress margin on standard milk chocolate formulations.
- Single-Origin Bean Dependence:Ecuador and Ghana account for the majority of fine flavor cacao imports, creating chokepoint risk when port congestion or phytosanitary holds delay shipments through Jebel Ali.
- Sugar Tax Escalation:Saudi Arabia's excise framework on sweetened products adds cost layers that manufacturers must absorb or pass through in price-sensitive hypermarket segments.
Strategic Opportunities
- Qatar Hospitality Buildout:FIFA legacy infrastructure and year-round event calendars are expanding hotel and restaurant chocolate procurement volumes for plated desserts and amenity programs.
- E-Commerce Gifting Platforms:Same-day delivery networks in Riyadh and Dubai enable direct-to-consumer seasonal campaigns that bypass traditional retail slotting fees.
- Functional Ingredient Convergence:Probiotic and adaptogenic formulations are gaining shelf space in UAE pharmacy and wellness retail channels, opening margin pools beyond conventional confectionery.
Industry Challenges
- Halal Audit Timeline Compression:ESMA certification renewals now require on-site facility inspections every 18 months, straining quality assurance staffing across multi-site operations.
- Conching Equipment Lead Times:European machinery suppliers quote 14-month delivery windows for 500kg batch refiners, delaying capacity expansion plans for mid-tier Saudi producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Chocolate Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Shops End User: Retail Consumers, Food Service, Bakeries, Confectioneries Price Tier: Premium, Mid-range, Economy, Luxury |
| Companies Covered | Ferrero International S.A., Patchi, Nestlé S.A., GODIVA Chocolatier, The Hershey Company, Mars, Incorporated, Chocoladefabriken Lindt & Sprüngli AG, Al Nassma Chocolate LLC, Mondelēz International, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Chocolate Market Trends and Innovations
Clean-label ingredient declarations and origin transparency are displacing legacy marketing claims across Middle East chocolate positioning, while digital traceability tools enable real-time compliance verification for halal supply chains.
Precision conching with real-time particle size monitoring is rewriting texture consistency standards in premium chocolate manufacturing. Artisanal producers in Dubai Design District and Riyadh's Diriyah Gate are adopting these systems to achieve sub-18 micron fineness that commands gifting premiums. The technology is compressing quality variation between small-batch and scaled production, enabling regional brands to challenge imported European positioning.
ESMA's 2024 updates to food labeling standards mandate Arabic ingredient disclosure and allergen prominence that exceeds CODEX baseline requirements. Domestic UAE manufacturers face reformulation costs for dual-language packaging compliance, while importers must redesign outer cartons for customs clearance. Dark chocolate positioned for health claims encounters additional substantiation hurdles that delay product registration timelines.
Gifting occasion fragmentation is reshaping procurement patterns across corporate and personal buyer segments. Eid and Ramadan remain volume peaks, but single-serve premium formats for daily self-indulgence are capturing shelf space in Saudi convenience stores. Kuwaiti consumers demonstrate the strongest pivot toward origin-labeled bars with harvest year specificity, pressuring distributors to carry narrower, deeper SKU assortments than the mass-market variety stacks of prior decades.
Middle East Chocolate Market Segmentation
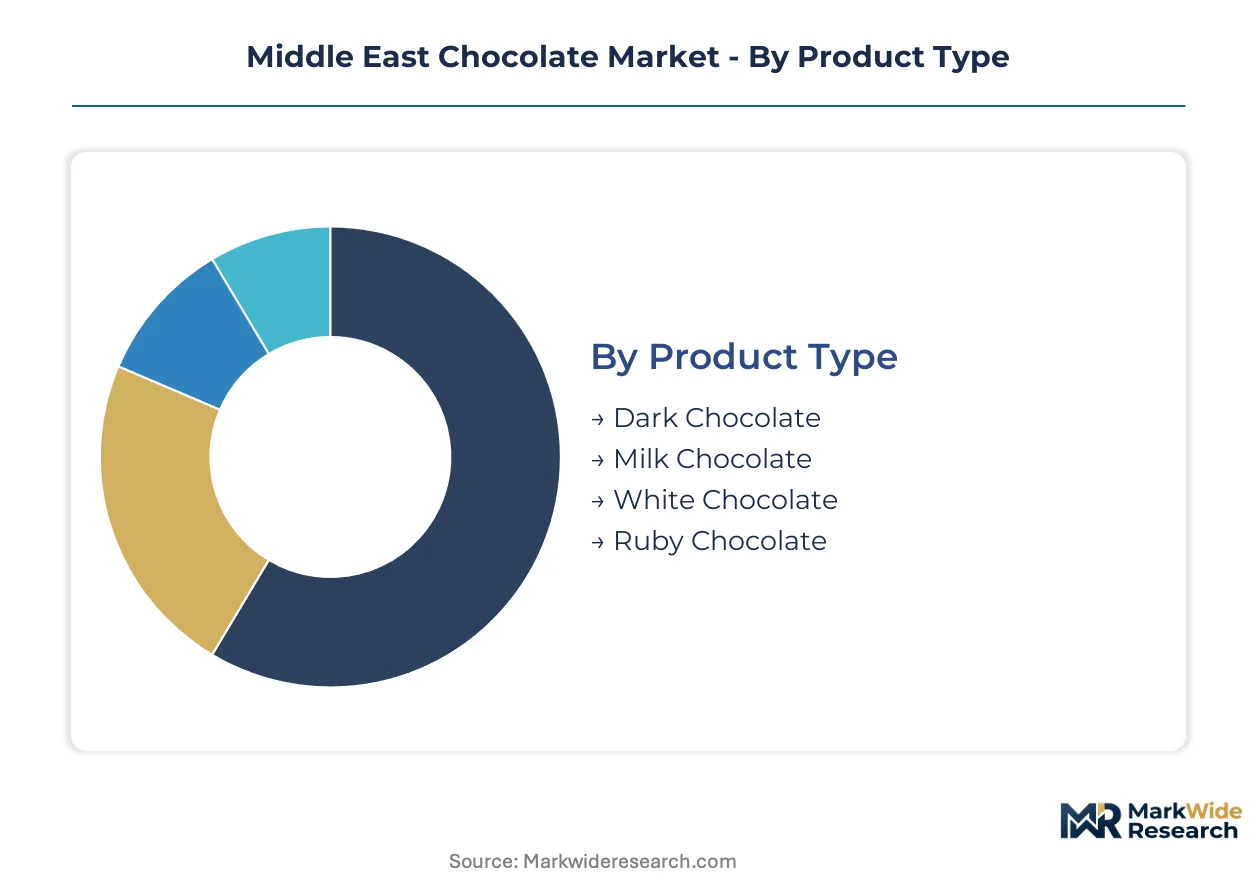
Segmentation in Middle East chocolate markets tracks how halal certification requirements and gifting traditions split demand across distinct technical and commercial boundaries. Manufacturers configure production lines and procurement strategies around these divides to capture margin pools in premium gifting versus volume throughput in everyday consumption.
Product Type:
Cocoa butter concentration and milk solids specification determine halal compliance pathways and equipment requirements across Middle East production facilities.
- Milk Chocolate:Formulated with minimum cocoa solids thresholds balanced against dairy content, this segment dominates supermarket and convenience store volume throughput across Saudi Arabia and UAE. Saudi retail consumers drive the highest per-capita consumption intensity for milk chocolate gifting assortments during Ramadan and Eid occasions.
- Dark Chocolate:Higher cocoa butter ratios and reduced dairy dependence simplify halal certification protocols while enabling health-positioned claims. UAE specialty shops and pharmacy wellness channels are capturing expanding margin pools as Kuwaiti consumers pivot toward origin-labeled bars with harvest year specificity.
- White Chocolate:Cocoa butter base without cocoa solids requires stricter tempering protocols for shelf stability in Gulf climate conditions.
- Ruby Chocolate:Ruby cacao bean processing yields distinctive color without artificial additives, appealing to boutique producers in Dubai Design District.
Today's leader: Milk Chocolate. Tomorrow's challenger: Dark Chocolate.
Distribution Channel:
Channel selection determines captive audience access and slotting fee structures for seasonal gifting campaigns across Middle East urban centers.
- Supermarkets:Hypermarket private-label programs compete on volume with standardized halal-certified formulations, while ESMA labeling mandates enforce Arabic ingredient disclosure compliance. Saudi Arabia's excise framework on sweetened products compresses margins in price-sensitive hypermarket segments.
- Specialty Shops:Curated assortments command gifting premiums through origin transparency and artisanal positioning, with Dubai Design District and Riyadh's Diriyah Gate producers adopting precision conching systems. Kuwait demonstrates the strongest demand for harvest-year-specific origin labeling among Gulf states.
- Online Retailers:Same-day delivery networks in Riyadh and Dubai enable direct-to-consumer seasonal campaigns bypassing traditional retail slotting fees.
- Convenience Stores:Single-serve premium formats for daily self-indulgence are capturing expanded shelf space in Saudi convenience channels.
Specialty shops hold the premium position. Online retailers are climbing the fastest.
End User:
End-use configuration shapes batch size requirements and packaging format specifications across Middle East chocolate procurement.
- Retail Consumers:Gifting occasion fragmentation has expanded beyond Eid and Ramadan peaks into daily self-indulgence formats, with corporate and personal buyer segments demanding narrower, deeper SKU assortments. Saudi consumers concentrate the highest per-capita chocolate consumption intensity in the regional landscape.
- Food Service:Qatar's FIFA legacy infrastructure and year-round event calendars are expanding hotel and restaurant procurement volumes for plated desserts and amenity programs.
- Bakeries:Industrial couverture requirements for tempering stability dominate procurement specifications in UAE and Saudi commercial baking operations.
- Confectioneries:Custom formulation demands for enrobing and molding applications require dedicated halal-certified production line access.
Retail consumers anchor current volume. Food service offers the steepest expansion trajectory.
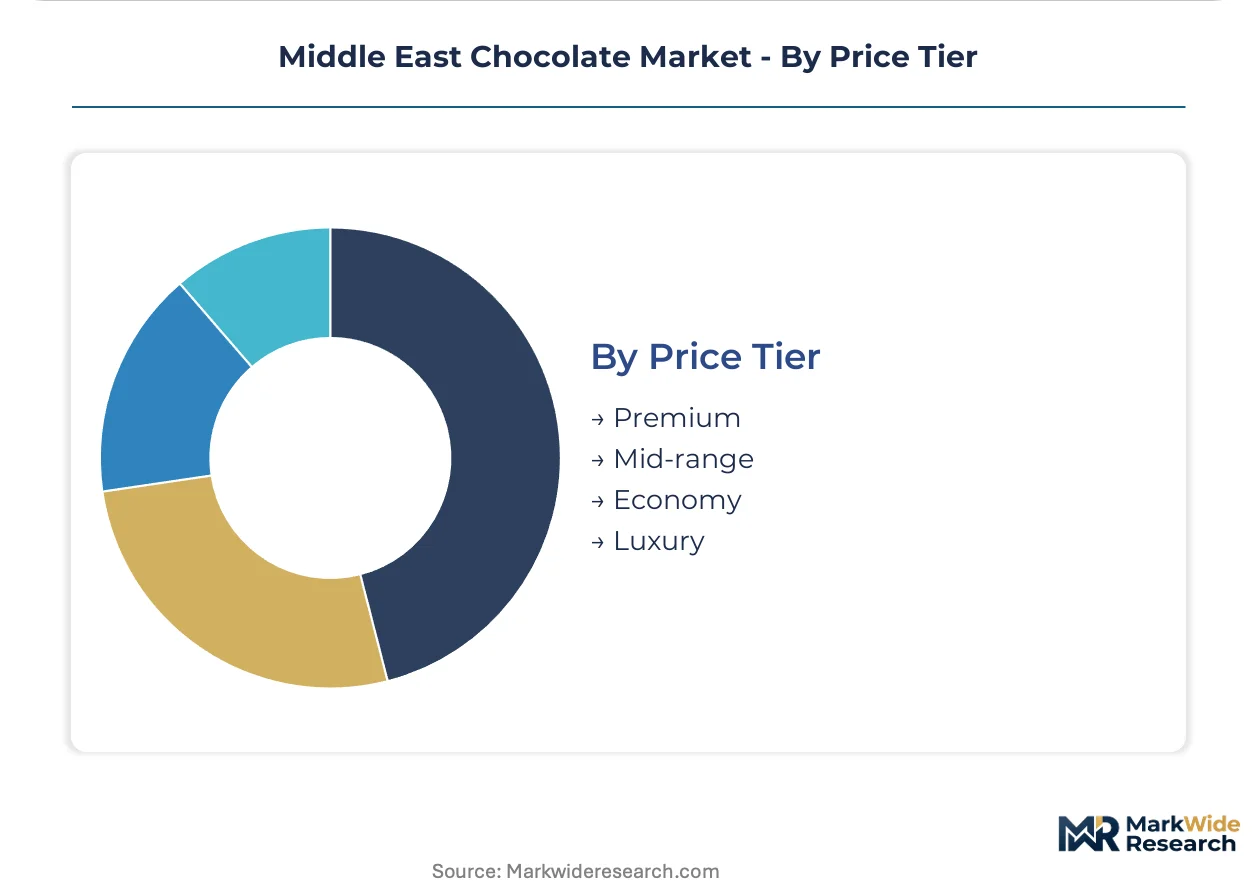
Price Tier:
Price stratification aligns with certification grade complexity and cocoa origin traceability costs across Middle East supply chains.
- Luxury:Artisanal craftsmanship and boutique network positioning dominate Levant and Gulf state gifting segments, with Beirut heritage brands leveraging regional presence for premium placement. Dubai International Airport and Abu Dhabi International Airport captive retail spaces prioritize luxury chocolate as cultural souvenirs.
- Premium:Origin-labeled cocoa and distinctive packaging formats tailored to Eid and Ramadan occasions command disproportionate profitability through seasonal peaks.
- Mid-range:Reformulation pressures from sugar reduction mandates and national sweetened product tax frameworks reshape standard recipes across this tier.
- Economy:Private-label programs compete on volume with compressed margins exposed to cocoa butter price volatility from West African supply concentration.
Luxury commands profitability. Premium is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chocolate manufacturing talent and halal certification expertise concentrate in Gulf metropolitan hubs, with Riyadh, Dubai, and Jeddah anchoring the regional production base.
Saudi Arabia
Retail consumers drive the highest per-capita chocolate consumption intensity across the Middle East, with Ramadan and Eid gifting traditions sustaining year-round demand. SFDA enforces segregated production lines and certified ingredient sourcing that compel dedicated facility investments. Riyadh-based manufacturers are scaling precision conching systems to achieve sub-18 micron fineness for premium positioning.
United Arab Emirates
Dubai International Airport and Abu Dhabi International Airport captive retail spaces prioritize luxury chocolate as cultural souvenirs, expanding duty-free channel volumes. ESMA mandates Arabic ingredient disclosure and allergen prominence that exceeds CODEX baseline requirements, forcing dual-language packaging redesigns. Dubai Design District artisanal producers are adopting real-time particle size monitoring to challenge imported European texture standards.
Qatar
FIFA legacy infrastructure and year-round event calendars are expanding hotel and restaurant procurement volumes for plated desserts and amenity programs. The country's national food regulator enforces halal compliance protocols aligned with GCC standardization frameworks. Doha hospitality clusters are driving industrial couverture demand for tempering-stable formulations in commercial baking operations.
Kuwait
Consumers demonstrate the strongest pivot toward origin-labeled bars with harvest year specificity, pressuring distributors to carry narrower, deeper SKU assortments. National sweetened product tax frameworks add cost layers that manufacturers must absorb or pass through in price-sensitive segments. Kuwait City specialty retail clusters are capturing expanding margin pools for dark chocolate positioned in pharmacy wellness channels.
Lebanon
Beirut heritage brands leverage regional boutique networks to dominate luxury gifting segments across Levant and Gulf states. Central bank foreign currency restrictions complicate cocoa butter import financing for domestic converters. Bekaa Valley processing facilities maintain artisanal craftsmanship traditions despite supply chain disruptions, preserving defensible positioning in premium tier markets.
Middle East Chocolate Market Competitive Landscape
Top-tier vendors anchor the luxury and premium tiers through controlled supply chains and distinctive packaging formats, while mid-tier converters compete on halal certification speed and reformulation agility. The vendor base stratifies sharply between European heritage houses with Gulf distribution partnerships and regional specialists leveraging local ingredient sourcing. Three archetypes dominate: heritage European brands with seasonal gifting positioning, Gulf-based camel milk specialists occupying defensible niches, and Levantine boutique networks emphasizing artisanal craftsmanship. Competitive moves concentrate on M&A for distribution access and capacity expansion for dedicated halal production lines.
Within the heritage European tier, Ferrero International S.A. and Chocoladefabriken Lindt & Sprüngli AG exemplify controlled supply chain strategies that lock in hazelnut and cocoa butter sourcing relationships. Among regional specialists, Al Nassma Chocolate LLC occupies a position as the only large-scale camel milk producer, anchoring UAE duty-free and hospitality channel access. Patchi represents the Levantine boutique archetype, leveraging Beirut heritage and regional boutique network density for luxury gifting placement across Gulf Cooperation Council states.
| Leading Market Players |
|---|
| Ferrero International S.A. |
| Patchi |
| Nestlé S.A. |
| GODIVA Chocolatier |
| The Hershey Company |
| Mars, Incorporated |
| Chocoladefabriken Lindt & Sprüngli AG |
| Al Nassma Chocolate LLC |
| Mondelēz International |
| Others |
Pricing and Supply Chain Analysis
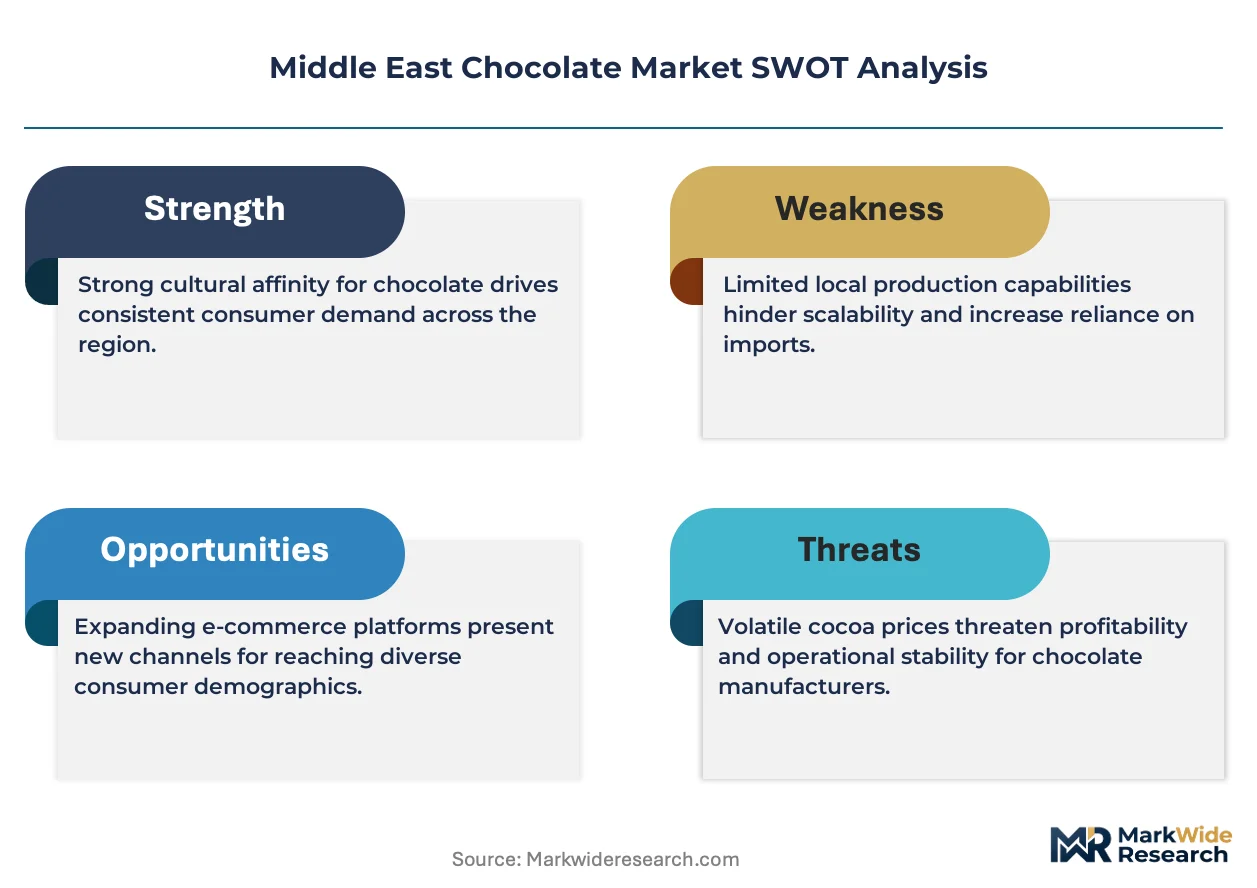
SFDA halal certification mandates gate both qualified supply relationships and premium-tier pricing access, compelling manufacturers to absorb dedicated facility costs that stratify final price positioning across compliant and non-compliant product tiers.
Pricing Analysis
Unbundled ingredient certification costs versus bundled artisanal craftsmanship premiums split the Middle East chocolate market into distinct pricing architectures. Three-tier pricing structure across premium, standard, and economy levels reflects halal audit grade, cocoa origin traceability, and seasonal gifting intensity. Pricing pressure stems from Saudi Arabia's excise framework on sweetened products, compressing margins in hypermarket segments. Economy-tier buyers exhibit highest price sensitivity, while luxury gifting purchasers prioritize provenance over cost.
Supply Chain Analysis
Containerized freight costs through Jebel Ali and port congestion premiums shape landed cocoa butter economics for Middle East converters. West African supply concentration in Ghana and Côte d'Ivoire, coupled with Ecuadorian fine flavor bean dependence, creates chokepoint exposure when phytosanitary holds delay shipments. Raw material sourcing draws from ICE futures markets, European couverture suppliers, and regional camel milk processors. Single-origin bean dependence constitutes the primary structural risk. Distribution runs through duty-free captive retail, hypermarket private-label programs, and direct-to-consumer e-commerce networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East chocolate market functions as a stable compounder, with halal certification requirements creating persistent barriers that protect incumbent returns and sustain premium pricing power.
For Market Incumbents: Extend dedicated halal production line investments into segregated facility networks across Riyadh and Dubai, locking in SFDA and ESMA compliant supply relationships before audit timeline compression intensifies. Deepen backward integration into controlled hazelnut and cocoa butter sourcing to defend margin position against ICE futures volatility. Channel control through boutique network density remains essential as e-commerce gifting platforms erode traditional retail slotting fee advantages.
For New Entrants and Emerging Players: Direct-to-consumer same-day delivery platforms in Riyadh and Dubai offer the most penetrable route for bypassing established retail gatekeepers. Target functional ingredient convergence in UAE pharmacy and wellness channels, where probiotic and adaptogenic formulations command shelf space beyond conventional confectionery. White-space exists in Qatar hospitality procurement following FIFA legacy infrastructure expansion. Corporate gifting accounts represent an underdeveloped segment with fragmented incumbent presence.
For Investors and Strategic Acquirers: Roll-up economics work for regional halal-certified mid-tier producers because ESMA's 18-month audit renewal cycles create compliance moats that scale across acquired facilities. Long-term viability centers on platform consolidation of Saudi and UAE production assets with shared certification infrastructure. Acquisition targets should demonstrate established SFDA relationships and precision conching capability. Watch for camel milk processing patent filings as inflection indicators for defensible niche positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal-Certified Facility Expansion | SFDA segregated production mandates lock in compliant supply relationships and premium-tier access. |
| Precision Conching Technology Adoption | Real-time particle size monitoring enables sub-18 micron fineness that challenges European texture standards. |
| Camel Milk Supply Chain Integration | Lyophilization and UHT stabilization techniques create defensible positioning in duty-free and hospitality channels. |
| Direct-to-Consumer Platform Launch | Same-day delivery networks bypass traditional retail slotting fees and capture seasonal gifting volumes. |
| Functional Ingredient Formulation | Probiotic and adaptogenic convergence opens margin pools in UAE pharmacy and wellness retail channels. |
Research Methodology
Multiple input streams — primary interviews with chocolate manufacturing executives, halal certification auditors, and duty-free retail buyers; secondary validation through customs trade data, ESMA regulatory filings, and Nielsen retail audit records — were reconciled through bottom-up production volume modeling and top-down consumer expenditure triangulation.
Cross-referencing historical consumption patterns against expert panel inputs anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user configuration, and price tier stratification. CAGRs were derived from reconciled volume and value outputs. Forecast inputs incorporated cocoa butter futures volatility curves and seasonal gifting intensity coefficients specific to Ramadan and Eid purchasing cycles.
The model assumes a particular technology adoption path for precision conching and camel milk processing; alternative pathways for lyophilization scale-up would alter the outlook for regional specialty producers. Forecasts reflect assumptions about halal certification timeline stability and excise tax framework persistence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low Calorie Keto Desserts Market
Confectionery
India Industrial Chocolate Market
Confectionery
Truffle Chocolate Market
Confectionery
Crunchy Chocolate Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
North America Dark Chocolate Market
Confectionery
Buttercream Frosting Market
Confectionery
Chocolate Spread Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Brain Mint Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Functional Confectionery Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Low Calorie Sweets Market
Confectionery
Global Compound Chocolate Market