
 Green Tea Chocolate Market | 2026-2036
Green Tea Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Green Tea Chocolate Market Analytics
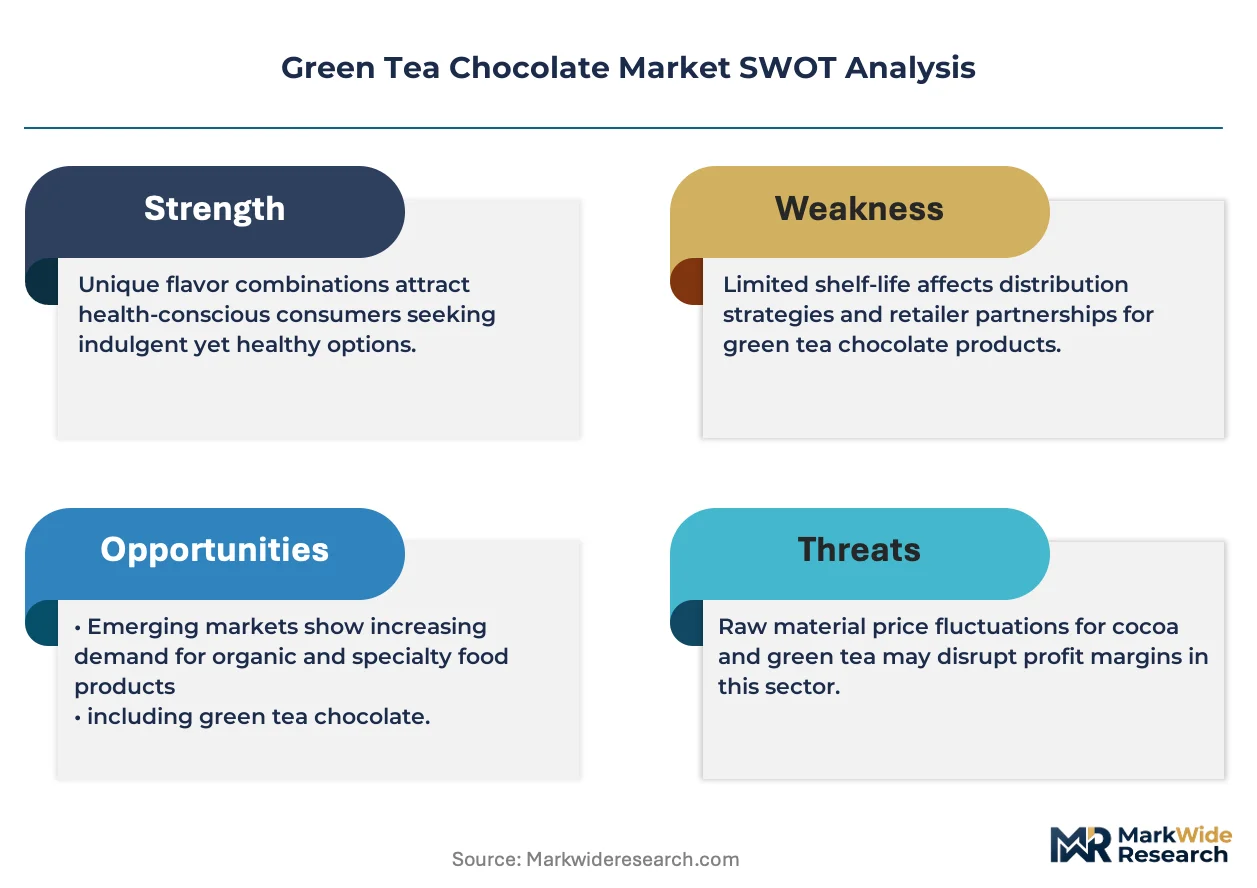
Capital-intensity divergence between mass-market cocoa processors and artisanal matcha specialists is bifurcating competitive dynamics in green tea chocolate. Nestlé leverages integrated bean-to-bar infrastructure across multiple continents to sustain cost advantages in milk chocolate formulations. Royce' anchors premium positioning through Hokkaido-sourced dairy and ceremonial-grade matcha, dominating gift-channel distribution in East Asia.
Green tea chocolate denotes confectionery products incorporating Camellia sinensis leaf extract or powder, typically containing 0.5-3% tea solids by weight and manufactured through controlled-temperature conching to preserve catechin integrity and prevent astringency. The category serves both indulgence-oriented retail consumers and functional-food buyers seeking antioxidant content. Dark chocolate formulations with matcha flavor variation occupy the highest margin tier due to dual health-positioning and lower sugar thresholds, while organic chocolate segments compete on supply-chain transparency rather than unit economics. E-commerce distribution channels are expanding fastest among online shoppers, though supermarkets still control volume throughput for milk chocolate SKUs targeting food services.
FDA GRAS status for green tea extract in confectionery applications governs US market entry, while EFSA health claim regulations constrain antioxidant messaging on European packaging. Japan's Ministry of Agriculture, Forestry and Fisheries (MAFF) and JAS organic standards shape export-grade matcha sourcing requirements for international brands. Stakeholders must monitor evolving catechin concentration caps and origin-label enforcement as botanical ingredient scrutiny intensifies across import jurisdictions.
Market Dynamics
Clean-label ingredient mandates across import jurisdictions are forcing wholesale reformulation of matcha-infused chocolate lines, compressing margins for manufacturers reliant on conventional emulsifiers and synthetic flavor stabilizers.
Growth Catalysts
- EFSA antioxidant health claim frameworks:Permitted catechin-content messaging on European packaging enables dual-positioning for functional-food buyers seeking verified wellness benefits.
- Ceremonial-grade matcha concentration in Uji and Nishio:Proximity to heritage cultivation zones gives Japanese manufacturers sourcing advantages for premium gift-channel SKUs.
- Controlled-temperature conching advances:Precision thermal management during chocolate processing preserves epigallocatechin gallate integrity without astringency development.
Market Restraints
- Single-origin matcha supply concentration:Dependence on Japanese and Chinese leaf processors creates vulnerability to harvest volatility and trade friction.
- FDA GRAS notification thresholds:Green tea extract concentration caps in US confectionery applications limit formulation flexibility for high-catechin positioning.
- Organic cacao butter cost premiums:JAS and EU organic certification requirements for clean-label SKUs inflate input costs versus conventional milk chocolate bases.
Strategic Opportunities
- White-label matcha sourcing in Vietnam:Emerging highland cultivation outside traditional Japanese zones offers cost-competitive ceremonial-grade supply for mid-market entrants.
- Direct-to-consumer subscription channels:Recurring revenue models bypass supermarket slotting fees and capture lifetime value from wellness-oriented repeat buyers.
- EU Green Deal sustainable packaging mandates:Compostable wrapper requirements favor early movers with integrated bio-material supply chains.
Industry Challenges
- Cross-functional formulation expertise scarcity:Confectionery chemists with simultaneous competency in chocolate rheology and tea polyphenol stability command premium compensation.
- Dual-certification timeline compression:Parallel pursuit of JAS organic and Fairtrade cocoa credentials extends new product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Tea Chocolate Market |
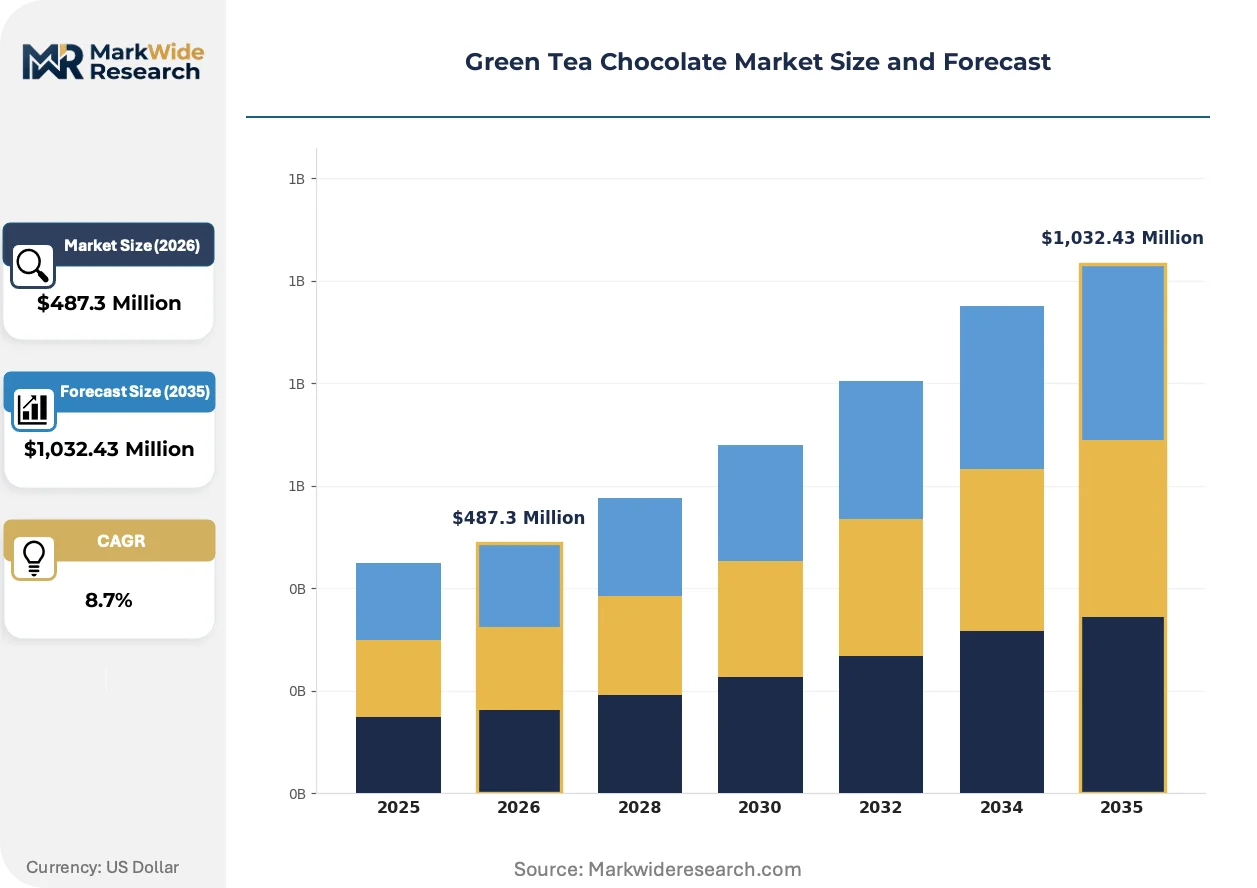
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Organic Chocolate End User: Retail Consumers, Food Services, Health Stores, Online Shoppers Distribution Channel: Supermarkets, Convenience Stores, Specialty Shops, E-commerce Flavor Variation: Matcha, Jasmine, Mint, Citrus |
| Companies Covered | Nestlé, Meiji Holdings, Lindt & Sprüngli, Mars, Royce', Lotte Confectionery, Mondelez International, Hershey, Galler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Tea Chocolate Market Evolving Landscape
Formulation science and distribution architecture are undergoing simultaneous transformation as botanical ingredient scrutiny intensifies and direct-channel economics reshape go-to-market economics for premium confectionery.
Microencapsulation of matcha polyphenols using lipid-based carrier systems is displacing conventional dry-powder blending in high-margin dark chocolate formulations. Artisanal manufacturers in Kyoto and Seoul are adopting spray-chilled lipid shell technologies to mask bitterness while extending shelf-stable catechin activity. This encapsulation advance is displacing legacy flavor-masking approaches dependent on sugar and dairy fat loads.
REACH-compliant botanical extract documentation requirements are mandating full supply-chain traceability for green tea leaf sourcing into European confectionery. EFSA novel food consultation pathways now govern matcha varieties outside traditional Camellia sinensis cultivars, adding regulatory overhead for innovation pipelines. Premium dark chocolate SKUs with origin-specific matcha claims face the steepest compliance burden and are consolidating supplier relationships to reduce audit fragmentation.
Wellness-oriented buyers are unbundling impulse confectionery purchases from planned antioxidant supplementation routines, creating distinct occasion-based segmentation. Supermarket milk chocolate SKUs targeting food services are losing velocity to curated online assortments emphasizing single-origin matcha provenance and third-party catechin verification. South Korean e-commerce platforms and Japanese subscription services are capturing the most concentrated migration of high-loyalty functional-food consumers.
Green Tea Chocolate Market Segmentation
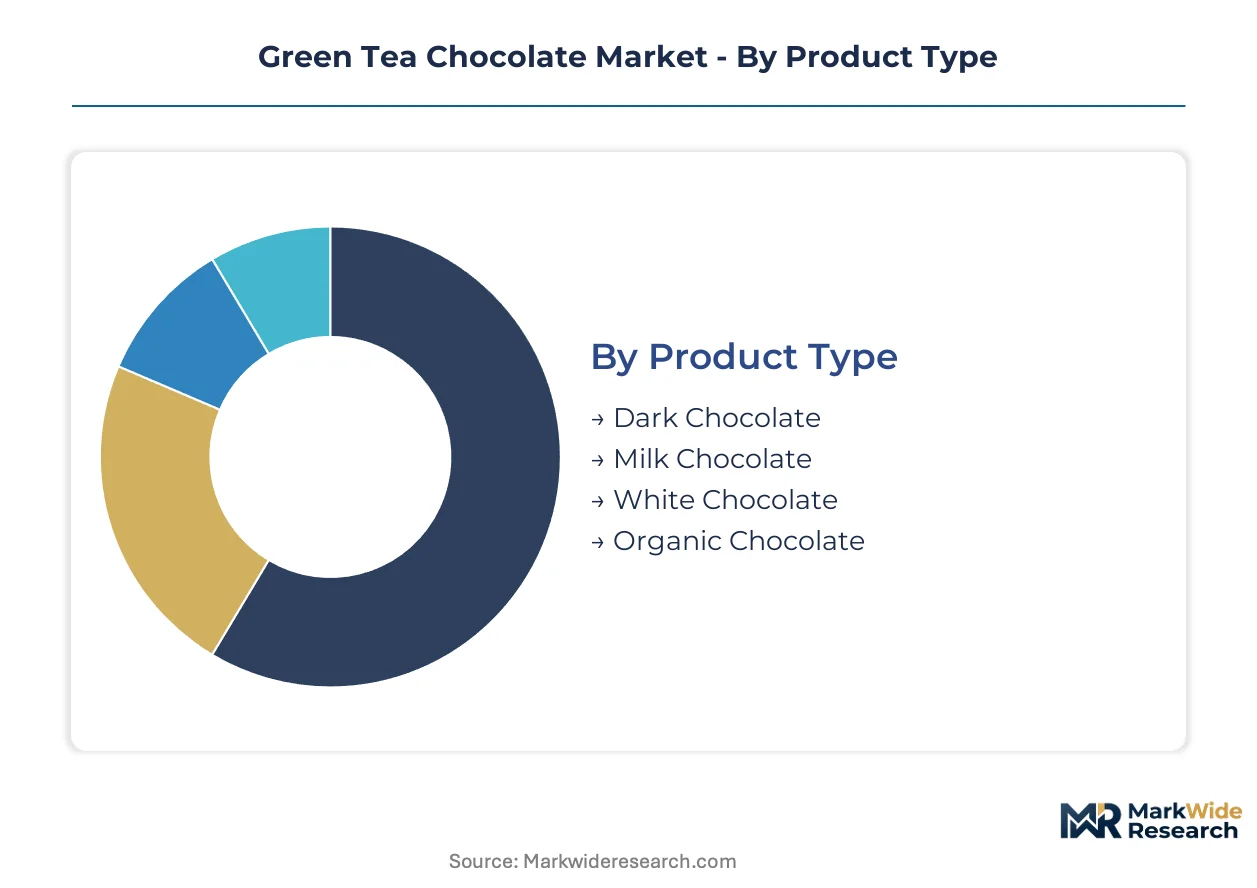
Green tea chocolate segmentation reflects divergent supply chain configurations across export-oriented ceremonial-grade formulations and domestically consumed mass-market SKUs. Category boundaries increasingly blur as functional-food positioning penetrates conventional confectionery channels.
Product Type:
Dark chocolate variants dominate export flows to European and North American wellness markets, while milk chocolate SKUs anchor domestic consumption across East Asian retail networks.
- Dark Chocolate:Formulations with 70%+ cacao content and 1-3% ceremonial-grade matcha achieve the highest catechin retention through controlled-temperature conching. Demand concentrates in German and French health-food retail where EFSA antioxidant messaging compliance enables premium positioning.
- Milk Chocolate:Lower cacao butter ratios accommodate higher matcha loading without excessive bitterness, though Hokkaido-sourced dairy requirements constrain Japanese manufacturers to domestic and regional Asian distribution.
- White Chocolate:Cocoa butter base without cacao solids permits vivid green color presentation but sacrifices dual antioxidant claims; popular in Korean gift-channel assortments.
- Organic Chocolate:JAS and EU organic certification requirements extend development timelines; appeals to transparency-focused buyers in Swiss and Austrian specialty retail.
Dark chocolate holds the largest share; momentum sits with organic chocolate as clean-label mandates intensify across import jurisdictions.
End User:
Cost tier stratification separates impulse-driven supermarket purchases from subscription-based wellness routines with lifetime value multiples.
- Retail Consumers:Supermarket and convenience channel buyers purchasing 50-100g bars for immediate consumption; price-sensitive segment driving volume in Japanese kombini networks.
- Food Services:Dessert manufacturers and café chains sourcing 5-10kg couverture blocks for pastry applications; concentrates in Seoul and Tokyo metropolitan bakery clusters.
- Health Stores:Third-party catechin verification and single-origin matcha provenance command 40-60% price premiums over conventional retail; expanding fastest among German drugstore chains.
- Online Shoppers:Direct-to-consumer subscription models bypass slotting fees; South Korean platforms capture highest functional-food loyalty migration.
Retail consumers anchor volume throughput; online shoppers are expanding most quickly as wellness-oriented buyers unbundle planned supplementation from impulse purchases.
Distribution Channel:
Volume scale differentiates mass-market throughput from curated specialty penetration with divergent margin profiles.
- Supermarkets:Control 70%+ of milk chocolate SKU velocity in Japan; slotting fees and promotional calendar dependencies compress net margins for matcha-infused lines.
- Convenience Stores:Kombini chains in Tokyo and Osaka drive single-serve 30g bar consumption; limited shelf space favors established brand recognition.
- Specialty Shops:Kyoto and Seoul artisanal chocolatiers command 3-5x supermarket price points through ceremonial-grade sourcing narratives and in-store tasting experiences.
- E-commerce:Subscription and curated assortment models capture highest catechin-verification SKU attachment; bypasses geographic constraints on specialty retail access.
Supermarkets retain the largest share; e-commerce gains share fastest as direct-channel economics reshape go-to-market strategies for premium positioning.
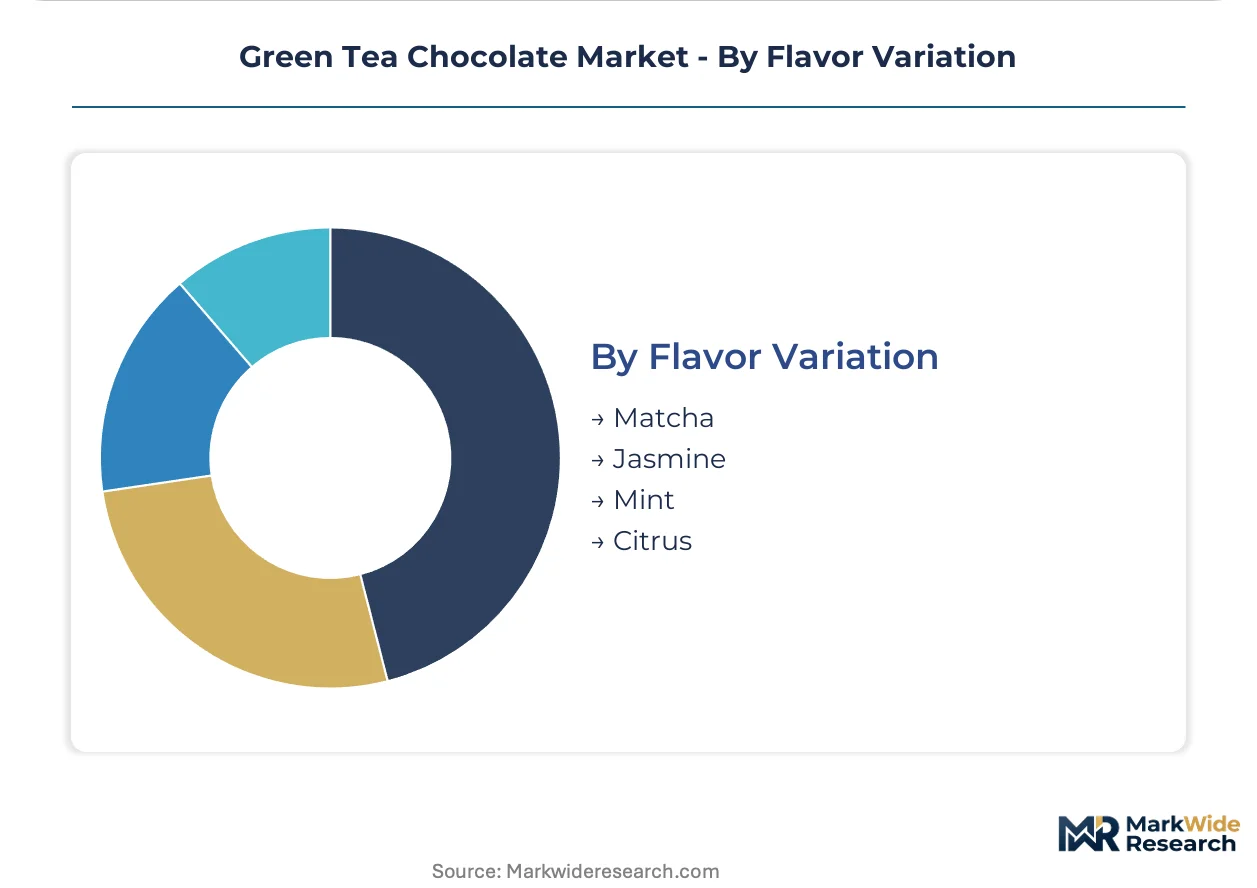
Flavor Variation:
Application maturity separates heritage matcha formulations from experimental botanical extensions with shorter commercialization histories.
- Matcha:Ceremonial-grade Uji and Nishio sourcing anchors premium tier; microencapsulation advances now mask residual bitterness without sugar load increases.
- Jasmine:Scented tea infusion creates aromatic differentiation; limited to gift-channel SKUs in Chinese and Taiwanese export markets due to narrower Western palate acceptance.
- Mint:Cross-category familiarity reduces education costs; popular in North American seasonal assortments.
- Citrus:Yuzu and sudachi variants target Japanese domestic novelty seekers; perishable oil components constrain shelf-stable formulation options.
Matcha dominates revenue concentration; citrus exhibits the steepest expansion trajectory as regional flavor experimentation penetrates premium lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese manufacturers command 40-60% price premiums in European health-food retail, while Vietnamese highland matcha cultivation is compressing input costs for mid-market entrants across Southeast Asian export channels.
Japan
MAFF JAS organic certification and ceremonial-grade Uji matcha sourcing anchor premium gift-channel positioning. Tokyo and Osaka kombini chains drive single-serve 30g bar velocity through established brand recognition. Kyoto artisanal chocolatiers exploit proximity to Nishio heritage cultivation zones for in-store tasting experiences.
South Korea
Seoul metropolitan bakery clusters concentrate food services demand for 5-10kg couverture blocks. MFDS food additive regulations govern green tea extract concentration thresholds in domestic confectionery applications. Busan-Ulsan logistics hubs facilitate e-commerce platform distribution capturing functional-food loyalty migration.
Germany
EFSA antioxidant health claim frameworks enable catechin-content messaging compliance for premium dark chocolate positioning. REACH botanical extract documentation mandates full supply-chain traceability for matcha leaf sourcing. Berlin and Munich health-food retail chains command third-party verification premiums over conventional supermarket SKUs.
United States
FDA GRAS notification thresholds constrain high-catechin formulation flexibility for wellness-oriented positioning. California and New York Metro specialty retail channels drive organic chocolate segment expansion. Direct-to-consumer subscription models bypass supermarket slotting fees in Pacific Coast urban markets.
Vietnam
Emerging highland matcha cultivation outside traditional Japanese zones offers cost-competitive ceremonial-grade supply. Domestic processors lack JAS organic certification infrastructure for export-grade positioning. Da Lat and Lam Dong province clusters supply mid-market private-label programs for regional Southeast Asian chocolate manufacturers.
Green Tea Chocolate Market Competitive Landscape
Concentration sits with diversified confectionery conglomerates and specialized East Asian premium brands. The vendor base spans integrated bean-to-bar operators, regional dairy-integrated specialists, and private-label matcha sourcing intermediaries. Three archetypes dominate: multinational cocoa processors leveraging continental infrastructure, Japanese ceremonial-grade specialists controlling gift-channel distribution, and emerging Vietnamese cultivator-processors competing on input cost. Capacity expansion and strategic partnerships represent the dominant competitive moves, with backward integration into matcha leaf processing gaining traction.
Among diversified multinational conglomerates, Nestlé and Mondelez International exemplify scale-driven archetypes with integrated continental manufacturing footprints. Japanese specialists Royce' and Meiji Holdings occupy premium-tier positions through Hokkaido dairy integration and ceremonial-grade matcha sourcing narratives. Lindt & Sprüngli represents the European premium dark chocolate archetype navigating EFSA compliance frameworks for antioxidant positioning.
| Leading Market Players |
|---|
| Nestlé |
| Meiji Holdings |
| Lindt & Sprüngli |
| Mars |
| Royce' |
| Lotte Confectionery |
| Mondelez International |
| Hershey |
| Galler |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Japanese ceremonial-grade matcha processors anchors price floors across premium chocolate tiers, compressing margins for mid-market entrants unable to secure long-term offtake agreements with Uji or Nishio cultivators.
Pricing Analysis
The customization-premium spread separates configured-to-order ceremonial-grade formulations from standard milk chocolate SKUs. Three-tier pricing structure across premium, standard, and economy levels reflects JAS organic certification status and single-origin matcha provenance claims. Pricing pressure stems from Vietnamese highland matcha flooding mid-market channels with cost-competitive supply. Retail consumers in Japanese kombini networks exhibit highest price sensitivity, while German health-store buyers tolerate 40-60% premiums for third-party catechin verification.
Supply Chain Analysis
Strait of Malacca transit underwrites logistics costs for Southeast Asian cacao butter imports into East Asian processing facilities. Supply concentrates in Japan, China, and Vietnam for matcha leaf sourcing, with Hokkaido dairy anchoring Japanese milk chocolate production. Raw material dependencies include ceremonial-grade Camellia sinensis, organic cacao butter, and lipid-based microencapsulation carriers. Single-source vulnerability to Japanese harvest volatility threatens formulation continuity. Distribution runs through supermarket slotting-fee structures for volume SKUs and direct-to-consumer subscription channels for premium positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as post-pandemic wellness routines normalize antioxidant supplementation into planned consumption rather than impulse indulgence.
For Market Incumbents: Shield premium positioning through captive supply agreements with heritage cultivation zones in Uji and Nishio, insulating against Vietnamese cost competition. Deepen backward integration into matcha leaf processing to compress dual-certification timelines and accelerate product development cycles.
For New Entrants and Emerging Players: Lead with white-label matcha sourcing from Da Lat highland clusters to penetrate Southeast Asian private-label programs before JAS certification infrastructure matures. Target South Korean e-commerce platforms with subscription-based catechin-verified assortments, capturing functional-food loyalty migration away from supermarket impulse channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription archetypes with third-party antioxidant verification, offering superior cash-flow quality against transactional retail models. Acquisition targets should demonstrate integrated microencapsulation capabilities and REACH-compliant supply-chain documentation. Monitor EFSA novel food consultation pathways as inflection indicators for regulatory overhead expansion on non-traditional matcha cultivars.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Matcha Processing | Captive supply from Vietnamese highland cultivation compresses input costs for mid-market entrants. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and captures lifetime value from wellness-oriented repeat buyers. |
| Dual Certification Investment (JAS Organic + Fairtrade) | Extends development timelines but unlocks 40-60% price premiums in German health-food retail. |
| Microencapsulation Technology Licensing | Spray-chilled lipid shell systems from Kyoto specialists mask bitterness without sugar load increases. |
| Sustainable Packaging Transition | EU Green Deal compostable wrapper mandates favor early movers with integrated bio-material supply chains. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, EFSA health claim registrations, MAFF export certifications, and customs trade data for matcha leaf and cacao butter flows. Interviews with confectionery R&D directors, procurement leads at premium chocolate manufacturers, JAS organic certifiers, and e-commerce platform category managers inform supply-chain and channel dynamics. Bottom-up SKU-level volume triangulation against top-down category value estimates validates market sizing.
Segmentation dimensions modeled include product type (dark, milk, white, organic), end-user archetype (retail, food services, health stores, online), distribution channel structure, and flavor variation maturity. CAGRs derive from trend-line analysis of historical consumption patterns adjusted for regulatory catalysts and channel-shift elasticity across the projection horizon. Forecast inputs incorporate ceremonial-grade matcha supply concentration indices and EFSA antioxidant messaging compliance penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained JAS organic certification enforcement and stable East Asian trade flows would require recalibration. Forecasts reflect documented assumptions regarding catechin retention technology diffusion and clean-label mandate adoption timelines. Practitioners should keep alternative scenarios live as botanical ingredient scrutiny intensifies across import jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
Caramel Chocolate Market
Confectionery
Functional Confectionery Market
Confectionery
Edible Glitter Market
Confectionery
Low-Fat Sweets Market
Confectionery
Global Mochi Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Citrus Gummies Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
Mooncake Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
South Africa Confectionery Market
Confectionery
Confectionery Fillings Market
Confectionery
Buttercream Frosting Market
Confectionery
UK Confectionery Market
Confectionery
Middle East Chocolate Market