
 Global Industrial Chocolate Market | 2026-2036
Global Industrial Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Chocolate Market Intelligence
The consolidation among large food processing companies, countered by a rising number of specialized pastry shops, is rebalancing buyer power. Barry Callebaut AG leverages its massive scale in cocoa processing and supply. Cargill Incorporated differentiates through its extensive ingredient portfolio and logistics network. Mondelez International Inc competes by integrating industrial chocolate into its global confectionery brands.
Industrial chocolate refers to chocolate sold in bulk formats, such as blocks or callets, to other businesses rather than directly to consumers. Its formulation, defined by specific cocoa butter percentages and viscosity levels, is optimized for large-scale production equipment in confectionery and bakery applications. Couverture chocolate, with its higher cocoa butter content, commands premium pricing and serves high-end applications. The confectionery application segment remains the dominant consumer of industrial chocolate, followed closely by bakery.
Food safety and labeling standards, enforced by bodies like the U.S. FDA and Europe's EFSA, govern market access. New EU regulations on deforestation-free supply chains are creating significant compliance challenges for cocoa sourcing. Suppliers must now navigate the complex trade-off between securing traceable, sustainable cocoa and managing input cost volatility for their food processing clients.
Market Dynamics
The central structural force shaping the market is the mandatory shift towards demonstrable supply chain sustainability. New regulations, particularly the EU Green Deal, are compelling a complete overhaul of cocoa sourcing, traceability, and documentation protocols for all suppliers.
Growth Catalysts
- Premium Bakery Inclusions:Demand from the artisanal and industrial bakery segment for high-cocoa-content callets and blocks is expanding volume, especially for products used in pastries, cakes, and breads that command a higher price point.
- Clean-Label Formulations:Consumer demand for simple, recognizable ingredients is compelling food manufacturers to seek industrial chocolates with fewer additives, driving growth for single-origin and organic-certified bulk chocolate products.
- Food Processing Expansion:The development of large-scale food processing infrastructure in Southeast Asian and Middle Eastern economies creates new, high-volume geographic markets for industrial chocolate suppliers beyond established European centers.
Market Restraints
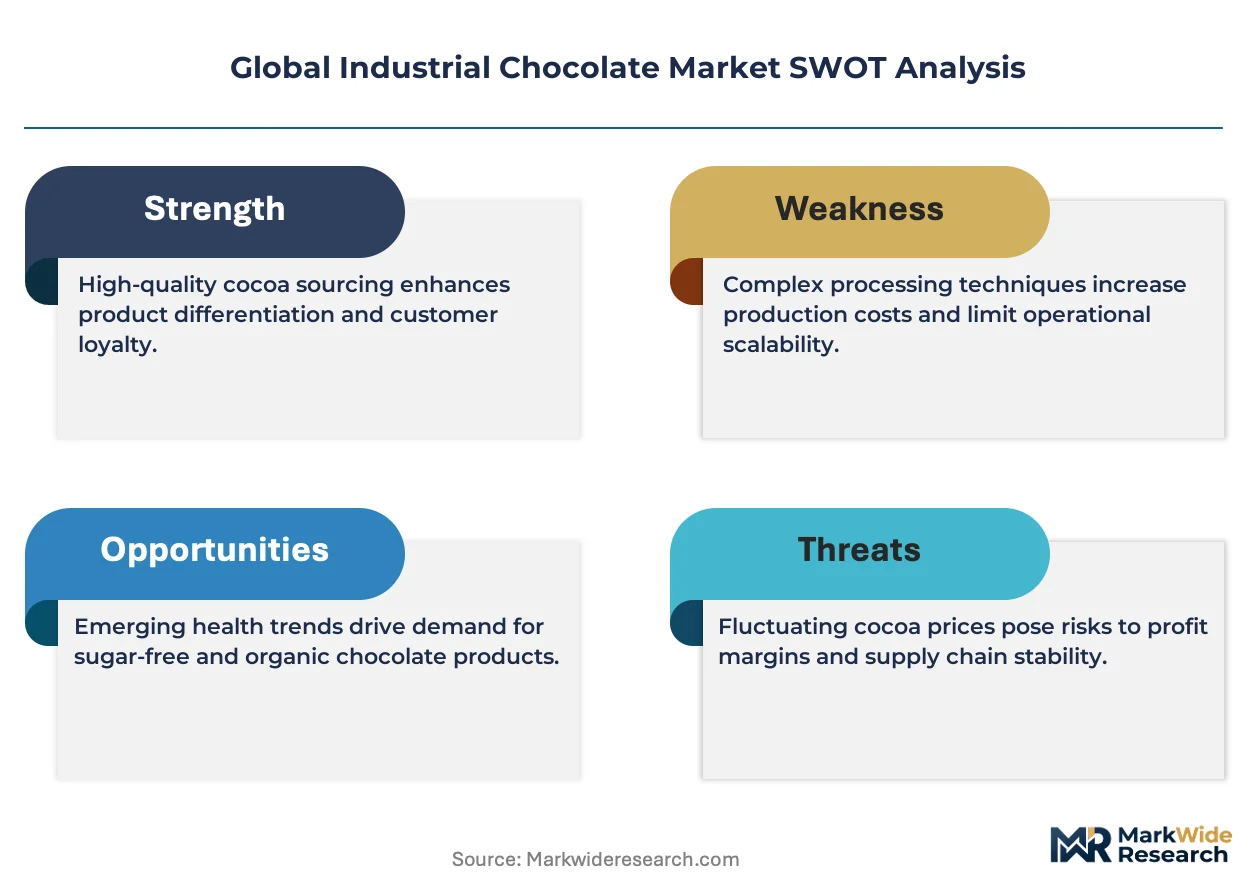
- Cocoa Price Volatility:Extreme price fluctuations for cocoa beans, the primary raw material, create significant margin pressure and forecasting challenges for industrial chocolate producers and their food processing clients.
- Concentrated Sourcing Risk:The geographic concentration of cocoa cultivation in a few West African nations, such as Ivory Coast and Ghana, exposes the entire supply chain to risks from climate events, crop disease, and political instability.
- Regulatory Compliance Costs:New deforestation-free regulations from the European Union introduce substantial administrative and technological costs for verifying and documenting the origin of every cocoa shipment, impacting operational efficiency.
Strategic Opportunities
- Plant-Based Chocolate:Formulating industrial chocolate using alternative milk powders like oat, almond, or soy opens a significant growth area to serve the expanding vegan and plant-based food manufacturing sector.
- High-End Food Service:Supplying couverture and specialty chocolates to the growing high-end hospitality and restaurant sector in markets like the UAE and Saudi Arabia provides a channel for premium, high-margin products.
- Blockchain for Traceability:Implementing blockchain technology offers a method to provide immutable, verifiable proof of origin and compliance with sustainability standards, creating a competitive advantage with large food processing clients.
Industry Challenges
- Traceability System Implementation:The operational challenge involves deploying and scaling complex digital traceability systems across fragmented supply chains with thousands of smallholder farms to meet new regulatory mandates like the EUDR.
- Skill Gap in Sustainability:A scarcity of professionals with combined expertise in agronomy, supply chain logistics, and sustainability compliance hinders the ability of suppliers to effectively manage ethical sourcing programs at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Chocolate Market |
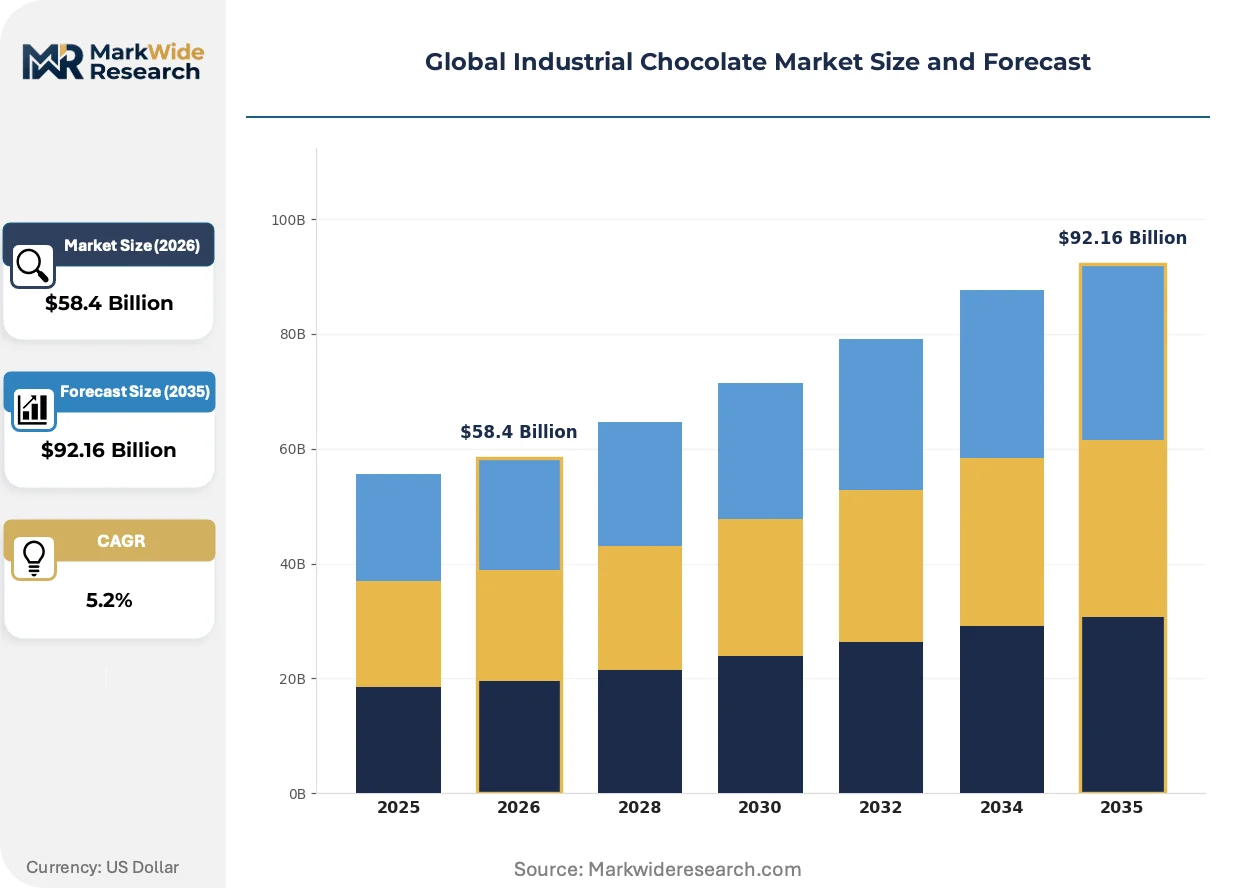
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $92.16 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Couverture, Compound, Cocoa Mass, Cocoa Butter, Baking Chocolate Application: Confectionery, Bakery, Beverage, Dairy Products, Ice Cream Manufacturing End User: Chocolate Manufacturers, Food Processing Companies, Pastry Shops, Beverage Producers Packaging Type: Bulk Bags, Retail Packs, Tins, Pouches, Drums |
| Companies Covered | Barry Callebaut AG, Cargill Incorporated, Cémoi Group, Fuji Oil Holdings Inc, Mondelez International Inc, Mars Incorporated, Nestlé S.A., The Hershey Company, Chocoladefabriken Lindt & Sprüngli AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Chocolate Market Strategic Shifts & Innovations
A fundamental tension between the pursuit of industrial efficiency and the growing mandate for ethical, transparent sourcing defines the market's evolution. Innovations focus on resolving this conflict through new technologies, while regulatory and demand-side shifts force greater accountability.
Precision fermentation techniques are emerging to create novel cocoa-free base ingredients with chocolate-like flavor profiles. Food technology startups and specialized ingredient labs are pioneering this approach for confectionery applications. This innovation is decentralizing flavor creation away from purely agricultural commodity cycles, offering a path to more stable, predictable, and sustainable raw material inputs.
The U.S. FDA is intensifying its guidance and enforcement regarding heavy metal limits, specifically for cadmium and lead, in dark chocolate and cocoa powder. This action forces suppliers to invest in rigorous soil analysis and selective sourcing from cocoa-growing regions with lower natural soil contamination. Products with high cocoa content are most affected by this scrutiny.
Food processing clients are moving away from purely transactional purchasing toward collaborative co-development partnerships for new product lines. This model is displacing traditional, price-driven procurement by embedding chocolate suppliers into the client's innovation process for bakery and confectionery goods. The shift is most visible in Europe, where brands seek customized formulations and transparent supply chains.
Global Industrial Chocolate Market Segmentation
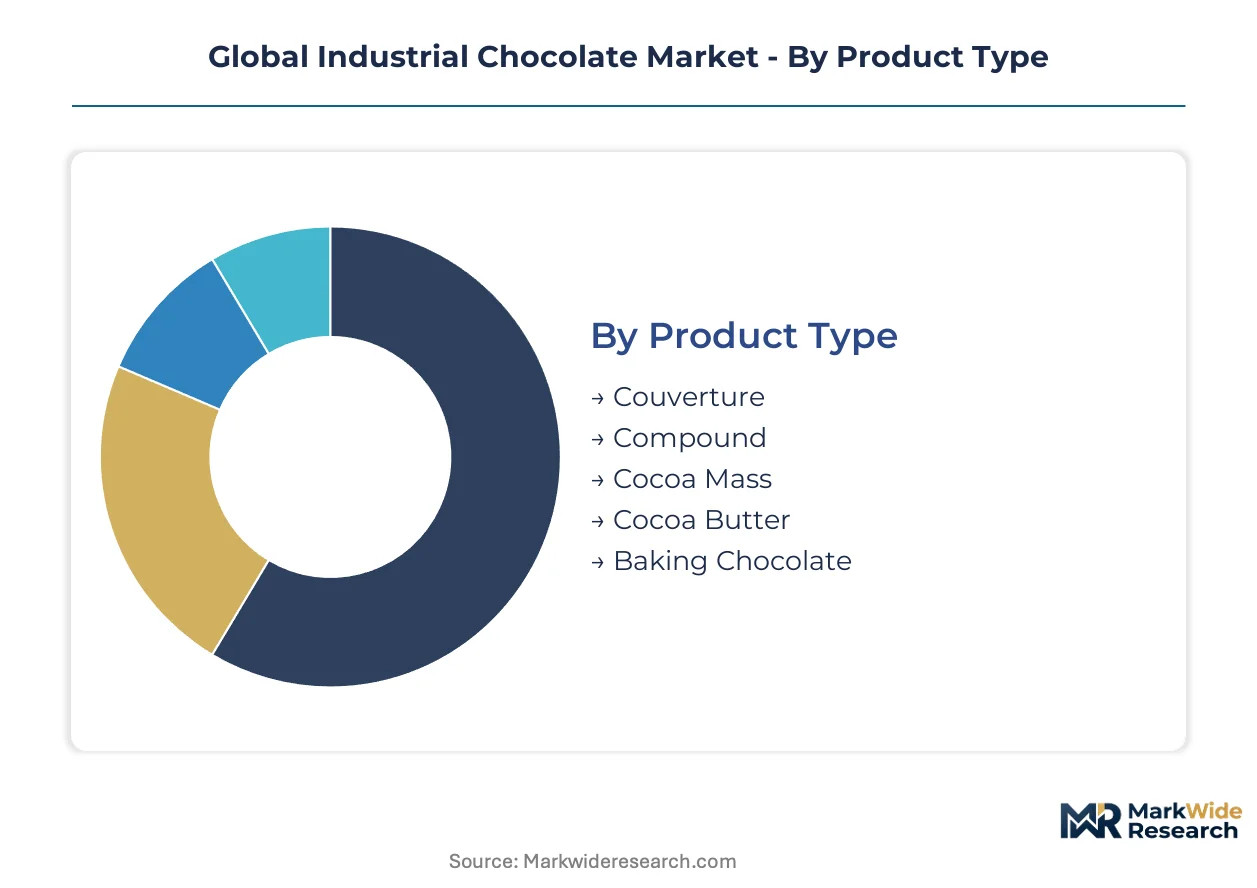
Segmentation within the global industrial chocolate market clarifies demand patterns for bulk cocoa products across diverse applications. Understanding these distinctions enables suppliers to tailor formulations and delivery formats for specific client needs. This market analysis categorizes industrial chocolate by product type, application, end user, and packaging type.
Product Type:
The product type segmentation highlights varying formulation complexities and regulatory approval burdens, particularly for specialized ingredients requiring specific certifications.
- Couverture:This product features a high cocoa butter content, typically above 31%, enabling superior melt characteristics and a glossy finish. Demand concentrates in high-end pastry shops and gourmet confectionery producers in European markets seeking premium inclusions.
- Cocoa Mass:Also known as cocoa liquor, this is pure ground cocoa beans, forming the base for all chocolate products and requiring stringent heavy metal testing. Food processing companies utilize cocoa mass extensively for its intense flavor in mass-produced confectionery and bakery items.
- Compound:A cost-effective alternative using vegetable fats instead of cocoa butter, requiring less demanding storage conditions.
- Cocoa Butter:The pure fat extracted from cocoa beans, valued for its smooth texture and melting properties in chocolate and cosmetic applications.
- Baking Chocolate:Formulated for high-temperature applications, often with lower sugar content, it maintains structural integrity in bakery products.
Leading the category by volume: Cocoa Mass. Growing fastest: Couverture.
Application:
Industrial chocolate applications vary significantly in volume requirements and technical specifications, impacting ingredient selection and processing scale for manufacturers.
- Confectionery:This segment represents the largest consumer, incorporating industrial chocolate into bars, pralines, and molded figures. Manufacturers require precise viscosity and tempering properties for efficient high-volume production lines.
- Bakery:Industrial chocolate is a critical component for premium cakes, cookies, and pastries, often as chips, chunks, or fillings. The segment demands heat-stable formulations that retain flavor and texture during baking processes.
- Beverage:Used in hot chocolate mixes, flavored milk, and specialty coffee drinks, requiring fine particle size and solubility.
- Dairy Products:Incorporated into yogurts, desserts, and ice cream coatings, where stability against moisture and freezing is essential.
- Ice Cream Manufacturing:Utilizes coatings, variegates, and inclusions that resist freezer burn and maintain snap or chewiness at low temperatures.
This category sees significant innovation in functional properties, driven by demand for specific textures and melt profiles in end products.
End User:
The end-user landscape reflects diverse purchasing power and technical integration, ranging from large-scale manufacturers to specialized artisanal producers.
- Food Processing Companies:These large entities purchase industrial chocolate in vast quantities for diverse product lines, often seeking custom formulations and long-term supply contracts. Their procurement patterns prioritize consistency, cost-efficiency, and compliance with global food safety standards.
- Chocolate Manufacturers:Dedicated chocolate producers use industrial chocolate as a primary raw material for their branded consumer products. They often require specific cocoa origins and precise flavor profiles for product differentiation.
- Pastry Shops:Artisanal and specialized pastry shops source high-quality couverture and baking chocolate for premium desserts and confections.
- Beverage Producers:Companies manufacturing flavored milk, hot chocolate, or specialty drinks procure industrial chocolate in formats optimized for liquid dispersion.
Buyer power in this segment is increasingly concentrated among major food processing companies, influencing supplier R&D efforts.
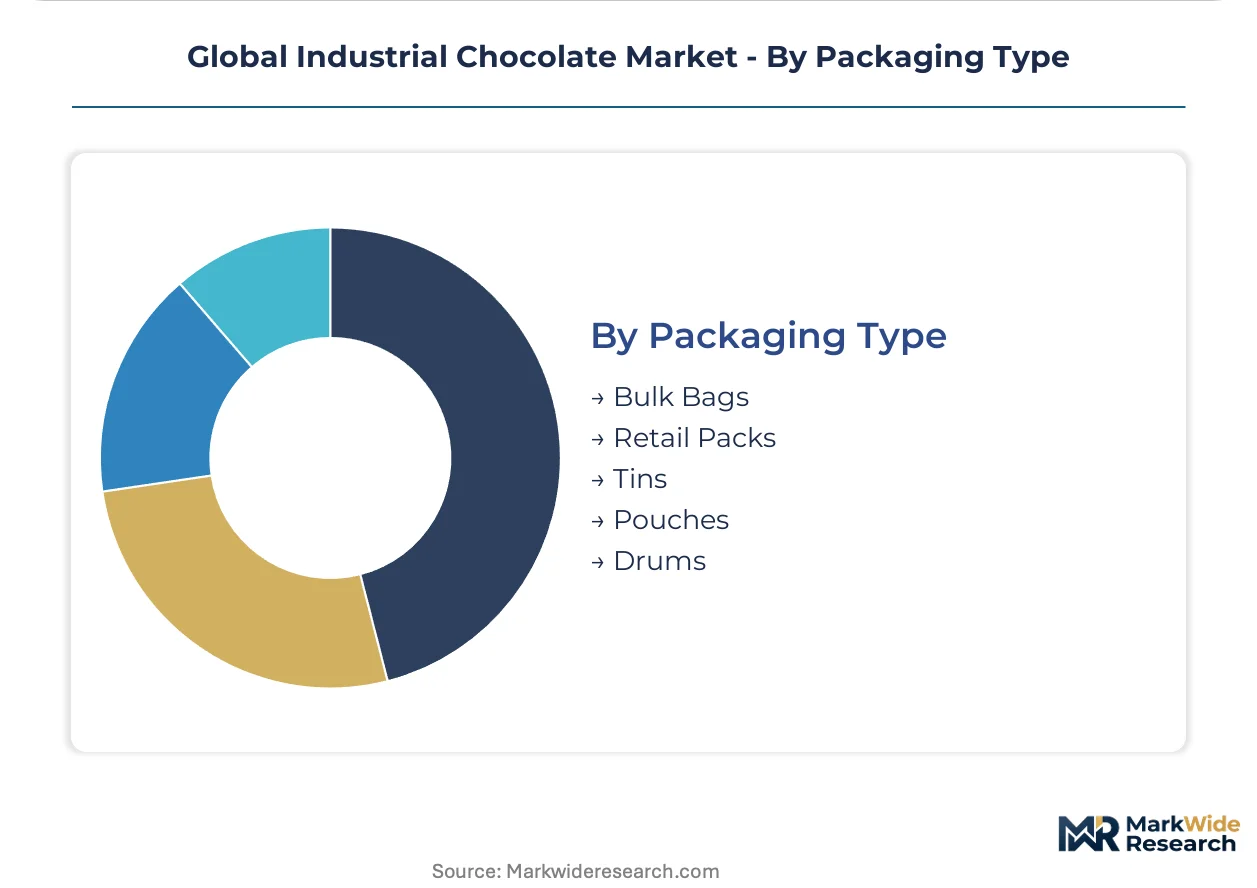
Packaging Type:
Packaging solutions for industrial chocolate are designed to optimize logistics, preserve product quality, and integrate seamlessly into diverse manufacturing operations.
- Bulk Bags:Large, multi-layered bags, often weighing hundreds of kilograms, are used for high-volume deliveries to major food processors. This format minimizes packaging waste and reduces handling costs for clients with automated dispensing systems.
- Drums:Robust cylindrical containers, typically holding 200-250 kg of chocolate, provide secure transport and storage for solid or liquid industrial chocolate. Drums are favored for their durability and ease of handling with forklifts in industrial settings.
- Retail Packs:Smaller, consumer-oriented packaging, though less common for true industrial bulk, serves smaller professional users or specialized culinary schools.
- Tins:Airtight metal containers, often used for specialty or high-value couverture, providing excellent protection against moisture and oxidation.
- Pouches:Flexible packaging solutions for smaller quantities of callets or chips, offering convenience and reduced material weight for specific applications.
Efficiency in supply chain management heavily depends on selecting the appropriate packaging type for each client’s operational scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cocoa bean cultivation in West African nations like Ivory Coast and Ghana fundamentally influences industrial chocolate supply globally. Demand centers in established European markets and rapidly expanding food processing hubs across Asia and the Middle East. New sustainability mandates from the European Union reshape sourcing protocols for all market participants.
United States
Demand for industrial chocolate in the United States stems from its vast food processing sector and consumer preference for confectionery items. The U.S. FDA enforces strict food safety and labeling standards, including heavy metal limits for cocoa products. Major confectionery manufacturers in states like Pennsylvania and Illinois drive significant bulk purchases for their production lines.
Germany
German food manufacturers require industrial chocolate for a wide array of bakery and confectionery applications. The EU Green Deal's deforestation regulations significantly impact cocoa sourcing strategies for German companies. Industrial clusters in North Rhine-Westphalia and Bavaria integrate advanced processing technologies for customized chocolate formulations.
Switzerland
Swiss demand for industrial chocolate centers on high-end couverture and specialty products for its renowned chocolate and pastry industries. Swissmedic regulations ensure premium quality and rigorous ingredient traceability for all food products. Geneva and Zurich remain key hubs for gourmet chocolate production and innovation.
Belgium
Belgian confectionery producers are significant consumers of industrial chocolate, prioritizing specific melt characteristics and flavor profiles for pralines and molded figures. The European Food Safety Authority (EFSA) guidelines dictate ingredient purity and additive usage in Belgium. Cities like Brussels and Bruges are home to numerous artisanal and large-scale chocolate manufacturers.
Singapore
Singapore's expanding food processing infrastructure and high-end hospitality sector drive demand for industrial chocolate, particularly for premium bakery inclusions. The Singapore Food Agency (SFA) oversees food safety and import regulations, ensuring product quality. Food innovation parks and manufacturing zones in Jurong provide a growing market for bulk chocolate suppliers.
Global Industrial Chocolate Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue plant-based alternatives and specialized ingredient solutions. The market structure exhibits consolidation among a few global giants, alongside a growing number of specialized ingredient suppliers. Strategic archetypes include integrated commodity processors, specialized ingredient providers, and brand-focused confectionery manufacturers. Dominant competitive moves involve capacity expansion and strategic partnerships for sustainable sourcing.
At the scale-driven end, Barry Callebaut AG and Cargill Incorporated exemplify comprehensive global supply chain management for cocoa and industrial chocolate. Mondelez International Inc. represents a major confectionery brand integrating industrial chocolate into its extensive portfolio. These entities leverage their vast networks to meet diverse client requirements, from bulk cocoa mass to customized formulations.
| Leading Market Players |
|---|
| Barry Callebaut AG |
| Cargill Incorporated |
| Cémoi Group |
| Fuji Oil Holdings Inc |
| Mondelez International Inc |
| Mars Incorporated |
| Nestlé S.A. |
| The Hershey Company |
| Chocoladefabriken Lindt & Sprüngli AG |
| Others |
Cost & Logistics Intelligence
Vertical integration into cocoa processing and sourcing anchors both the supply position and the pricing power for major industrial chocolate producers. This strategic choice enables control over raw material quality and ensures compliance with evolving sustainability mandates.
Pricing Analysis
Warranty bundling for industrial chocolate extends to quality certifications and traceability documentation, crucial for market access. Pricing structures primarily operate on contract-based long-term offtake agreements, supplemented by commodity spot market transactions for smaller volumes. Price differentiation stems from cocoa butter content, origin certifications, and customization levels for specific client applications. Pricing pressure stems from volatile cocoa bean prices and the rising costs of regulatory compliance. Food processing companies are highly price-sensitive for bulk ingredients, while specialized pastry shops prioritize quality over cost.
Supply Chain Analysis
Cocoa bean supply draws predominantly from West African nations, specifically Ivory Coast and Ghana, creating a concentrated sourcing risk. Raw material dependencies include cocoa beans, sugar, and milk powders. Supply chain risk centers on commodity price volatility and the potential for regulatory restrictions, such as the EU Green Deal's deforestation rules, to disrupt traditional sourcing channels. Distribution runs through bulk formats like drums and bulk bags, directly to food processing facilities and confectionery manufacturers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story, where the EU Green Deal's deforestation rules create a significant barrier to entry for non-compliant players, favoring those with established traceable supply chains.
For Market Incumbents: Cement relationships with certified cocoa cooperatives through long-term contracts and direct investment in sustainable farming practices. This mitigates the threat of supply chain disruption from new sustainability mandates. Expand processing capacity in proximity to growing demand centers, particularly in Southeast Asia, to reduce logistics costs and enhance responsiveness to client needs. Invest in blockchain technology for immutable traceability records, creating a competitive advantage in a market demanding transparency.
For New Entrants and Emerging Players: Artisanal pastry shops and high-end food service providers represent an underserved buyer archetype seeking premium, specialty, and plant-based industrial chocolate. Target these segments by offering customized couverture formulations with unique flavor profiles or organic certifications. A focused go-to-market strategy emphasizing clean-label ingredients and verifiable ethical sourcing can differentiate new players from established bulk commodity suppliers. Develop plant-based alternatives to capture the expanding vegan food manufacturing sector.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized ingredient providers with proprietary plant-based chocolate formulations or advanced traceability platforms. The long-term viability of industrial chocolate hinges on verifiable sustainability and resilient supply chains, making firms with strong ESG credentials attractive. A signal to watch is the increasing M&A activity involving companies offering precision fermentation technologies, indicating a shift towards alternative cocoa sources to de-risk commodity dependence.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Increases market reach and reduces lead times for food processors in high-growth regions. |
| Blockchain Traceability Implementation | Provides immutable proof of origin, critical for EU Green Deal compliance and client trust. |
| Plant-Based Chocolate Development | Captures share in the expanding vegan and health-conscious food manufacturing sector. |
| Direct Sourcing Partnerships | Secures sustainable cocoa supply and builds resilience against commodity price volatility. |
| Customized Formulation Co-development | Embeds chocolate suppliers into client innovation processes, fostering long-term relationships. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a broad market overview. This was complemented by primary interviews with food processing executives, cocoa traders, and sustainability managers to gather granular insights. The approach combined bottom-up data aggregation with top-down market validation, ensuring comprehensive data coverage and accuracy.
Market granularity was modeled across product type, application, end user, packaging type, and key regional demand centers throughout the analysis window. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and validated against projected market dynamics. Key forecast inputs included cocoa bean price trends, regulatory compliance costs, and consumer demand shifts for premium and clean-label products.
Revisions become necessary when geopolitical instability in West Africa, new food safety mandates, or rapid shifts in consumer preferences materialize. Forecasts reflect assumptions regarding stable regulatory environments and continued investment in sustainable sourcing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Germany Chocolate Market
Confectionery
North America Chocolate Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Dark Chocolate Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Africa Compound Chocolate Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Buttercream Frosting Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
Coffee Gummy Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Global Confectionery Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market