
 India Industrial Chocolate Market | 2026-2036
India Industrial Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
India Industrial Chocolate Market Foresight
Modular portion packs and single-serve sachet configurations are replacing bulk slab deliveries for small bakeries, is realigning procurement patterns across tier-two cities. Barry Callebaut Group leverages its technical centers in Mumbai to sustain formulation partnerships with domestic biscuit brands. Jindal Drugs Pvt Ltd anchors cocoa butter equivalent production from its Kerala processing base. Cargill, Incorporated competes through integrated bean sourcing into its Davanagere facility, controlling upstream supply for regional confectioners.
India industrial chocolate comprises cocoa mass, butter, powder, and derivatives processed for B2B applications requiring defined particle size, fat content, and viscosity parameters for enrobing or moulding. Manufacturers temper blends to precise melting curves between 32°C and 34°C to ensure snap and gloss in finished confectionery. Dark chocolate segments lead value contribution due to premium positioning in artisan bakery and ice-cream coating applications. Milk chocolate dominates volume through dairy product inclusions and mass-market confectionery fillings. Ruby chocolate occupies a nascent premium niche among specialty dessert channels seeking color differentiation without artificial additives.
FSSAI labeling and fortification rules, BIS cocoa product standards, and CDSCO food additive approvals collectively govern ingredient composition and market access for domestic and imported chocolate inputs. Compliance with these frameworks raises reformulation costs but also filters informal suppliers, tightening channel control for organized processors. Stakeholders must monitor evolving PLI scheme extensions for food processing and state-level cold-chain subsidies that could reshape regional manufacturing economics.
Market Dynamics
FSSAI fortification mandates and BIS quality standards are tightening ingredient traceability requirements, forcing cocoa processors to upgrade batch-tracking systems and reformulate blends for compliance. This regulatory compression is reshaping procurement relationships between organized processors and informal suppliers across Maharashtra and Gujarat industrial corridors.
Growth Catalysts
- Fortification Mandates:FSSAI labeling rules for micronutrient fortification in cocoa products are expanding addressable demand for functional chocolate ingredients in health-oriented bakery applications.
- Cold-Chain Expansion:State-level cold-chain subsidies in Maharashtra and Karnataka are reducing spoilage losses for temperature-sensitive cocoa butter shipments to tier-two confectionery clusters.
- Artisan Bakery Premiumization:Dark chocolate coatings with defined particle size distributions are displacing compound alternatives in Mumbai-Pune artisan ice-cream and dessert channels.
Market Restraints
- Cocoa Butter Price Volatility:International cocoa futures volatility transmits directly into Indian cocoa butter equivalent production costs, compressing margin visibility for Kerala-based processors.
- Import Dependency Concentration:West African bean sourcing concentration creates supply disruption exposure for Davanagere and Mumbai processing facilities during harvest cycle gaps.
- Reformulation Cost Burden:CDSCO food additive approval timelines extend new ingredient qualification cycles, delaying product launches for regional contract manufacturers.
Strategic Opportunities
- Untapped Northeast Penetration:Guwahati and Siliguri bakery clusters remain underserved by organized industrial chocolate distributors, offering first-mover channel establishment potential.
- Ruby Chocolate Positioning:Color-differentiated couverture applications in specialty dessert channels command premium positioning without artificial additive dependencies.
- PLI Scheme Extension:Central government food processing incentives could subsidize tempering equipment upgrades for mid-scale Mumbai-Pune contract manufacturers.
Industry Challenges
- Skilled Tempering Technician Scarcity:Precision melting curve calibration for 32°C to 34°C snap specifications requires specialized training absent in tier-two vocational pipelines.
- Legacy ERP Integration Friction:Batch-tracking compliance with FSSAI traceability mandates demands retrofitting analog inventory systems at Gujarat biscuit coating facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Industrial Chocolate Market |
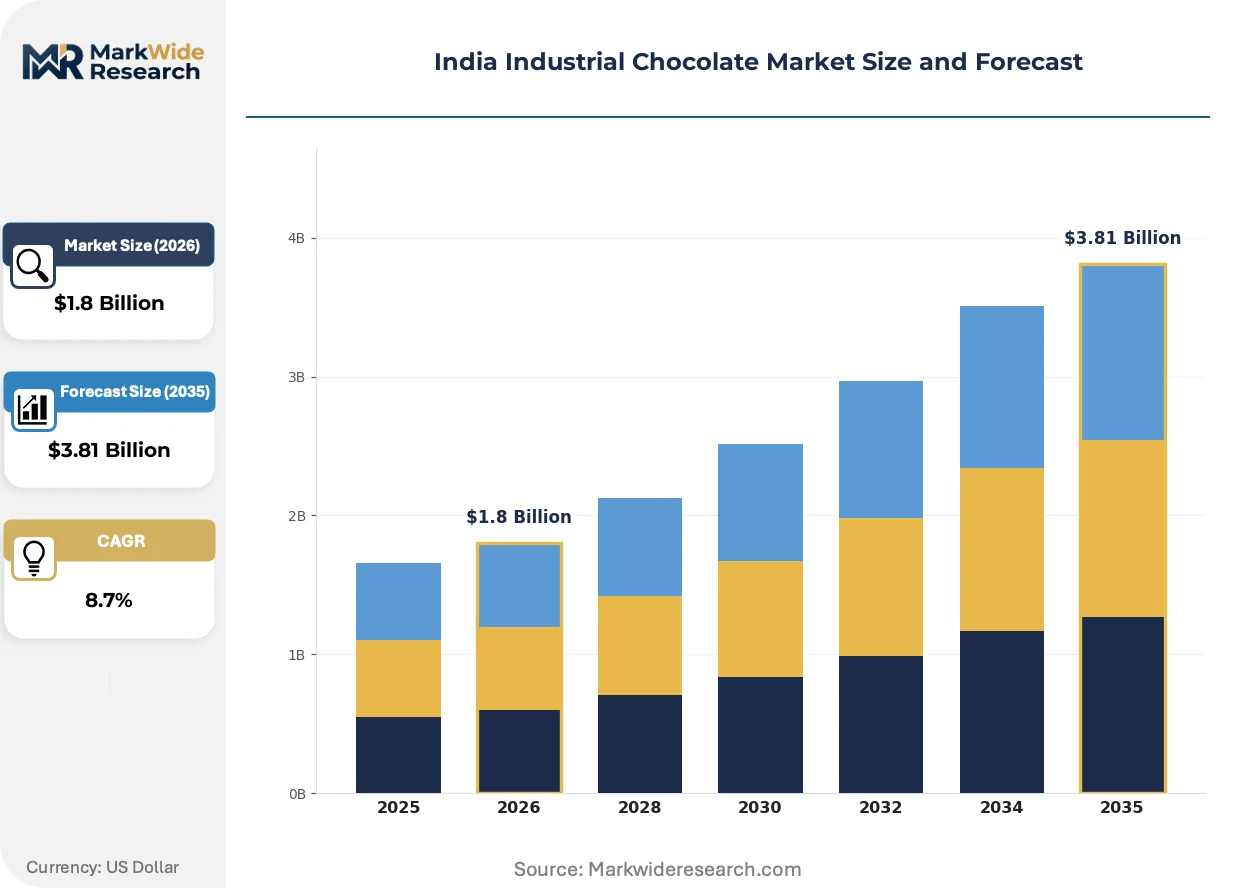
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End Use Industry: Bakery, Confectionery, Dairy Products, Beverages Distribution Channel: Online Retail, Wholesale, Supermarkets, Specialty Stores Application: Coatings, Fillings, Moulding, Baking |
| Companies Covered | Puratos Group, Jindal Drugs Pvt Ltd (Jindal Cocoa), Barry Callebaut Group, FarmSpice Traders Private Ltd (Cocoabean), The Campco Ltd, Lotus Chocolate Company Ltd, Aadra International, Cargill, Incorporated, DP Cocoa Products Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Industrial Chocolate Market Shifts & Advancements
Precision tempering automation and single-serve packaging configurations are compressing production batch sizes while expanding customization capabilities for regional bakery chains. These shifts are redrawing equipment investment priorities and supplier relationships across Indian industrial chocolate processing.
Continuous tempering systems with real-time viscosity monitoring are electrifying small-batch production economics for Mumbai-Pune artisan contract manufacturers. Bakery chains in Delhi-NCR are adopting these units to reduce changeover downtime between dark, milk, and ruby chocolate runs. The technology is compressing minimum viable order quantities, enabling tier-two city bakeries to access previously volume-gated premium couverture grades.
FSSAI fortification mandates for iron and zinc in cocoa-based products are forcing reformulation partnerships between processors and micronutrient premix suppliers. BIS cocoa product standards now require documented particle size distribution certificates for imported cocoa mass. Dark chocolate segments for ice-cream coating applications face the steepest compliance adjustment timelines due to existing fat-content specifications.
Modular portion packs are displacing bulk slab deliveries as the dominant procurement format among Ahmedabad and Surat small bakeries. Distributors are unbundling logistics services from product supply, offering dedicated cold-chain subscriptions separate from ingredient invoices. This unbundling is most visible in Gujarat biscuit coating channels where seasonal demand spikes previously forced inventory carrying cost absorption by processors.
India Industrial Chocolate Market Segmentation
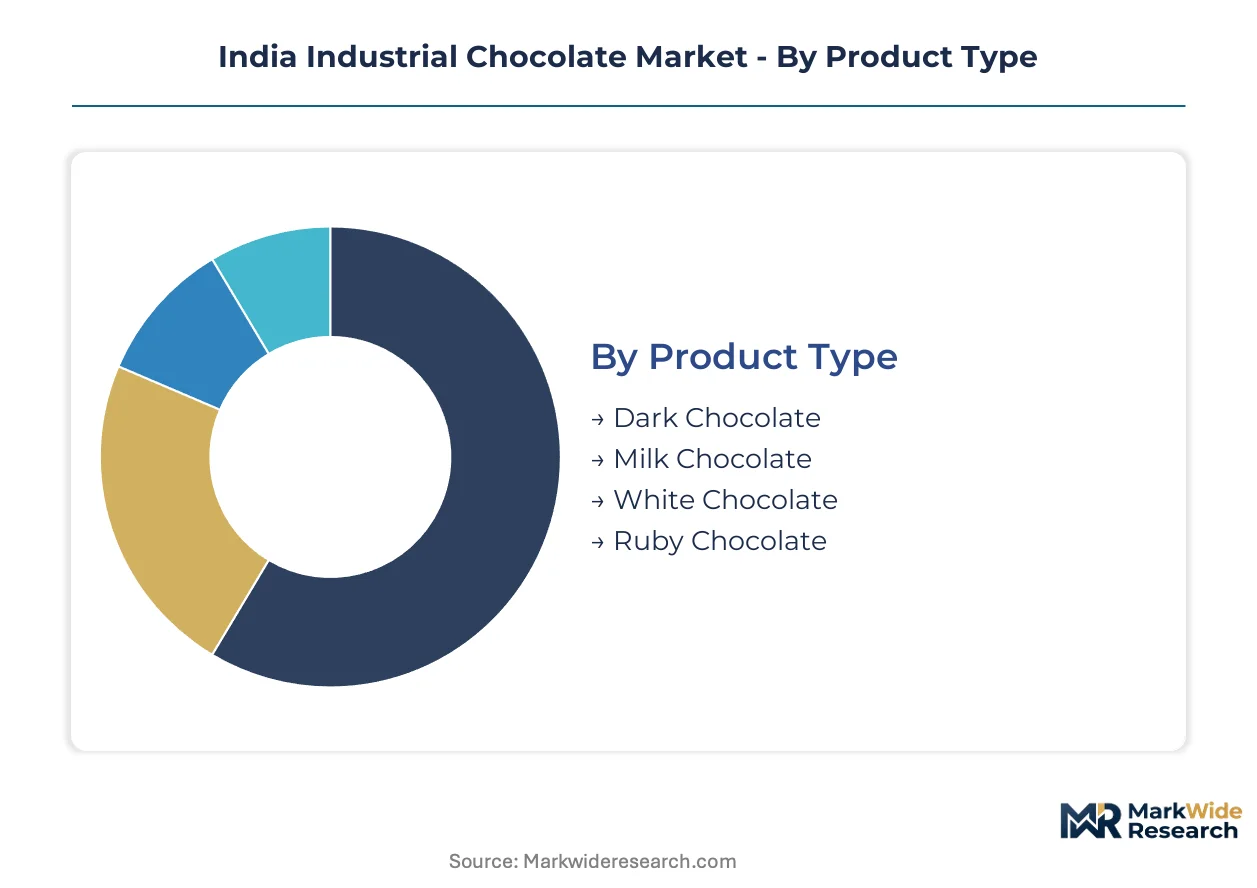
Industrial chocolate procurement in India diverges sharply between mass-volume commodity grades and precision-tempered premium couvertures. Understanding these segment boundaries reveals where margin pools concentrate and which technical specifications command pricing power across Maharashtra and Gujarat manufacturing corridors.
Product Type:
Volume leadership sits with dairy-inclusive formulations, while premium positioning clusters around cocoa-intense and color-differentiated grades.
- Dark Chocolate:Cocoa mass exceeding 50% delivers defined snap and gloss for artisan ice-cream coatings. Mumbai-Pune dessert manufacturers specify particle size distributions below 20 microns for enrobing applications, with FSSAI fortification mandates driving iron and zinc premix partnerships.
- Milk Chocolate:Milk solids and cocoa butter blends dominate biscuit filling volumes through mass-market confectionery channels. Gujarat dairy processors supply skim milk powder to Davanagere facilities, though cocoa butter price volatility compresses margin visibility for Kerala-based compound manufacturers.
- White Chocolate:Cocoa butter base without cocoa solids serves premium bakery glazes and specialty dessert bases. Delhi-NCR artisan chains specify minimum 20% cocoa butter content for tempering stability.
- Ruby Chocolate:Pink-hued couverture from unfermented cocoa beans occupies nascent premium positioning among Mumbai specialty dessert channels seeking color differentiation without artificial additives.
Mature deployment sits with Milk Chocolate. Newer deployment is concentrated in Ruby Chocolate.
End Use Industry:
Application heat tolerance and fat-content specifications determine processor-customer matching across temperature-sensitive supply chains.
- Bakery:Cookie and biscuit coating demand concentrates in Ahmedabad and Surat manufacturing clusters, with compound chocolate displacing pure couverture in mass-market packaged goods. Modular portion packs are displacing bulk slab deliveries among tier-two city bakeries.
- Confectionery:Defined viscosity parameters for enrobing and moulding applications require precise tempering curve calibration between 32°C and 34°C. Maharashtra contract manufacturers cluster near cold-chain logistics hubs to serve pan-Indian distribution.
- Dairy Products:Ice-cream coating specifications demand rapid crystallization for snap retention through freeze-thaw cycles. Dark chocolate segments face steepest FSSAI compliance adjustment timelines due to existing fat-content specifications.
- Beverages:Cocoa powder and mass derivatives for chocolate drinks and flavored milk applications. BIS quality standards now require documented particle size distribution certificates for imported inputs.
Volume concentration anchors in Bakery. Premium specification growth is expanding most quickly in Confectionery.
Distribution Channel:
Logistics unbundling from product supply is reshaping procurement economics for small-scale manufacturers.
- Online Retail:Digital platforms enable tier-two city bakeries to access previously volume-gated premium couverture grades with compressed minimum order quantities. Real-time inventory visibility supports just-in-time procurement for seasonal demand spikes.
- Wholesale:Traditional distributor networks dominate Gujarat and Maharashtra bulk procurement, with dedicated cold-chain subscriptions now offered separate from ingredient invoices. Seasonal inventory carrying costs are shifting from processors to logistics providers.
- Supermarkets:Limited penetration for industrial-grade inputs; primarily serves small bakery retail operations with consumer-packaged chocolate for ingredient substitution.
- Specialty Stores:Curated couverture selections for artisan Mumbai-Pune dessert channels requiring technical consultation on tempering parameters.
Established procurement runs through Wholesale. Channel innovation is concentrating in Online Retail.
Application:
Processing method determines equipment investment requirements and technical service intensity in processor-customer relationships.
- Coatings:Enrobing applications for biscuits, ice-cream bars, and confectionery centers require controlled viscosity for uniform thickness. Continuous tempering systems with real-time monitoring are electrifying small-batch production economics for Mumbai-Pune contract manufacturers.
- Fillings:Viscous centers for pralines and bakery items demand fat-content stability through shelf-life cycles. Dairy product inclusions dominate volume through mass-market channels.
- Moulding:Precision tempering for defined snap and gloss specifications in tablet and figure production. Skilled technician scarcity for melting curve calibration constrains tier-two facility expansion.
- Baking:Ingredient incorporation into dough and batter matrices, with lower tempering precision requirements than surface applications.
Equipment standardization centers on Coatings. Technical complexity is climbing fastest in Moulding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity concentrates in southern and western states while consumption demand radiates from northern and western industrial corridors. Kerala and Karnataka anchor cocoa butter equivalent production. Maharashtra and Gujarat absorb the bulk of compound chocolate procurement for biscuit coating applications.
Maharashtra
Mumbai-Pune dessert manufacturers drive demand for dark chocolate couvertures with sub-20 micron particle specifications. FSSAI fortification mandates for iron and zinc premixes are forcing reformulation partnerships between processors and micronutrient suppliers. Contract manufacturers cluster near cold-chain logistics hubs in Pune to serve pan-Indian distribution networks.
Gujarat
Ahmedabad and Surat bakery chains are displacing bulk slab deliveries with modular portion packs for seasonal cookie production. BIS cocoa product standards now require documented particle size distribution certificates for imported mass inputs. Compound chocolate coatings dominate procurement for mass-market packaged biscuits across Surat manufacturing clusters.
Karnataka
Davanagere processing facilities control upstream bean supply for regional confectioners through integrated sourcing operations. State-level cold-chain subsidies are reducing spoilage losses for temperature-sensitive cocoa butter shipments to tier-two clusters. Bangalore-based distributors are unbundling logistics services from product supply for small bakery procurement.
Kerala
Jindal Drugs anchors cocoa butter equivalent production from its Kerala processing base, serving dairy-inclusive formulation demand. International cocoa futures volatility transmits directly into production costs, compressing margin visibility for local processors. Kochi port infrastructure supports import dependency for West African bean sourcing during harvest cycle gaps.
Delhi-NCR
Artisan bakery chains in the capital region specify minimum 20% cocoa butter content for white chocolate tempering stability. CDSCO food additive approval timelines extend new ingredient qualification cycles for regional contract manufacturers. Continuous tempering adoption is reducing changeover downtime between dark, milk, and ruby chocolate production runs.
India Industrial Chocolate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement, processing, and distribution vectors. The vendor base stratifies between integrated bean-to-bar operators, regional compound manufacturers, and technical service-oriented couverture suppliers. Three archetypes dominate: upstream-integrated agricultural processors, formulation-technical service hybrids, and distribution-logistics aggregators. Capacity expansion and cold-chain infrastructure partnerships constitute the primary competitive moves.
Among multinational-integrated operators, Cargill and Barry Callebaut occupy positions anchored by upstream sourcing control and technical center presence. Jindal Drugs represents the domestic processing archetype with Kerala-based cocoa butter equivalent production. Puratos Group exemplifies the technical service model through formulation partnerships with domestic biscuit brands.
| Leading Market Players |
|---|
| Puratos Group |
| Jindal Drugs Pvt Ltd (Jindal Cocoa) |
| Barry Callebaut Group |
| FarmSpice Traders Private Ltd (Cocoabean) |
| The Campco Ltd |
| Lotus Chocolate Company Ltd |
| Aadra International |
| Cargill, Incorporated |
| DP Cocoa Products Pvt Ltd |
| Others |
Supply & Pricing Matrix
Premium-mid-economy pricing differentiation across India industrial chocolate traces to FSSAI fortification mandates and BIS certification requirements that filter informal suppliers from organized channels. This tiered structure manifests in procurement patterns where artisan Mumbai-Pune dessert manufacturers absorb 20% cocoa butter content specifications while Gujarat biscuit coating facilities optimize for compound chocolate bulk deliveries.
Pricing Analysis
Margin tightening in commodity-grade compound chocolate reflects international cocoa futures volatility transmitting directly into Kerala-based cocoa butter equivalent production costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with BIS particle size distribution certificates commanding premiums for imported cocoa mass. Cost-down pressure on mid-scale processors accelerates as Davanagere facilities compete with integrated bean-to-bar operators. Tier-two city bakeries exhibit highest price sensitivity, while Delhi-NCR artisan chains prioritize tempering stability over unit economics.
Supply Chain Analysis
BIS quality standards and FSSAI traceability mandates are reshaping sourcing toward documented West African bean supply chains for Mumbai and Davanagere processing facilities. Geographic supply concentration draws from Côte d'Ivoire, Ghana, and Ecuador for cocoa bean inputs, with Kerala and Karnataka anchoring domestic cocoa butter equivalent production. Raw material dependencies rest on cocoa mass, cocoa butter, and dairy powder inclusions. Single-source vulnerability from West African harvest cycle gaps threatens continuity for regional confectioners. Distribution runs through unbundled cold-chain subscriptions separate from ingredient invoices, shifting seasonal inventory carrying costs to logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India industrial chocolate is consolidating around FSSAI compliance capabilities that exclude informal compound manufacturers from organized procurement channels. Regulatory compression is accelerating exit timelines for batch-tracking deficient Gujarat biscuit coating facilities.
For Market Incumbents: Deepen backward integration into Kerala cocoa butter equivalent production to buffer international futures volatility exposure. Expand tempering equipment capacity in Pune cold-chain logistics corridors to capture artisan bakery premiumization demand. Fortify channel control through technical center partnerships that lock in domestic biscuit brand formulation relationships against emerging regional compound manufacturers.
For New Entrants and Emerging Players: Specialty distributors represent the most penetrable channel partner type for Guwahati and Siliguri bakery cluster penetration. Target underserved Northeast Indian markets with modular portion pack configurations sized for seasonal cookie production spikes. Pursue white-label couverture supply agreements with tier-two city ice-cream manufacturers seeking dark chocolate coating alternatives to compound substitutes.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale Mumbai-Pune contract manufacturers with installed continuous tempering systems and FSSAI-compliant batch-tracking infrastructure. Long-term viability over the projection horizon favors processors with integrated bean sourcing and micronutrient premix partnerships. Watch CDSCO food additive approval timeline acceleration as the inflection signal for reformulation-ready acquisition targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bean Sourcing | Cargill's Davanagere facility demonstrates how captive West African supply insulates margin visibility from futures volatility. |
| Continuous Tempering System Deployment | Barry Callebaut Mumbai technical centers leverage real-time viscosity monitoring to compress changeover downtime between chocolate grades. |
| Micronutrient Premix Partnership | FSSAI iron and zinc fortification mandates force reformulation alliances that lock processors into qualified supplier networks. |
| Cold-Chain Infrastructure Partnership | Maharashtra state subsidies enable Pune logistics hubs to reduce spoilage losses for temperature-sensitive cocoa butter shipments. |
| Ruby Chocolate Capability Buildout | Pink-hued couverture positioning captures specialty dessert channel premiums without artificial additive dependencies. |
Research Methodology
Document review covered FSSAI fortification guidelines, BIS cocoa product standards, and CDSCO food additive approval databases, complemented by interviews with Kerala processing plant managers, Maharashtra contract manufacturer procurement leads, Gujarat biscuit coating facility operators, and Delhi-NCR artisan bakery technical directors. Secondary validation drew from customs import records for cocoa mass and butter, SEC filings of multinational food processors, and state-level cold-chain subsidy program disclosures. Bottom-up demand modeling from tier-two city bakery clusters was cross-referenced against top-down supply capacity assessments from Karnataka and Kerala processing bases.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type tier, end-use application heat tolerance specifications, distribution channel format, and regional manufacturing corridor clustering. CAGRs were derived from slope analysis of processed cocoa derivative demand curves, with specific inputs including Maharashtra cold-chain infrastructure buildout rates and Gujarat biscuit production seasonal indices.
Caveats apply where international cocoa futures volatility, FSSAI labeling rule amendments, or PLI scheme extension decisions could materially shift the outlook for regional processor economics. Forecasts reflect documented assumptions about regulatory compliance timelines and infrastructure subsidy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Saudi Arabia Chocolate Market
Confectionery
Chocolate Confectionery Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Green Tea Chocolate Market
Confectionery
Black Treacle Market
Confectionery
Confectionery Fillings Market
Confectionery
Global Mochi Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
Japan Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
Europe Dark Chocolate Market
Confectionery
Mooncake Market
Confectionery
Mints Market