
 Vegan Chocolate Market | 2026-2036
Vegan Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Chocolate Market Intelligence
Belgium's cocoa processing corridor is reconfiguring capacity toward dairy-free tempering lines and allergen-segregated facilities. Barry Callebaut leverages its bean-to-bar infrastructure to supply compound coatings for private-label vegan lines. Lindt & Sprungli AG anchors premium positioning through controlled-origin cacao sourcing and Swiss manufacturing discipline. Mondelez International, Inc. competes on scale, distributing plant-based variants through mass retail channels across multiple continents.
Vegan chocolate denotes confectionery products formulated without milk solids, whey, or other animal-derived ingredients, typically employing cocoa mass, cocoa butter, and plant-based milk alternatives such as oat or rice extracts to achieve comparable mouthfeel and snap. The manufacturing process requires precise tempering curves between 27°C and 32°C to stabilize cocoa butter polymorphs in the absence of dairy fat emulsifiers. Dark chocolate dominates current volume owing to its naturally dairy-free composition and lower reformulation burden for established manufacturers. Raw chocolate, produced through unroasted bean processing below 46°C, commands premium pricing in health food shops and specialty stores. Gourmet chocolate segments concentrate margin pools around single-origin certifications and limited-batch releases through direct-to-consumer channels.
FDA allergen labeling rules and EU REACH frameworks governing food contact materials shape cross-border ingredient sourcing and packaging compliance for vegan chocolate exporters. EFSA nutrition and health claims regulations constrain how manufacturers communicate protein equivalence or environmental benefits on European packaging. Stakeholders must monitor evolving cocoa sustainability standards and traceability mandates as procurement decisions increasingly hinge on verified deforestation-free supply chains rather than price alone.
Market Dynamics
The EU Green Deal's tightening ingredient disclosure requirements are forcing manufacturers to reconfigure supply chains and segregate allergen facilities, compressing margins for mid-tier producers while rewarding vertically integrated bean-to-bar operators with certified deforestation-free sourcing.
Growth Catalysts
- Oat milk extraction advances:Enzymatic hydrolysis protocols now achieve dairy-comparable fat crystallization in tempering curves, removing the mouthfeel barrier that previously limited vegan chocolate to dark varieties.
- EFSA nutrition claims framework:Clarified protein equivalence labeling rules enable manufacturers to communicate nutritional parity on European packaging, accelerating retail placement in conventional confectionery aisles.
- Berlin-Munich producer density:Germany's clustered vegan-certified artisan networks generate knowledge spillovers in bean sourcing and small-batch processing, lowering entry barriers for regional craft entrants.
Market Restraints
- Cocoa butter price volatility:Weather disruptions in West African growing regions and speculative commodity positions create input cost instability that dairy-free formulations cannot hedge through fat blending alternatives.
- Belgian processing corridor concentration:Limited dairy-free tempering line capacity at major compound coating facilities creates queuing bottlenecks for private-label vegan line launches.
- REACH food contact material compliance:Cross-border packaging certification for plant-based emulsifiers adds 8-14 week lead times to European export shipments.
Strategic Opportunities
- Raw chocolate health positioning:Unroasted bean processing below 46°C unlocks premium pricing in specialty retail and direct-to-consumer channels for antioxidant-focused buyers.
- Single-origin certification convergence:Pairing geographic traceability with vegan credentials commands margin premiums in Swiss and German gourmet segments.
- Mass retail shelf expansion:Specialty confectionery retailers are dedicating incremental linear footage to plant-based alternatives, creating first-mover positioning for scaled compound coating suppliers.
Industry Challenges
- Polymorph stabilization expertise:Precise tempering curve management between 27°C and 32°C without dairy fat emulsifiers requires specialized chocolate engineering talent that remains concentrated in Belgian and Swiss technical institutes.
- Deforestation-free verification timelines:EU traceability mandates for cocoa procurement are extending supplier onboarding cycles, compressing product development calendars for seasonal launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Chocolate Market |
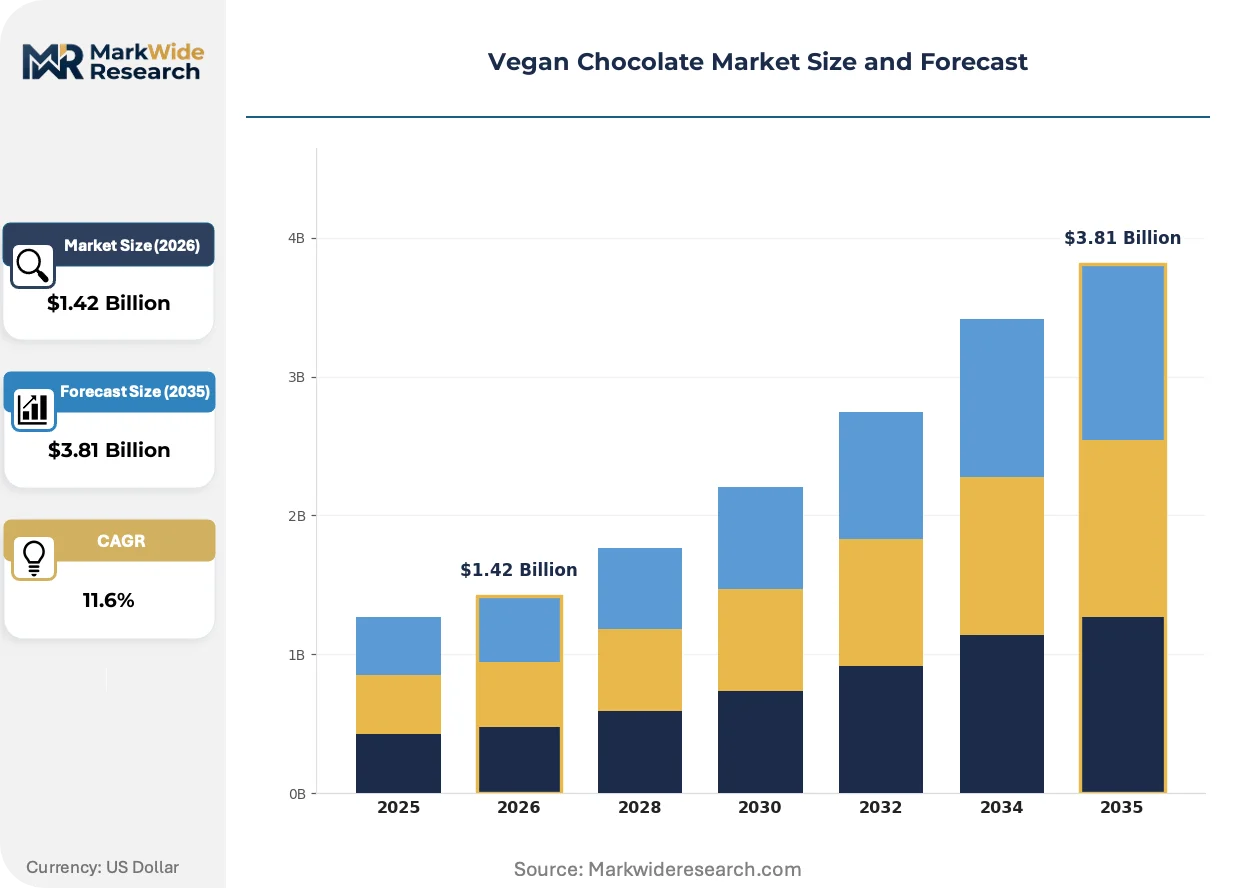
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, Raw Chocolate, Gourmet Chocolate Ingredient Type: Cocoa Butter, Coconut Sugar, Almond Milk, Cashew Cream Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops Packaging Type: Wrapper, Box, Bulk, Eco-friendly Pouch |
| Companies Covered | Nestle S.A, Mars, Inc., Mondelez International, Inc., The Hershey Company, Barry Callebaut, Lindt & Sprungli AG, Plamil Foods Ltd, Alter Eco, Endangered Species Chocolate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Chocolate Market Strategic Shifts & Innovations
Precision fermentation and enzymatic fat structuring are collapsing the functional gap between plant-based and dairy chocolate, while regulatory disclosure mandates and channel fragmentation reshape how manufacturers build brand equity and capture margin.
Precision fermentation-derived cocoa butter equivalents are collapsing the cost-performance tradeoff that previously confined vegan chocolate to premium tiers. Mid-scale manufacturers in the Netherlands and Germany are adopting these lipids at pilot scale, enabling price-competitive milk chocolate analogs that replicate dairy fat crystallization behavior without agricultural cocoa exposure.
REACH frameworks governing food contact materials are tightening cross-border packaging compliance for vegan chocolate exporters. Industrial consequence includes mandatory migration testing for plant-based emulsifier interactions with barrier films, most acutely affecting German private-label suppliers serving multi-country retail contracts who must now maintain parallel packaging specifications.
Direct-to-consumer subscription models are displacing traditional specialty retail distribution for limited-batch vegan chocolate releases. Gourmet segments in Switzerland and urban Germany are pivoting toward membership-based access to single-origin certifications, bypassing wholesale margin structures while capturing consumer willingness-to-pay through exclusive origin storytelling and controlled-release scarcity.
Vegan Chocolate Market Segmentation
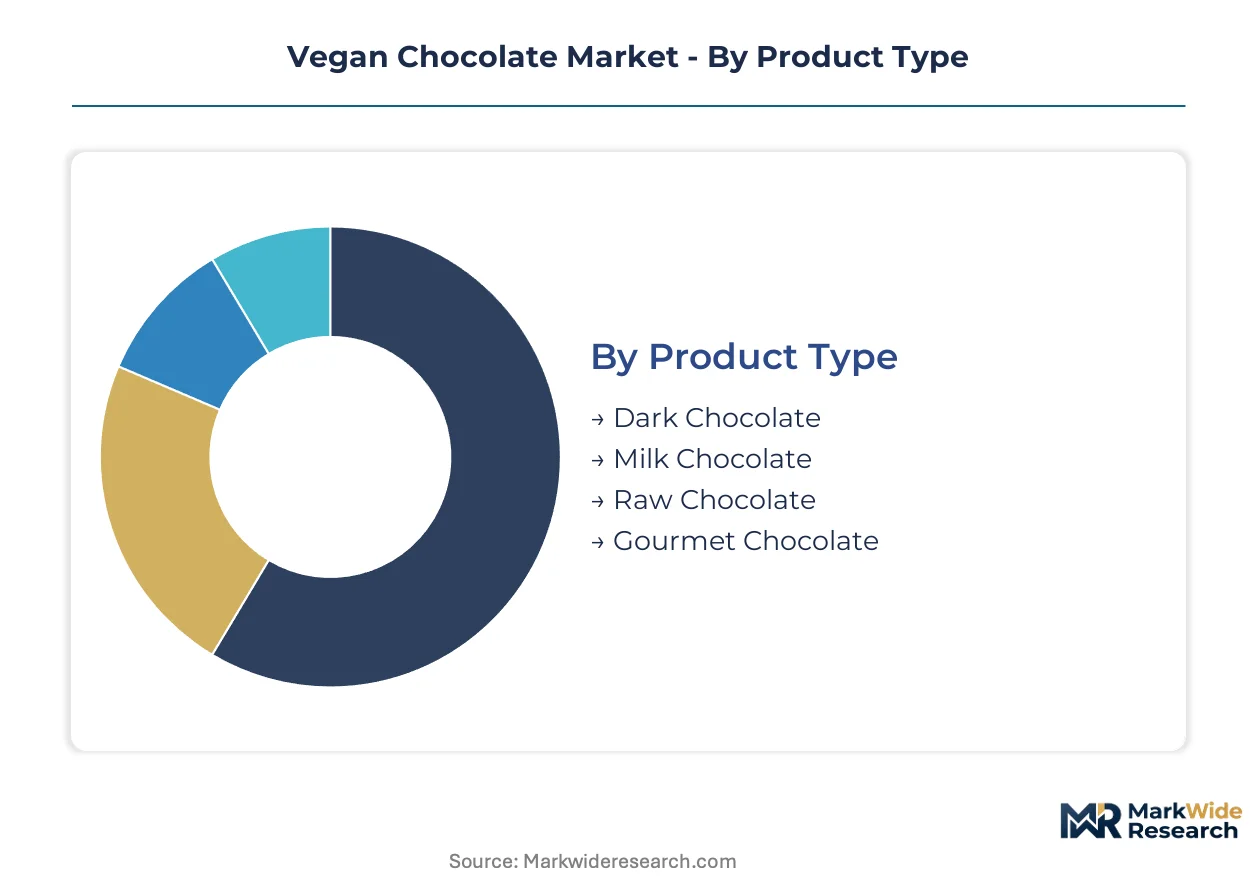
Vegan chocolate segmentation reveals divergent velocity profiles across product formats and channel strategies. Cycle times vary dramatically—raw and gourmet variants turn inventory slowly through direct channels while supermarket milk chocolate analogs rotate rapidly via mass retail placement.
Product Type:
Dark chocolate maintains the shortest production-to-shelf cycle, leveraging existing dairy-free infrastructure without reformulation delays. Raw and gourmet segments extend lead times through specialized tempering protocols and limited-batch scheduling.
- Dark Chocolate:Formulated from cocoa mass, cocoa butter, and sugar without milk solids, achieving stable polymorph structure through conventional tempering between 27°C and 32°C. Demand concentrates in German supermarkets where EFSA-compliant labeling enables placement in conventional confectionery aisles alongside premium positioning.
- Milk Chocolate:Employs oat or rice milk extracts combined with enzymatic hydrolysis to replicate dairy fat crystallization behavior and mouthfeel. Belgian processing corridors are reconfiguring tempering lines toward this segment as oat milk extraction advances remove previous texture barriers.
- Raw Chocolate:Unroasted bean processing below 46°C preserves antioxidant compounds and enzyme activity. Swiss and German health food shops command premium pricing for this positioning.
- Gourmet Chocolate:Single-origin certifications and limited-batch releases through direct-to-consumer channels. Berlin-Munich artisan networks generate knowledge spillovers in bean sourcing for this tier.
Dark chocolate anchors the volume base while milk chocolate gains share at the steepest rate as enzymatic fat structuring collapses the cost-performance gap with dairy analogs.
Ingredient Type:
Cost tier differentiation separates commodity inputs from specialty alternatives, with cocoa butter commanding premium positions against plant-based milk derivatives that scale through enzymatic processing.
- Cocoa Butter:Primary lipid source determining snap, gloss, and melting profile through polymorph V stabilization. West African supply chains face deforestation-free verification timelines that extend procurement cycles.
- Coconut Sugar:Low-glycemic sweetener alternative gaining traction in raw chocolate formulations. German health food shops favor this positioning for metabolic health claims.
- Almond Milk:Early plant-based milk alternative with established consumer recognition but limited fat crystallization compatibility. Mid-tier manufacturers blend this with cocoa butter for cost-managed recipes.
- Cashew Cream:Premium fat source delivering superior mouthfeel and emulsion stability. Swiss gourmet producers leverage this for high-margin limited releases.
Cocoa butter dominates input costs while cashew cream expands most quickly in premium tier applications.
Distribution Channel:
Channel fragmentation creates divergent margin structures, with direct-to-consumer subscription models displacing wholesale intermediaries in gourmet segments while mass retail scales volume through compound coating supply arrangements.
- Online Retail:Direct-to-consumer subscription models for single-origin and limited-batch releases. Swiss manufacturers bypass wholesale margin structures through membership-based access.
- Supermarkets:Mass retail placement requires EFSA nutrition claims compliance and REACH food contact material certification. Barry Callebaut supplies compound coatings for private-label vegan lines in this channel.
- Specialty Stores:Curated shelf space for artisan producers with vegan certification. Berlin and Munich host dense networks in this tier.
- Health Food Shops:Antioxidant-focused positioning for raw chocolate variants with premium pricing power.
Supermarkets anchor volume throughput while online retail climbs the fastest as direct-to-consumer models capture willingness-to-pay through exclusive origin storytelling.
Packaging Type:
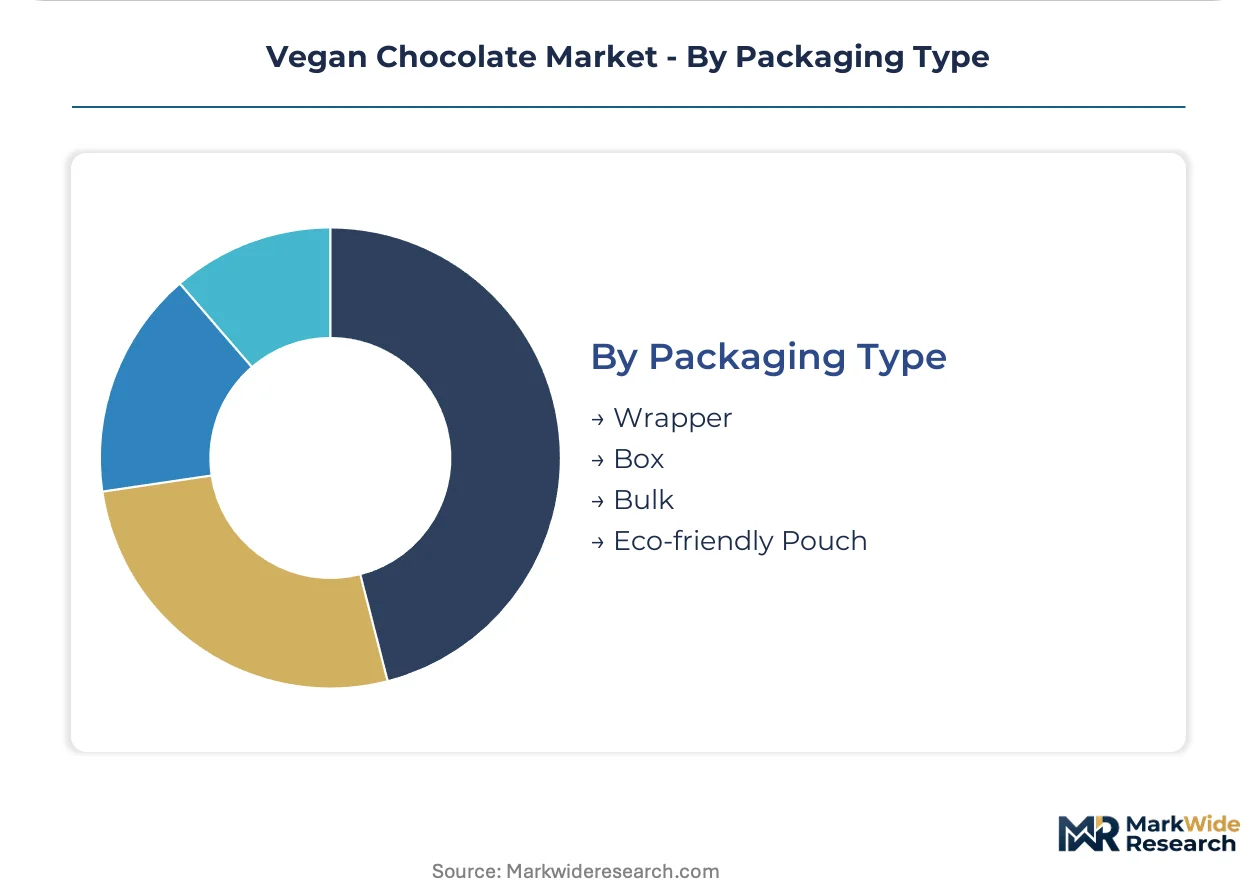
Application context drives format selection, with individual wrappers serving impulse purchase occasions while bulk formats address foodservice and manufacturing ingredient demand.
- Wrapper:Individual portion packaging for convenience retail and on-premise consumption. REACH migration testing for plant-based emulsifier interactions adds 8-14 week lead times.
- Box:Gift-oriented formats commanding premium pricing in Swiss and German gourmet segments. Seasonal launches concentrate demand in this format.
- Bulk:Foodservice and manufacturing ingredient supply with cost efficiency focus. Belgian processing corridors supply this tier through compound coating arrangements.
- Eco-friendly Pouch:Flexible packaging with biodegradable barrier films aligning with EU Green Deal sustainability mandates. German private-label suppliers maintain parallel specifications for multi-country retail contracts.
Wrapper formats dominate unit volume while eco-friendly pouches gain share fastest as regulatory disclosure requirements tighten packaging compliance standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA labeling standards anchor European market development, with Germany's dense producer networks and Switzerland's premium manufacturing discipline setting the competitive template for plant-based confectionery expansion.
Germany
Berlin and Munich host the densest concentration of vegan-certified artisan chocolate producers in Europe, generating knowledge spillovers in bean sourcing and small-batch processing. The EU Green Deal's tightening ingredient disclosure requirements accelerate facility reconfiguration toward allergen-segregated production lines. Bavarian processing clusters are expanding dairy-free tempering capacity to capture private-label contract growth from mass retail chains.
Switzerland
Swiss manufacturing discipline anchors premium positioning through controlled-origin cacao sourcing and precise tempering protocols between 27°C and 32°C. Swissmedic food safety frameworks govern health claim substantiation for antioxidant-focused raw chocolate variants. Zurich and Geneva direct-to-consumer subscription models bypass wholesale intermediaries through membership-based access to limited-batch releases.
Belgium
The cocoa processing corridor stretching from Antwerp to Brussels is reconfiguring capacity toward dairy-free tempering lines and allergen-segregated facilities. REACH food contact material compliance adds 8-14 week lead times to packaging certification for plant-based emulsifier interactions. Barry Callebaut leverages bean-to-bar infrastructure to supply compound coatings for private-label vegan lines serving multi-country retail contracts.
United States
FDA allergen labeling rules shape cross-border ingredient sourcing and packaging compliance for vegan chocolate exporters targeting European markets. California and New York Metro area health food shops command premium pricing for raw chocolate positioning. Domestic mass retail placement accelerates through compound coating supply arrangements with mid-tier private-label distributors.
United Kingdom
London specialty retailers curate shelf space for plant-based alternatives alongside conventional confectionery aisles. EFSA nutrition claims framework clarification enables protein equivalence labeling for oat milk chocolate analogs. Midlands-based manufacturing facilities are piloting precision fermentation-derived cocoa butter equivalents to collapse cost-performance gaps with dairy formulations.
Vegan Chocolate Market Key Industry Players
Capability concentration sits with Swiss and Belgian bean-to-bar specialists possessing polymorph stabilization expertise; scale advantage sits with multinational confectionery conglomerates distributing through mass retail channels across multiple continents. The market structure fragments across three tiers: premium artisan producers with single-origin certifications, mid-scale compound coating suppliers serving private-label contracts, and mass-market brands leveraging existing distribution infrastructure. Strategic moves concentrate on capacity expansion in dairy-free tempering lines and portfolio diversification into raw and gourmet positioning.
Among scale-driven multinationals, Nestle S.A., Mars, Inc., and Mondelez International, Inc. exemplify the mass-market tier through existing confectionery distribution networks and compound coating supply capabilities. These entities occupy positions that leverage shelf space relationships with supermarket chains while navigating EFSA and FDA labeling compliance for plant-based line extensions. Their geographic span across European and North American markets anchors volume throughput in the category.
| Leading Market Players |
|---|
| Nestle S.A |
| Mars, Inc. |
| Mondelez International, Inc. |
| The Hershey Company |
| Barry Callebaut |
| Lindt & Sprungli AG |
| Plamil Foods Ltd |
| Alter Eco |
| Endangered Species Chocolate |
| Others |
Cost & Logistics Intelligence
Belgian cocoa processing corridors concentrate dairy-free tempering capacity, anchoring margin pools with bean-to-bar specialists who command premiums through deforestation-free certification and polymorph stabilization expertise unavailable to mid-tier compound coating suppliers.
Pricing Analysis
Swiss and German gourmet segments command 40-60% spreads over mass retail milk chocolate analogs, with price differentiation anchored in single-origin certification tier and direct-to-consumer subscription access. Three-tier pricing structure across premium, standard, and economy levels separates raw chocolate health positioning from private-label supermarket placement and bulk foodservice supply. Cost compression in mid-tier oat milk formulations is intensifying because enzymatic hydrolysis advances democratize dairy-comparable mouthfeel. Mass retail buyers exhibit highest price sensitivity, while Swiss subscription members accept sustained premiums for limited-batch provenance.
Supply Chain Analysis
EU REACH frameworks governing food contact materials restrict cross-border flows of plant-based emulsifier packaging, extending certification timelines for exporters targeting multi-country retail contracts. Supply concentrates in Côte d'Ivoire and Ghana for cocoa butter, the Netherlands and Germany for oat milk extraction infrastructure, and Belgium for dairy-free tempering line capacity. Raw material dependencies include West African cocoa mass, enzymatically structured oat lipids, and cashew cream for premium emulsion stability. Single-source vulnerability runs through concentrated Belgian processing corridors where queuing bottlenecks delay private-label vegan line launches. Distribution runs through compound coating arrangements for mass retail, direct-to-consumer subscriptions for gourmet tiers, and specialty retailer curated placement for artisan producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived cocoa butter equivalents threaten incumbent positioning by collapsing cost-performance gaps that previously protected premium-tier pricing, forcing established manufacturers to defend through supply chain control and certification depth.
For Market Incumbents: Insulate margin pools through backward integration into deforestation-free West African sourcing and captive dairy-free tempering capacity expansion in Bavarian processing clusters. Counter precision fermentation substitutes by deepening single-origin certification portfolios and exclusive direct-to-consumer subscription relationships that lock in willingness-to-pay through scarcity mechanics. For New Entrants and Emerging Players: Establish a beachhead in raw chocolate antioxidant positioning for German health food shops where incumbents lack specialized unroasted bean processing expertise. Target Berlin-Munich artisan network adjacencies for knowledge spillover access in small-batch tempering protocols. Lead with eco-friendly pouch packaging aligned with EU Green Deal mandates to bypass incumbent packaging specification advantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale compound coating suppliers serving private-label supermarket contracts. Long-term viability hinges on deforestation-free traceability infrastructure and enzymatic fat structuring capabilities rather than commodity cocoa exposure. Watch precision fermentation lipid adoption rates as the inflection signal separating premium-defensible from commoditized positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Deforestation-Free Certification Program | EU traceability mandates now require verified supply chains for cocoa procurement compliance. |
| Dairy-Free Tempering Line Expansion | Belgian processing corridors face queuing bottlenecks limiting private-label vegan contract growth. |
| Direct-to-Consumer Subscription Launch | Swiss manufacturers bypass wholesale margins through membership-based limited-batch access models. |
| Precision Fermentation Lipid Partnership | Dutch and German pilots demonstrate cost-competitive milk chocolate analogs without agricultural cocoa. |
| Eco-Friendly Packaging Specification | REACH migration testing requirements favor suppliers with parallel multi-country certification capabilities. |
Research Approach
Desk research of EFSA nutrition claims filings, EU Green Deal regulatory texts, and cocoa sustainability certification databases preceded structured interviews with Belgian processing corridor plant managers, German supermarket category buyers, Swiss artisan chocolate makers, and Dutch precision fermentation R&D directors. Primary fieldwork combined with secondary validation against SEC filings of listed confectionery conglomerates and customs trade data for cocoa butter imports. Bottom-up segment sizing triangulated against top-down market value estimates.
Assumptions held fixed include EFSA labeling framework stability, REACH food contact material enforcement continuity, and oat milk extraction technology diffusion rates; variables stress-tested included cocoa butter price volatility bands and precision fermentation lipid cost curves. The analytical framework modeled volume and value across product type, ingredient tier, distribution channel, and packaging format dimensions. CAGRs derived from segment-level growth rate synthesis weighted by base-year revenue contributions. Forecast inputs incorporated enzymatic hydrolysis adoption timelines and deforestation-free verification completion rates.
Stress conditions across West African weather disruption severity, EU regulatory disclosure tightening pace, and plant-based emulsifier packaging migration test delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factor weightings. Material shifts in precision fermentation lipid cost competitiveness or EU traceability mandate enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Textured Pea Protein Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Yucca Extract Market
Plant Based Food
China Plant-Based Food and Beverages Market
Plant Based Food
Plant-Based Waters Market
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Smart Plant Based Food Packaging Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Plant Based Eggs Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Faba Bean Protein Market
Plant Based Food
Plant-Based Nuggets Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Kava Root Extract Market