
 Ruby Chocolate Market | 2026-2036
Ruby Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Ruby Chocolate Market Analytics
Multi-source cocoa procurement is broadening as manufacturers diversify beyond traditional bean supply chains. Barry Callebaut leverages its integrated bean-to-bar infrastructure to secure consistent ruby cocoa volumes. Nestlé competes through scaled confectionery distribution across European and Asian retail networks. Fazer anchors Nordic market presence with specialized ruby chocolate formulations for seasonal product cycles.
Ruby chocolate derives its distinctive pink hue and berry-fruit notes from specific ruby cocoa bean varieties processed without added colorants or flavor masking, yielding a natural anthocyanin-derived pigmentation. The product serves premium confectionery and bakery sectors seeking differentiated positioning beyond conventional milk, dark, or white chocolate categories. Ruby confectionery and ruby coating applications command margin premiums in artisanal chocolate products and ice cream inclusions. Bakery products represent an emerging application vector as commercial kitchens integrate ruby chips into patisserie and viennoiserie formats.
EU EFSA novel food assessments and FDA GRAS determinations govern ruby chocolate market access across primary Western jurisdictions, with labeling standards enforced by national food safety authorities. REACH compliance for processing aids and EU deforestation-free supply chain regulations reshape cocoa sourcing verification requirements. Stakeholders must monitor evolving novel food approvals in Asia-Pacific jurisdictions and adapt traceability systems to emerging due diligence mandates.
Market Dynamics
EU deforestation-free supply chain regulations and novel food authorization frameworks are compressing sourcing timelines while forcing bean-to-bar traceability investments across Western European markets.
Growth Catalysts
- Ruby cocoa bean varietal expansion:Specialized cultivation programs in Ecuador and Brazil are securing proprietary bean volumes for premium confectionery applications.
- EU EFSA novel food pathway:Streamlined authorization processes under the 2015/2283 regulation are accelerating ruby chocolate product launches across member states.
- Artisanal bakery integration:Commercial patisserie and viennoiserie segments are adopting ruby chips as differentiated inclusions for seasonal product cycles.
Market Restraints
- Bean supply concentration:Ruby cocoa varietals depend on specific terroirs in Ecuador and Ivory Coast, creating geographic concentration risk.
- Processing cost structure:Unfermented bean protocols and controlled anthocyanin preservation require specialized infrastructure absent in conventional chocolate processing.
- White chocolate substitution:Lower-cost white chocolate with added colorants competes in price-sensitive confectionery segments.
Strategic Opportunities
- Asia-Pacific regulatory openings:Japan's PMDA and South Korea's MFDS are evaluating novel food applications, creating first-mover positioning potential.
- Ice cream inclusion expansion:Ruby coating applications for premium frozen dessert bars remain underdeveloped relative to confectionery saturation.
- Direct-to-consumer channels:Specialty chocolate subscription services and chef-direct platforms are bypassing traditional retail gatekeepers.
Industry Challenges
- Anthocyanin stabilization expertise:Food chemists with ruby-specific processing knowledge remain scarce relative to conventional chocolate technology pools.
- Dual certification timelines:simultaneous EU organic and Fairtrade approvals extend product development cycles by 18-24 months.
- Legacy ERP integration:Bean-to-bar traceability systems require reconfiguration of existing supply chain software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ruby Chocolate Market |
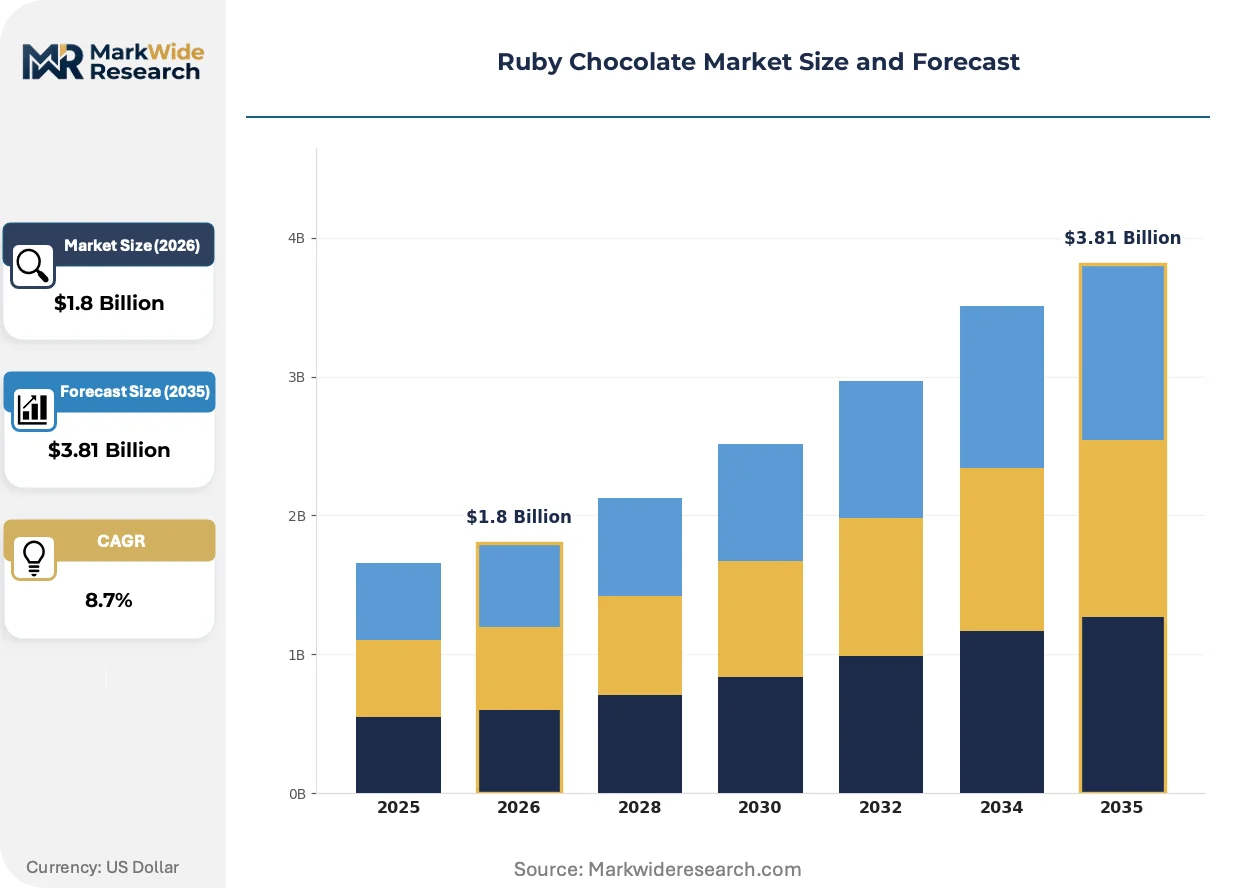
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ruby Bars, Ruby Chips, Ruby Coating, Ruby Confectionery End User: Retailers, Food Manufacturers, Bakery Shops, Online Stores Application: Chocolate Products, Bakery Products, Ice Cream, Snacks Packaging Type: Bags, Boxes, Pouches, Bulk Packaging |
| Companies Covered | Barry Callebaut, Nestlé, KitKat, Leonidas, Prestat, Fazer, Rococo Chocolates, AANI & DANI, Oilean Chocolates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ruby Chocolate Market Evolving Landscape
Processing technology advances and shifting procurement patterns are reconfiguring how ruby chocolate moves from bean to finished confectionery, with regulatory pressure accelerating transparency investments.
Precision fermentation of cocoa pulp extracts is electrifying alternative ruby flavor development, allowing manufacturers to replicate berry-fruit notes without proprietary bean dependency. Ingredient technology firms in Switzerland and the Netherlands are piloting these bioprocesses at commercial scale. The technology is electrifying competitive positioning by decoupling premium positioning from geographic bean sourcing constraints.
EU deforestation-free regulation (EUDR) entered full enforcement in December 2024, mandating geolocation verification for all cocoa batches entering European supply chains. Chocolate manufacturers must now deploy satellite-linked farm mapping and mass-balance documentation systems. Small-batch artisanal producers face disproportionate compliance burdens relative to integrated processors with captive agronomy teams.
Chef-driven specification is replacing commodity procurement in premium segments, with pastry chefs and chocolatiers now dictating bean origin and processing parameters directly. This disintermediation compresses traditional distributor margins while rewarding manufacturers with technical service capabilities. The pattern is most visible in France and Belgium, where institutional buyers in haute cuisine and luxury hospitality command sourcing priority.
Ruby Chocolate Market Segmentation
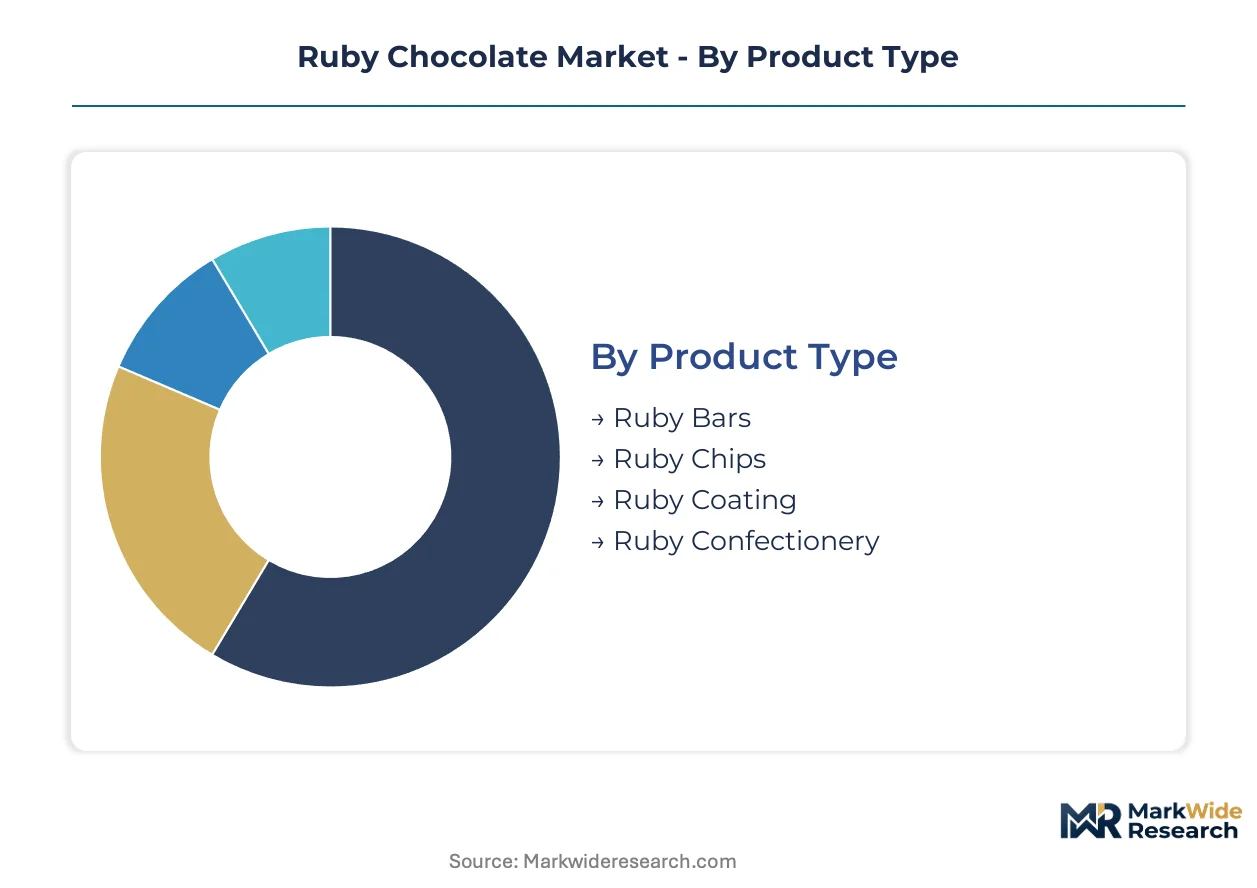
Ruby chocolate segmentation reveals how distinct buyer requirements reshape product specifications across confectionery, bakery, and frozen dessert channels. Processing protocols and anthocyanin preservation needs vary sharply by end-use application, driving specialized formulation investments.
Product Type:
Industrial buyers differentiate by processing stage and integration complexity into downstream manufacturing lines.
- Ruby Bars:Solid format for direct retail sale and artisanal chocolatier remelting. Premium positioning in Belgian and French specialty retail commands formulation precision for snap texture and gloss retention.
- Ruby Chips:Standardized callet sizing optimized for automated bakery and ice cream inclusion lines. Patisserie integration in Nordic markets drives demand for controlled melt profiles in laminated dough applications.
- Ruby Coating:Lower viscosity formulations for enrobing and panning operations. Ice cream bar manufacturers specify coating variants for thermal shock resistance during frozen distribution.
- Ruby Confectionery:Finished packaged products including pralines, tablets, and seasonal gift formats. Japanese department store channels favor refined particle size for mouthfeel differentiation.
Volume sits with Ruby Chips; growth tilts toward Ruby Coating.
End User:
Procurement scale and technical service requirements separate mass-market distributors from specification-driven artisanal buyers.
- Retailers:Supermarkets, specialty food stores, and department store food halls managing seasonal assortment planning. German and UK grocery chains prioritize private-label ruby ranges for Q4 gifting cycles.
- Food Manufacturers:Industrial confectionery and frozen dessert producers with integrated chocolate processing. Swiss and Italian manufacturers dominate scaled procurement for pan-European brand distribution.
- Bakery Shops:Independent patisseries and regional bakery chains requiring small-batch flexibility. Parisian and Vienna viennoiserie specialists drive specification innovation for laminated applications.
- Online Stores:Direct-to-consumer platforms and subscription services bypassing traditional wholesale. Nordic markets show strongest penetration for chef-direct and gifting-focused e-commerce.
Food Manufacturers capture volume leadership; Bakery Shops expand most quickly.
Application:
Thermal processing tolerance and flavor pairing requirements dictate formulation segmentation across finished goods categories.
- Chocolate Products:Core confectionery applications including tablets, pralines, and enrobed items. Belgian and Swiss premium brands anchor positioning through controlled particle refinement and temper stability.
- Bakery Products:Inclusion and decoration uses in croissants, cakes, and viennoiserie. French laminated dough specialists specify chip formats that resist fat bloom through multi-day production cycles.
- Ice Cream:Coating and inclusion applications for premium frozen dessert bars. Italian gelato manufacturers and Japanese ice cream innovators drive coating viscosity specifications for dipping operations.
- Snacks:Emerging category spanning ruby-drizzled popcorn, granola clusters, and fruit-nut combinations. Dutch and UK snack innovators test limited editions for millennial-targeted convenience positioning.
Chocolate Products dominate current volume; Ice Cream claims the steepest expansion trajectory.
Packaging Type:
Supply chain configuration and buyer handling infrastructure determine format selection from artisanal to industrial scale.
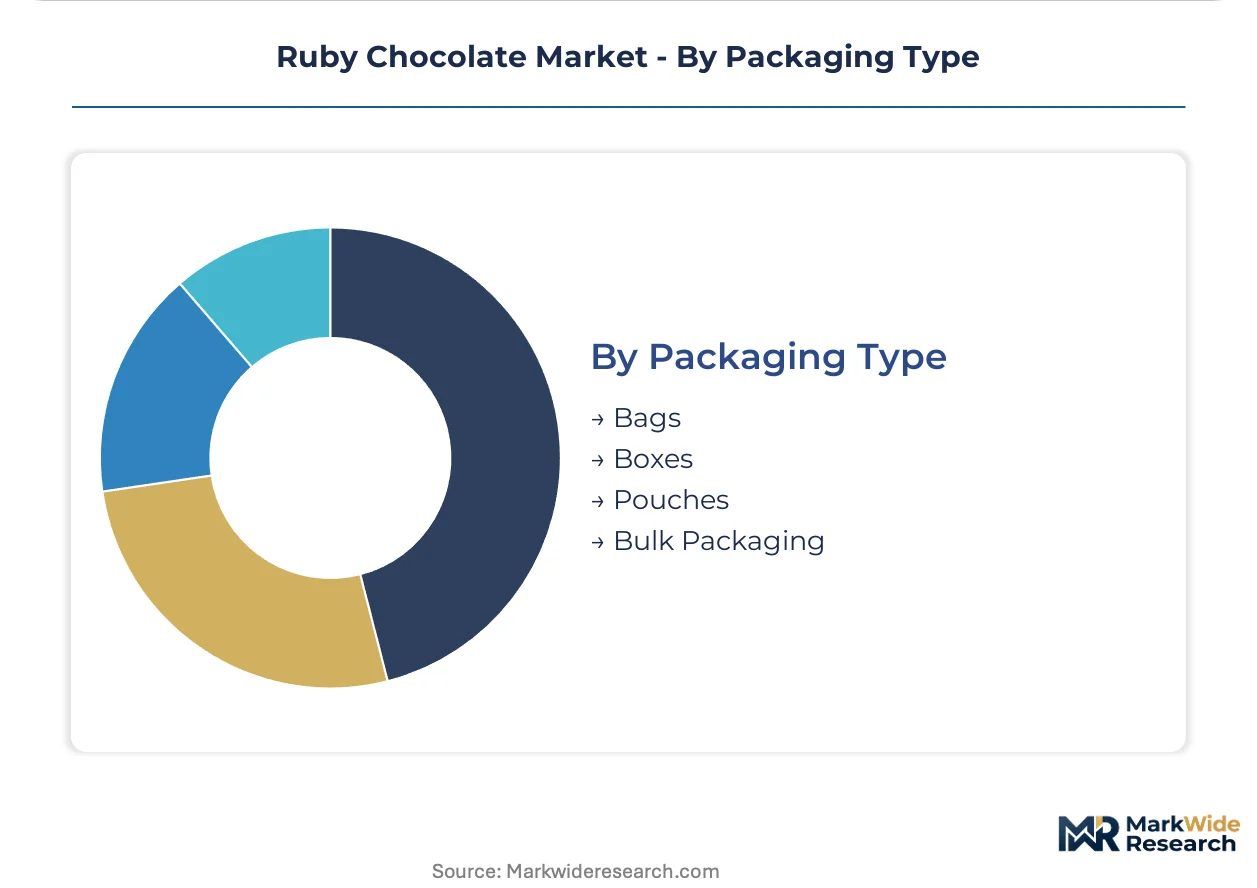
- Bags:Flexible packaging for retail portion control and foodservice bulk. UK and German retail channels favor resealable formats for home baking segments.
- Boxes:Rigid presentation packaging for gifting and premium retail. Japanese department stores and Belgian chocolatiers specify box formats for seasonal assortment merchandising.
- Pouches:Stand-up and flat pouch configurations for e-commerce and convenience retail. Nordic online channels prefer lightweight pouches for reduced shipping cost.
- Bulk Packaging:Industrial totes and drums for manufacturing integration. Swiss and Italian confectionery plants specify temperature-controlled bulk logistics for just-in-time production.
Bulk Packaging handles manufacturing volume; Boxes gain share fastest in premium gifting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer willingness to pay for differentiated cocoa products concentrates in Western European markets, with artisanal bakery applications and premium confectionery channels driving geographic demand patterns. Regulatory frameworks in the EU, Japan, and select Asia-Pacific jurisdictions shape market access trajectories. Processing infrastructure clusters around established chocolate manufacturing regions with bean-to-bar capabilities.
Belgium
Belgian praline manufacturers and specialty chocolatiers anchor premium ruby chocolate demand through controlled particle refinement specifications. EFSA novel food authorization under Regulation 2015/2283 streamlines product launches across EU member states. Brussels and Flemish chocolate clusters drive formulation innovation for snap texture and gloss retention in artisanal applications.
Switzerland
Swiss industrial confectionery producers dominate scaled procurement for pan-European brand distribution with integrated chocolate processing lines. REACH compliance for processing aids and EU deforestation-free supply chain regulations reshape cocoa sourcing verification requirements. Zurich and Lake Geneva manufacturing corridors deploy temperature-controlled bulk logistics for just-in-time production cycles.
Japan
Japanese department store channels and ice cream innovators favor refined particle size for mouthfeel differentiation in premium positioning. PMDA novel food evaluations are progressing for ruby chocolate market access, creating first-mover positioning potential. Tokyo and Osaka food halls drive seasonal assortment merchandising through gifting-focused retail formats.
France
French laminated dough specialists and haute cuisine institutional buyers dictate bean origin and processing parameters through chef-driven specification. ANSM labeling enforcement and national food safety authority standards govern ingredient transparency requirements. Parisian viennoiserie clusters and Provence artisanal networks specify chip formats resisting fat bloom through multi-day production cycles.
Germany
German grocery chains prioritize private-label ruby ranges for Q4 gifting cycles with resealable packaging formats for home baking segments. KBA-equivalent food safety oversight and EU organic certification timelines extend product development cycles. Cologne and Munich retail corridors integrate seasonal assortment planning for mass-market distribution scale.
Ruby Chocolate Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated processors secure proprietary bean volumes through specialized cultivation programs. The vendor base concentrates around bean-to-bar specialists with captive agronomy teams and scaled confectionery distributors with European and Asian retail network penetration. Three archetypes define competitive positioning: integrated cocoa processors controlling upstream supply, diversified confectionery conglomerates leveraging distribution scale, and regional artisanal specialists anchoring seasonal product cycles. M&A activity and strategic partnerships reshape market share, while portfolio diversification into bakery and frozen dessert applications extends addressable channels.
Among integrated cocoa processors, Barry Callebaut exemplifies the bean-to-bar archetype with infrastructure spanning bean sourcing through finished chocolate production. Nestlé occupies a position representing diversified confectionery scale with pan-regional retail network access. Fazer anchors Nordic market specialization with regional formulation expertise for seasonal cycles. These three entities represent distinct competitive vectors: upstream supply control, mass-market distribution leverage, and geographic niche dominance.
| Leading Market Players |
|---|
| Barry Callebaut |
| Nestlé |
| KitKat |
| Leonidas |
| Prestat |
| Fazer |
| Rococo Chocolates |
| AANI & DANI |
| Oilean Chocolates |
| Others |
Value Network & Pricing Analysis
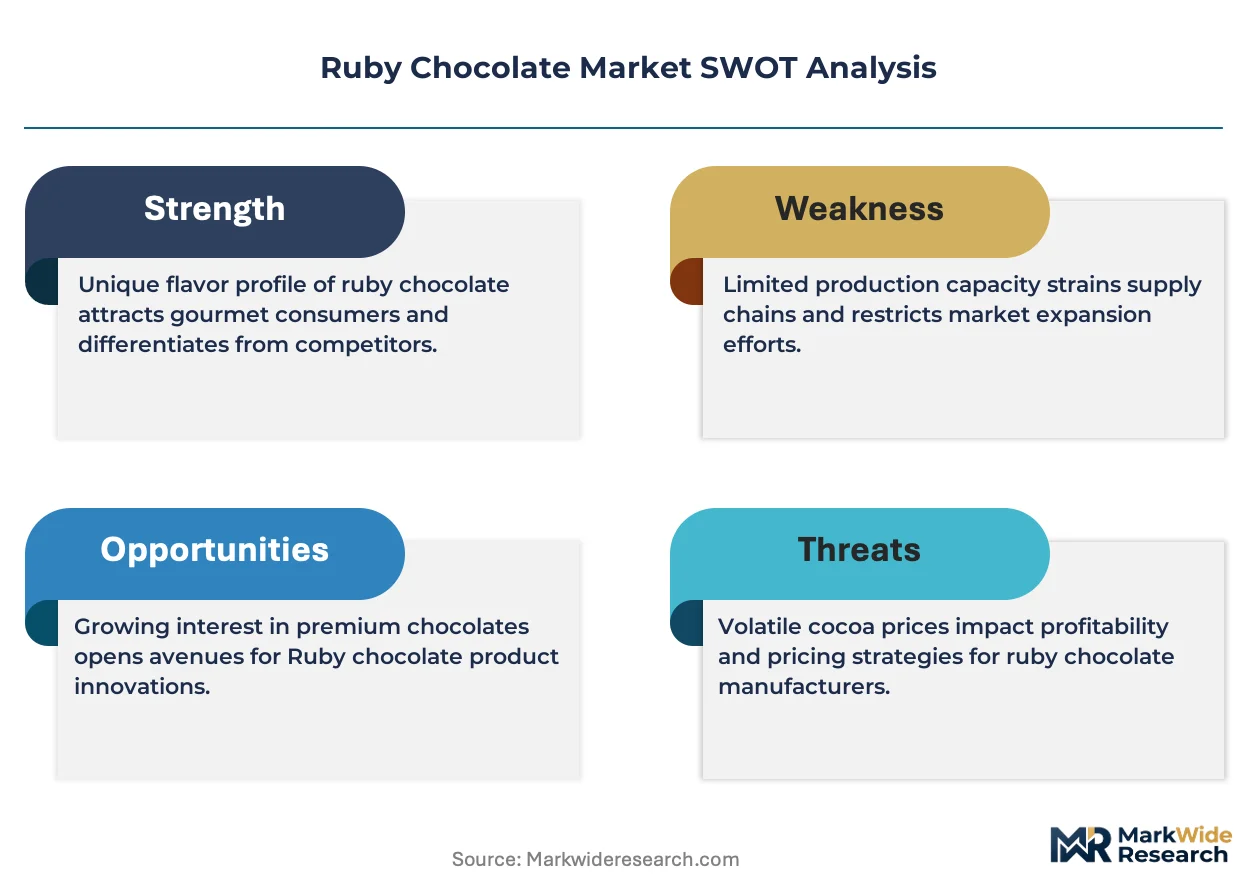
Family-owned cocoa processors with multi-generational sourcing relationships anchor pricing discipline through captive farm partnerships in Ecuador and Ivory Coast, insulating premium ruby chocolate tiers from commodity cocoa volatility while forcing contract renegotiations with price-sensitive industrial buyers.
Pricing Analysis
Volume concentrates in industrial ruby chips for automated bakery lines, while margin accrues to artisanal ruby bars for specialty retail. Three-tier pricing structure across premium, standard, and economy levels separates Belgian praline specifications from German private-label ranges. Pricing pressure stems from white chocolate substitution with added colorants in Asian mass-market segments. Food manufacturers exhibit highest price sensitivity due to formulation cost targets, whereas Parisian viennoiserie specialists accept premium positioning for provenance documentation.
Supply Chain Analysis
Direct-to-chef channels handle specification-driven demand from French haute cuisine and Belgian chocolatier ateliers, bypassing traditional distributor markups. Bean supply draws from Ecuadorian and Ivorian terroirs with proprietary ruby varietal cultivation, resting on unfermented processing protocols and controlled anthocyanin preservation. Single-source vulnerability concentrates in Ecuador's coastal growing regions exposed to climate volatility. Distribution runs through temperature-controlled bulk logistics for Swiss and Italian confectionery plants, with artisanal callet sizing for Nordic patisserie integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology for cocoa pulp extract replication is displacing proprietary bean dependency, compressing the window for incumbent processors to secure varietal supply advantages before laboratory-derived flavor profiles achieve cost parity.
For Market Incumbents: Deepen backward integration into Ecuadorian farm mapping systems to satisfy EUDR geolocation mandates before compliance deadlines tighten. Anchor capacity expansion in Brazilian ruby varietal programs to diversify beyond Ivory Coast concentration risk. Prioritize anthocyanin stabilization R&D to defend formulation expertise against biotech entrants. For New Entrants and Emerging Players: Artisanal ice cream inclusion specialists represent the most penetrable buyer archetype, with coating viscosity specifications still unsettled and Italian gelato manufacturers seeking differentiated frozen dessert positioning. Target Japanese department store food halls through refined particle size offerings that command mouthfeel premiums. Pursue chef-direct subscription models to bypass entrenched European distributor networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale processors with EFSA novel food approvals already secured but lacking capital for EUDR traceability infrastructure. Position for consolidation plays across Nordic seasonal chocolate specialists with strong regional brand equity but limited export compliance capabilities. Monitor PMDA authorization timelines as the inflection signal for Asia-Pacific market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Bean-to-Bar Traceability Investment | EUDR satellite-linked farm mapping satisfies EU deforestation-free mandates for Belgian and Swiss manufacturers. |
| Precision Fermentation Partnership | Bioprocess licensing from Swiss and Dutch ingredient technology firms decouples premium positioning from geographic sourcing constraints. |
| Artisanal Bakery Channel Expansion | Ruby chip specifications for laminated dough applications capture Parisian and Vienna viennoiserie demand. |
| Asia-Pacific Regulatory Approval | PMDA and MFDS novel food pathways unlock first-mover positioning in Japanese department store channels. |
| Direct-to-Consumer Platform Launch | Chef-direct subscription services bypass traditional retail gatekeepers in Nordic gifting-focused e-commerce segments. |
Research Methodology
Document review covered EFSA novel food authorization records, EU deforestation-free regulation implementation guidance, and customs trade data for cocoa bean imports, complemented by interviews with chocolate processing executives, pastry chef specification buyers, and food safety compliance officers. Secondary validation drew from REACH processing aid registrations, PMDA consultation documents, and Fairtrade certification timelines. Bottom-up demand modeling across bakery, confectionery, and ice cream channels triangulated against top-down cocoa grinding statistics.
Segment-level outputs across product type, end user, application, and packaging format dimensions were generated through the projection horizon. CAGRs were derived from elasticity-adjusted volume trajectories incorporating ruby varietal expansion rates and artisanal adoption curves. Industry-specific inputs included anthocyanin preservation technology maturity, novel food approval pathway durations, and chef-driven specification penetration indices.
Revisions become necessary when precision fermentation achieves cost parity with bean-derived ruby chocolate, or when EUDR enforcement tightens beyond current geolocation documentation requirements. Forecasts reflect assumptions regarding continued EU market access dominance and stable Ecuadorian ruby varietal yields. Periodic stress-testing of base assumptions against biotech flavor replication timelines and Asia-Pacific regulatory acceleration scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Coffee Gummy Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Japan Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
Chocolate Couverture Market
Confectionery
Licorice Candy Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Middle East Chocolate Market
Confectionery
Cocoa and Chocolate Market
Confectionery
North America Gummy Market
Confectionery
Caramel Chocolate Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market
Confectionery
United States and Europe Macarons Market
Confectionery
Infused Fruits Jellies Market
Confectionery
North America Marshmallow Market