
 Chocolate Processing Equipment Market | 2026-2036
Chocolate Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Processing Equipment Market Outlook
Equipment leasing and project finance is fragmenting competitive access across the chocolate processing landscape. Aasted ApS leverages its tempering technology leadership to anchor premium contracts with industrial manufacturers. Sollich KG competes through specialized enrobing and cooling tunnel designs that sustain its position in European confectionery hubs.
Chocolate processing equipment encompasses machinery engineered to transform cocoa liquor, butter, and solids into finished confectionery through controlled thermal, mechanical, and aeration processes, typically operating within precise temperature bands of 28°C to 50°C for crystallization and viscosity management. Conching machines dominate capital allocation among large manufacturers seeking flavor development and particle size refinement, while automation solutions represent the fastest-expanding technology segment as labor costs pressure batch processing economics. Gourmet chocolates application demand concentrates investment in precision tempering and small-capacity cooling tunnels that protect premium product integrity.
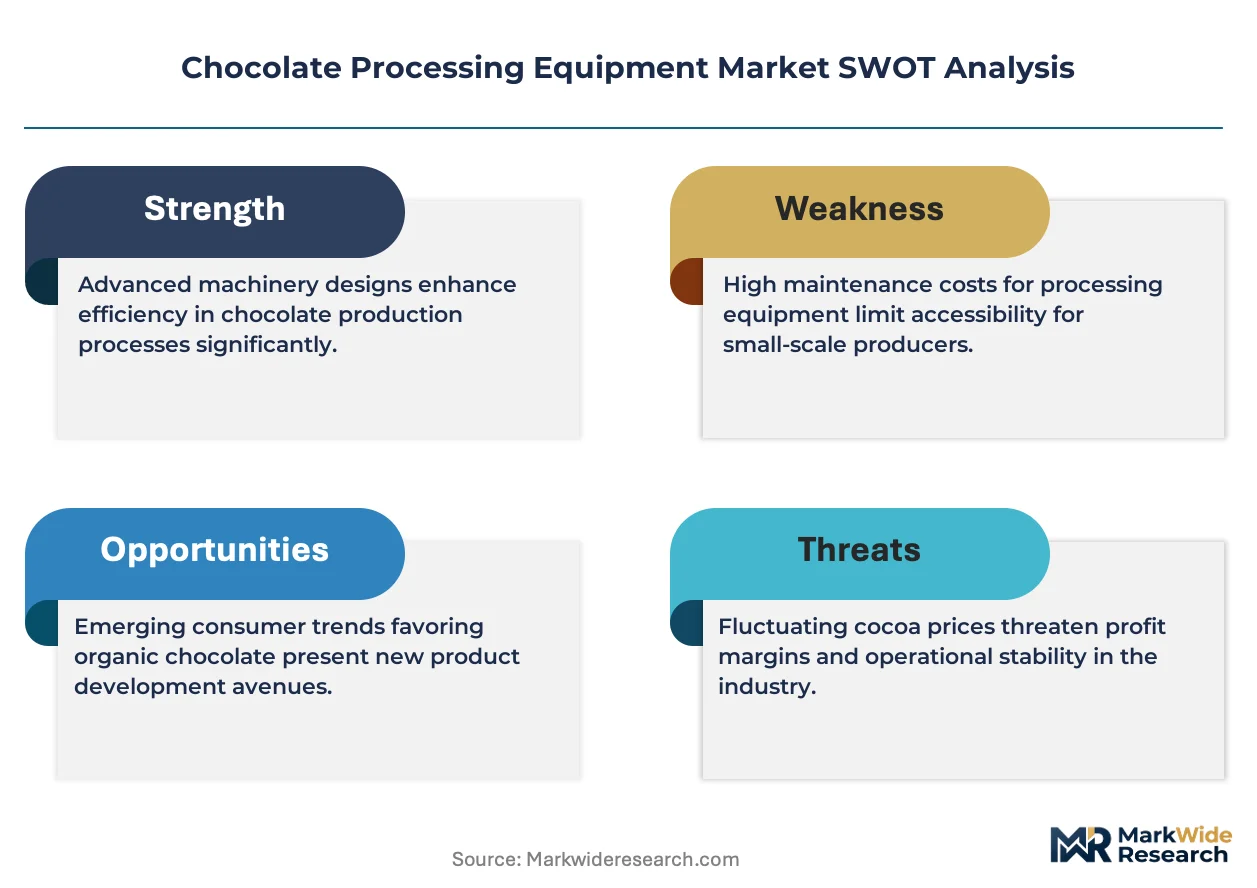
Food manufacturers in Europe navigate EFSA hygiene standards and CE machinery directives that mandate stainless steel contact surfaces and clean-in-place protocols, while US-based producers align with FDA food safety modernization requirements and USDA dairy-crossover regulations where milk chocolate lines operate. ISO 22000 certification shapes supplier qualification thresholds across both regulatory environments. Stakeholders must weigh capital deployment timing between continuous processing scale economies and flexible batch systems that serve contract manufacturing growth.
Market Dynamics
Automation is compressing batch processing economics across chocolate manufacturing, forcing mid-scale producers to choose between continuous line investments and contract manufacturing partnerships as labor costs reset operational thresholds.
Growth Catalysts
- EFSA Hygiene Mandates:Stainless steel contact surface requirements and clean-in-place protocols are accelerating equipment replacement cycles among European processors seeking certification compliance.
- Bean-to-Bar Proliferation:Artisanal chocolate makers in Belgium and Switzerland are driving demand for small-batch tempering and conching systems with precise temperature control.
- Aeration Technology:Controlled mechanical aeration processes are expanding application scope into mousse-based and aerated bar formats that command premium positioning.
Market Restraints
- Cocoa Butter Volatility:Input cost swings for cocoa butter and liquor concentrate are compressing capital allocation flexibility for equipment buyers in price-sensitive segments.
- Specialized Component Concentration:Precision temperature control modules and crystallization sensors rely on concentrated supplier bases in German and Swiss industrial corridors.
- CE Machinery Directive Friction:Extended conformity assessment timelines for modified processing lines are delaying commissioning schedules for brownfield expansions.
Strategic Opportunities
- India FSSAI Alignment:Emerging chocolate consumption in tier-two Indian cities is creating first-mover positioning for suppliers configuring equipment to local dairy-crossover requirements.
- Energy Recovery Convergence:Heat exchange systems integrated with crystallization tunnels are hybridizing thermal efficiency with product quality control in new system architectures.
- Equipment Leasing Channels:Project finance vehicles are opening access barriers for artisanal producers previously excluded from capital-intensive continuous processing lines.
Industry Challenges
- Crystallization Expertise Gap:Shortages of process engineers trained in polymorph-specific tempering protocols are constraining operational uptime for precision-dependent installations.
- ISO 22000 Certification Burden:Extended audit timelines and documentation requirements are stretching supplier qualification cycles for equipment vendors serving multinational food manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Processing Equipment Market |
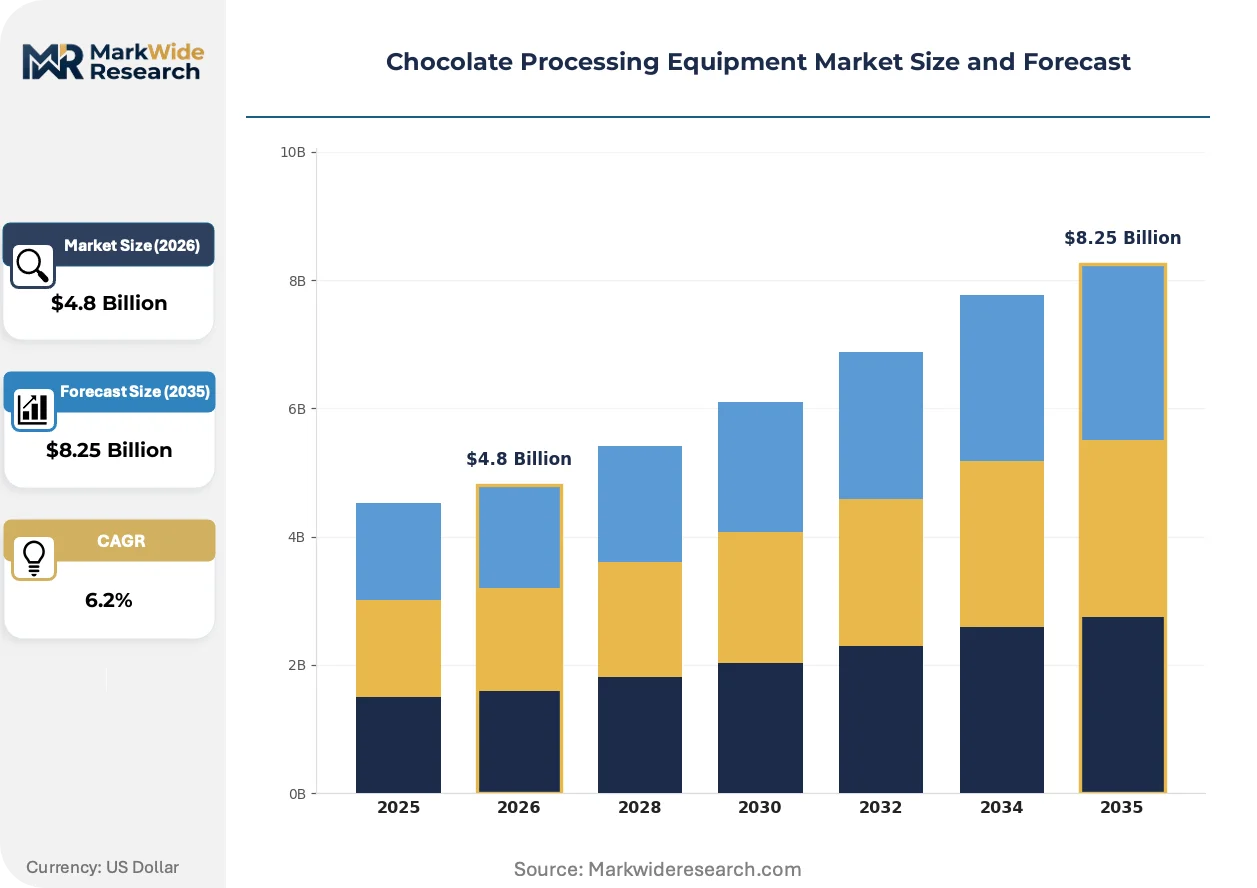
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milling Equipment, Conching Machines, Tempering Machines, Cooling Tunnels Application: Confectionery Production, Bakery Products, Snack Foods, Gourmet Chocolates Technology: Batch Processing, Continuous Processing, Advanced Mixing, Automation Solutions End User: Chocolate Manufacturers, Food and Beverage Companies, Retailers, Artisanal Producers |
| Companies Covered | Aasted ApS, Sollich KG, Bühler Group, Hacos NV, Selmi, GEA Group, Royal Duyvis Wiener, NETZSCH Group, JBT Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Processing Equipment Market Strategic Shifts
Digital process control and thermal efficiency engineering are converging to redefine competitive differentiation in chocolate manufacturing equipment, with precision crystallization management emerging as the critical performance variable.
Induction heating systems for tempering circuits are hybridizing energy efficiency with temperature uniformity control. Mid-scale confectionery manufacturers in Italy and Spain are retrofitting existing lines at accelerating pace. This hybridization is compressing the performance gap between batch and continuous processing economics.
REACH chemical safety assessments are extending to food contact materials in processing equipment, mandating expanded substance testing for polymer seals and lubricants. European OEMs are reformulating component specifications ahead of enforcement deadlines. Gourmet chocolate specialists with export exposure to EU markets are prioritizing pre-certified equipment configurations to avoid supply disruption.
After-sales service unbundling is fragmenting traditional equipment procurement relationships. Industrial buyers are separating maintenance contracts from capital purchases, engaging third-party technical service providers for crystallization calibration and sensor replacement. This pattern is most pronounced among US-based contract manufacturers operating multiple brand lines with varying throughput requirements.
Chocolate Processing Equipment Market Segmentation
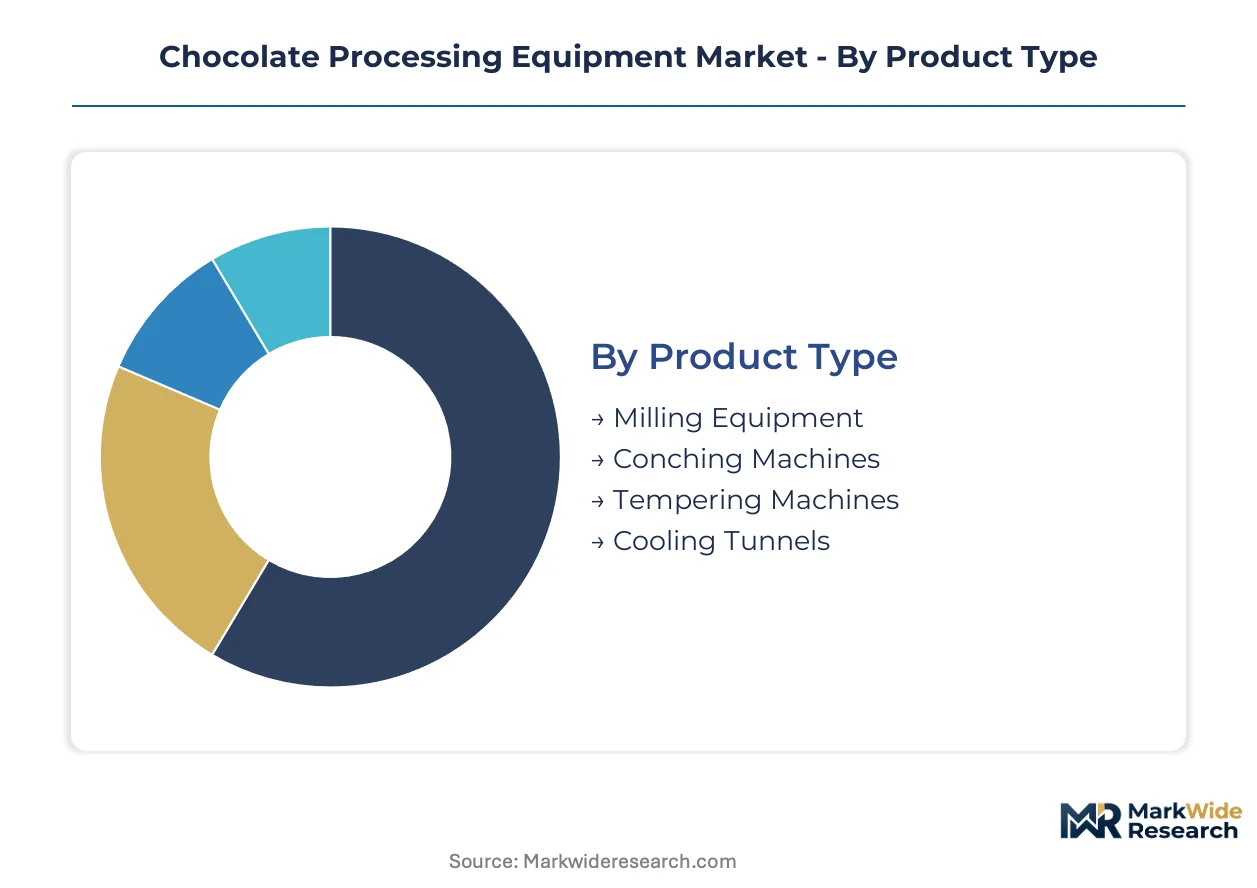
Equipment selection in chocolate processing hinges on crystallization precision, throughput scale, and regulatory compliance architecture. Segment boundaries reflect divergent capital deployment timelines between industrial continuous lines and artisanal batch systems.
Product Type:
Cycle times vary dramatically across equipment categories, with tempering and cooling systems turning over fastest while conching installations anchor decade-long depreciation schedules.
- Milling Equipment:Particle size reduction systems process cocoa nibs into liquor through mechanical shear and pressure, typically achieving 15-25 micron fineness. Demand concentrates in Ghana and Côte d'Ivoire processing hubs where bean origin infrastructure is expanding.
- Conching Machines:Extended thermal-mechanical processing vessels refine flavor development through controlled friction heating and aeration over 12-72 hour cycles. Industrial manufacturers in Switzerland and Belgium allocate the largest capital shares here, constrained by acoustic enclosure requirements and energy recovery integration timelines.
- Tempering Machines:Precision crystallization systems manage polymorph formation through controlled temperature curves. Artisanal producers in Brussels and Zurich prioritize small-capacity units with sensor feedback loops.
- Cooling Tunnels:Conveyor-based thermal conditioning systems solidify tempered chocolate through zoned airflow management. Snack bar manufacturers favor compact modular configurations for line flexibility.
Conching machines dominate installed base. Tempering machines are where expansion concentrates.
Application:
Margin structures diverge sharply across end-use categories, with gourmet positioning commanding 3-4x equipment cost tolerance versus mass confectionery.
- Confectionery Production:Enrobing and molding lines for pralines, tablets, and countlines represent the volume anchor. EFSA hygiene mandates are accelerating stainless steel replacement cycles among European processors.
- Bakery Products:Chocolate inclusion systems for croissants, cookies, and cakes require viscosity-tolerant depositing mechanisms. German and French industrial bakeries drive specification requirements.
- Snack Foods:Coating and drizzling equipment for granola bars and trail mixes prioritizes throughput over crystallization precision. North American contract manufacturers favor quick-changeover designs.
- Gourmet Chocolates:Bean-to-bar and single-origin production demands precise temperature control within 0.5°C tolerance bands. Belgian and Swiss artisanal clusters sustain premium pricing for small-batch tempering and conching configurations.
Confectionery production absorbs the largest equipment volume. Gourmet chocolates generate the steepest expansion trajectory.
Technology:
Customer scale determines technology adoption patterns, with automation solutions penetrating fastest among mid-tier manufacturers facing labor cost pressure.
- Batch Processing:Discontinuous operation suited to recipe flexibility and small production runs. Artisanal producers in Switzerland maintain demand for manually supervised conching and tempering cycles.
- Continuous Processing:Uninterrupted flow systems achieving throughput economies through integrated milling, conching, and tempering sequences. Industrial manufacturers in Germany and the Netherlands anchor investment here.
- Advanced Mixing:High-shear and planetary mixing technologies for aerated and filled chocolate formats. Italian confectionery specialists prioritize mousse-capable configurations.
- Automation Solutions:Sensor networks, robotic handling, and digital process control systems. Mid-scale US and Spanish manufacturers are retrofitting existing lines at accelerating pace.
Continuous processing commands capital deployment scale. Automation solutions are climbing the fastest.
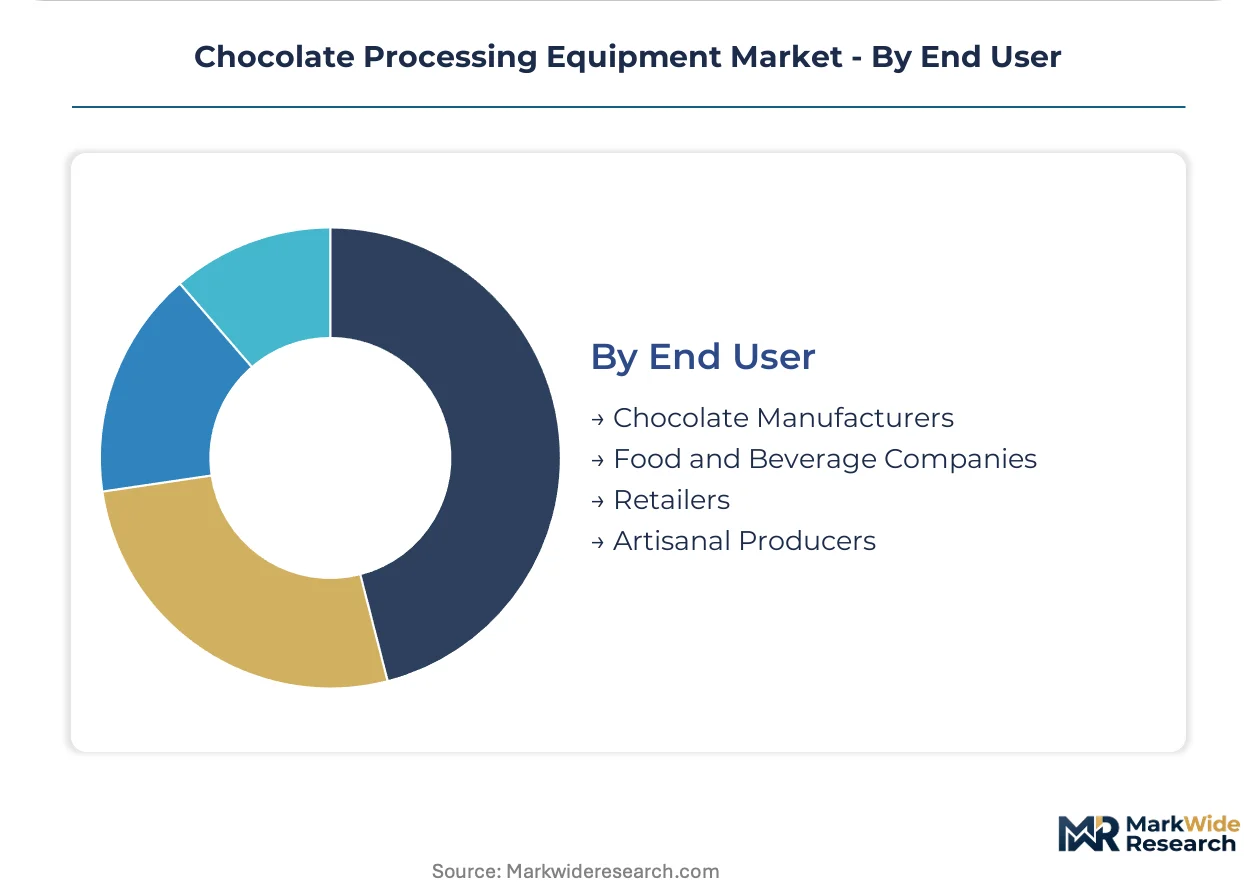
End User:
Procurement authority fragmentation shapes equipment specification complexity, with multinational food manufacturers imposing certification burdens that exclude smaller vendors.
- Chocolate Manufacturers:Dedicated cocoa processors operating integrated bean-to-bar facilities. Swiss and Belgian heritage houses concentrate demand for precision tempering technology.
- Food and Beverage Companies:Diversified manufacturers adding chocolate SKUs to existing portfolios. ISO 22000 certification requirements stretch supplier qualification cycles.
- Retailers:Private-label producers and in-house confectionery operations. German supermarket chains are driving standardization around modular line configurations.
- Artisanal Producers:Small-batch makers emphasizing provenance and craft positioning. Equipment leasing channels are opening access barriers previously excluding this segment from capital-intensive continuous lines.
Chocolate manufacturers anchor equipment revenue. Artisanal producers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German EFSA hygiene mandates and US FDA modernization requirements are reshaping equipment procurement timelines across key processing hubs, while Indian FSSAI alignment and Swiss precision engineering clusters concentrate specialized demand.
Germany
Industrial confectionery manufacturers in North Rhine-Westphalia drive automation retrofit cycles for continuous processing lines. CE Machinery Directive conformity assessments extend commissioning timelines for brownfield expansions. Cologne-based engineering corridors anchor precision temperature control module production for crystallization sensors.
United States
Contract manufacturers operating multiple brand lines favor quick-changeover cooling tunnel configurations. FDA Food Safety Modernization Act requirements and USDA dairy-crossover regulations govern milk chocolate line specifications. Chicago and Philadelphia industrial clusters sustain demand for sensor-integrated tempering systems.
Switzerland
Heritage chocolate houses in Zurich and Geneva concentrate investment in small-batch conching installations with acoustic enclosures. Swissmedic-aligned material safety standards influence polymer seal specifications for food contact surfaces. Vevey and Bern artisanal clusters prioritize 0.5°C tolerance tempering technology for single-origin production.
India
Tier-two city consumption growth in Pune and Ahmedabad creates first-mover positioning for dairy-crossover equipment configurations. FSSAI hygiene standards and BIS machinery safety certifications shape supplier qualification thresholds. Maharashtra and Gujarat processing hubs expand bean-origin infrastructure for milling equipment demand.
Belgium
Brussels artisanal producers sustain premium pricing for precision tempering and small-capacity cooling tunnels. EFSA stainless steel contact surface mandates accelerate replacement cycles among heritage praline manufacturers. Flemish confectionery corridors concentrate enrobing line investments for countline production.
Chocolate Processing Equipment Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement relationships. Equipment leasing vehicles and unbundled after-sales service contracts are compressing traditional vendor loyalty. Three archetypes dominate: tempering technology specialists, integrated continuous line engineers, and modular batch system fabricators. Strategic moves concentrate on geographic licensing partnerships and energy recovery technology convergence.
Among European precision engineering specialists, Aasted ApS and Sollich KG exemplify contrasting competitive positions. Aasted ApS anchors tempering technology leadership for industrial manufacturer contracts. Sollich KG occupies the specialized enrobing and cooling tunnel segment serving European confectionery hubs. Bühler Group represents the integrated systems archetype spanning milling through tempering sequences.
| Leading Market Players |
|---|
| Aasted ApS |
| Sollich KG |
| Bühler Group |
| Hacos NV |
| Selmi |
| GEA Group |
| Royal Duyvis Wiener |
| NETZSCH Group |
| JBT Corporation |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp freight corridor anchors cost dynamics for precision temperature control modules shipped from German engineering clusters to Belgian confectionery manufacturers, compressing margins for mid-scale buyers while amplifying price differentiation between ISO 22000-certified and standard-grade equipment configurations.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with CE-marked and FDA-compliant stainless steel systems commanding substantial premiums over baseline configurations. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and sensor integration density. Price differentiation intensifies as cocoa butter volatility constrains capital budgets among artisanal producers. Mass confectionery manufacturers exhibit highest price sensitivity, while gourmet chocolate houses prioritize precision tolerance over unit cost.
Supply Chain Analysis
Contract manufacturers operating multiple brand lines in Chicago and Philadelphia concentrate downstream demand for quick-changeover cooling tunnel configurations. Precision crystallization sensors and induction heating modules draw from concentrated supplier bases in Germany, Switzerland, and the Netherlands. Single-source vulnerability in temperature control module production exposes brownfield expansion timelines to extended lead times. Distribution runs through OEM-direct channels for industrial accounts and equipment leasing vehicles for artisanal market entry.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of process engineers trained in polymorph-specific tempering protocols constrains operational uptime and creates bottlenecks for precision-dependent installations, forcing stakeholders to compete for scarce technical capability rather than commodity capacity.
For Market Incumbents: Insulate tempering technology leadership through captive training programs for crystallization specialists and accelerated patent filing in energy recovery integration. Aasted ApS and Sollich KG anchor positions that emerging competitors threaten through modular automation retrofits. Backward integration into sensor calibration services locks in aftermarket revenue streams. For New Entrants and Emerging Players: Mid-market automation retrofits for Italian and Spanish confectionery manufacturers represent the most penetrable entry point, as labor cost pressure forces batch-to-continuous transitions without full line replacement. Equipment-as-a-service financing models bypass capital barriers that exclude artisanal producers from precision tempering access. Partnership with third-party technical service providers accelerates crystallization calibration credibility. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food equipment conglomerates with underoptimized chocolate processing divisions lacking dedicated R&D focus. Long-term viability hinges on energy efficiency convergence and digital process control integration. Watch for inflection when tier-two Indian city consumption triggers FSSAI-aligned equipment procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Recovery Technology Integration | Heat exchange systems hybridize thermal efficiency with crystallization precision for EFSA compliance. |
| Sensor-Network Automation Retrofit | Digital process control compresses batch-continuous economics for mid-scale Spanish and Italian manufacturers. |
| Equipment Leasing Channel Development | Project finance vehicles unlock artisanal producer access previously blocked by capital intensity. |
| Crystallization Specialist Training Programs | Captive expertise development addresses the polymorph-protocol engineer shortage constraining uptime. |
| India FSSAI Configuration Pre-Certification | Early alignment with dairy-crossover requirements captures Pune and Ahmedabad consumption growth. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with equipment OEM technical directors, plant engineers at Swiss and Belgian heritage chocolate houses, aftermarket service heads, and procurement leads at US contract manufacturers; alongside secondary validation through CE marking databases, FDA Food Safety Modernization Act guidance documents, FSSAI equipment safety circulars, and customs trade data for cocoa processing machinery. Bottom-up installation base estimates triangulated against top-down capital expenditure projections from food manufacturer SEC filings.
Forecast inputs span equipment category throughput scaling, automation penetration rates across manufacturer size tiers, and regulatory replacement cycle timing across European and North American jurisdictions. Segmentation modeling incorporates product type, application margin structure, technology adoption patterns, and end-user procurement authority fragmentation. CAGRs derive from historical capital deployment patterns projected through equipment lifecycle analysis and brownfield expansion pipeline tracking.
Macroeconomic conditions sit as an overlay; deviation in cocoa butter pricing volatility, European energy cost trajectories, or Indian rupee exchange rates would shift the trajectory. Forecasts reflect documented assumptions regarding EFSA enforcement timelines and FSSAI alignment adoption curves. Quarterly review of commissioning schedule delays and certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food & Beverages
Kiwi Fruit Market
Food & Beverages
Brazil Snack Bar Market
Food & Beverages
Edible Oil Adulteration Testing Chemicals Market
Food & Beverages
Matcha Cookie Market
Food & Beverages
Reconstituted Meat Market
Food & Beverages
Global TCD Alcohol DM Market
Food & Beverages
Middle East and Africa Sweet Biscuits Market
Food & Beverages
Plates Market
Food & Beverages
Probiotics Dietary Supplements Market
Food & Beverages
Vacuum Flask Market
Food & Beverages
Food Extrusion Market
Food & Beverages
Commercial Tandoor Oven Market
Food & Beverages
US Cheese Market
Food & Beverages
Saudi Arabia Bottled Water Market
Food & Beverages
Bottled Water Cooler Market
Food & Beverages
Baby Drinking Water Market