
 CBD-Infused Confectionery Market | 2026-2036
CBD-Infused Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
CBD-Infused Confectionery Market Analysis
American hemp processors is recalibrating extraction capacity toward food-grade CBD isolate to serve confectionery contract manufacturers. Curaleaf Holdings sustains vertical integration from biomass cultivation through finished goods packaging. Green Roads LLC leverages pharmacist-formulated positioning to differentiate in specialty retail channels. Charlotte's Web Holdings anchors premium shelf space through organic certification and controlled distribution.
CBD-infused confectionery denotes edible candy products incorporating cannabidiol extracts at standardized potencies, typically formulated with lipid-based carriers to enhance bioavailability through oral absorption. These products serve commercial purposes spanning stress management supplementation, sleep support, and recreational wellness consumption with precise dosing control. Gummies dominate volume throughput due to manufacturing scalability and flavor masking compatibility with hemp terpenes. Chocolates command premium margin pools through cocoa butter's natural synergy with lipophilic cannabinoids. Hard candies occupy niche positioning for extended-release sublingual absorption formats.
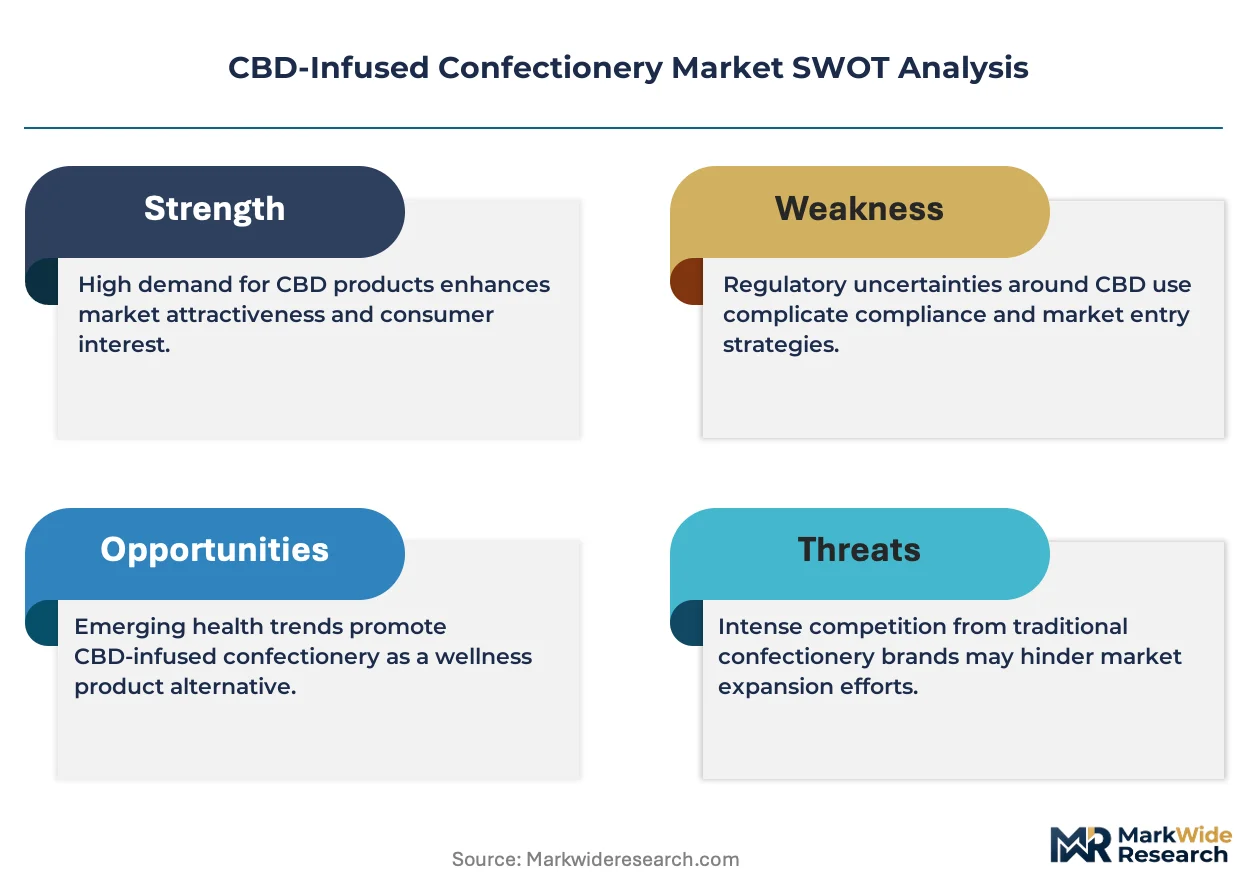
The FDA maintains enforcement discretion while developing a regulatory pathway for CBD in foods, creating compliance uncertainty that shapes formulation investments and interstate shipment protocols. The USDA oversees hemp cultivation licensing through the Farm Bill framework, with state agriculture departments implementing THC testing protocols that determine raw material legality. Stakeholders must monitor evolving state-level health department edibles regulations alongside federal rulemaking to anticipate channel access and product standard requirements.
Market Dynamics
FDA enforcement discretion on CBD food additives forces manufacturers to navigate interstate commerce barriers while awaiting formal rulemaking, compressing formulation investment timelines and reshaping contract manufacturing relationships across state lines.
Growth Catalysts
- Gen Z Wellness Consumption:Younger cohorts prioritize functional gummies for stress management over traditional supplements, creating pull-through demand in California and Colorado dispensary channels.
- Farm Bill Hemp Licensing:USDA oversight of cultivation permits expands compliant biomass supply, reducing raw material seizure risk for food-grade extraction facilities.
- Lipid-Based Nanoemulsion:Advanced carrier technologies improve cannabinoid bioavailability, enabling precise dosing claims that differentiate premium chocolate formulations.
Market Restraints
- THC Testing Protocol Variability:State agriculture departments apply divergent hemp potency thresholds, creating raw material quarantine risk at processing facilities.
- Specialty Cocoa Butter Concentration:Premium chocolate production depends on West African supply clusters vulnerable to climate-induced harvest volatility.
- FD&C Act Section 301(ll):The statutory prohibition on interstate shipment of CBD-added foods creates distribution fragmentation that elevates compliance costs.
Strategic Opportunities
- New York State Retail Infrastructure:Licensed dispensary expansion in Brooklyn and Manhattan creates shelf space for pharmacist-positioned gummy brands.
- Sleep Support Positioning:Melatonin-CBD combination formats target shift workers in healthcare and logistics sectors with documented circadian disruption.
- Organic Certification Premium:USDA Organic seal commands price separation in specialty retail, rewarding controlled distribution investments.
Industry Challenges
- Food Safety Modernization Act Compliance:Preventive controls qualified individual requirements strain mid-tier manufacturers lacking in-house regulatory expertise.
- Co-Manufacturer Qualification Timelines:Third-party facility audits for CBD handling extend new product development cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD-Infused Confectionery Market |
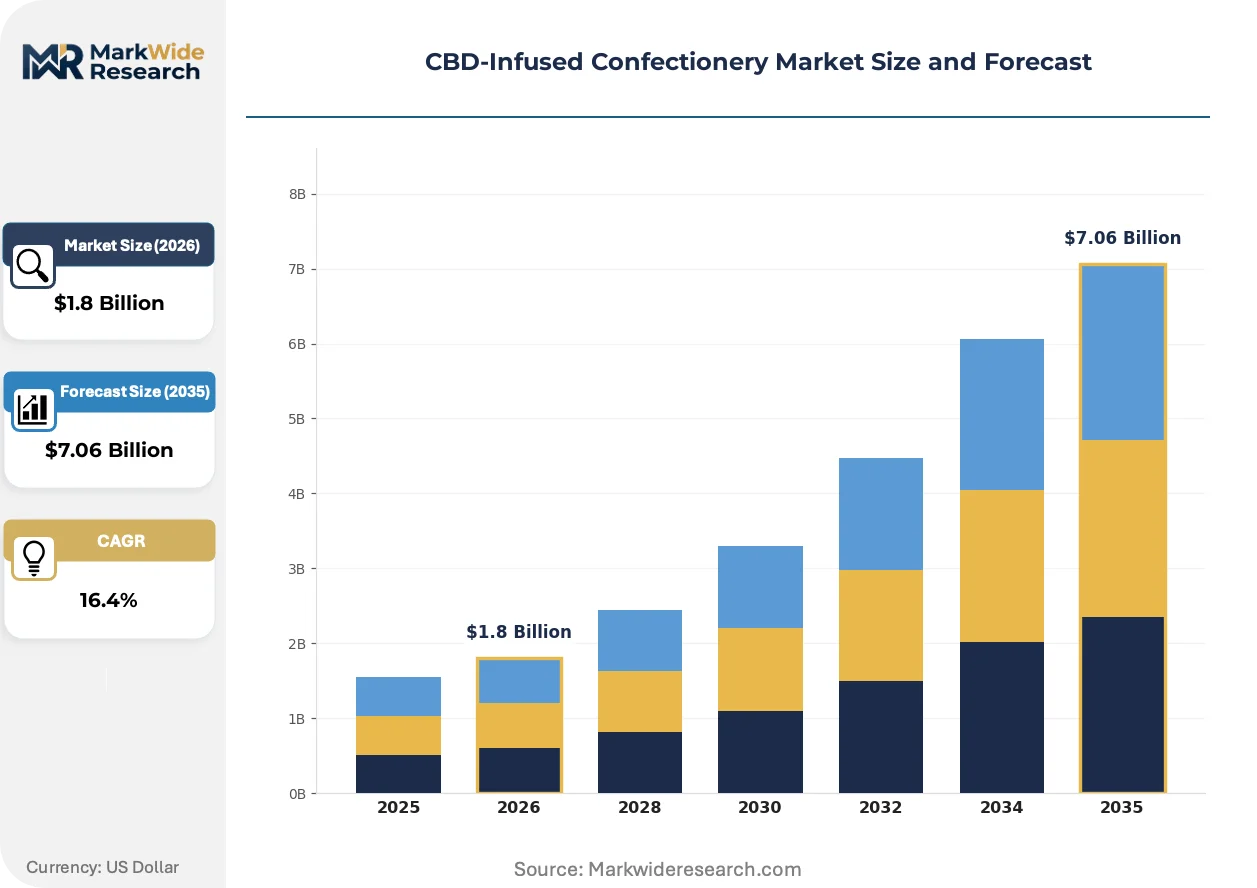
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummies, Chocolates, Hard Candies, Lollipops Ingredient Source: Hemp-Derived, Cannabis-Derived, Isolate, Broad Spectrum Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wellness Shops Target Audience: Health-Conscious Consumers, Recreational Users, Athletes, Seniors |
| Companies Covered | Green Roads LLC, Medterra CBD LLC, Curaleaf Holdings, Inc., CBDistillery, Joy Organics, Tilray Brands, Inc., Lazarus Naturals Inc., Ace Valley, Charlotte's Web Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD-Infused Confectionery Market Emerging Trajectories
Formulation science and distribution architecture are undergoing parallel transformation as manufacturers respond to bioavailability demands and channel access constraints. Three developments are compressing competitive timelines.
Nanoemulsion technology is converging with lipid carrier systems to enhance oral absorption rates for hydrophobic cannabinoids. California contract manufacturers are adopting microfluidic processing equipment at scale. This convergence is compressing the efficacy gap between sublingual tinctures and ingestible confectionery formats.
FDA's ongoing CBD product rulemaking is reshaping interstate shipment protocols while maintaining enforcement discretion. The regulatory uncertainty forces manufacturers to maintain dual formulation inventories for intrastate versus interstate distribution. California and Colorado health departments are advancing their own edibles frameworks ahead of federal clarity.
Specialty retail buyers are consolidating supplier relationships around vertically integrated producers with captive extraction capabilities. Dispensary channel managers in Denver and Los Angeles now require batch-level certificate of analysis documentation. This consolidation is most visible in premium chocolate segments where provenance claims drive repeat purchase.
CBD-Infused Confectionery Market Segmentation
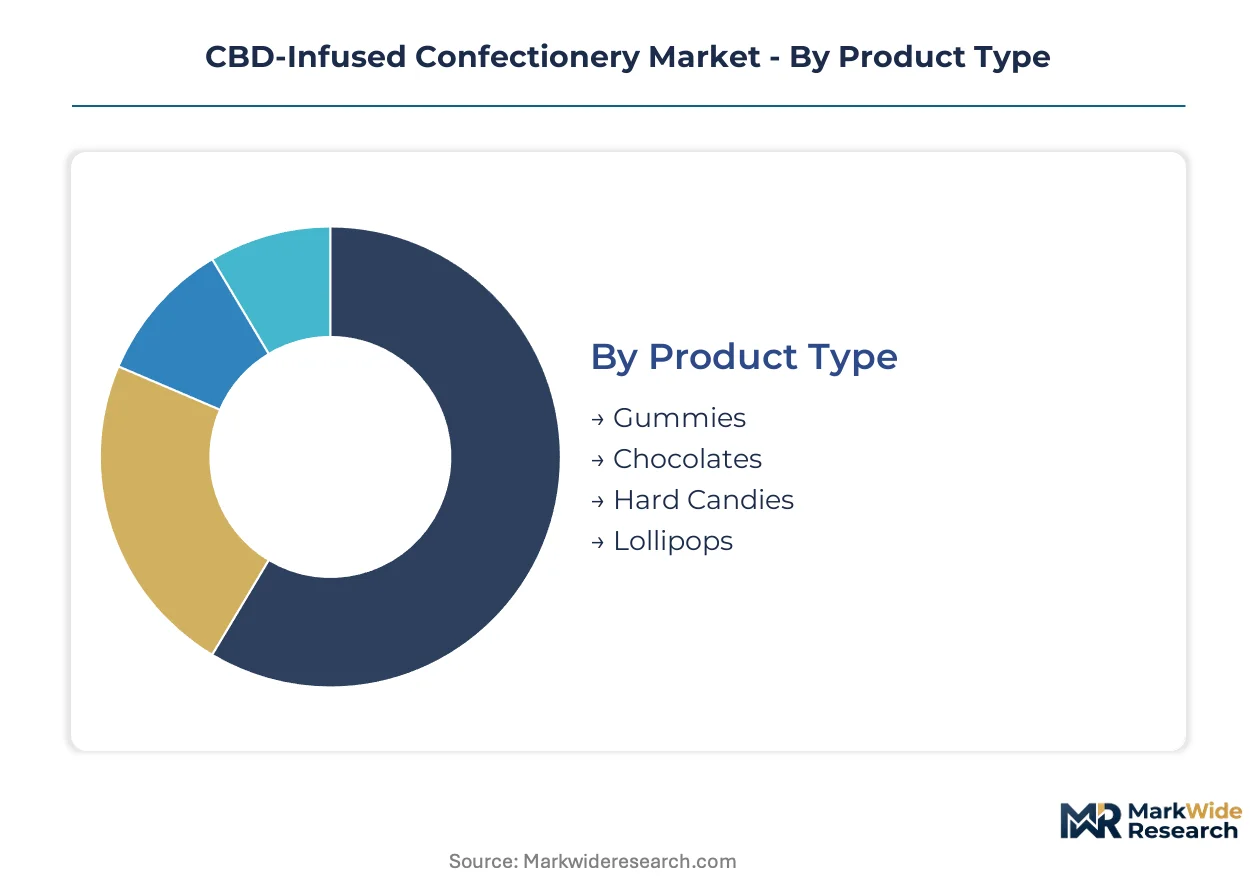
Segmentation in CBD confectionery reflects divergent bioavailability requirements, regulatory exposure levels, and channel access constraints. Manufacturers align formulation investments with specific audience tolerance thresholds and distribution compliance burdens.
Product Type:
Standalone formats dominate shelf space with discrete dosing and familiar consumption rituals, while embedded applications in functional foods remain nascent pending FDA clarity.
- Gummies:Gelatin or pectin matrices suspend lipid-based CBD nanoemulsions, enabling precise milligram standardization per unit. California and Colorado dispensary channels absorb the highest throughput volumes as Gen Z wellness seekers prioritize portability and flavor masking.
- Chocolates:Cocoa butter's lipophilic properties create natural synergy with cannabinoid carriers, supporting enhanced oral absorption without synthetic additives. Premium positioning in New York specialty retail rewards organic certification and provenance documentation.
- Hard Candies:Extended-dissolution formats enable sublingual absorption pathways, reducing first-pass metabolism losses. Niche positioning targets sleep support applications with melatonin combinations.
- Lollipops:Single-serve novelty formats concentrate in recreational wellness channels with lower repeat purchase frequency.
Gummies lead volumes today; chocolates are gaining share fastest through premium shelf space consolidation.
Ingredient Source:
Cost tier stratification separates commodity isolates from full-spectrum extracts, with compliance risk varying by THC threshold proximity.
- Hemp-Derived:Farm Bill-compliant biomass with THC below 0.3% dry weight enables interstate shipment under USDA licensing frameworks. Supply concentrates in Kentucky and Oregon processing clusters.
- Cannabis-Derived:State-regulated dispensary channels require intrastate cultivation and extraction, limiting scale but permitting higher cannabinoid diversity. California and Colorado operators dominate this tier.
- Isolate:Crystalline CBD at 99%+ purity minimizes regulatory risk for food-grade applications. Standardized potency supports pharmaceutical positioning in wellness shops.
- Broad Spectrum:THC-free formulations retain minor cannabinoids and terpenes for entourage effect claims without Schedule I exposure. Premium pricing reflects extraction complexity.
Isolate leads volumes today; broad spectrum is climbing the fastest as entourage effect marketing penetrates specialty retail.
Distribution Channel:
Customer type alignment determines margin structure, with subscription models in direct-to-consumer contrasting single-serve impulse purchases in mass retail.
- Online Retail:Direct-to-consumer platforms bypass interstate shipment restrictions through intrastate fulfillment networks. Subscription models capture recurring revenue in sleep support segments.
- Supermarkets:Mass retail placement awaits FDA rulemaking resolution, with current presence limited to hemp seed oil products without CBD claims.
- Specialty Stores:Dispensary and wellness shop channels require batch-level certificate of analysis documentation. Denver and Los Angeles buyers consolidate around vertically integrated suppliers.
- Wellness Shops:Pharmacist-positioned formats command price separation through clinical dosing protocols and melatonin combinations.
Specialty stores lead volumes today; online retail is expanding most quickly through subscription model adoption.
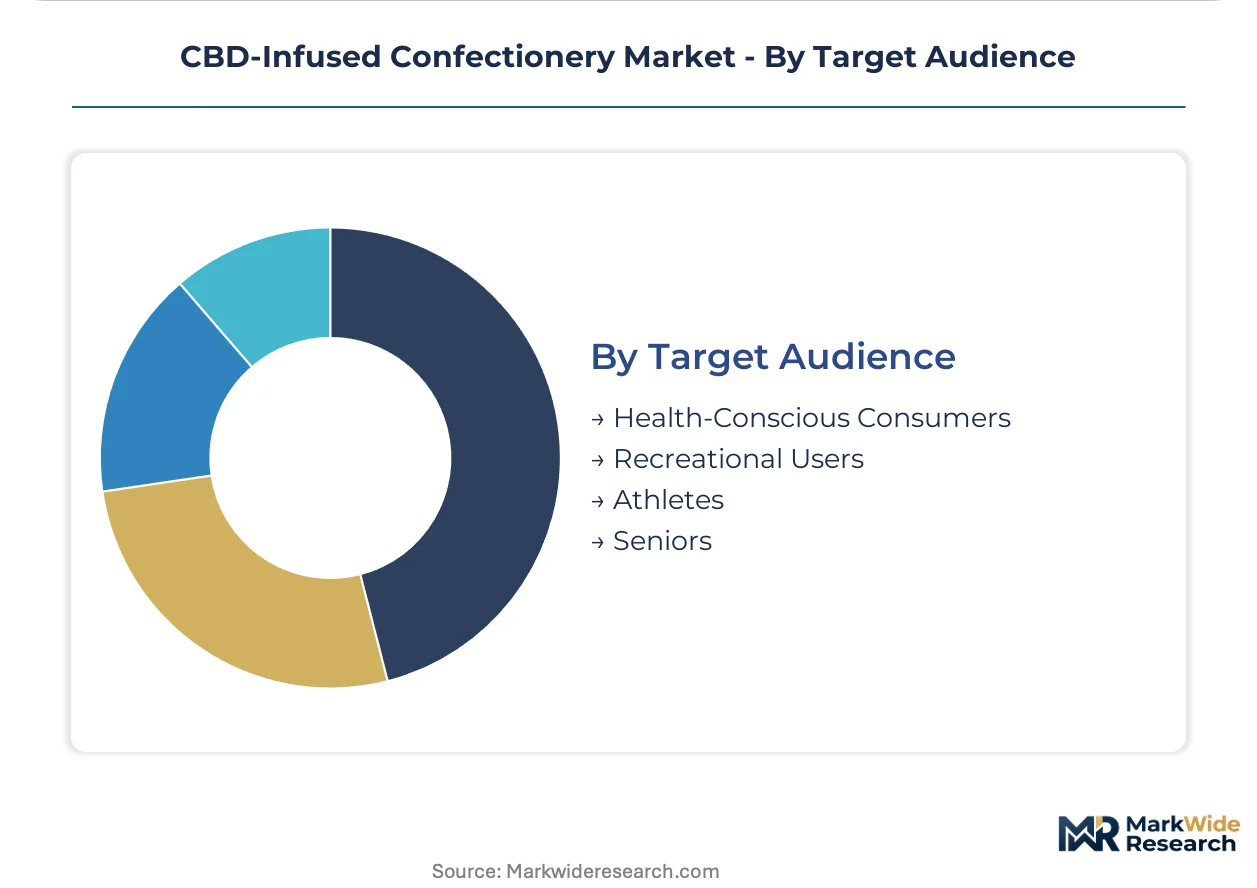
Target Audience:
Application focus separates therapeutic positioning from recreational consumption, with dosage precision and onset timing as key differentiators.
- Health-Conscious Consumers:Functional supplementation replaces traditional stress management products. Organic certification and clean label claims drive purchase decisions in California specialty channels.
- Recreational Users:Social consumption occasions prioritize flavor experience and discrete portability. Colorado dispensary channels serve this segment with higher potency tolerance.
- Athletes:Recovery and inflammation support applications require NSF Certified for Sport or Informed Sport verification. Limited SKU availability constrains penetration.
- Seniors:Joint comfort and sleep quality positioning targets Medicare-eligible demographics with lower THC sensitivity. Brooklyn and Manhattan wellness shops report strongest uptake.
Health-conscious consumers lead volumes today; seniors are gaining share fastest through pharmacist-channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains the deepest confectionery infrastructure, while Canada pursues federal clarity through Health Canada frameworks that diverge from American enforcement discretion models.
United States
California and Colorado dispensary channels absorb the highest gummy volumes as Gen Z consumers prioritize functional stress management formats. The FDA's ongoing CBD food additive rulemaking maintains interstate shipment barriers under FD&C Act Section 301(ll). Denver and Los Angeles buyers now require batch-level certificate of analysis documentation from vertically integrated suppliers.
Canada
Licensed producers pivot toward edibles manufacturing as dried flower margins compress in Ontario and British Columbia retail channels. Health Canada's Cannabis Act regulations provide federal clarity absent in American markets, enabling standardized national distribution. Toronto and Vancouver processing clusters concentrate nanoemulsion technology investments for enhanced bioavailability claims.
Germany
Pharmacy-channel CBD positioning gains traction as consumers seek pharmacist-verified dosing protocols for sleep support applications. The BfArM (Federal Institute for Drugs and Medical Devices) oversees cannabis scheduling under the Narcotics Act, with recent reforms expanding medical access. Berlin and Hamburg wellness retail clusters import broad-spectrum formulations from Dutch extraction facilities.
United Kingdom
Novel Foods authorization requirements under the FSA (Food Standards Agency) create compliance bottlenecks for ingestible CBD products entering English and Scottish markets. The UK maintains stricter THC thresholds than EU counterparts, quarantining non-compliant shipments at Dover and Felixstowe ports. London specialty retailers emphasize isolate-based chocolates to minimize regulatory exposure.
Switzerland
Swissmedic's relatively permissive CBD framework permits up to 1% THC in hemp-derived products, attracting formulation R&D from neighboring jurisdictions. Geneva and Zurich processing facilities serve as European nanoemulsion technology hubs. Baseland chocolate manufacturers leverage this regulatory flexibility for premium export positioning.
CBD-Infused Confectionery Market Vendor Landscape
American producers anchor the scale-driven tier; Canadian and European specialists hold pharmacy-channel positioning. The vendor base stratifies across vertically integrated cultivators, contract manufacturing platforms, and pharmacist-formulated brands. Three archetypes dominate: captive extraction operators controlling biomass-to-shelf supply chains; nanoemulsion technology licensors enabling bioavailability differentiation; and wellness-retail positioning specialists emphasizing organic certification. Capacity expansion and strategic co-manufacturer qualification represent the dominant competitive moves as FDA rulemaking timelines compress investment windows.
Within the vertically integrated tier, Curaleaf Holdings exemplifies captive supply chain architecture spanning biomass cultivation through finished goods packaging. Charlotte's Web Holdings anchors premium shelf positioning through controlled distribution investments and organic certification. Green Roads LLC occupies the pharmacist-formulated archetype, differentiating through clinical dosing protocols in specialty retail channels.
| Leading Market Players |
|---|
| Green Roads LLC |
| Medterra CBD LLC |
| Curaleaf Holdings, Inc. |
| CBDistillery |
| Joy Organics |
| Tilray Brands, Inc. |
| Lazarus Naturals Inc. |
| Ace Valley |
| Charlotte's Web Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Gen Z wellness seekers' preference for pharmacist-verified dosing protocols is forcing contract manufacturers to qualify dual-source CBD isolate suppliers, compressing margin pools as batch-level certificate of analysis documentation becomes table stakes for California and Colorado dispensary access.
Pricing Analysis
Dispensary channel markups absorb the highest margin layers, with vertically integrated operators capturing 40-50 point spreads over contract manufacturing platforms. Three-tier pricing structure across premium organic-certified, standard broad-spectrum, and economy isolate tiers separates Charlotte's Web Holdings from mid-tier gummy suppliers. Cost compression in economy isolate tiers is intensifying because Kentucky and Oregon hemp processors are expanding food-grade extraction capacity simultaneously. Price sensitivity concentrates in recreational wellness channels, while sleep support positioning in Brooklyn and Manhattan wellness shops tolerates 30% premiums for melatonin combinations.
Supply Chain Analysis
Dual-sourcing requirements from Denver and Los Angeles dispensary buyers mandate multi-supplier qualification for both CBD isolate and specialty cocoa butter inputs. Hemp biomass concentrates in Kentucky, Oregon, and Colorado cultivation clusters under USDA Farm Bill licensing. Cocoa butter draws from West African supply nodes vulnerable to climate-induced harvest volatility. Single-source vulnerability in premium chocolate inputs elevates quarantine risk at processing facilities. Distribution runs through vertically integrated captive networks for dispensary channels, with third-party logistics handling intrastate direct-to-consumer fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder. FDA rulemaking timelines create predictable investment windows while Gen Z wellness consumption sustains demand visibility.
For Market Incumbents: To counter FDA enforcement discretion on interstate shipment protocols, Curaleaf Holdings and Charlotte's Web Holdings should deepen backward integration into hemp cultivation to secure biomass-to-shelf supply chain control. Certification investment in USDA Organic and NSF Certified for Sport creates defendable shelf positioning as specialty retail buyers consolidate supplier relationships. For New Entrants and Emerging Players: Enter via sleep support gummy formats targeting shift workers in healthcare and logistics sectors, where documented circadian disruption sustains premium pricing tolerance. Brooklyn and Manhattan wellness shops represent the most penetrable channel geography, with pharmacist-formulated positioning as the viable go-to-market angle against entrenched dispensary incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with nanoemulsion technology licensors enabling bioavailability differentiation for chocolate and hard candy formats. The 5-10 year viability window rewards acquisition of broad-spectrum extraction specialists with captive terpene retention capabilities. Watch FDA publication of formal CBD food additive rulemaking as the definitive inflection signal for interstate commerce normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Nanoemulsion Technology Licensing | Microfluidic processing equipment adoption in California contract manufacturing facilities enhances oral absorption claims for premium chocolates. |
| Organic Certification Investment | USDA Organic seal acquisition rewards controlled distribution investments in New York specialty retail channels. |
| Pharmacist-Formulated Positioning | Clinical dosing protocols differentiate Green Roads LLC archetypes in wellness shops against recreational dispensary competitors. |
| Backward Integration into Cultivation | Captive hemp biomass supply reduces raw material quarantine risk from divergent state THC testing protocols. |
| Melatonin Combination Formats | Sleep support SKUs target shift worker demographics with documented circadian disruption in healthcare and logistics sectors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extraction facility operators, dispensary channel managers, contract manufacturing quality directors, and specialty retail category buyers with secondary validation against USDA hemp cultivation licensing data, FDA enforcement discretion documentation, state health department edibles frameworks, and batch-level certificate of analysis databases. Bottom-up volume modeling triangulated against top-down addressable wellness expenditure estimates.
Historical reference periods anchored the forecast window to pre-2018 Farm Bill baseline conditions through current enforcement discretion regime dynamics across the analysis window. Segmentation dimensions modeled include product type, ingredient source, distribution channel, and target audience, with bioavailability technology tier as an industry-specific overlay. CAGRs derived from fitted growth curves incorporating Gen Z demographic penetration rates and FDA rulemaking probability-weighted scenarios. Hemp biomass supply elasticity and cocoa butter price volatility served as key forecast inputs.
Inputs from extraction facility operators and dispensary buyers were available through the study window; gaps in FDA formal rulemaking timelines introduce uncertainty bands around interstate commerce normalization assumptions. Deviation in FDA publication schedule or state-level THC testing protocol harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Chocolate Market
Confectionery
United States and Europe Macarons Market
Confectionery
Brazil Chocolate Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Caramel Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Chocolate Flavors Market
Confectionery
UK Confectionery Market
Confectionery
UK Chocolate Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
South Africa Confectionery Market
Confectionery
Brain Mint Market
Confectionery
Edible Glitter Market