
 United Kingdom Spinal Surgery Devices Market | 2026-2036
United Kingdom Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Spinal Surgery Devices Market Analytics
England's National Health Service infrastructure expansion is rewriting procurement dynamics for spinal surgery devices across the United Kingdom. Medtronic leverages its broad implant portfolio to sustain presence in NHS supply frameworks. Stryker anchors its position through specialized navigation and imaging technologies for complex spinal procedures. Johnson & Johnson (DePuy Synthes) competes across multiple product categories with integrated instrument and implant systems.
United Kingdom spinal surgery devices encompass implants, instruments, biomaterials, and robotic systems designed for the correction, stabilization, and fusion of spinal pathologies, typically manufactured from titanium alloys, polyetheretherketone, or bone graft substitutes to achieve mechanical fixation and biological integration. These devices serve orthopedic and neurosurgical teams performing decompression, fusion, and deformity correction procedures in hospital operating theaters and specialized surgical centers. Implants and instruments capture the largest share of current revenue as mature categories with established reimbursement pathways, while surgical robots represent the fastest-expanding segment as capital-constrained trusts gradually adopt capital equipment through managed service agreements. Minimally invasive technology commands premium positioning against open surgery alternatives, reflecting its association with reduced length of stay and accelerated recovery protocols.
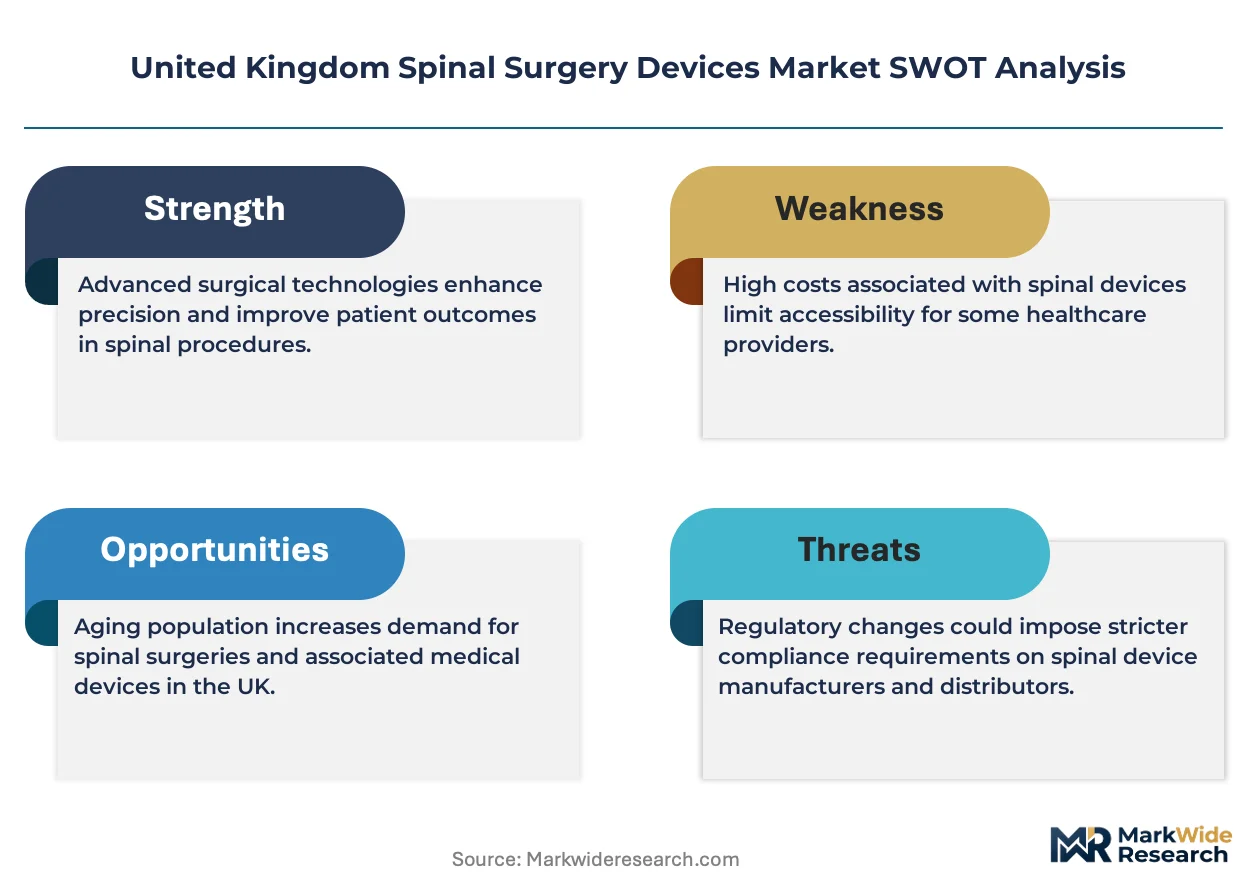
The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance and device registration requirements that elevate compliance costs for market participants, while NHS England's procurement frameworks and NICE technology appraisals shape which innovations achieve routine commissioning. BSI Group operates as a designated UK Approved Body under the retained EU Medical Devices Regulation, conducting conformity assessments that determine market access for implantable spinal devices. Stakeholders must monitor evolving NHS long-term plan priorities and integrated care system budget allocations to anticipate which surgical technologies will secure prioritized investment.
Market Dynamics
The Medicines and Healthcare products Regulatory Agency's retained EU Medical Devices Regulation implementation is compressing market access timelines and forcing manufacturers to restructure conformity assessment pathways ahead of UKCA marking deadlines.
Growth Catalysts
- Aging surgical demand:England's over-65 population requiring lumbar fusion and cervical decompression procedures is expanding NHS waiting list volumes for spinal interventions.
- Minimally invasive technique diffusion:Percutaneous pedicle screw systems and lateral interbody fusion approaches are reducing length-of-stay metrics that Integrated Care Systems track for reimbursement efficiency.
- NICE technology appraisals:Favorable guidance for motion-preserving disc replacements is opening routine commissioning pathways previously restricted to fusion hardware.
Market Restraints
- Titanium alloy input volatility:Aerospace and medical grade titanium supply concentration in Chinese and Russian smelting operations creates price instability for implant manufacturers.
- Single-source robotic dependency:Capital equipment procurement for navigation-assisted surgery concentrates among two dominant suppliers, limiting NHS trust negotiating leverage.
- Biologics substitution pressure:Bone morphogenetic protein alternatives and synthetic graft materials are displacing traditional interbody cages in specific fusion indications.
Strategic Opportunities
- Managed service agreements:Robotic system deployment through per-procedure leasing rather than capital purchase is unlocking adoption among cash-constrained NHS foundation trusts.
- Scotland and Wales expansion:Devolved health authority procurement frameworks in Edinburgh and Cardiff present underpenetrated channels relative to saturated English metropolitan trusts.
- Day-case spinal surgery:Ambulatory surgical center licensing reforms are enabling outpatient lumbar decompression procedures outside traditional hospital settings.
Industry Challenges
- Specialized surgical workforce gaps:Fellowship-trained spine surgeons capable of complex deformity correction remain concentrated in London, Manchester, and Birmingham teaching hospitals.
- UKCA transition timelines:BSI Group conformity assessment backlog is delaying market authorization for modified implant designs, compressing product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Spinal Surgery Devices Market |
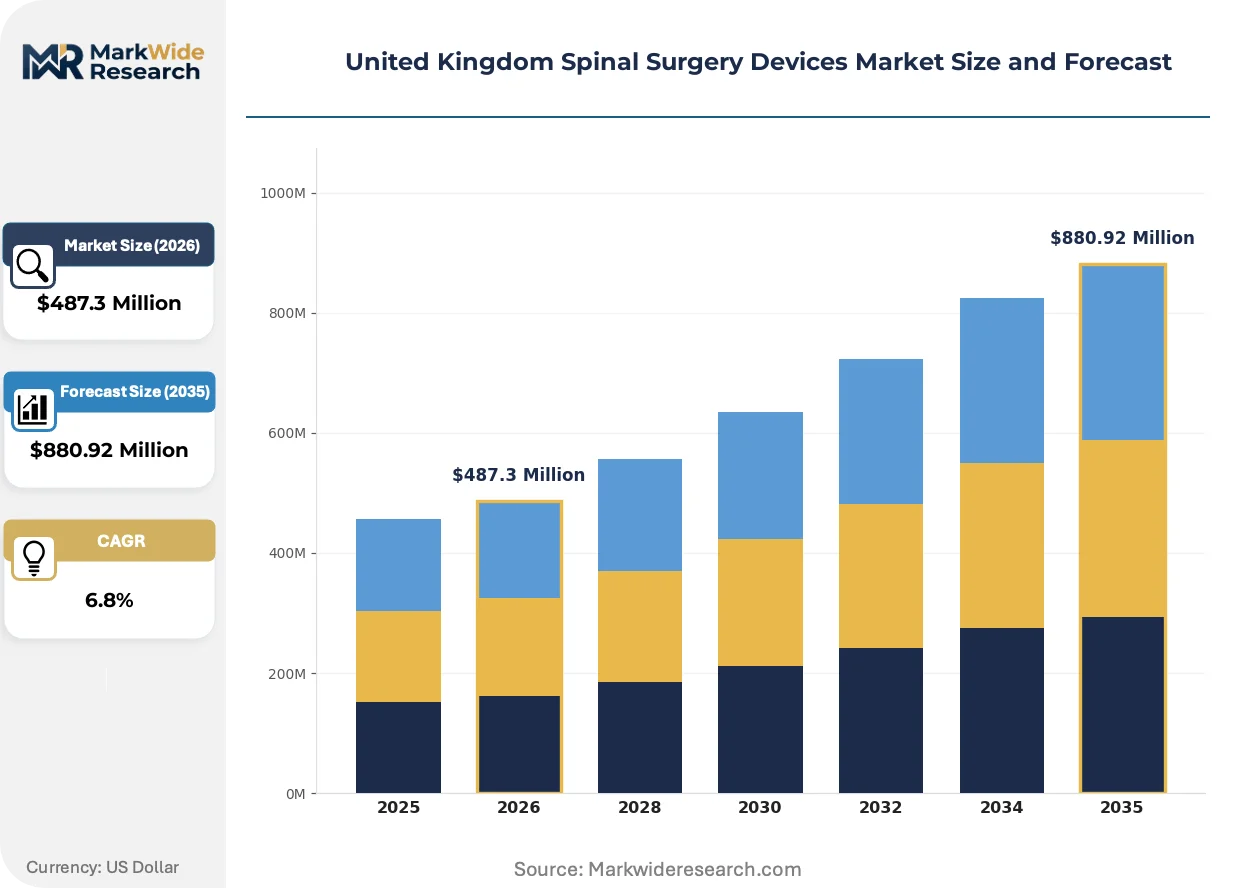
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implants, Instruments, Biomaterials, Surgical Robots End User: Hospitals, Ambulatory Surgical Centers, Clinics, Rehabilitation Centers Technology: Minimally Invasive, Open Surgery, Image-Guided, Navigation Systems Application: Degenerative Disc Disease, Spinal Stenosis, Fractures, Deformities |
| Companies Covered | Medtronic, Stryker, Johnson & Johnson (DePuy Synthes), Globus Medical Inc., Vadin Implants Ltd, Zimmer Biomet, NuVasive Inc., Orthofix Holdings Inc., B. Braun Melsungen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Spinal Surgery Devices Market Evolving Landscape
Navigation and imaging integration is collapsing the technical barrier between open and minimally invasive approaches, while procurement restructuring favors capital-light access models over traditional ownership.
Patient-specific 3D-printed titanium interbody cages with optimized porous architectures are collapsing the historical trade-off between mechanical strength and osseointegration speed. Complex spinal deformity centers in London and Manchester are adopting these implants for revision fusion cases where standard geometries failed. The technology is collapsing the addressable market for off-the-shelf premium cages by demonstrating superior radiographic fusion rates at equivalent reimbursement levels.
The retained EU Medical Devices Regulation's post-market surveillance requirements are mandating annual safety update reports and implantable device registries for all spinal fusion hardware. BSI Group-designated UK Approved Bodies are enforcing stricter clinical evidence standards for legacy products seeking UKCA recertification. High-volume pedicle screw systems with decades of clinical history face the greatest compliance burden, accelerating portfolio rationalization among manufacturers with thin regulatory affairs teams.
Integrated Care Systems are consolidating spinal surgery procurement across multiple hospital trusts into regional framework agreements with volume-tiered pricing. Single-source vendor relationships are displacing fragmented supplier contracts that previously allowed individual surgeons to specify preferred implant systems. This concentration is most visible in the Greater Manchester and West Midlands ICS footprints, where procurement teams now mandate cross-trust standardization for routine lumbar fusion instrumentation.
United Kingdom Spinal Surgery Devices Market Segmentation
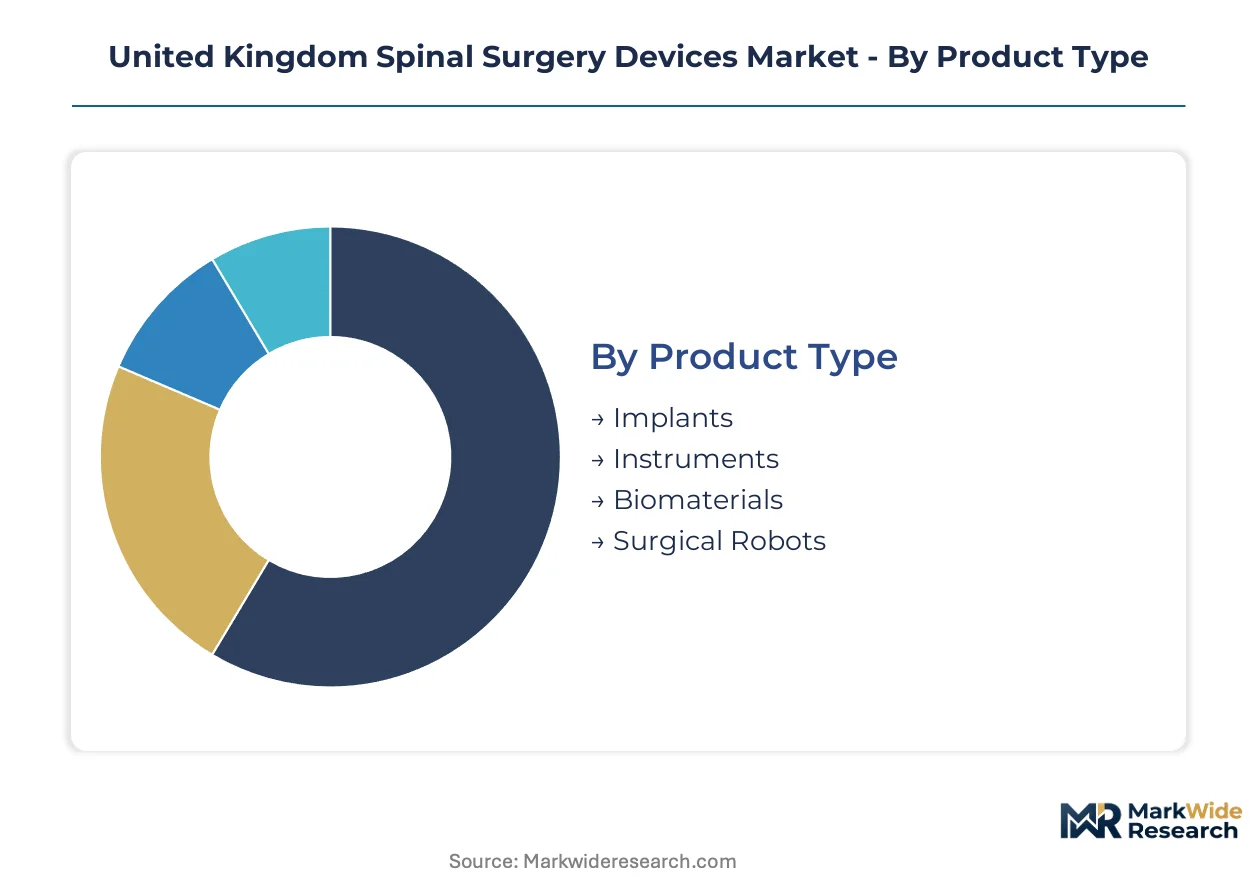
Segmentation in the United Kingdom spinal surgery devices market reveals distinct procurement patterns across NHS trusts and private providers. Product maturity, reimbursement pathways, and capital availability determine adoption velocity within each category.
Product Type:
Mature implant categories dominate current NHS expenditure, while emerging robotic platforms reshape capital procurement strategies across Integrated Care Systems.
- Implants:Titanium alloy pedicle screws, interbody cages, and cervical plates constitute the procedural backbone of lumbar and cervical fusion surgeries. Demand concentrates in England's major metropolitan hospital trusts, particularly London and Manchester surgical centers, where high-volume spine units drive standardized procurement frameworks.
- Instruments:Specialized retractors, drills, and insertion tools manufactured from surgical-grade stainless steel and aluminum alloys support open and minimally invasive approaches. England's National Health Service infrastructure expansion is rewriting procurement dynamics, with regional framework agreements consolidating supplier relationships across multiple trusts.
- Biomaterials:Bone graft substitutes, demineralized bone matrices, and synthetic osteoconductive materials augment fusion biology.
- Surgical Robots:Navigation-assisted platforms enable percutaneous screw placement and deformity correction with sub-millimeter accuracy.
Implants retain volume leadership; surgical robots hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive hospital installations from lean ambulatory settings pursuing outpatient migration.
- Hospitals:NHS foundation trusts and private hospital groups maintain comprehensive operating theater infrastructure for complex deformity correction and revision fusion procedures. London, Manchester, and Birmingham teaching hospitals concentrate fellowship-trained spine surgeons capable of advanced interventions.
- Ambulatory Surgical Centers:Licensed day-case facilities are expanding lumbar decompression capacity outside traditional hospital settings following regulatory reforms. Scotland and Wales present underpenetrated channels relative to saturated English metropolitan trusts.
- Clinics:Outpatient diagnostic and minor interventional sites support preoperative assessment and postoperative monitoring.
- Rehabilitation Centers:Post-acute facilities manage recovery protocols following instrumented fusion surgeries.
Hospitals command the capital equipment investment pipeline; ambulatory surgical centers are climbing the fastest as licensing reforms enable outpatient migration.
Technology:
Application context determines technology selection, with deformity complexity and patient comorbidity driving open versus minimally invasive trade-offs.
- Minimally Invasive:Percutaneous pedicle screw systems and lateral interbody fusion approaches reduce length-of-stay metrics that Integrated Care Systems track for reimbursement efficiency. Favorable NICE technology appraisals for motion-preserving alternatives are opening routine commissioning pathways.
- Open Surgery:Traditional posterior approaches remain necessary for severe deformity correction and multilevel revision fusions requiring direct visualization. Specialized surgical workforce gaps concentrate this demand in London, Manchester, and Birmingham teaching hospitals.
- Image-Guided:Intraoperative fluoroscopy and cone-beam CT enable real-time implant positioning verification.
- Navigation Systems:Optical and electromagnetic tracking platforms integrate with preoperative imaging for trajectory planning.
Open surgery maintains procedural volume dominance; minimally invasive techniques are gaining share fastest through length-of-stay optimization incentives.
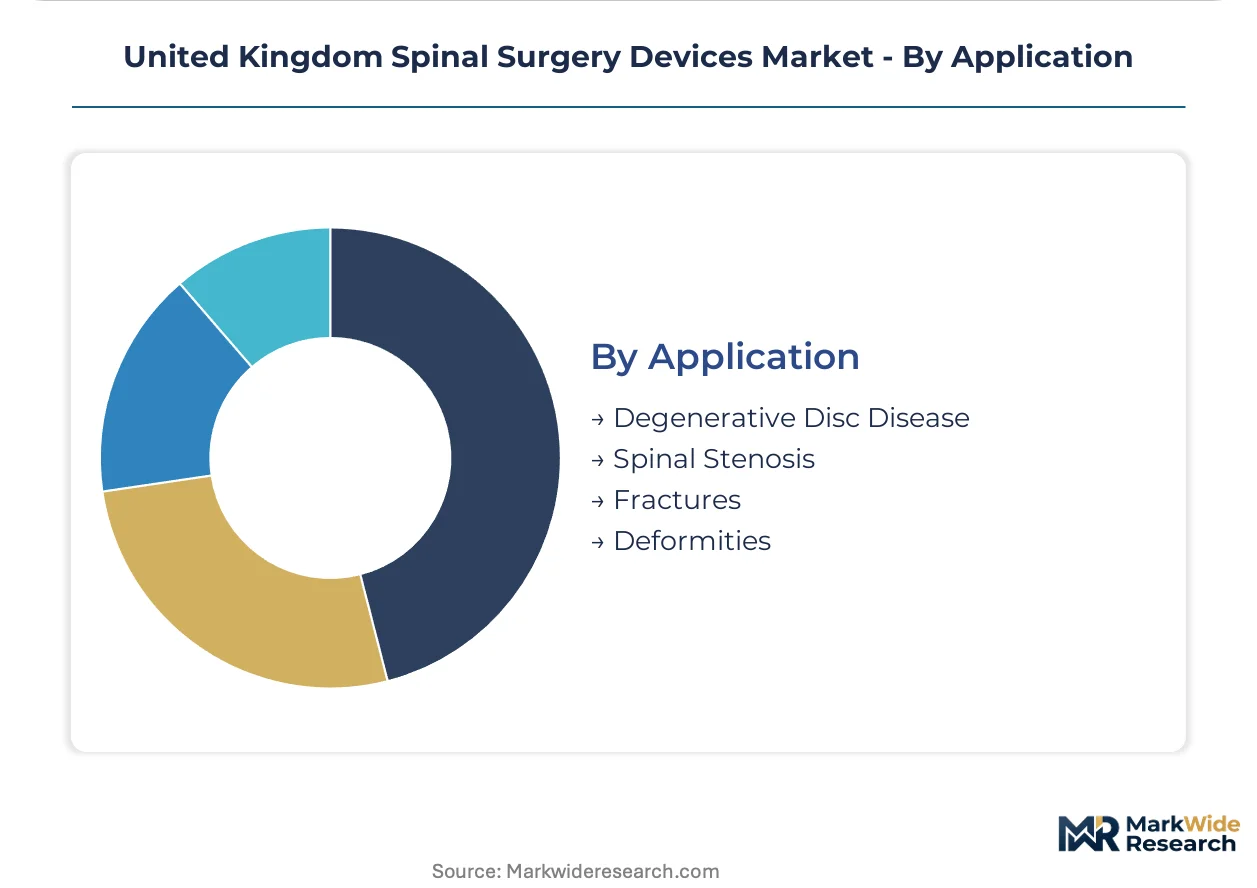
Application:
Volume distribution aligns with aging demographics and trauma incidence across England's regional health economies.
- Degenerative Disc Disease:Lumbar and cervical disc pathology drives the majority of elective fusion and disc replacement procedures. England's over-65 population requiring lumbar fusion is expanding NHS waiting list volumes for spinal interventions.
- Spinal Stenosis:Central and foraminal narrowing necessitates decompression with or without instrumented fusion depending on instability presence. Demand concentrates in major metropolitan hospital trusts with dedicated spine units.
- Fractures:Traumatic vertebral body compression and burst injuries require stabilization through percutaneous or open techniques.
- Deformities:Scoliosis, kyphosis, and spondylolisthesis correction represent the most technically demanding surgical category.
Degenerative disc disease retains volume leadership; deformity correction holds the steepest expansion curve as specialized centers expand referral networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Medicines and Healthcare products Regulatory Agency governs device registration across the United Kingdom, with NHS England procurement frameworks determining which innovations achieve routine commissioning in hospital trusts.
England
London and Manchester surgical centers concentrate high-volume spine units performing complex deformity correction. NHS England's Integrated Care Systems consolidate procurement across multiple trusts into regional framework agreements. Greater Manchester and West Midlands ICS footprints now mandate cross-trust standardization for routine lumbar fusion instrumentation.
Scotland
Edinburgh's devolved health authority procurement frameworks present underpenetrated channels relative to saturated English metropolitan trusts. NHS Scotland's technology appraisal processes operate independently from NICE guidance. Glasgow and Aberdeen teaching hospitals are expanding minimally invasive capacity through managed equipment service agreements.
Wales
Cardiff-based health boards are catching up to English adoption curves for navigation-assisted surgery. The Welsh Government's medical technology investment program targets backlog reduction in orthopedic waiting lists. Swansea and Newport surgical units are licensing ambulatory capacity for day-case spinal procedures.
Northern Ireland
Belfast's regional health economy maintains concentrated spine surgery capacity at Royal Victoria Hospital. The Department of Health's elective care transformation program prioritizes spinal intervention throughput. Derry and Newry secondary centers refer complex cases to the capital's specialized surgical workforce.
United Kingdom Spinal Surgery Devices Market Competitive Landscape
Full-line implant manufacturers and specialized navigation technology providers split the market into complementary competitive domains. The vendor base organizes around scale-driven portfolio breadth versus focused surgical system specialization. Three archetypes dominate: diversified orthopedic conglomerates with spine divisions, pure-play spinal technology specialists, and regional distribution-focused service providers. M&A activity concentrates on robotics and navigation capabilities, while managed service agreements reshape capital equipment access models.
Among diversified orthopedic conglomerates, Medtronic and Stryker exemplify the full-line archetype through broad implant portfolios and integrated surgical platforms. Johnson & Johnson's DePuy Synthes unit occupies a comparable position spanning multiple product categories. These three entities sit within the premium-tier procurement frameworks that NHS trusts utilize for high-volume fusion procedures, representing the consolidated end of a market that also accommodates specialized competitors in navigation and biologics segments.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Johnson & Johnson (DePuy Synthes) |
| Globus Medical Inc. |
| Vadin Implants Ltd |
| Zimmer Biomet |
| NuVasive Inc. |
| Orthofix Holdings Inc. |
| B. Braun Melsungen AG |
| Others |
Value Network & Pricing Analysis
Chinese and Russian titanium alloy smelting operations concentrate aerospace and medical-grade feedstock supply, anchoring implant manufacturing costs and compressing margin pools at the NHS procurement tier where volume-tiered framework agreements dominate.
Pricing Analysis
Geographic price spreads between London metropolitan trusts and Welsh health boards reflect differential procurement scale and ICS consolidation maturity. Three-tier pricing structure across premium navigation-integrated systems, standard pedicle screw constructs, and economy interbody cages stratifies by brand recognition and after-sales service bundling. Cost compression in the economy tier intensifies as biologics substitution accelerates, with ambulatory surgical centers exhibiting highest price sensitivity and specialized deformity centers showing lowest.
Supply Chain Analysis
Tariff exposure between UK-EU post-Brexit trade arrangements and China-dominated rare earth processing dominates supply chain risk assessment for spinal implant manufacturers. Raw material sourcing draws from Chinese titanium sponge, German precision machining components, and US-sourced polyetheretherketone resin. Single-source vulnerability concentrates in robotic navigation platform suppliers. Distribution runs through NHS Supply Chain centralized procurement with regional framework agreements to individual trust stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through UKCA marking requirements and BSI Group conformity assessment backlogs create substantial switching costs for hospital trusts.
For Market Incumbents: Harden regulatory affairs capabilities to accelerate UKCA recertification timelines and compress product refresh cycles. Deepen backward integration into titanium alloy processing to offset Chinese smelting price volatility. Secure exclusive managed service agreements for robotic platforms before capital-constrained trusts consolidate supplier relationships.
For New Entrants and Emerging Players: Scotland and Wales devolved health authority frameworks present underpenetrated procurement channels with less consolidated supplier relationships than English metropolitan trusts. Target day-case spinal surgery licensing expansions in Swansea and Newport where ambulatory capacity gaps outpace incumbent coverage. Pursue per-procedure leasing models to bypass capital purchase barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward navigation and robotics specialists with existing CE marking pathways that accelerate UKCA transition timelines. Long-term viability hinges on portfolio breadth spanning implants through capital equipment. Monitor BSI Group conformity assessment queue lengths as inflection indicator for market authorization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Marking Acceleration | BSI Group backlog compression unlocks faster product refresh cycles for implant manufacturers. |
| Managed Service Agreement Expansion | Per-procedure robotic leasing bypasses NHS capital constraints concentrated in foundation trusts. |
| Scotland and Wales Geographic Expansion | Devolved procurement frameworks in Edinburgh and Cardiff offer less saturated competitive terrain. |
| Biologics Portfolio Diversification | Synthetic graft substitutes counter displacement pressure on traditional interbody cage revenue. |
| Day-Case Surgery Licensing Pursuit | Ambulatory center capacity builds capture outpatient migration enabled by regulatory reforms. |
Research Methodology
A spread of perspectives from NHS procurement directors, spinal surgeons at teaching hospitals, biomedical engineers, and GPO contracts managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against hospital procurement databases, NICE technology appraisal records, and MHRA device registration filings. Bottom-up trust-level expenditure modeling triangulated against top-down manufacturer revenue pattern analysis.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by product type, technology approach, application severity, and end-user setting. CAGRs derived from procedure volume elasticity to aging demographics and capital equipment replacement cycles. Forecast inputs incorporated ICS consolidation timelines, UKCA transition velocity, and NICE guidance revision patterns.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by mid-tier implant manufacturers or accelerated robotic platform launches would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Near Vision Devices Market
Medical Devices
Deflectable Catheters Market
Medical Devices
Saudi Arabia Aesthetic Devices Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Dynamic Spinal Tethering Systems Market
Medical Devices
North America Medical Devices Market
Medical Devices
India Biopsy Devices Market
Medical Devices
Neurostimulation Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Venturi Mask Market