
 Bovine Pericardial Valve Market | 2026-2036
Bovine Pericardial Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Bovine Pericardial Valve Market Outlook
The capability gap between vertically integrated tissue processors and contract manufacturers is collapsing as proprietary fixation chemistries become the decisive cost driver. Edwards Lifesciences leverages its in-house bovine tissue sourcing and anti-calcification platforms to sustain premium positioning across surgical and transcatheter portfolios. Medtronic anchors its competitiveness through controlled supply chains for pericardial tissue and integrated delivery system manufacturing. Abbott Laboratories differentiates via specialized stent frame geometries optimized for bovine pericardial leaflets in transfemoral deployments.
A bovine pericardial valve is a bioprosthetic heart valve fabricated from the fibrous sac surrounding a cow's heart, chemically treated with glutaraldehyde or non-aldehyde fixation to reduce immunogenicity and calcification, and mounted on a metal or polymer stent frame for implantation via open-heart surgery or catheter-based delivery. Its primary purpose is to replace diseased native or prosthetic heart valves without requiring lifelong anticoagulation therapy associated with mechanical alternatives. Bioprosthetic valves occupy the largest revenue pool due to established reimbursement and surgeon familiarity, while transcatheter valves represent the fastest-growing segment as interventional cardiology displaces conventional surgery in intermediate-risk patients. Hospitals dominate procurement volume, though cardiac surgery centers capture disproportionate margins through bundled payment structures for complex valve procedures.
The FDA governs bovine pericardial valves through premarket approval and humanitarian device exemption pathways, while the EMA's Medical Device Regulation imposes stricter clinical follow-up and post-market surveillance obligations on European manufacturers. Japan's PMDA requires Japan-specific clinical data for novel transcatheter valve designs, creating a regulatory moat for early entrants with established local investigator networks. Stakeholders must monitor how evolving durability evidence from real-world transcatheter valve registries reshapes surgical versus interventional procedure economics.
Market Dynamics
The transition from surgical to transcatheter valve replacement is compressing procedure economics and forcing manufacturers to capture margin through proprietary fixation chemistries rather than tissue sourcing scale.
Growth Catalysts
- Japan's METI clusters:Government-backed medical device innovation hubs in Osaka and Tokyo are accelerating minimally invasive valve procedure adoption through subsidized training and reimbursement alignment.
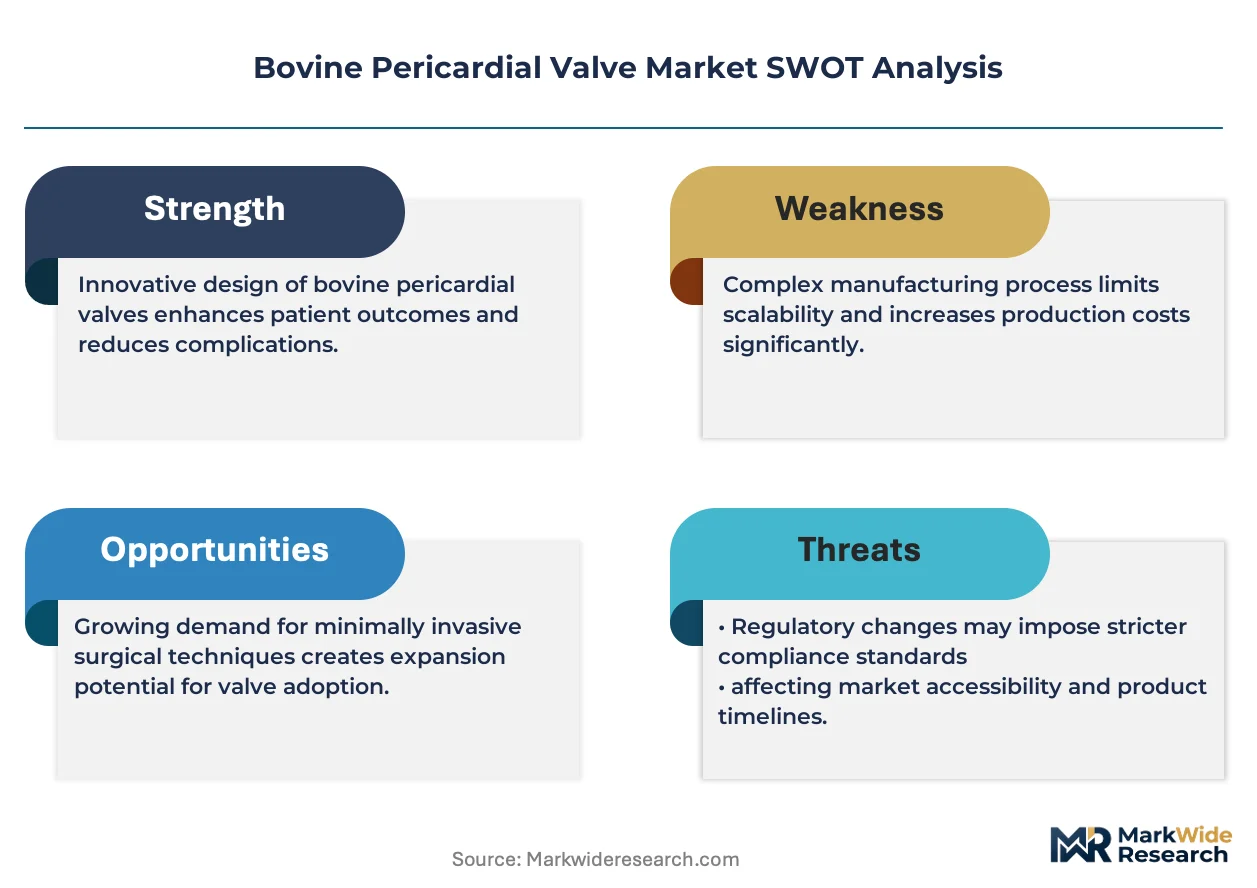
- FDA streamlined PMA pathway:The updated premarket approval framework for tissue-based cardiovascular devices reduces clinical trial burden for bioprosthetic valve manufacturers entering the US market.
- Anti-calcification chemistry advances:Novel non-aldehyde fixation methods are extending valve durability and expanding eligible patient populations to younger demographics previously restricted to mechanical valves.
Market Restraints
- Bovine pericardium supply concentration:Premium tissue sourcing depends on a limited network of certified abattoirs in Australia and New Zealand, creating vulnerability to livestock disease outbreaks.
- PMDA Japan-specific data requirements:The regulator mandates local clinical evidence for novel transcatheter designs, erecting a multi-year barrier for manufacturers lacking established investigator networks.
- Mechanical valve substitution threat:Next-generation polymer mechanical valves with reduced anticoagulation requirements threaten bioprosthetic dominance in cost-sensitive hospital procurement.
Strategic Opportunities
- India's underpenetrated cardiac surgery market:Rising middle-class healthcare expenditure and CDSCO regulatory harmonization create entry pathways for transcatheter valve platforms.
- EU MDR post-market surveillance data:Mandatory long-term durability registries generate proprietary real-world evidence that manufacturers can leverage for premium positioning.
- Convergence of imaging and delivery systems:Integration of intraprocedural CT-fluoroscopy fusion with self-expanding stent frames enables safer transfemoral deployment in intermediate-risk anatomies.
Industry Challenges
- Transcatheter skill acquisition timelines:Interventional cardiologists require 100+ supervised cases to achieve independent competency, constraining procedure volume expansion.
- EMA MDR technical documentation burden:Bioprosthetic valve manufacturers face 18-24 month certification delays due to enhanced clinical evaluation report requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bovine Pericardial Valve Market |
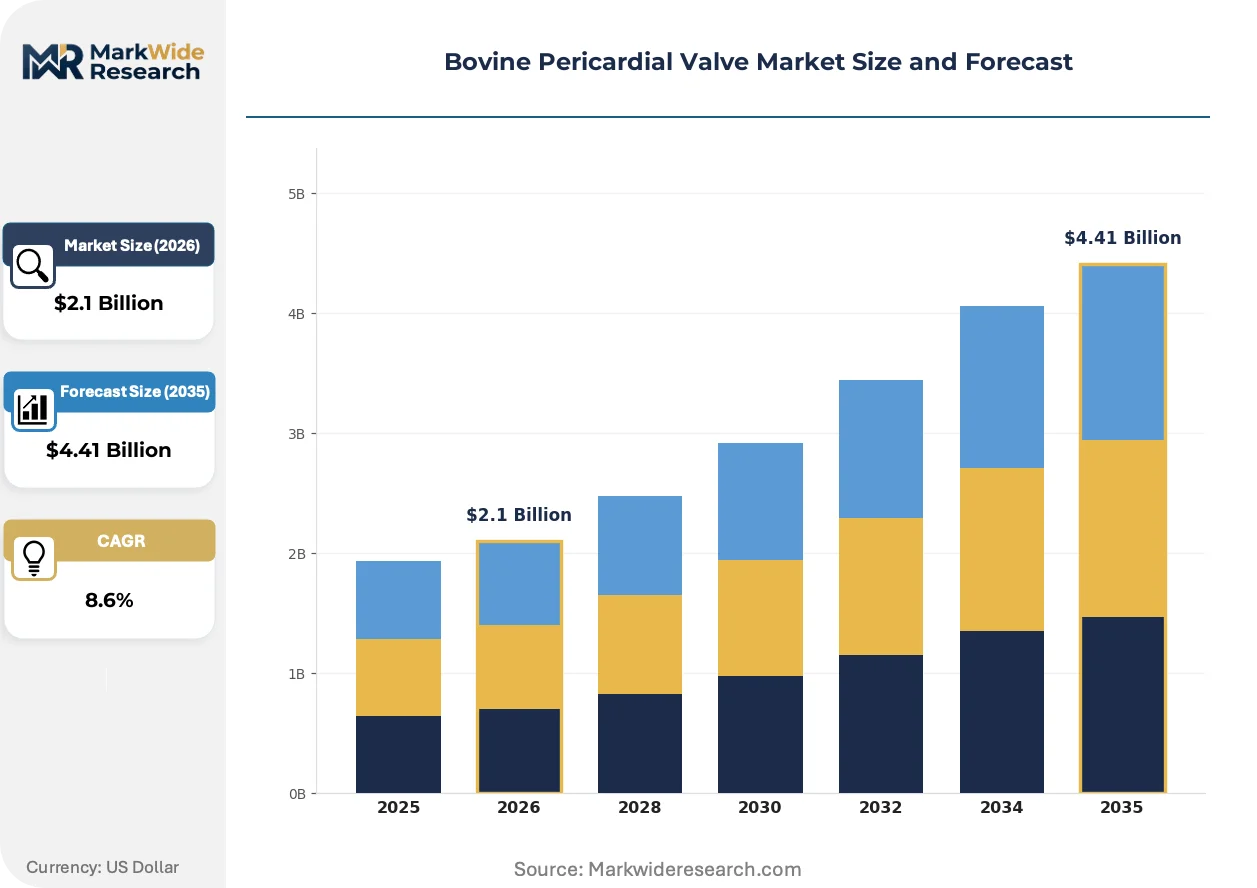
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.41 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Valves, Bioprosthetic Valves, Transcatheter Valves, TAVR Valves End User: Hospitals, Cardiac Surgery Centers, Outpatient Clinics, Research Institutions Delivery Mode: Surgical Procedures, Interventional Procedures, Minimally Invasive Techniques, Open-Heart Surgery Application: Valvular Heart Disease, Congenital Heart Defects, Heart Valve Repair, Heart Valve Replacement |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, LivaNova PLC, Meril Life Sciences Pvt. Ltd., CryoLife, Inc., Colibri Heart Valve, LLC, Braile Biomedica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bovine Pericardial Valve Market Strategic Shifts
Proprietary fixation platforms and delivery system miniaturization are separating durable market participants from contract-dependent assemblers. Three developments are compressing competitive timelines.
Polymer stent frame technology is fragmenting the transfemoral deployment landscape. Nitinol self-expanding designs with specialized geometries optimized for bovine pericardial leaflet kinematics are capturing share from balloon-expandable platforms. Cardiac surgery centers in Germany and Japan are adopting these systems for intermediate-risk patients previously routed to conventional surgery.
EMA's Medical Device Regulation imposes stricter clinical follow-up obligations on European manufacturers than its predecessor directive. Bioprosthetic valve sponsors must now submit 15-year post-approval safety data, forcing redesign of clinical trial endpoints and registry infrastructure. Smaller manufacturers lacking integrated surveillance capabilities are exiting the European market.
Hospital procurement committees are unbundling valve and delivery system purchasing, pressuring manufacturers to defend component pricing separately. Bundled payment structures for complex valve procedures in US cardiac surgery centers favor suppliers offering comprehensive procedure support over bare device vendors. This behavioral shift concentrates procurement authority within value analysis committees rather than individual surgeons.
Bovine Pericardial Valve Market Segmentation
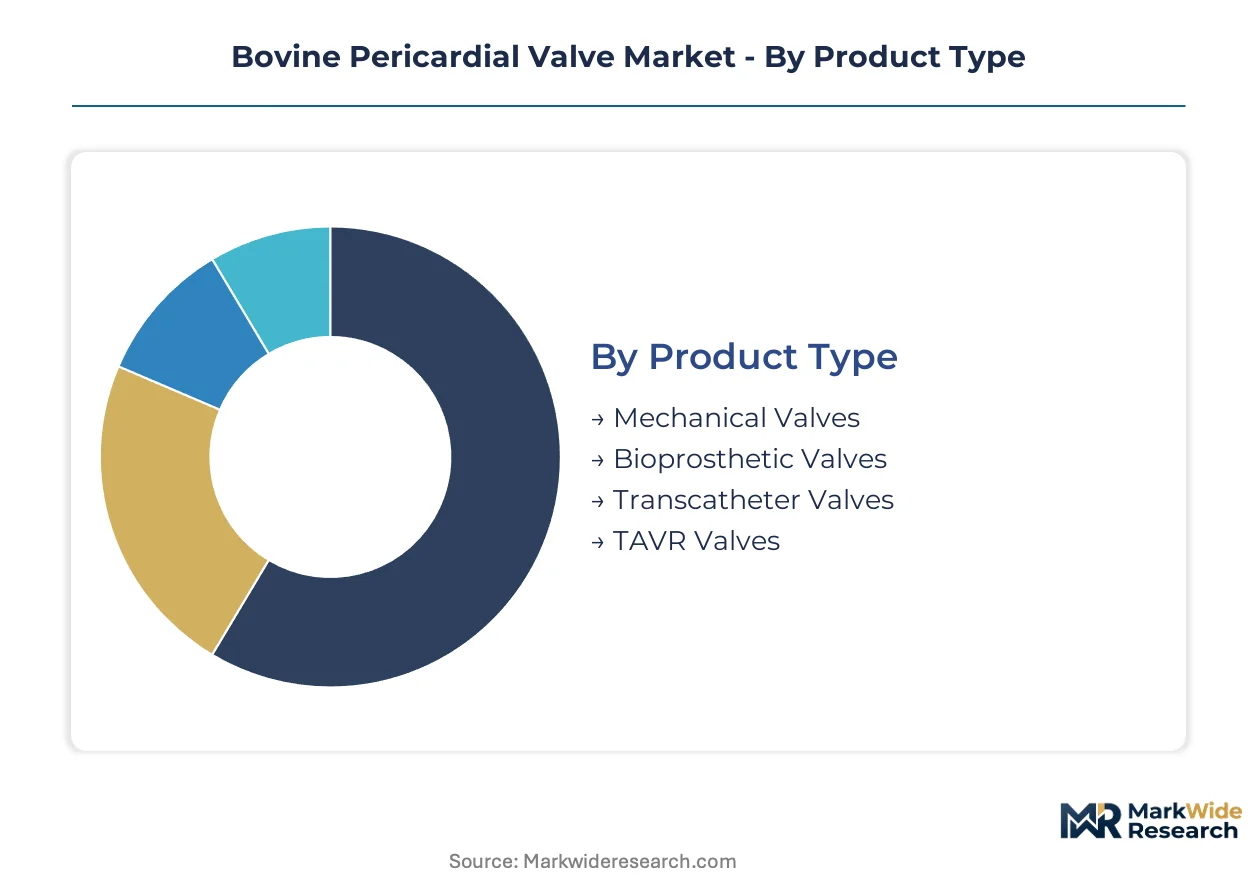
Bovine pericardial valve procurement patterns diverge sharply across clinical settings and procedural approaches. Substitution pressures from mechanical valves and polymer alternatives reshape competitive dynamics within each segment category.
Product Type:
Mechanical valve substitution threat varies dramatically by product category, with anticoagulation-free bioprosthetic designs facing intensifying pressure from next-generation polymer alternatives.
- Bioprosthetic Valves:Fabricated from glutaraldehyde-fixed bovine pericardium mounted on polymer or metal stents, these devices dominate revenue pools through established surgeon familiarity and reimbursement pathways. Demand concentrates in US cardiac surgery centers where bundled payment structures favor comprehensive procedure support. The segment faces mounting pressure from mechanical valve durability improvements in younger patient cohorts.
- Transcatheter Valves:Catheter-deployable bovine pericardial systems enable transfemoral aortic valve replacement without sternotomy. Japan's METI-supported innovation clusters in Osaka and Tokyo are accelerating adoption through subsidized interventional cardiologist training. PMDA's local clinical data requirements erect barriers for manufacturers lacking established investigator networks.
- TAVR Valves:Transcatheter aortic valve replacement systems represent a procedural subcategory with specialized delivery geometries optimized for bovine leaflet kinematics.
- Mechanical Valves:Pyrolytic carbon tilting-disc or bileaflet designs requiring lifelong anticoagulation therapy.
Bioprosthetic valves retain volume leadership; transcatheter valves hold the steepest expansion curve.
End User:
Procurement authority is migrating from individual surgeons toward value analysis committees, with margin capture varying by facility complexity and case mix.
- Hospitals:General acute care facilities dominate absolute procurement volume through high case throughput and standardized device contracts. US hospital systems are unbundling valve and delivery system purchasing, pressuring manufacturers to defend component pricing separately.
- Cardiac Surgery Centers:Specialized facilities capture disproportionate margins through bundled payment structures for complex valve procedures. Germany's expanding cardiac surgery centers are driving transcatheter adoption for intermediate-risk patients previously routed to conventional surgery.
- Outpatient Clinics:Ambulatory settings with limited procedural capabilities for diagnostic and follow-up care.
- Research Institutions:Academic medical centers conducting clinical trials and durability registry studies.
Hospitals retain volume leadership; cardiac surgery centers hold the steepest expansion curve.
Delivery Mode:
Procedural economics compress as interventional techniques displace conventional surgery, forcing manufacturers to capture margin through fixation chemistry rather than tissue sourcing scale.
- Interventional Procedures:Catheter-based deployment via transfemoral or transapical access eliminates sternotomy and cardiopulmonary bypass. Demand concentrates in Japan where aging demographics and METI cluster support accelerate minimally invasive adoption. Skill acquisition timelines of 100+ supervised cases constrain volume expansion.
- Minimally Invasive Techniques:Port-access or robotic-assisted surgical approaches with reduced tissue trauma.
- Surgical Procedures:Conventional valve replacement through median sternotomy with direct visualization.
- Open-Heart Surgery:Full sternotomy with cardiopulmonary bypass for complex anatomical presentations.
Surgical procedures retain volume leadership; interventional procedures hold the steepest expansion curve.
Application:
Patient age and comorbidity profiles determine valve selection, with durability evidence reshaping eligibility criteria across indication categories.
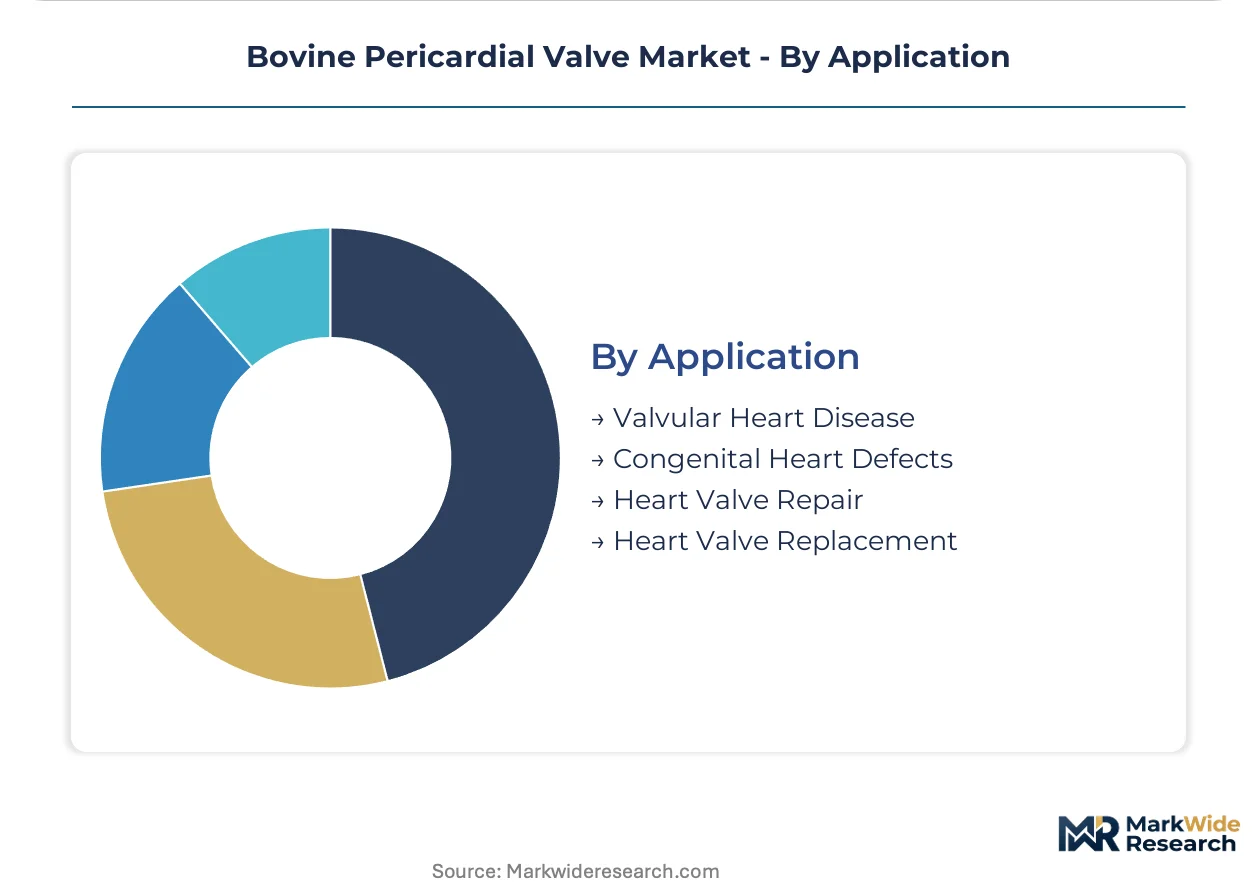
- Heart Valve Replacement:Definitive therapy for irreparable native or prosthetic valve dysfunction using bioprosthetic or mechanical substitutes. Demand concentrates in Germany and Japan where cardiac surgery centers are expanding transcatheter options for intermediate-risk anatomies. Anti-calcification chemistry advances are extending bioprosthetic durability and expanding eligible populations.
- Valvular Heart Disease:Acquired conditions including aortic stenosis and mitral regurgitation from degenerative, rheumatic, or infectious etiologies.
- Congenital Heart Defects:Structural abnormalities present from birth requiring early or delayed valve intervention.
- Heart Valve Repair:Preservation of native valve tissue through annuloplasty or leaflet reconstruction techniques.
Heart valve replacement retains volume leadership; valvular heart disease applications hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan and Germany where cardiac surgery centers command premium procurement terms, while cost-sensitive hospital systems in India and Brazil compress margins through volume-driven contracting. Regulatory divergence between FDA streamlined pathways and PMDA local data requirements fragments competitive positioning across major markets. Tissue sourcing networks in Australia and New Zealand anchor supply security for premium manufacturers serving high-value geographies.
United States
Hospital systems dominate procurement volume through standardized device contracts and bundled payment structures for complex valve procedures. The FDA's updated premarket approval pathway for tissue-based cardiovascular devices reduces clinical trial burden for bioprosthetic valve manufacturers entering the market. Cardiac surgery centers in Cleveland and Houston capture disproportionate margins through comprehensive procedure support offerings.
Germany
Cardiac surgery centers are expanding transcatheter bovine pericardial valve adoption for intermediate-risk patients previously routed to conventional surgery. The EMA's Medical Device Regulation imposes stricter clinical follow-up and post-market surveillance obligations on European manufacturers than its predecessor directive. Medical device innovation clusters in Berlin and Munich accelerate minimally invasive procedure adoption through subsidized interventional cardiologist training programs.
Japan
Aging demographics and METI-supported medical device innovation clusters in Osaka and Tokyo are accelerating minimally invasive valve procedures. PMDA requires Japan-specific clinical data for novel transcatheter valve designs, creating a regulatory moat for early entrants with established local investigator networks. Kansai region cardiac centers drive adoption of self-expanding stent frame systems optimized for bovine pericardial leaflet kinematics.
India
Rising middle-class healthcare expenditure and CDSCO regulatory harmonization create entry pathways for transcatheter valve platforms in an underpenetrated cardiac surgery market. Metropolitan hospital systems in Mumbai and Delhi-NCR are unbundling valve and delivery system purchasing, pressuring manufacturers to defend component pricing separately. Domestic manufacturers leverage cost-advantaged tissue processing to serve price-sensitive institutional procurement committees.
Australia
Premium tissue sourcing from certified abattoirs in Queensland and New South Wales creates supply security vulnerability to livestock disease outbreaks. TGA registration requirements align with international standards while maintaining rigorous post-market surveillance for bioprosthetic durability. Sydney and Melbourne cardiac centers serve as regional training hubs for transcatheter skill acquisition across Asia-Pacific markets.
Bovine Pericardial Valve Market Competitive Environment
Concentration sits with vertically integrated tissue processors possessing proprietary fixation chemistries and captive supply chains for pericardial sourcing. Three strategic archetypes define competitive positioning: integrated manufacturers controlling bovine tissue sourcing through certified abattoir networks, specialized assemblers relying on contract tissue processing with differentiated stent frame geometries, and emerging regional players leveraging cost-advantaged production for price-sensitive hospital procurement. Dominant competitive moves include backward integration into tissue sourcing to secure supply continuity and technology licensing partnerships for non-aldehyde fixation platforms.
Among US-based integrated manufacturers, Edwards Lifesciences Corporation exemplifies the vertically integrated archetype with in-house bovine tissue sourcing and anti-calcification platforms. Medtronic plc anchors the controlled supply chain segment through integrated pericardial tissue networks and delivery system manufacturing capabilities. Abbott Laboratories occupies a specialized position via differentiated stent frame geometries. These three entities represent the premium-tier competitive vector where proprietary fixation chemistry and procedure support bundling determine margin capture.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| LivaNova PLC |
| Meril Life Sciences Pvt. Ltd. |
| CryoLife, Inc. |
| Colibri Heart Valve, LLC |
| Braile Biomedica |
| Others |
Value Chain & Pricing Dynamics
FDA premarket approval tiers and ISO 13485 certification levels simultaneously gate supplier qualification and create price differentiation ladders in bovine pericardial valve procurement. Premium manufacturers with captive tissue processing capabilities command configured-to-order pricing for specialized fixation chemistries, while contract assemblers compete on standardized bioprosthetic platforms.
Pricing Analysis
Configured-to-order pricing for proprietary anti-calcification platforms commands substantial premiums over standardized glutaraldehyde-fixed valves. Pricing stratifies across premium, standard, and economy tiers based on fixation chemistry sophistication and stent frame customization level. Cost compression in the standard tier is intensifying because hospital procurement committees are unbundling valve and delivery system purchasing. General acute care hospitals exhibit highest price sensitivity; specialized cardiac surgery centers in Germany and Japan show lowest sensitivity due to bundled payment structures.
Supply Chain Analysis
Australia and New Zealand anchor premium bovine pericardial tissue sourcing through networks of certified abattoirs meeting TGA and ISO veterinary standards. Manufacturing draws from glutaraldehyde and novel non-aldehyde fixation reagents, nitinol and cobalt-chromium stent alloys, and specialized polymer delivery catheter materials. Single-source vulnerability concentrates in certified abattoir networks exposed to livestock disease outbreak risk. Distribution runs through direct hospital contracting and group purchasing organization agreements in the United States, with regional distributor networks serving European and Asia-Pacific markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bovine pericardial valve market is recovering from procedural volume compression during the pandemic, with cyclical expansion driven by aging demographics accelerating transcatheter eligibility expansion.
For Market Incumbents: Secure backward integration into certified abattoir networks to eliminate tissue sourcing vulnerability from livestock disease disruptions. Expand capacity for non-aldehyde fixation platforms in Japan to exploit PMDA regulatory moats before competitor investigator networks mature. Mechanical valve durability improvements in younger cohorts represent the priority substitution threat requiring defensive innovation in extended-durability bioprosthetic chemistry. For New Entrants and Emerging Players: Lead with cost-advantaged tissue processing capabilities targeting India's underpenetrated cardiac surgery market where CDSCO harmonization reduces regulatory friction. Focus initial commercialization on standardized surgical bioprosthetic platforms rather than transcatheter systems requiring 100+ case physician training partnerships. Partner with established delivery system manufacturers to bypass catheter engineering development timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract tissue processors lacking integrated fixation chemistry capabilities. Long-term viability over the next decade hinges on proprietary durability data from real-world registries rather than device engineering alone. Watch for EMA MDR enforcement actions forcing smaller manufacturers to exit European markets, creating distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Fixation Chemistry Development | Non-aldehyde platforms extend valve durability and expand eligible patient populations to younger demographics. |
| Japan Investigator Network Establishment | PMDA local data requirements create multi-year barriers for competitors lacking established clinical sites. |
| Certified Abattoir Backward Integration | Captive tissue sourcing eliminates supply disruption risk from livestock disease outbreaks in Australia and New Zealand. |
| Transcatheter Skill Training Infrastructure | Subsidized interventional cardiologist programs in METI clusters accelerate procedure volume expansion. |
| EU MDR Post-Market Surveillance Investment | Mandatory 15-year durability registries generate proprietary real-world evidence for premium positioning. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with cardiac surgeons, interventional cardiologists, hospital purchasing committee members, and biomedical engineering directors; and secondary validation through FDA PMA filings, EMA MDR technical documentation, PMDA approval summaries, and hospital procurement database extracts. Bottom-up triangulation across tissue processor capacity estimates and top-down reconciliation against procedure volume data anchored market sizing.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, delivery mode, end-user facility tier, and regional regulatory cluster. CAGRs were derived from procedure elasticity modeling against demographic projections and reimbursement policy scenarios. Fixation chemistry adoption curves and transcatheter penetration rates by surgical risk stratification served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained reimbursement alignment for transcatheter procedures or unexpected mechanical valve breakthroughs would require recalibration. Forecasts reflect assumptions regarding physician training pipeline capacity and tissue sourcing network stability. Recalibration cycles align with material shifts in regulatory enforcement patterns and durability registry publications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Reusable Medical Battery Market
Medical Devices
Lacrimal Duct Stent Tube Market
Medical Devices
Orthodontic Retainers Market
Medical Devices
Bowel Stimulators Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
North America Biopsy Devices Market
Medical Devices
Hearing Aids Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Injection Practice Pad Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Electrosurgical Devices Market