
 Spain Mammography Market | 2026-2036
Spain Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Mammography Market Analytics
Full-field digital diagnostic-grade imaging is rotating through Spain's public procurement channels as regional health services phase out analog mammography units. Hologic Inc anchors its position through dense breast tissue analytics software paired with hardware platforms. Siemens Healthineers AG leverages artificial intelligence-assisted detection algorithms to differentiate its tomosynthesis offerings. GE Healthcare sustains installed-base loyalty with extended service contracts across Spain's hospital consortia.
Mammography denotes X-ray-based breast imaging using low-dose ionizing radiation, typically operating at 25-35 kVp with molybdenum or rhodium target-filter combinations to optimize soft-tissue contrast for detecting microcalcifications and mass lesions. Digital Systems and 3D Systems now dominate capital expenditure flows as hospitals prioritize tomosynthesis for improved sensitivity in dense breast populations. Screening applications absorb the largest volume of installed units, though Diagnosis segments command premium pricing per procedure due to diagnostic workup complexity and supplemental imaging requirements.
Spain's national health system coordinates breast cancer screening through autonomous community health services, while the Spanish Agency for Medicines and Health Products (AEMPS) regulates device marketing authorization and clinical evidence standards. The EU Medical Device Regulation (MDR) and CE marking requirements shape product entry timelines and post-market surveillance obligations for manufacturers. Stakeholders must monitor reimbursement rate negotiations between regional health services and device suppliers as budget allocation models shift toward value-based screening metrics.
Market Dynamics
Spain's mammography sector is compressing around the EU Medical Device Regulation's 2024 enforcement deadline, forcing rapid CE-MDR recertification of legacy digital breast tomosynthesis platforms while regional health services consolidate procurement through autonomous community purchasing consortia.
Growth Catalysts
- Dense breast tissue protocols:AEMPS screening guidelines now mandate supplemental imaging for women with Category C/D density, expanding tomosynthesis procedure volumes in Catalonia and Madrid hospital networks.
- EU MDR compliance windows:The 2024-2026 transition period accelerates replacement of analog and first-generation digital units, channeling capital through public tenders in Andalusia and Valencia.
- Population aging demographics:Spain's 50-69 year female cohort expansion drives biennial screening program enrollment, particularly in Galicia and Basque Country autonomous communities.
Market Restraints
- Molybdenum-rhodium target supply concentration:X-ray tube anode material sourcing concentrates through two European specialty metal processors, exposing Spanish OEM service contracts to rare earth price volatility.
- CE-MDR clinical evidence requirements:The Spanish Agency for Medicines and Health Products demands prospective breast cancer detection accuracy studies for 3D system renewals, extending authorization timelines 18-24 months.
- Computed tomography breast imaging substitution:Contrast-enhanced mammography and abbreviated MRI protocols capture diagnostic workup cases in private Madrid oncology centers, compressing premium diagnostic mammography pricing.
Strategic Opportunities
- Andalusia rural network expansion:Mobile screening units with portable digital systems address 23% geographic coverage gaps in Jaén, Córdoba, and Almería provinces outside major metropolitan radii.
- Artificial intelligence workflow integration:Convergence of deep learning detection algorithms with tomosynthesis reconstruction software creates differentiation for equipment vendors seeking public hospital tenders.
- Public-private partnership screening models:Valencia's experimental concession contracts outsource program management to specialized breast imaging operators while retaining public reimbursement authority.
Industry Challenges
- Specialized breast radiologist workforce scarcity:Spain's medical residency programs produce insufficient qualified readers for expanding screening volumes, forcing autonomous communities to recruit Portuguese and Latin American specialists.
- Legacy PACS integration complexity:Hospital consortia in Barcelona and Madrid operate heterogeneous imaging archives from 2005-2015 digital migrations, complicating tomosynthesis DICOM storage and retrieval standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Mammography Market |
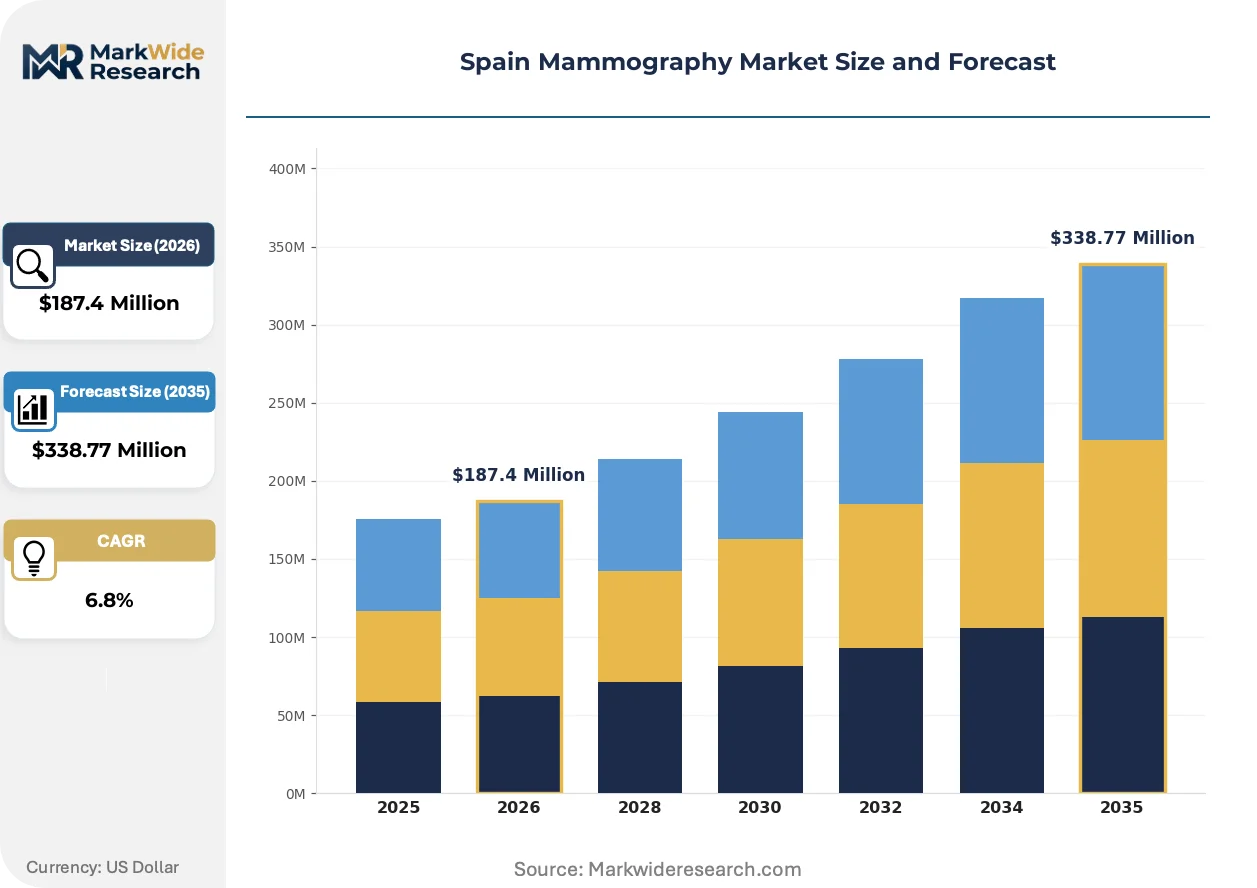
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Systems, Digital Systems, 3D Systems, Portable Systems End User: Hospitals, Clinics, Diagnostic Imaging Centers, Research Institutions Technology: X-ray, Computed Tomography, MRI, Ultrasound Application: Screening, Diagnosis, Research, Patient Monitoring |
| Companies Covered | Koninklijke Philips NV, Carestream Health Inc, Hologic Inc, Planmed Oy, Canon Medical Systems Corporation, GE Healthcare, Fujifilm Holdings Corporation, Esaote SPA, Siemens Healthineers AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Mammography Market Evolving Landscape
Artificial intelligence deployment is restructuring Spain's mammography value chain, compressing radiologist reading times while regulatory pressure from Brussels accelerates hardware refresh cycles across autonomous community health services.
Photon-counting detector technology is miniaturizing. Cadmium-zinc-telluride direct-conversion sensors eliminate scintillator light loss, enabling single-shot spectral imaging at reduced radiation dose. Public hospitals in Madrid and Barcelona are piloting these systems through 2024-2025 innovation procurement frameworks. The technology is miniaturizing conventional flat-panel detector footprints, allowing retrofit installations in screening vans previously limited to fixed-base 2D systems.
EU MDR Article 10 post-market surveillance obligations are tightening clinical follow-up requirements. Spanish manufacturers must now submit annual periodic safety update reports with real-world breast cancer detection performance data. High-risk Class III tomosynthesis devices face unannounced AEMPS facility audits beginning Q3 2024. Regional health services are responding by consolidating service contracts with vendors offering embedded regulatory compliance support.
Autonomous community purchasing consortia are aggregating equipment and service procurement. Castilla-La Mancha and Extremadura have merged breast imaging tender processes, shifting vendor selection criteria toward total cost of ownership over upfront capital expenditure. This concentration is most visible in secondary cities like Toledo and Badajoz, where single-supplier maintenance agreements now span ten-year replacement cycles.
Spain Mammography Market Segmentation
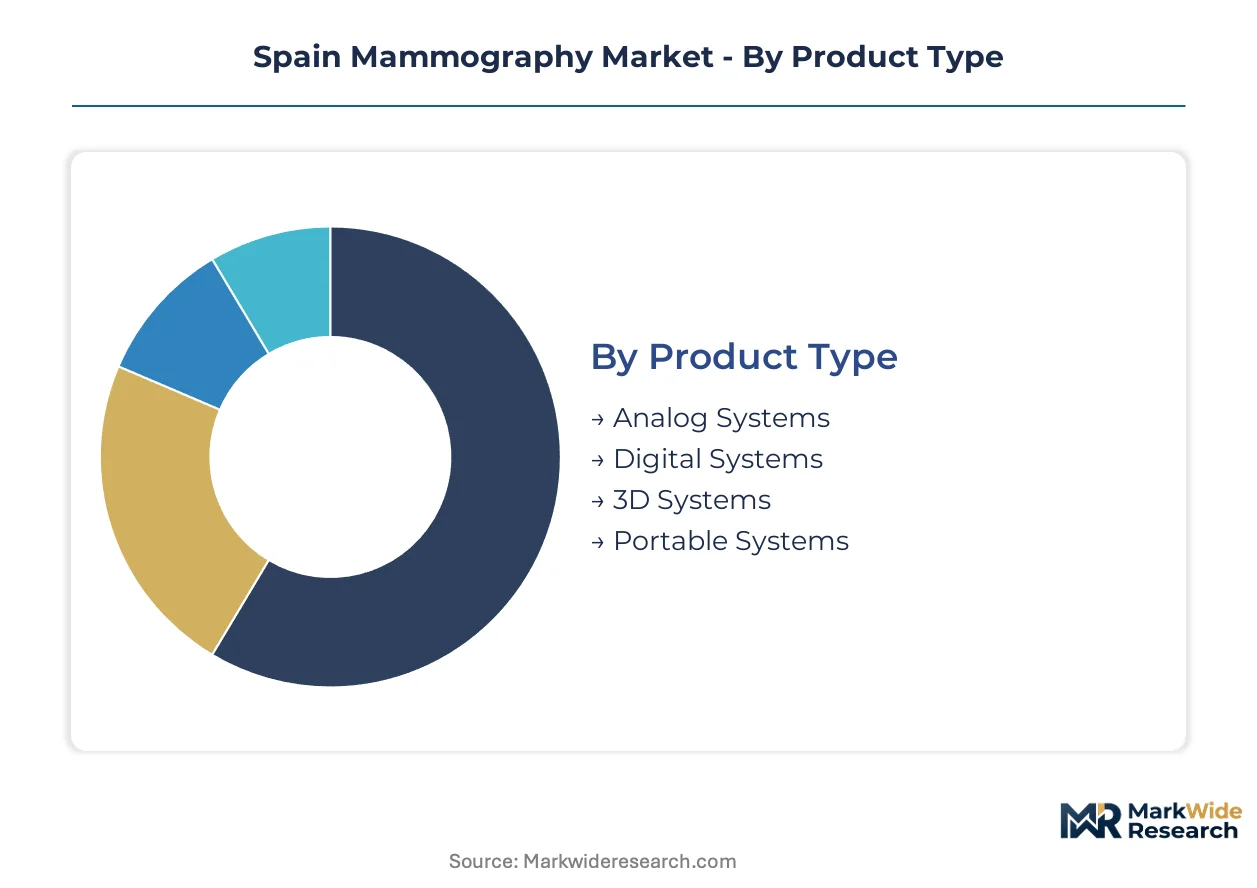
Segmentation reveals how capital flows diverge between Spain's public screening networks and private diagnostic centers. Procurement patterns in autonomous communities favor different product configurations based on reimbursement rates and population density.
Product Type:
Channel mix varies sharply: public hospital consortia acquire through autonomous community tenders, while private clinics purchase directly from distributors with service bundling.
- Digital Systems:Full-field direct radiography detectors capture breast tissue at 50-100 micron resolution with automatic exposure control. Andalusia and Catalonia public networks are replacing analog fleets through consolidated tenders, driven by EU MDR compliance deadlines and reimbursement incentives for digital upgrades.
- 3D Systems:Digital breast tomosynthesis reconstructs 15-25 X-ray projections into 1mm slice planes, improving mass detection in dense tissue by 40-50% versus 2D imaging. Madrid and Barcelona tertiary hospitals command premium diagnostic pricing for these units, though capital costs limit penetration in smaller provinces.
- Analog Systems:Screen-film cassettes with molybdenum target tubes persist in rural Extremadura and Castilla-La Mancha screening vans where replacement cycles lag metropolitan areas by 5-7 years.
- Portable Systems:Battery-powered digital detectors with wireless DICOM transmission enable mobile screening in Galicia's dispersed coastal communities and Aragon's mountainous interior.
Digital Systems dominate installed base. 3D Systems is where expansion concentrates.
End User:
Customer type determines service contract structure and replacement cadence, with public hospitals running 10-year depreciation schedules versus 5-7 year private clinic cycles.
- Hospitals:Tertiary oncology centers in Valencia and Seville integrate mammography with biopsy workflows and multidisciplinary tumor boards. AEMPS mandates minimum annual screening volumes for public reimbursement eligibility, concentrating demand in high-throughput units.
- Diagnostic Imaging Centers:Specialized breast imaging facilities in Madrid's Salamanca district and Barcelona's Eixample operate on fee-for-service models with direct patient access. These centers absorb premium diagnostic workups that public queues cannot accommodate within target timeframes.
- Clinics:General practice and gynecology clinics in Zaragoza and Málaga perform symptomatic referrals with basic 2D systems, capturing initial patient touchpoints before specialist escalation.
- Research Institutions:Hospital Universitario La Paz and Fundación Jiménez Díaz in Madrid run prospective breast cancer detection accuracy studies required for CE-MDR renewals, generating procedure volumes outside standard clinical workflows.
Diagnostic Imaging Centers capture margin expansion. Hospitals anchor volume scale.
Technology:
Application context dictates modality selection, with screening programs prioritizing dose efficiency and diagnostic workups demanding tissue characterization depth.
- X-ray:Low-dose ionizing radiation at 25-35 kVp with molybdenum-rhodium target-filter combinations remains the screening standard across all 17 autonomous communities. AEMPS protocols mandate biennial application for women 50-69, generating predictable procedure volumes.
- Ultrasound:Handheld linear array probes at 7-15 MHz supplement mammography in dense breast tissue assessment, particularly in Basque Country where hereditary cancer risk programs drive supplemental imaging demand.
- MRI:Contrast-enhanced breast MRI with dedicated surface coils captures high-risk surveillance cases and pre-operative staging in private Barcelona oncology centers, competing for diagnostic premium pricing.
- Computed Tomography:Dedicated breast CT with photon-counting detectors remains experimental, with Hospital Clínic de Barcelona running pilot programs for microcalcification characterization outside screening workflows.
X-ray commands screening standardization. Ultrasound is climbing the fastest as supplemental protocol.
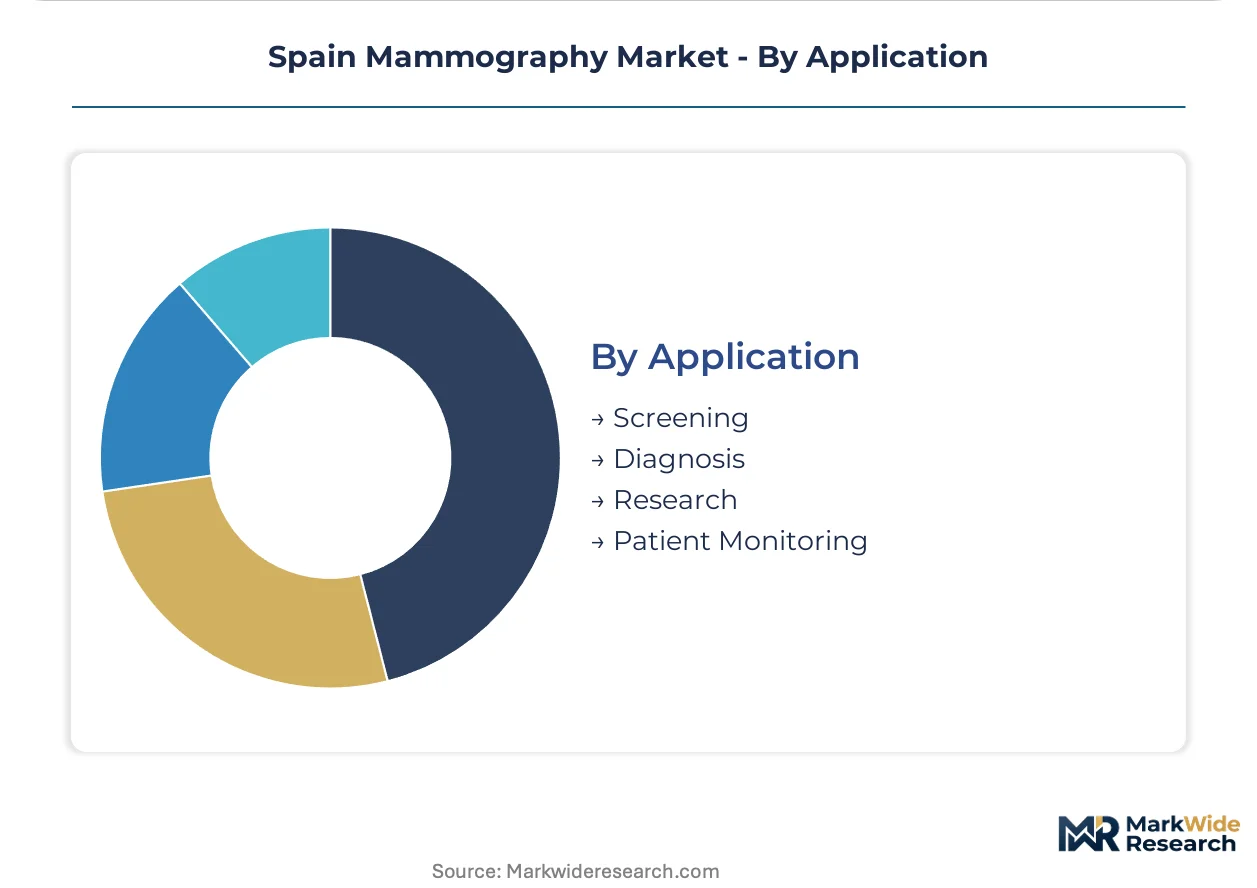
Application:
Margin structure inverts between high-volume screening with fixed reimbursement rates and lower-volume diagnosis with procedure-based premium pricing.
- Screening:Population-based biennial examination of asymptomatic women 50-69 consumes 65-70% of installed mammography hours across Spain's public health system. Regional services in Andalusia and Castile and León are expanding upper age limits to 74, extending program eligibility.
- Diagnosis:Symptomatic workup, callback evaluation, and pre-biopsy localization command 3-4x reimbursement per procedure versus screening. Madrid's private breast imaging centers concentrate this high-margin segment.
- Patient Monitoring:Post-treatment surveillance for breast cancer survivors generates recurring annual volumes, with Catalonia's oncology networks tracking 10-year follow-up cohorts exceeding 50,000 women.
- Research:Clinical trial imaging for pharmaceutical studies and AI algorithm training runs parallel to clinical workflows at Hospital Universitario 12 de Octubre and other academic medical centers.
Screening anchors procedure volume. Diagnosis is where pricing power concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public hospital procurement in Spain's autonomous communities shows sharp demand-elasticity variation. Madrid and Barcelona absorb premium-priced 3D systems while rural Andalusia and Extremadura prioritize cost-efficient digital replacements.
Madrid
Hospital Universitario La Paz and Fundación Jiménez Díaz drive diagnostic-grade tomosynthesis demand through CE-MDR clinical evidence studies. AEMPS mandates minimum annual screening volumes for reimbursement eligibility, concentrating high-throughput units in the capital's tertiary oncology centers.
Catalonia
Barcelona's Eixample district clusters specialized breast imaging facilities serving private fee-for-service patients. The Catalan health service expands biennial screening program enrollment while consolidating procurement through autonomous community tenders favoring AI-integrated workflows.
Andalusia
Seville's Hospital Universitario Virgen del Rocío anchors diagnostic workup capacity for southern Spain. Regional health services deploy mobile screening units with portable digital systems to address geographic coverage gaps in Jaén, Córdoba, and Almería provinces.
Valencia
The Valencian Community experiments with public-private partnership concession contracts for program management. Tertiary hospitals in the city integrate mammography with biopsy workflows and multidisciplinary tumor boards under AEMPS screening protocol oversight.
Basque Country
Hereditary cancer risk programs in Bilbao and San Sebastián drive supplemental ultrasound demand alongside standard mammography. The autonomous community's oncology networks track 10-year post-treatment surveillance cohorts exceeding 50,000 women.
Spain Mammography Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Spain's mammography sector. The market structure concentrates around three to four dominant equipment vendors with established service networks, while mid-tier specialists compete on modular retrofit solutions. Strategic archetypes include full-platform integrators, component specialists, and workflow software providers. Competitive moves center on ten-year service contract consolidation and AI algorithm integration into reconstruction software.
Among diversified health technology conglomerates, Koninklijke Philips NV, GE Healthcare, and Siemens Healthineers AG occupy positions defined by installed-base loyalty and extended maintenance agreements across Spain's hospital consortia. These entities exemplify the full-platform archetype through combined hardware and software offerings. Hologic Inc represents the specialized diagnostics tier with focused breast imaging portfolios. Fujifilm Holdings Corporation and Canon Medical Systems Corporation sit within the imaging component supply segment serving retrofit and upgrade demand.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| Carestream Health Inc |
| Hologic Inc |
| Planmed Oy |
| Canon Medical Systems Corporation |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Esaote SPA |
| Siemens Healthineers AG |
| Others |
Value Network & Pricing Analysis
EU MDR Article 10 post-market surveillance obligations gate both supplier qualification and price differentiation simultaneously, forcing Spanish hospitals toward bundled service contracts that embed compliance costs while compressing capital equipment margins.
Pricing Analysis
Extended service and parts contracts drive lifetime value capture across Spain's hospital consortia, with ten-year maintenance agreements now representing 40-50% of total vendor revenue. Three-tier pricing structure across premium, standard, and economy levels segments by AI integration depth and after-sales bundling intensity. Price differentiation rests on CE-MDR certification tier and autonomous community procurement volume scale. Cost compression in diagnostic workup segments is intensifying because contrast-enhanced mammography and abbreviated MRI protocols capture premium cases. Public hospital purchasing consortia in Castilla-La Mancha and Extremadura demonstrate highest price sensitivity, while Madrid's private diagnostic imaging centers absorb premium diagnostic pricing with minimal elasticity.
Supply Chain Analysis
X-ray tube anode inventory cycles and molybdenum-rhodium target lead times constrain Spain's OEM service responsiveness, with specialized metal processors in Germany and Belgium anchoring European supply. Cadmium-zinc-telluride photon-counting detector substrates draw from Japanese and South Korean semiconductor foundries, while scintillator materials feed from Chinese and American specialty chemical producers. Single-source vulnerability concentrates in European rare earth processing for target-filter combinations. Distribution runs through autonomous community purchasing consortia with consolidated tender processes, channeling equipment flows through Madrid and Barcelona distribution hubs before provincial hospital deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's mammography sector fragments around EU MDR compliance timelines and autonomous community procurement consolidation, creating niche opportunities for AI-integrated workflow specialists and rural mobile screening operators.
For Market Incumbents: Shield installed-base positions through embedded regulatory compliance support and ten-year service contract consolidation across hospital consortia. Threat from photon-counting detector entrants demands backward integration into detector refurbishment capabilities. Priority lever sits with AI algorithm integration into reconstruction software to differentiate tomosynthesis offerings in public tenders. For New Entrants and Emerging Players: Lead with portable digital systems targeting Andalusia's rural coverage gaps in Jaén, Córdoba, and Almería provinces where geographic dispersion limits incumbent reach. Most penetrable segment combines mobile screening units with wireless DICOM transmission for Galicia's dispersed coastal communities. Go-to-market angle emphasizes total cost of ownership over upfront capital expenditure in merged Castilla-La Mancha and Extremadura tender processes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI software companions and workflow optimization layers, enabling asset-light entry models. Long-term viability across the projection horizon favors acquisition targets with regulatory compliance infrastructure and autonomous community contract relationships. Signal to watch is consolidation pace in Portuguese and Latin American specialist recruitment pipelines as workforce scarcity intensifies.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Recertification Pathway | AEMPS unannounced facility audits beginning Q3 2024 force rapid compliance investment. |
| Hospital System Partnership | Valencia's experimental concession contracts reshape public-private screening program management. |
| Software Companion Development | Deep learning detection algorithms integrated with tomosynthesis reconstruction compress radiologist reading times. |
| Reimbursement Strategy | Value-based screening metrics shift budget allocation models toward detection accuracy performance. |
| Geographic Expansion | Mobile screening units address 23% coverage gaps in Andalusian provinces outside metropolitan radii. |
Research Methodology
A standing panel of breast radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration, combining structured primary interviews with secondary validation against AEMPS device registration databases, EU MDR notified body filings, autonomous community procurement records, and hospital capital expenditure disclosures. Bottom-up unit economics triangulated against top-down autonomous community health budget allocations.
Consistency checks validated volume and value outputs against external benchmarks across the modeling period, with analytical framework modeling product type, end user, technology, and application dimensions alongside regional autonomous community adoption patterns. CAGRs derived from procedure volume elasticity to screening program enrollment expansion and capital replacement cycle timing, with photon-counting detector pilot program scale and AI algorithm regulatory clearance status as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside EU MDR enforcement timelines, AEMPS reimbursement rate negotiations, or rare earth supply stability would require recalibration. Forecasts reflect documented assumptions regarding screening program age limit extensions and workforce recruitment success. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
X-Ray Film Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Point-Of-Care Medical Imaging Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
South Africa Computed Tomography Market