
 Global Tumor Tracking Systems Market | 2026-2036
Global Tumor Tracking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tumor Tracking Systems Market Intelligence
Hospital procurement channels for radiation oncology equipment are reconfiguring around bundled service contracts that pair hardware with continuous software upgrades. Thermo Fisher Scientific leverages its life sciences distribution network to reach academic medical centers pursuing translational research applications. Siemens Healthineers anchors its position through direct field-service teams embedded at major radiotherapy centers across multiple continents. Varian Medical Systems competes by controlling the full workflow from simulation through treatment delivery.
Tumor tracking systems comprise integrated hardware-software platforms that detect, monitor, and compensate for respiratory and anatomical motion during external beam radiation therapy, typically achieving spatial accuracy within one millimeter through electromagnetic or optical sensing modalities. These systems enable clinicians to tighten treatment margins, escalate dose per fraction, and spare adjacent healthy tissue in curative and palliative regimens. Optical tracking retains the largest installed base among product types due to its maturity in cranial and spinal applications, while markerless electromagnetic platforms represent the fastest-expanding segment as algorithms improve real-time lung tumor localization without implanted fiducials. Integrated software solutions capture disproportionate margin pools by locking customers into recurring analytics subscriptions.
FDA 510(k) clearances and EU MDR conformity assessments shape product development timelines, with both regulators demanding extensive clinical validation of algorithm-driven motion compensation. ISO 13485 quality management systems and IEC 60601 electrical safety standards form baseline requirements for market access across all major jurisdictions. Stakeholders must monitor how FDA's evolving software-as-a-medical-device guidance and the EU AI Act's risk classification framework will reshape validation burdens for artificial intelligence-enhanced tracking algorithms.
Market Dynamics
Markerless electromagnetic tracking algorithms are compressing clinical validation timelines while forcing hardware-software unbundling, as cancer centers demand modular upgrades without full platform replacement cycles.
Growth Catalysts
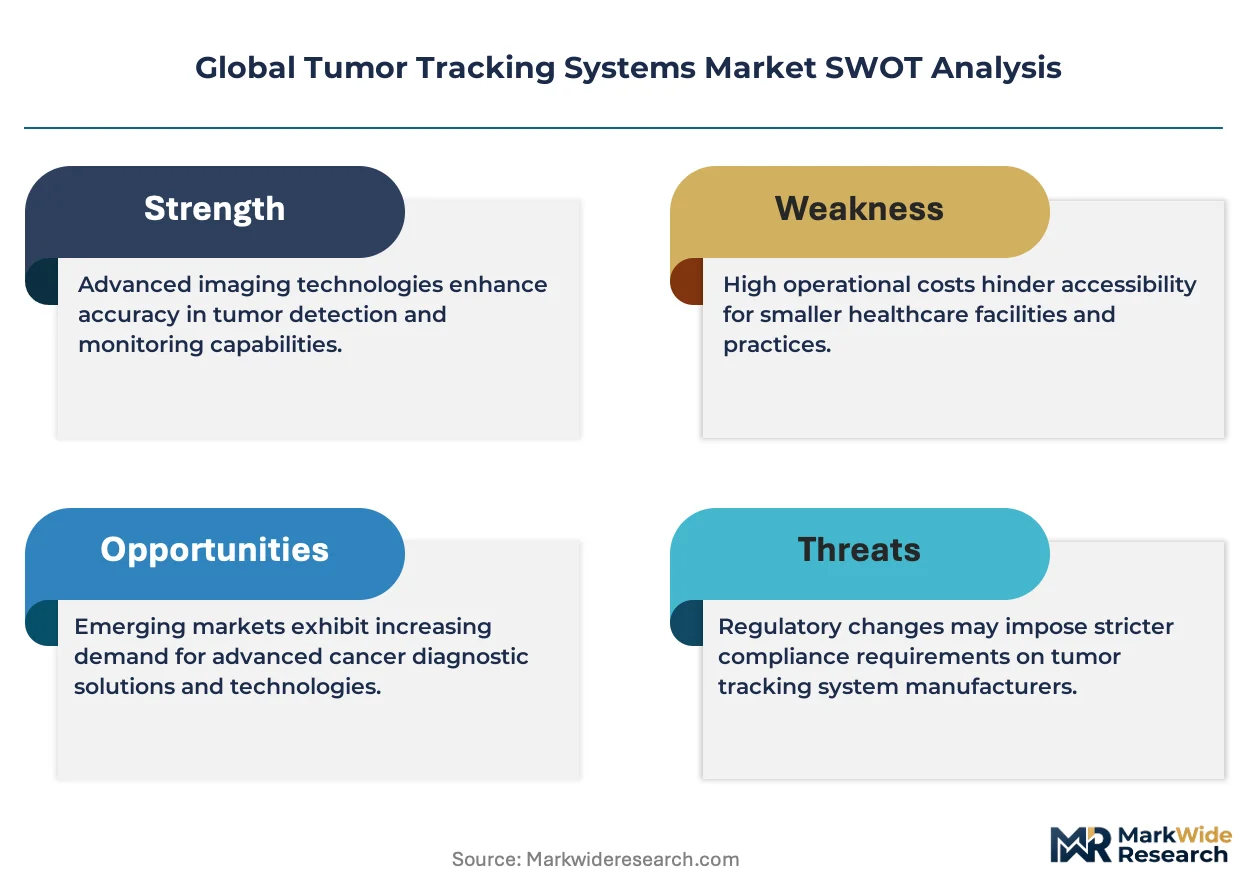
- EU MDR framework:Stricter software validation requirements for integrated motion management platforms are locking early-compliant vendors into multi-year hospital service contracts.
- Lung cancer protocols:Real-time tumor localization without implanted fiducials is expanding treatable patient populations previously excluded from curative radiotherapy.
- Japan METI initiatives:Government-backed precision medicine programs are accelerating reimbursement coverage for advanced motion compensation technologies in academic medical centers.
Market Restraints
- Input cost volatility:Electromagnetic sensor arrays and high-speed optical cameras face supply concentration in Taiwanese semiconductor foundries, exposing margins to foundry allocation cycles.
- Technical limitation:Current algorithms struggle with tumor visibility in patients with extreme body mass index variation, restricting addressable populations in North American markets.
- Regulatory friction:FDA 510(k) clearance pathways for software-as-a-medical-device are extending review timelines for AI-enhanced tracking algorithms beyond historical hardware-only benchmarks.
Strategic Opportunities
- Underpenetrated geography:Brazil's ANVISA regulatory harmonization with FDA standards is opening procurement channels for refurbished electromagnetic tracking systems in São Paulo's private oncology networks.
- Technology convergence:Integration of real-time magnetic resonance imaging with electromagnetic tracking is enabling direct tumor visualization during treatment delivery.
- Distribution innovation:Direct-to-hospital software subscription models are bypassing traditional capital equipment leasing channels, capturing recurring revenue from mid-tier cancer centers.
Industry Challenges
- Specialized workforce scarcity:Medical physicists trained in commissioning electromagnetic tracking systems command premium compensation, constraining deployment velocity at community hospitals.
- Legacy integration complexity:Proprietary data formats from installed linear accelerators resist seamless interoperability with third-party tracking platforms, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tumor Tracking Systems Market |
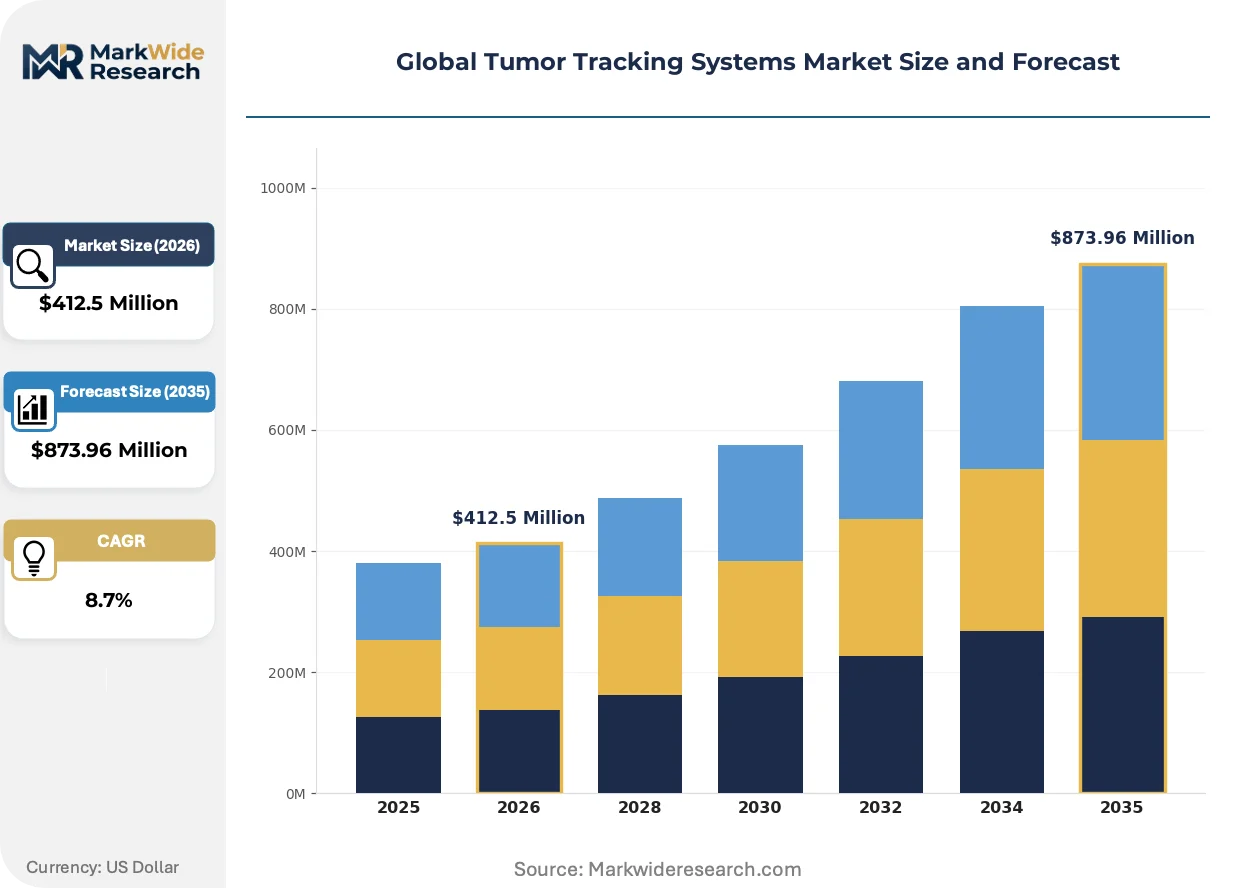
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Tracking, Electromagnetic Tracking, Ultrasound Tracking, Infrared Tracking, Radiofrequency Tracking Application: Lung Cancer, Prostate Cancer, Breast Cancer, Head & Neck Cancer, Liver Cancer End User: Oncology Clinics, Research Institutions, Radiotherapy Centers, Surgical Hospitals, Cancer Centers Technology: Real-Time Imaging, Marker-Based Systems, Markerless Systems, Motion Management, Integrated Software Solutions |
| Companies Covered | Menarini Silicon Biosystems, Cell Biolabs, Inc., Thermo Fisher Scientific, QIAGEN, Genekam, Miltenyi Biotec, STEMCELL Technologies Inc., Varian Medical Systems, Inc., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tumor Tracking Systems Market Strategic Shifts & Innovations
Artificial intelligence inference at the edge is compressing latency thresholds for motion compensation while regulatory frameworks race to validate algorithm-driven clinical decisions without human-in-the-loop verification.
Markerless electromagnetic tracking is hybridizing optical sensing with deep learning-based anatomical recognition to eliminate fiducial implantation procedures. Major cancer centers in Germany and the United States are piloting these platforms for abdominal malignancies. The technology is hybridizing hardware procurement models by decoupling sensor arrays from treatment delivery systems, enabling component-level upgrades.
FDA's evolving software-as-a-medical-device guidance is reclassifying algorithm-driven motion compensation as higher-risk devices requiring clinical outcome studies. Manufacturers face expanded documentation burdens for training data provenance and algorithm update protocols. Radiation oncology departments are responding by consolidating vendor relationships to reduce validation overhead.
After-sales service unbundling is fragmenting traditional equipment leasing arrangements into discrete software maintenance, hardware warranty, and clinical support contracts. Independent service organizations are capturing mid-tier hospital accounts previously locked into manufacturer-integrated offerings. This pattern is most visible in United States outpatient proton therapy centers seeking operational flexibility.
Global Tumor Tracking Systems Market Segmentation
Tumor tracking systems fragment across hardware modalities, clinical applications, and technology architectures that dictate distinct procurement cycles and service intensity. Understanding these divides clarifies where vendors capture recurring revenue versus one-time equipment sales.
Product Type:
After-sales-service intensity varies sharply across tracking modalities, with electromagnetic platforms demanding continuous algorithm updates while optical systems require periodic calibration contracts.
- Optical Tracking:Camera-based triangulation systems achieve sub-millimeter accuracy for cranial and spinal targets using passive reflective markers. German university hospitals anchor installed base demand for legacy optical platforms in stereotactic radiosurgery suites.
- Electromagnetic Tracking:Sensor arrays detect alternating magnetic fields from implanted or surface coils, enabling real-time lung tumor localization without line-of-sight constraints. Japanese academic medical centers under METI precision medicine programs are accelerating adoption of markerless electromagnetic configurations for abdominal malignancies.
- Ultrasound Tracking:Acoustic imaging tracks soft-tissue motion in prostate and liver applications with portable hardware footprints.
- Infrared Tracking:LED-based position sensing dominates cost-sensitive installations in emerging market radiotherapy centers.
- Radiofrequency Tracking:Electromagnetic beacon systems serve niche applications in intraoperative navigation and brachytherapy guidance.
By volume, Optical Tracking leads. By growth pace, Electromagnetic Tracking is ahead.
Application:
Clinical indication determines reimbursement coding, treatment margin protocols, and the economic case for tracking hardware investment.
- Lung Cancer:Respiratory motion compensation enables stereotactic ablative radiotherapy for early-stage tumors previously deemed untreatable. United States cancer centers in Texas and Florida are expanding markerless tracking capacity for high-volume lung protocols.
- Prostate Cancer:Intrafraction motion management supports hypofractionated regimens that compress treatment courses from eight weeks to four or five sessions. German outpatient radiotherapy networks prioritize electromagnetic tracking for prostate dose escalation programs.
- Breast Cancer:Deep inspiration breath-hold integration with surface tracking reduces cardiac dose in left-sided treatments.
- Head & Neck Cancer:Rigid immobilization requirements limit tracking value-add relative to positioning verification systems.
- Liver Cancer:Fiducial-based electromagnetic tracking addresses respiratory and diaphragmatic motion in stereotactic body radiation therapy.
Prostate Cancer applications generate the highest per-procedure reimbursement. Lung Cancer applications are climbing the fastest as screening expands treatable cohorts.
End User:
Customer type shapes contract structure, with research institutions demanding data rights while clinical operators prioritize uptime guarantees.
- Oncology Clinics:Community-based facilities in the United States are consolidating vendor relationships to reduce physicist training burden across multi-site networks.
- Research Institutions:Academic medical centers in Germany and Japan negotiate publication rights and algorithm transparency as contract terms.
- Radiotherapy Centers:High-throughput operators in Brazil's São Paulo private networks are piloting refurbished electromagnetic systems following ANVISA regulatory harmonization.
- Surgical Hospitals:Hybrid operating suites require tracking interoperability with navigation systems and imaging archives.
- Cancer Centers:Comprehensive cancer centers in the United States anchor demand for integrated motion management across multiple disease sites.
Radiotherapy Centers dominate unit volume. Research Institutions command the steepest expansion trajectory as translational programs proliferate.
Technology:
Software-hardware integration depth determines margin capture, with integrated platforms locking customers into recurring analytics subscriptions.
- Real-Time Imaging:Continuous fluoroscopic or MRI-derived feedback enables direct tumor visualization during beam delivery. Siemens Healthineers and Varian Medical Systems are competing to integrate real-time magnetic resonance with electromagnetic tracking at major German and United States academic centers.
- Marker-Based Systems:Implanted fiducials or surface markers provide stable reference points for motion compensation algorithms. Established clinical validation pathways under FDA 510(k) and EU MDR sustain installed base loyalty despite invasive implantation requirements.
- Markerless Systems:Deep learning-based anatomical recognition eliminates fiducial procedures, expanding treatable populations. Algorithm-driven classification under FDA software-as-a-medical-device guidance and EU AI Act risk frameworks is extending validation timelines.
- Motion Management:Gating and tracking control systems synchronize beam delivery with respiratory phase.
- Integrated Software Solutions:Analytics platforms aggregate treatment data across patient cohorts for outcome modeling and protocol optimization.
Marker-Based Systems retain the largest installed footprint. Markerless Systems are gaining share fastest as algorithm confidence improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Cologne rail corridor underwrites Germany's centrality in European radiotherapy equipment logistics, while Japan's Shinkansen network connects Tokyo academic medical centers to Osaka manufacturing clusters for precision instrumentation.
United States
Texas Medical Center in Houston and MD Anderson Cancer Center anchor demand for markerless electromagnetic lung tracking systems. FDA 510(k) clearance pathways for software-as-a-medical-device are extending review timelines for AI-enhanced algorithms beyond historical hardware benchmarks. Florida's proton therapy centers in Jacksonville and Orlando are piloting refurbished tracking platforms under bundled service contracts.
Germany
Heidelberg University Hospital and Munich's Rechts der Isar Medical Center drive adoption of integrated motion management for stereotactic body radiation therapy. EU MDR conformity assessments for algorithm-driven platforms are locking early-compliant vendors into multi-year hospital service agreements. The Rhine-Main cluster around Frankfurt concentrates procurement decision-making for central European radiotherapy networks.
Japan
University of Tokyo Hospital and Osaka University Hospital accelerate deployment of real-time tumor localization under METI precision medicine initiatives. PMDA regulatory harmonization with FDA standards compresses validation timelines for electromagnetic tracking systems. The Nagoya-Tokyo corridor hosts manufacturing facilities supplying sensor arrays to domestic cancer centers.
Brazil
São Paulo's private oncology networks in the Jardins and Moema districts are piloting refurbished electromagnetic tracking systems following ANVISA regulatory harmonization with FDA standards. The country's national health surveillance agency is streamlining import pathways for pre-owned radiotherapy equipment. Rio de Janeiro's Barra da Tijuca medical corridor is consolidating vendor relationships to reduce physicist training burdens.
United Kingdom
The Royal Marsden NHS Foundation Trust and University College London Hospitals anchor demand for optical tracking in stereotactic radiosurgery suites. MHRA post-Brexit regulatory autonomy is creating divergence timelines from EU MDR for software validation requirements. The Cambridge-Oxford-London golden triangle concentrates translational research programs pursuing markerless tracking algorithms.
Global Tumor Tracking Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying sensor arrays and calibration modules to multiple OEMs. The vendor base concentrates around three strategic archetypes: diversified life sciences conglomerates with distribution depth, dedicated radiation oncology equipment manufacturers with embedded field service, and emerging software-native vendors pursuing subscription revenue models. Dominant competitive moves include strategic partnerships between hardware OEMs and AI algorithm developers, plus geographic expansion through refurbished equipment channels in price-sensitive markets.
Among diversified life sciences conglomerates, Thermo Fisher Scientific leverages its research reagent distribution network to reach academic medical centers pursuing translational applications, while Siemens Healthineers anchors hospital relationships through direct field-service teams embedded at major radiotherapy centers. Varian Medical Systems occupies a position exemplifying the integrated workflow archetype, controlling simulation-to-delivery pipelines that lock customers into proprietary motion management ecosystems.
| Leading Market Players |
|---|
| Menarini Silicon Biosystems |
| Cell Biolabs, Inc. |
| Thermo Fisher Scientific |
| QIAGEN |
| Genekam |
| Miltenyi Biotec |
| STEMCELL Technologies Inc. |
| Varian Medical Systems, Inc. |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Taiwanese semiconductor foundries supplying electromagnetic sensor arrays and high-speed optical cameras concentrate manufacturing capacity for precision motion detection hardware, translating foundry allocation cycles directly into equipment pricing volatility for radiotherapy OEMs and cancer center procurement teams.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the installed base, with premium tiers capturing bundled software subscriptions and continuous algorithm updates while economy tiers trade calibration-only service contracts. Price differentiation rests on FDA 510(k) clearance status and ISO 13485 certification grade, with validated AI-enhanced platforms commanding substantial premiums over legacy optical configurations. Cost compression in mid-tier electromagnetic systems is intensifying because Japanese METI-subsidized academic deployments are absorbing vendor R&D overhead. Community oncology clinics in Brazil and United States outpatient networks exhibit highest price sensitivity, whereas German university hospitals and Japanese precision medicine centers prioritize clinical validation depth over procurement cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Taiwanese and Japanese component suppliers are stabilizing working capital for electromagnetic tracking OEMs facing hospital procurement delays. Hardware fabrication draws from Taiwan, Japan, and Germany, with sensor arrays sourced from Nagoya-Tokyo corridor facilities, optical cameras from German precision optics clusters, and semiconductor substrates from Taiwanese foundries. Raw material dependencies span rare-earth magnetic alloys, high-purity optical glass, and radiation-hardened ASICs. Single-source vulnerability concentrates in Taiwanese semiconductor allocation cycles triggered by competing consumer electronics demand. Distribution runs through direct field-service teams embedded at major radiotherapy centers, supplemented by refurbished equipment channels penetrating price-sensitive Brazilian and United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where proprietary data formats from installed linear accelerators are forcing middleware development investments, with interoperability emerging as the decisive competitive moat.
For Market Incumbents: Insulate installed base loyalty by embedding field-service teams deeper into hospital physics departments and accelerating backward integration into sensor array manufacturing to secure Taiwanese foundry allocation priority. Defend against software-native entrants by consolidating algorithm update subscriptions into multi-year hospital service contracts that increase switching costs. FDA software-as-a-medical-device reclassification threats demand preemptive clinical outcome study investment to maintain clearance velocity. For New Entrants and Emerging Players: Build out direct-to-hospital software subscription models bypassing traditional capital equipment leasing channels, targeting mid-tier United States community oncology clinics and Brazilian private radiotherapy networks with modular electromagnetic tracking upgrades. São Paulo's Jardins and Moema districts offer the most penetrable geography following ANVISA regulatory harmonization. Lead with algorithm transparency and publication rights to differentiate from incumbent proprietary ecosystems. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because software maintenance contracts and analytics subscriptions are displacing one-time equipment sales as the dominant margin pool. Target acquisition profiles center on software-native vendors with validated markerless electromagnetic algorithms and established hospital data integration. Watch FDA software-as-a-medical-device guidance finalization as the critical signal for validation burden inflection and vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-a-Medical-Device FDA Submission | AI-enhanced tracking algorithms require clinical outcome studies under evolving guidance timelines. |
| EU MDR Conformity Assessment Pathway | Early-compliant vendors lock multi-year German hospital service contracts ahead of competitor validation. |
| Academic Medical Center Partnership | Heidelberg and Tokyo hospitals negotiate publication rights and algorithm transparency as contract terms. |
| Refurbished Equipment Channel Expansion | ANVISA-harmonized Brazilian procurement opens São Paulo private oncology networks to cost-competitive entry. |
| Real-Time MRI Integration Development | Siemens Healthineers and Varian compete to merge electromagnetic tracking with direct tumor visualization. |
Research Approach
Operator-level perspectives from radiation oncology physicists, hospital purchasing committee chairs, biomedical engineers commissioning electromagnetic tracking systems, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) clearance databases, EU MDR conformity assessment records, hospital procurement databases, and CMS Medicare reimbursement filings. Bottom-up equipment unit economics triangulated against top-down cancer center capital expenditure patterns.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling volume and value through segmentation across product modality, clinical application, technology architecture, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, reimbursement code expansion trajectories, and algorithm validation timeline assumptions. Forecast inputs incorporated METI precision medicine subsidy absorption rates and ANVISA regulatory harmonization implementation pace.
Sensitivities concentrate around FDA software-as-a-medical-device guidance finalization, Taiwanese foundry allocation disruption, and EU AI Act risk classification enforcement. Forecasts reflect documented assumptions on algorithm clinical validation success rates and hospital procurement consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Global 3D Printed Surgical Models Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
Middle East and Africa Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Airway Management Devices Market
Medical Devices
Wireless Breast Pump Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Soft Tissue Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Europe Medical Devices Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Corneal Implants Market