
 Japan Electric Wheelchair Market | 2026-2036
Japan Electric Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Electric Wheelchair Market Insights
A widening capability gap in motor and controller manufacturing is reorganizing competitive tiers within the Japan electric wheelchair landscape. Yamaha Motor leverages its precision drivetrain heritage to dominate high-torque outdoor mobility platforms. WHILL Inc. differentiates through sleek mechatronic design and omnidirectional wheel technology that commands premium positioning in compact urban segments. Matsunaga Manufactory sustains its presence via specialized rehabilitation configurations tailored to Japanese clinical protocols.
Japan electric wheelchairs are battery-powered mobility devices incorporating brushless DC motors, programmable controllers, and lithium-ion or gel cell power systems designed to transport users with limited ambulatory function across indoor and outdoor environments. Frame construction typically employs aluminum alloys or carbon fiber composites to balance structural integrity against transport weight for caregivers and institutional handlers. Foldable and compact product types lead unit shipments due to Japan's constrained residential dimensions and narrow transit infrastructure, while heavy-duty configurations capture concentrated margin pools from bariatric rehabilitation clients. Lithium-ion battery technology displaces legacy lead-acid systems fastest among institutional purchasers seeking reduced maintenance cycles and extended duty periods.
PMDA medical device classification requirements and JIS standards for electric wheelchairs govern product safety, electromagnetic compatibility, and clinical efficacy thresholds for market authorization within Japan. METI's subsidy frameworks for welfare equipment procurement directly shape municipal purchasing patterns and reimbursement accessibility for elderly users. Stakeholders must monitor evolving battery recycling mandates under Japan's Home Appliance Recycling Law and anticipate how stricter PMDA software validation rules for smart controller firmware will reshape development timelines and compliance costs.
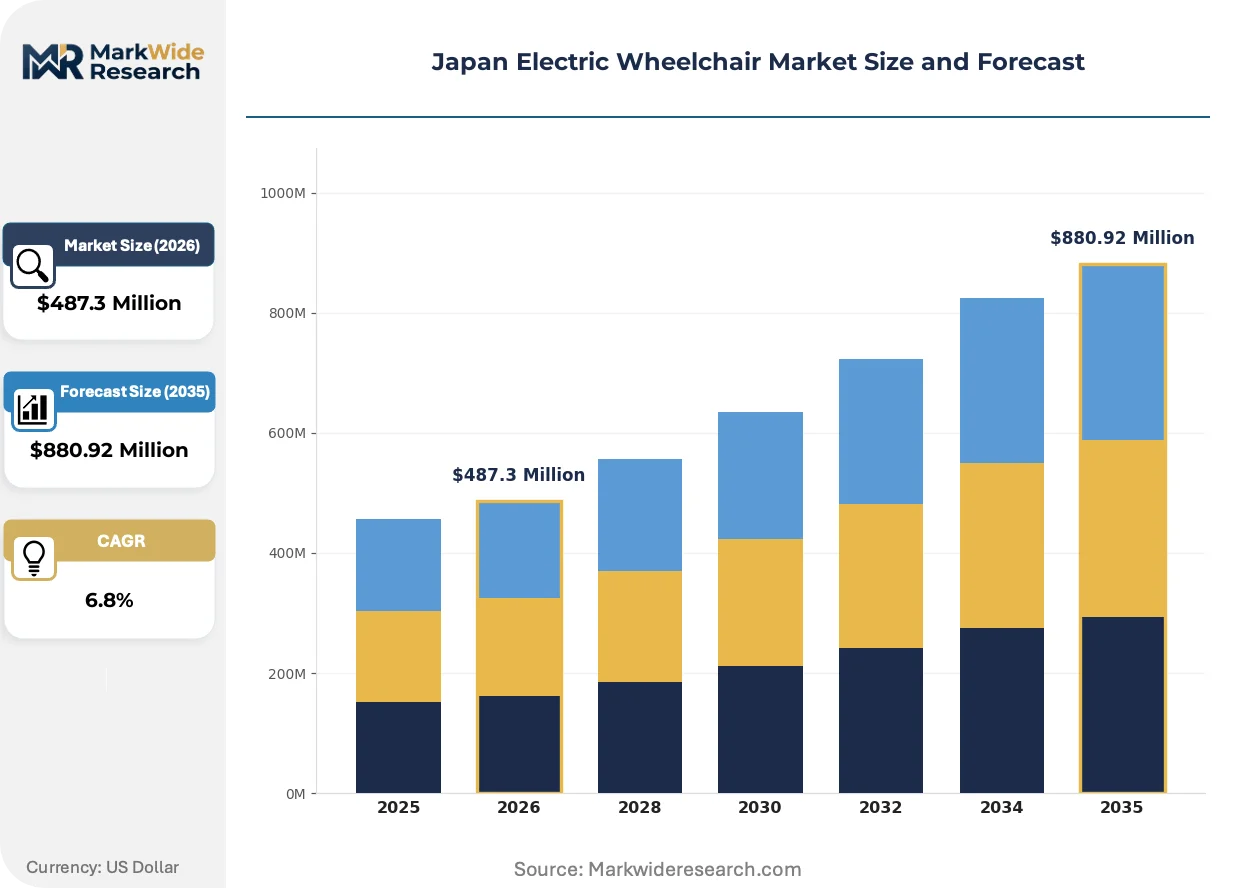
Market Dynamics
METI's robotics integration standards are compressing development timelines while elevating controller firmware complexity, forcing manufacturers to reallocate R&D resources toward software validation and away from hardware iteration cycles.
Growth Catalysts
- Osaka Prefecture elderly care procurement:Municipal welfare equipment subsidies from METI are accelerating fleet replacement schedules across assisted living facilities.
- Lithium-ion battery chemistry:Reduced maintenance cycles and extended duty periods are pulling institutional purchasers away from legacy lead-acid systems.
- JIS electromagnetic compatibility standards:Harmonized testing protocols are lowering certification barriers for domestic manufacturers seeking rapid product iteration.
Market Restraints
- Controller semiconductor supply:Concentrated sourcing from East Asian foundries creates vulnerability in programmable motor driver availability.
- PMDA software validation timelines:Extended firmware review periods for smart wheelchair controllers are delaying product launches by 8-14 months.
- Carbon fiber composite costs:Lightweight frame materials remain priced at 3-4x aluminum alloy equivalents, limiting adoption in economy-tier configurations.
Strategic Opportunities
- Nagoya metropolitan rehabilitation corridor:Underpenetrated bariatric mobility demand in central Japan presents margin expansion potential for heavy-duty platform specialists.
- Home Appliance Recycling Law battery mandates:Forward-integrated recycling infrastructure investments will capture value from end-of-life lithium-ion packs.
- Omnidirectional wheel convergence:Integration of mechatronic steering with compact foldable frames opens premium positioning in Tokyo's constrained residential segments.
Industry Challenges
- Embedded systems firmware talent:Scarce controller programming expertise in brushless DC motor management is extending development cycles.
- Clinical protocol customization:Matsunaga Manufactory's specialized rehabilitation configurations have created de facto standards that new entrants must reverse-engineer.
- Legacy facility infrastructure:Narrow doorways and non-elevator buildings in Japan's aging housing stock limit deployable product specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Electric Wheelchair Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable, Powered, Heavy-Duty, Compact Battery Type: Lithium-Ion, Gel Cell, Lead-Acid, Nickel-Metal Hydride Usage Purpose: Indoor Mobility, Outdoor Mobility, Rehabilitation Support, Daily Activities Target User: Elderly, Disabled, Post-Surgery Patients, Rehabilitation Clients |
| Companies Covered | Invacare Corporation, Permobil AB, Pride Mobility Products Corp., Sunrise Medical LLC, Drive DeVilbiss Healthcare, Ottobock SE & Co. KGaA, Yamaha Motor Co., Ltd., Matsunaga Manufactory Co., Ltd., WHILL Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Electric Wheelchair Market Trends and Innovations
Controller architecture is splitting into divergent development paths as manufacturers weigh premium smart functionality against cost-engineered reliability for institutional bulk procurement.
Brushless DC motor controller firmware is bifurcating into two development streams. High-end platforms integrate real-time terrain adaptation and smartphone connectivity for urban premium users. Economy-tier controllers prioritize fault tolerance and field-serviceability for Osaka and Yokohama nursing home fleets. This technical divergence is compressing mid-market positioning as buyers polarize toward capability extremes.
PMDA's pending software validation rules for assistive device firmware are tightening electromagnetic compatibility documentation requirements. Manufacturers must submit expanded clinical efficacy data for controller updates. Rehabilitation centers in Tokyo Prefecture are delaying procurement decisions until regulatory clarity emerges, creating temporary demand pauses.
Municipal purchasing departments are consolidating wheelchair procurement through METI-subsidized welfare equipment frameworks. Individual retail channels face margin compression as Tokyo, Nagoya, and Yokohama authorities negotiate volume-based pricing. Direct manufacturer relationships with prefectural health bureaus are displacing traditional medical device distributors in institutional segments.
Japan Electric Wheelchair Market Segmentation
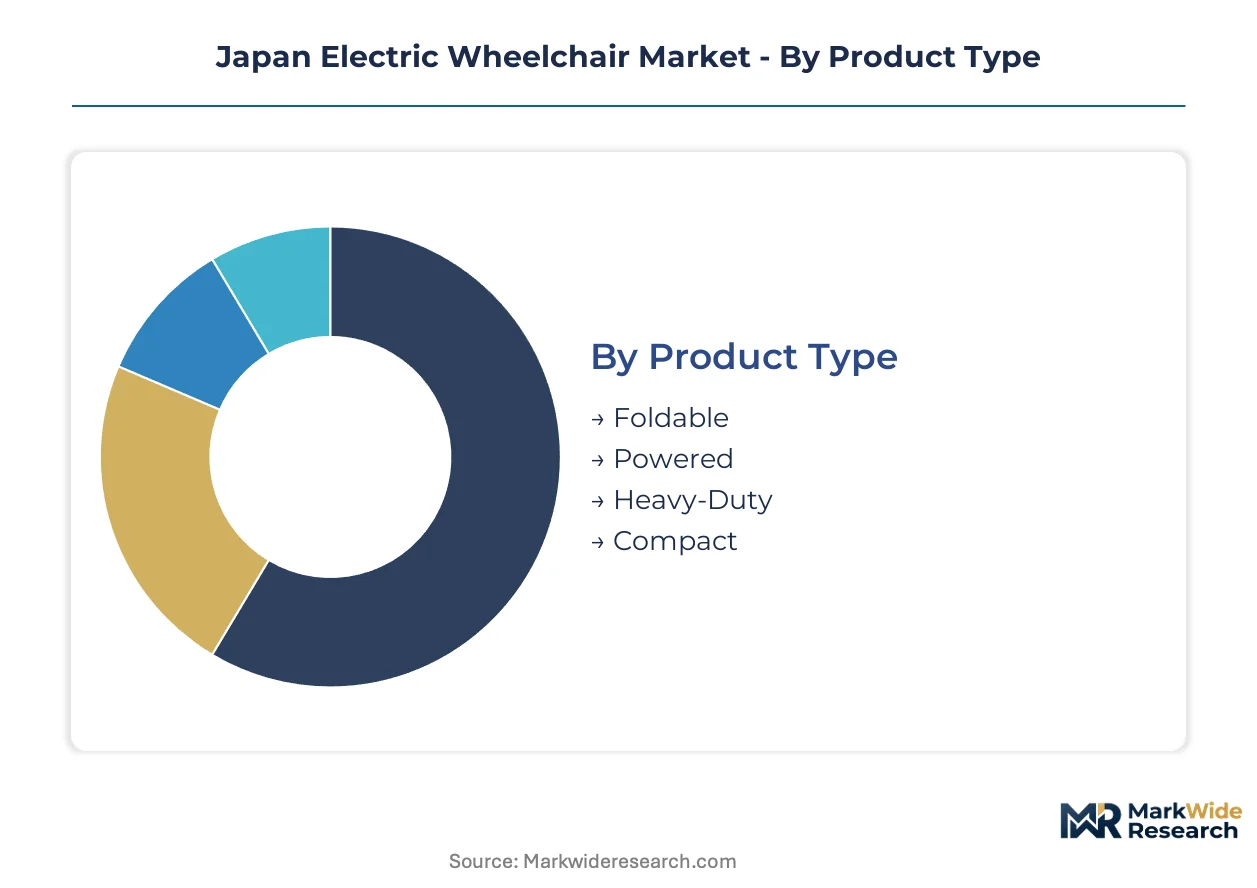
Japan's electric wheelchair market fragments across four critical dimensions that determine procurement channels, reimbursement pathways, and technical specifications. Municipal welfare frameworks prioritize certain configurations over others, while clinical rehabilitation protocols impose distinct performance requirements. Understanding these segment boundaries enables manufacturers to align product development with institutional purchasing workflows and METI subsidy eligibility criteria.
Product Type:
Channel distribution varies sharply across product architectures, with institutional bulk procurement favoring standardized foldable units while premium urban retail channels concentrate on compact and powered variants with advanced controller features.
- Foldable:Aluminum alloy frames with collapsible seat mechanisms dominate Osaka and Yokohama nursing home fleet orders. METI welfare equipment subsidies accelerate replacement cycles for institutional handlers seeking reduced storage footprints.
- Powered:Programmable brushless DC motor systems with joystick or sip-and-puff interfaces command premium positioning in Tokyo metropolitan rehabilitation centers. Real-time terrain adaptation firmware attracts urban users navigating varied sidewalk conditions.
- Heavy-Duty:Reinforced carbon steel or aluminum construction supports bariatric weight ratings for specialized clinical applications in Nagoya corridor facilities.
- Compact:Narrow-width frames with tight turning radii address Japan's constrained residential doorways and elevator dimensions.
By volume, Foldable leads. By growth pace, Compact is gaining share fastest among Tokyo apartment dwellers.
Battery Type:
Cost tier stratification separates lithium-ion premium positioning from legacy chemistry economy configurations, with institutional purchasers weighing total lifecycle costs against upfront procurement budgets.
- Lithium-Ion:High energy density cells with integrated battery management systems deliver extended duty periods for Osaka Prefecture elderly care facilities. Reduced maintenance cycles and faster recharge times offset higher initial acquisition costs under METI subsidy frameworks.
- Gel Cell:Sealed lead-acid variants with spill-proof electrolyte suspension retain presence in budget-constrained municipal procurement where capital expenditure limits override operational efficiency priorities.
- Lead-Acid:Flooded cell technology persists in legacy fleet replacements where procurement departments prioritize lowest unit cost.
- Nickel-Metal Hydride:Intermediate energy density chemistry occupies niche positioning between lithium-ion performance and lead-acid economy tiers.
By volume, Gel Cell maintains institutional share. By technology transition velocity, Lithium-Ion is expanding most quickly among forward-integrated purchasers.
Usage Purpose:
Application-specific engineering requirements drive controller firmware specialization, with rehabilitation protocols demanding distinct motion profiles from daily activity configurations.
- Indoor Mobility:Low-speed precision controllers with tight turning algorithms optimize navigation within Japan's narrow residential corridors and standard 800mm doorways. Matsunaga Manufactory's clinical protocol integrations shape de facto performance benchmarks.
- Outdoor Mobility:High-torque drivetrains with terrain-adaptive suspension address sidewalk irregularities and curb transitions across Tokyo, Yokohama, and Nagoya metropolitan corridors. Yamaha Motor's precision engineering heritage dominates this specification tier.
- Rehabilitation Support:Clinician-programmable motion parameters with session data logging enable therapeutic progress tracking in institutional settings.
- Daily Activities:General-purpose configurations balance indoor maneuverability against limited outdoor capability for mixed-use residential deployment.
By installed base, Indoor Mobility leads. By reimbursement expansion, Rehabilitation Support shows steepest trajectory as clinical efficacy documentation strengthens.
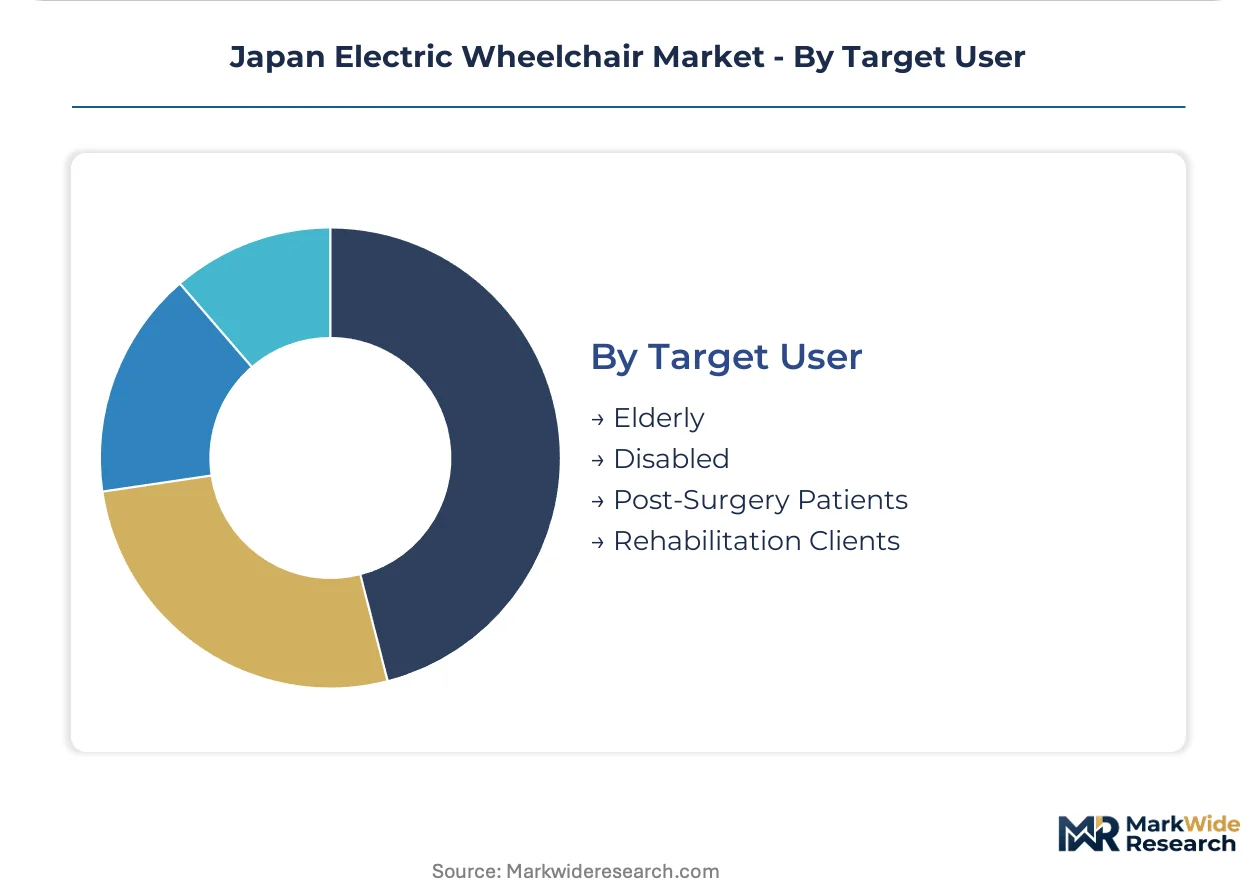
Target User:
Customer type segmentation aligns with Japan's demographic structure and healthcare infrastructure, with elderly users representing volume concentration while post-surgery patients drive premium feature adoption.
- Elderly:Japan's aging population demographic—concentrated in Tokyo, Osaka, and Aichi prefectures—generates sustained institutional and retail demand for mobility preservation solutions. METI welfare equipment subsidies directly reduce out-of-pocket acquisition barriers.
- Disabled:Permanent mobility impairment users require customized controller interfaces and seating configurations tailored to specific functional limitations.
- Post-Surgery Patients:Temporary rehabilitation clients in acute care and sub-acute facilities drive demand for rental and short-term lease configurations with rapid adjustability.
- Rehabilitation Clients:Long-term therapeutic users in outpatient and day-care settings require durable platforms with clinical protocol compatibility.
By population served, Elderly dominates unit demand. By feature intensity per user, Post-Surgery Patients generate highest controller customization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's electric wheelchair trade balance tilts toward domestic manufacturing self-sufficiency, with limited export orientation but substantial inbound technology licensing from European and North American mobility specialists. Prefectural welfare procurement frameworks create localized demand clusters that concentrate equipment deployment in metropolitan corridors.
Kanto/Tokyo
Tokyo Prefecture's dense rehabilitation center network drives premium compact wheelchair specifications for constrained residential environments. METI welfare equipment subsidies reduce out-of-pocket costs for elderly users in Shinjuku and Setagaya wards. The Tokyo metropolitan corridor anchors national demand for omnidirectional wheel technology in high-rise apartment settings.
Kansai/Osaka
Osaka Prefecture's elderly care facilities generate institutional bulk procurement volumes exceeding other western Japan regions. Municipal welfare departments accelerate fleet replacement schedules through subsidized welfare equipment frameworks. The Osaka-Kobe corridor concentrates bariatric rehabilitation demand in specialized clinical settings.
Chubu/Nagoya
Aichi Prefecture's automotive manufacturing heritage supplies precision motor and controller components to domestic wheelchair assemblers. Nagoya metropolitan rehabilitation centers present underpenetrated demand for heavy-duty mobility platforms. The Toyota-Nagoya industrial zone enables just-in-time component logistics for regional manufacturers.
Kyushu
Fukuoka Prefecture's aging demographic profile matches national welfare equipment subsidy eligibility thresholds. Municipal health bureaus in Kitakyushu and Kumamoto consolidate procurement through METI-subsidized frameworks. Kyushu's legacy housing stock with narrow doorways limits deployable product specifications to compact frame configurations.
Hokkaido
Hokkaido's dispersed rural population creates logistical challenges for wheelchair service and maintenance infrastructure. Sapporo municipal authorities negotiate volume-based pricing with manufacturers for institutional fleet deployment. Cold climate battery performance requirements drive specification differentiation for northern Japan deployments.
Japan Electric Wheelchair Market Competitive Landscape
Concentration sits with diversified precision engineering conglomerates and specialized rehabilitation equipment fabricators. The vendor base splits between multinational mobility specialists with established distribution networks and domestic manufacturers leveraging clinical protocol relationships. Two strategic archetypes dominate: drivetrain engineering heritage players and mechatronic design innovators. Competitive moves center on firmware development partnerships and prefectural health bureau direct contracting relationships.
Among multinational mobility specialists, Invacare Corporation and Permobil AB represent established archetypes with institutional distribution infrastructure. Within the domestic tier, Yamaha Motor Co., Ltd. exemplifies precision engineering heritage applied to high-torque outdoor platforms, while WHILL Inc. occupies a position in premium compact urban segments through mechatronic differentiation. Matsunaga Manufactory Co., Ltd. anchors specialized rehabilitation configurations tailored to Japanese clinical protocols.
| Leading Market Players |
|---|
| Invacare Corporation |
| Permobil AB |
| Pride Mobility Products Corp. |
| Sunrise Medical LLC |
| Drive DeVilbiss Healthcare |
| Ottobock SE & Co. KGaA |
| Yamaha Motor Co., Ltd. |
| Matsunaga Manufactory Co., Ltd. |
| WHILL Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day controller semiconductor lead times from East Asian foundries compress margin buffers for Japanese assemblers while amplifying pricing power for integrated drivetrain specialists with captive component stocks. This inventory pressure concentrates procurement leverage among Yamaha Motor and WHILL Inc., forcing smaller fabricators toward standardized controller architectures with reduced customization premiums.
Pricing Analysis
The customization-premium spread separates Matsunaga Manufactory's clinician-configured rehabilitation platforms from Osaka nursing home fleet orders. Three-tier pricing structure across premium, standard, and economy levels reflects controller firmware complexity and battery chemistry grade. Cost compression in economy-tier foldable units intensifies as METI volume subsidies consolidate municipal purchasing. Institutional procurement departments exhibit highest price sensitivity, while Tokyo metropolitan rehabilitation centers absorb premium positioning for compact omnidirectional configurations.
Supply Chain Analysis
The Taiwan Strait transit route for controller semiconductors constitutes a critical chokepoint for programmable motor driver availability across Japanese assembly lines. Component sourcing draws from Taiwan, South Korea, and China for brushless DC controllers, lithium-ion cells, and carbon fiber prepregs. Single-source vulnerability in 32-bit motor control microprocessors exposes manufacturers to foundry allocation disruptions. Distribution runs through METI-subsidized welfare equipment frameworks that displace traditional medical device distributors in prefectural procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
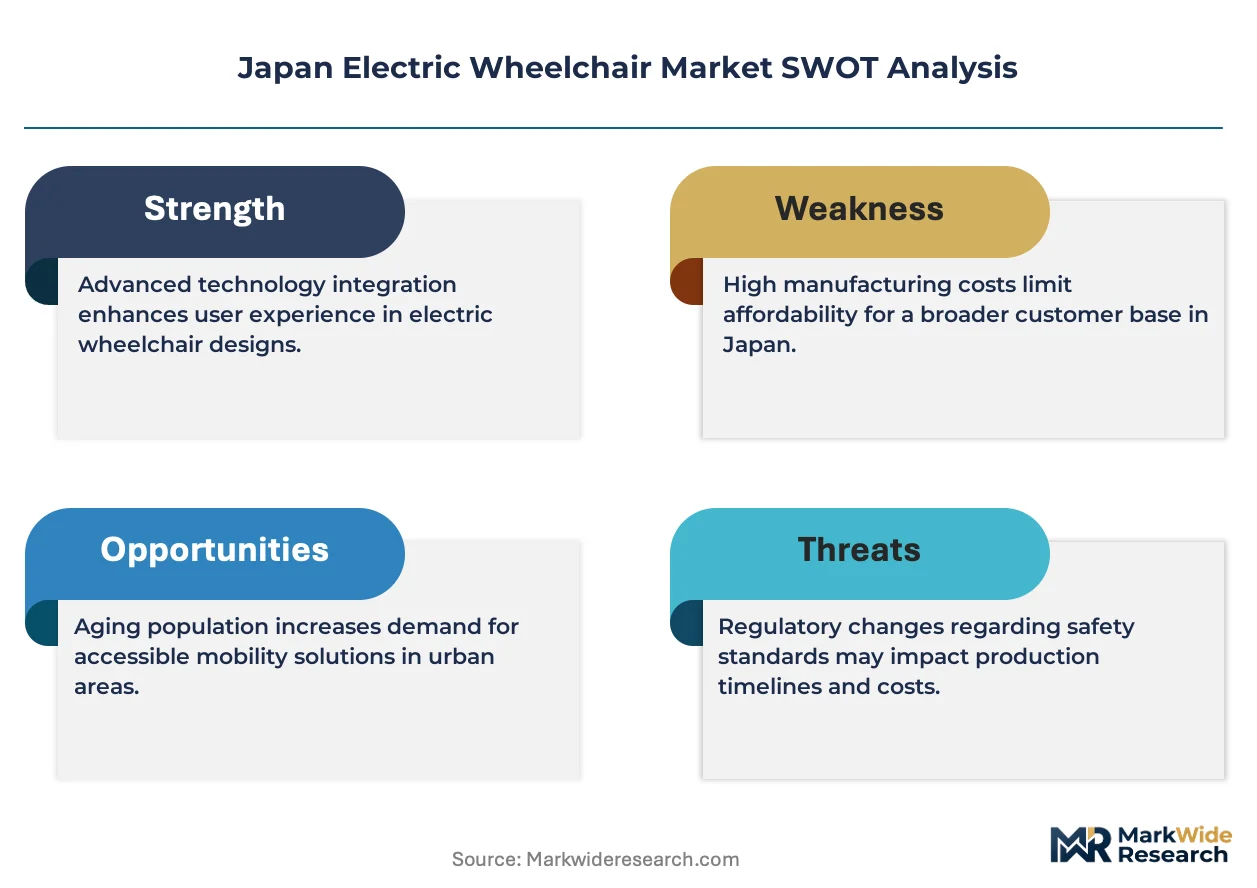
This market functions as a defensive-moat story anchored in regulatory entrenchment. PMDA software validation timelines and METI subsidy eligibility criteria erect structural barriers that favor incumbents with established prefectural health bureau relationships.
For Market Incumbents: Shield firmware development partnerships against emerging Chinese controller suppliers by deepening clinical protocol integrations with Nagoya and Osaka rehabilitation centers. Secure lithium-ion cell supply through backward integration into battery pack assembly or long-term offtake agreements with South Korean chemistry specialists. METI's pending robotics integration standards threaten to obsolete legacy controller architectures without real-time terrain adaptation capabilities. For New Entrants and Emerging Players: Differentiate on compact omnidirectional wheel convergence for Tokyo's high-rise residential segments where WHILL Inc. has established premium positioning but volume penetration remains incomplete. Target underpenetrated bariatric rehabilitation demand in the Nagoya metropolitan corridor where heavy-duty platform specialization commands margin expansion. Pursue direct contracting relationships with Aichi Prefecture municipal health bureaus rather than distributor intermediaries. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-utility play because Japan's elderly population concentration generates sustained replacement demand regardless of macroeconomic cycles. Acquisition targets should display integrated controller firmware capabilities and established METI subsidy qualification histories. Monitor PMDA software validation rule finalization as the signal for regulatory compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software Validation Pathway | Accelerated firmware review timelines compress competitive entry windows for smart controller platforms. |
| Prefectural Health Bureau Partnership | Direct METI welfare equipment contracting displaces distributor intermediaries in institutional procurement. |
| Lithium-Ion Battery Supply Agreement | Long-term cell offtake secures energy density advantages for extended-duty institutional configurations. |
| Omnidirectional Wheel Technology Licensing | Mechatronic steering IP unlocks premium positioning in Tokyo's constrained residential segments. |
| Clinical Protocol Integration Program | Matsunaga-compatible rehabilitation configurations establish de facto standards for therapeutic motion parameters. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of METI welfare equipment procurement databases, PMDA medical device registration filings, and JIS standards documentation. Interviews with rehabilitation center biomedical engineers, prefectural health bureau procurement officers, electric wheelchair distributor operations heads, and lithium-ion battery supply specialists informed demand-side validation. Top-down macroeconomic indicators and bottom-up unit shipment data triangulate market size estimates.
Segmentation dimensions modeled include product architecture, battery chemistry, usage purpose, and target user demographic across the analysis window. CAGRs derive from regression analysis against elderly population projections, METI subsidy allocation trends, and lithium-ion battery cost curves. Forecast inputs incorporate PMDA software validation timeline assumptions and carbon fiber composite price elasticity for lightweight frame materials.
The analysis sits within stated boundaries; outcomes outside current METI subsidy continuity and PMDA regulatory trajectory would require recalibration. Forecasts reflect documented assumptions regarding institutional procurement consolidation velocity and semiconductor supply normalization. Practitioners should keep alternative scenarios live as robotics integration standards and battery recycling mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cervical Disc Prosthesis Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Skull Clamp Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Global Aneurysm Clips Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Brachytherapy Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Ocular Adhesive Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Ankle Mobile Bearing System Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Airway Management Tubes Market