
 Software As a Medical Device Market | 2026-2036
Software As a Medical Device Market Size, Share, and Industry Trends Forecast 2026-2036
Software As a Medical Device Market Insights
Subscription-based financing and asset-light deployment models is rewriting competitive entry barriers for smaller algorithm developers. Viz.ai leverages cloud-native architecture to reduce upfront infrastructure costs for hospital buyers. Siemens Healthcare anchors its position through embedded systems integration with existing imaging hardware. Philips differentiates by controlling end-to-end regulatory compliance services alongside its software platforms.
Software as a Medical Device encompasses standalone applications intended to perform medical purposes without being part of a hardware medical device, typically operating through artificial intelligence algorithms, mobile interfaces, or cloud-based analytics to diagnose, treat, or monitor patients. These systems process patient data through validated computational models to generate clinically actionable outputs for healthcare providers. Diagnostic applications currently occupy the largest revenue pool within product type segments, while artificial intelligence within technology segments commands the fastest expansion trajectory as clinical validation frameworks mature. Remote patient monitoring in delivery mode segments is attracting disproportionate R&D investment following pandemic-era infrastructure buildouts.
FDA pre-certification programs and EU MDR software classification rules are tightening quality management requirements, forcing developers to rebuild documentation protocols before market authorization. China's NMPA has issued dedicated AI medical device review guidelines that create parallel but distinct compliance pathways from Western frameworks. Stakeholders must monitor divergence between regional validation standards to avoid redundant clinical studies that fragment commercial timelines.
Market Dynamics
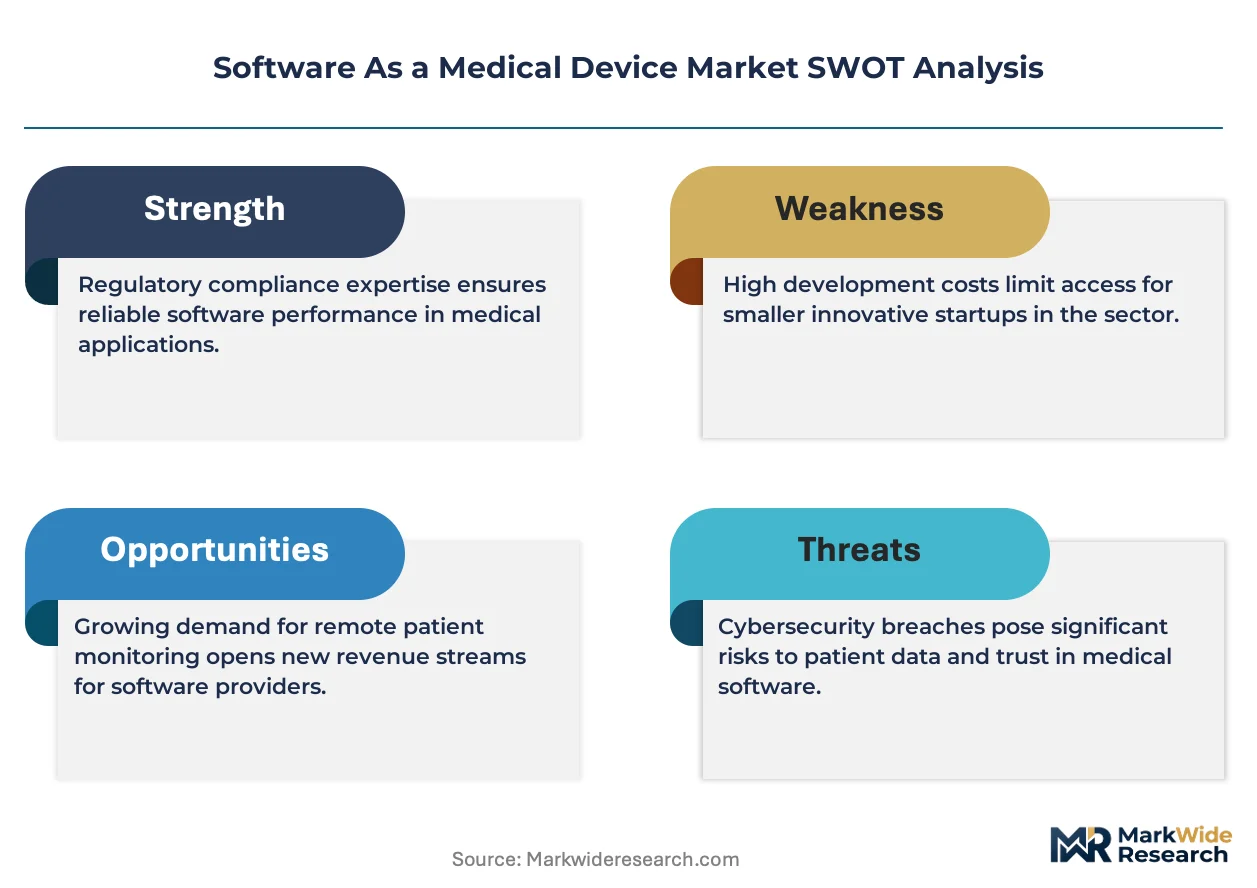
FDA pre-certification pathways and EU MDR software classification rules are forcing algorithm developers to rebuild quality management documentation before commercial authorization, compressing timelines for market entry.
Growth Catalysts
- Cloud-native deployment:Hospital systems in the United States are prioritizing asset-light infrastructure that reduces capital expenditure for AI diagnostic tools. This procurement preference accelerates vendor onboarding cycles.
- NMPA AI review guidelines:China's dedicated regulatory pathway for algorithm-based medical devices creates distinct but navigable compliance frameworks. Developers leveraging these guidelines gain parallel market access.
- Reimbursement maturation:Germany's digital therapeutics reimbursement catalog is expanding coverage categories for standalone diagnostic software. This policy shift validates revenue models for prescription-grade applications.
Market Restraints
- Clinical validation costs:Multi-site prospective studies required by FDA pre-certification programs impose seven-figure expenditure burdens on pre-revenue developers. This capital intensity filters market participants.
- Regulatory fragmentation:Divergent validation standards between FDA, EMA, and NMPA force redundant clinical evidence generation. Timeline extension from parallel compliance pathways delays commercialization.
- Legacy system integration:Hospital IT infrastructure heterogeneity creates technical friction for standalone software deployment. Interoperability requirements with existing PACS and EHR systems extend implementation cycles.
Strategic Opportunities
- Rural health networks:Underserved regions in India present whitespace for teleradiology algorithms that bypass specialist shortage constraints. Distribution through national telemedicine infrastructure reduces customer acquisition costs.
- EU AI Act alignment:Early compliance with risk-classification requirements for high-risk medical AI creates competitive moats. Developers embedding conformity assessment procedures capture premium positioning.
- Edge computing convergence:Hybrid architectures combining cloud analytics with on-device inference address latency-sensitive emergency applications. This technology pairing opens trauma and surgical navigation segments.
Industry Challenges
- Regulatory science talent scarcity:Qualified professionals capable of navigating FDA Q-Sub meetings and EU notified body interactions command premium compensation. Recruitment competition with pharmaceutical firms constrains scaling.
- Algorithm drift monitoring:Continuous validation requirements for machine learning-based devices demand post-market surveillance infrastructure. Building these capabilities diverts engineering resources from product development.
- Health system procurement consolidation:Centralized purchasing decisions by integrated delivery networks compress vendor margins and extend sales cycles. Smaller developers face exclusion from qualified supplier lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software As a Medical Device Market |
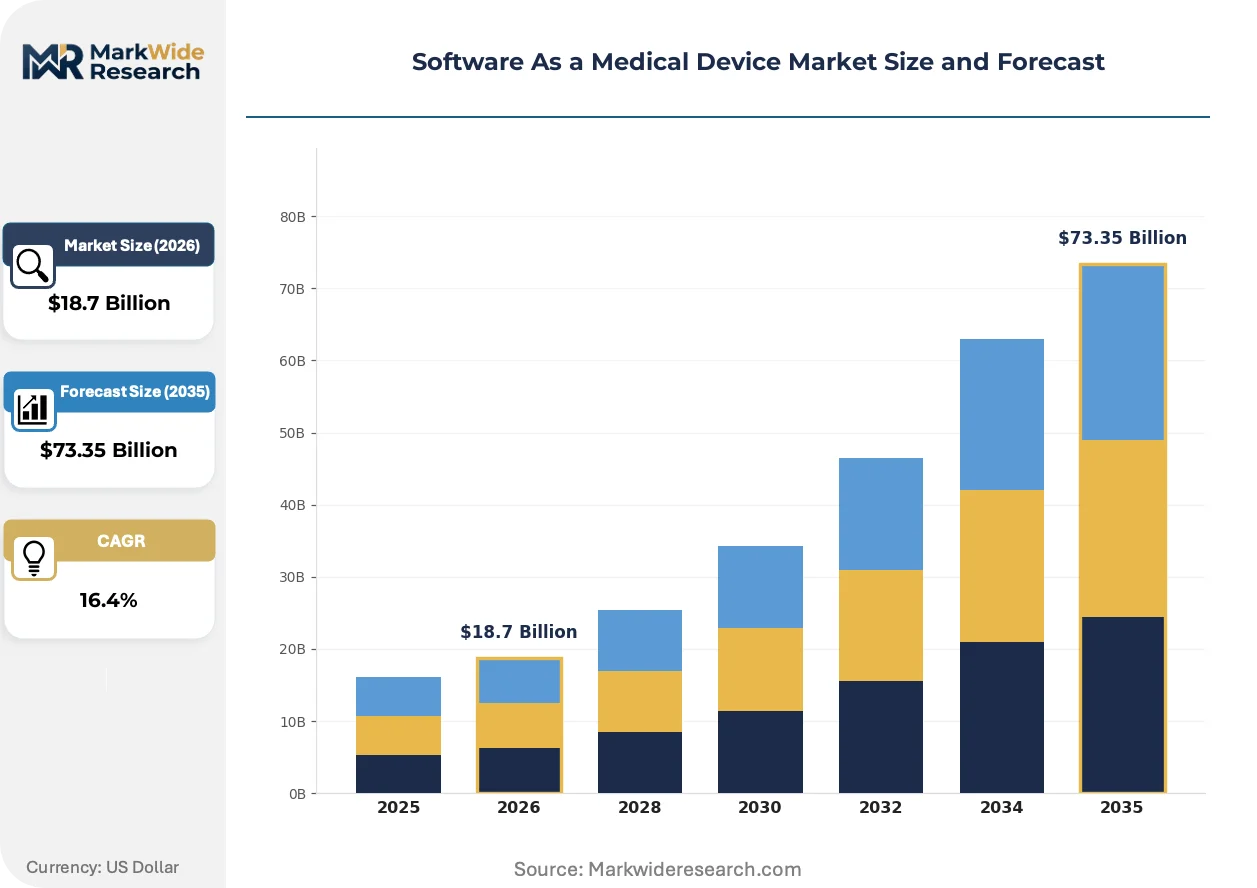
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic, Therapeutic, Monitoring, Imaging Technology: Artificial Intelligence, Cloud Computing, Mobile Applications, Embedded Systems Delivery Mode: Remote Patient Monitoring, In-Hospital Use, Home Use, Standalone Systems End User: Clinics, Hospitals, Medical Laboratories, Home Care Providers |
| Companies Covered | Medtronic, Siemens Healthcare, Philips, GE Healthcare, Roche, Viz.ai, Digital Diagnostics, Arterys, BrightInsight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software As a Medical Device Market Trends and Innovations
Computational architectures and regulatory frameworks are converging to redefine how diagnostic algorithms achieve clinical deployment and economic sustainability.
Multimodal AI systems are hybridizing computer vision with natural language processing to generate integrated diagnostic reports from imaging studies and electronic health records simultaneously. Radiology departments in academic medical centers are piloting these platforms for emergency stroke triage. This convergence is compressing the gap between image acquisition and actionable clinical output.
EU MDR software classification rules are tightening quality management system requirements for standalone diagnostic applications. Manufacturers must now demonstrate clinical evidence proportional to risk classification across all intended use populations. Cardiology monitoring applications face the steepest documentation burdens as notified bodies apply stricter scrutiny to algorithm-based arrhythmia detection.
Hospital procurement committees are consolidating vendor evaluation around cybersecurity certification and liability insurance coverage rather than algorithm accuracy metrics alone. This behavioral shift elevates established enterprise software providers over specialized algorithm developers. The United States exhibits the most pronounced preference consolidation as health system breach exposure drives risk-averse selection criteria.
Software As a Medical Device Market Segmentation
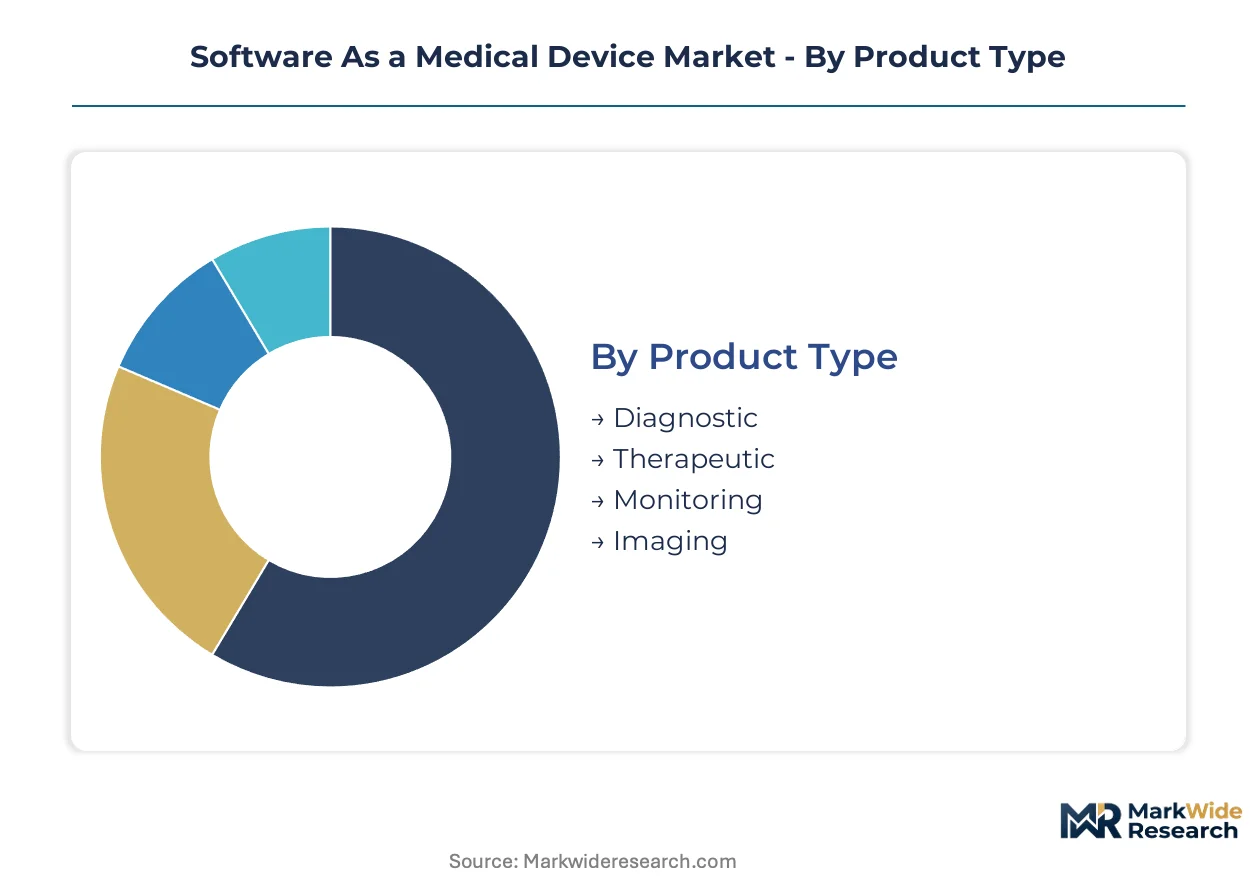
Software as a Medical Device classification determines regulatory pathways, reimbursement eligibility, and integration requirements for algorithm developers. Segmentation by product function, technical architecture, deployment setting, and care setting reveals where capital allocation concentrates and where compliance burdens vary.
Product Type:
Mature diagnostic platforms coexist with emerging therapeutic modalities across hospital procurement portfolios.
- Diagnostic:Algorithms analyzing medical images, laboratory results, or physiological signals to detect disease states. United States health systems prioritize these tools for emergency department triage where specialist availability constrains throughput. FDA pre-certification pathways have compressed authorization timelines for well-validated diagnostic indications.
- Therapeutic:Software delivering personalized treatment protocols or behavioral interventions for chronic conditions. Germany's expanding digital therapeutics reimbursement catalog validates prescription-grade therapeutic applications for diabetes management and cognitive behavioral therapy.
- Monitoring:Continuous physiological tracking systems generating alerts for clinical deterioration. Remote patient monitoring infrastructure buildouts concentrate demand in cardiology and post-surgical recovery applications.
- Imaging:Advanced visualization and reconstruction algorithms enhancing radiological interpretation. Academic medical centers deploy these systems for complex oncology staging and surgical planning workflows.
Diagnostic retains volume leadership; Therapeutic holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive infrastructure plays from asset-light deployment models.
- Artificial Intelligence:Machine learning models trained on clinical datasets to generate predictive or classification outputs. China's NMPA dedicated review guidelines create parallel but distinct compliance pathways from FDA frameworks. Multi-site prospective validation studies impose substantial pre-revenue expenditure burdens.
- Cloud Computing:Scalable infrastructure enabling real-time algorithm deployment without on-premise hardware investment. Hospital procurement committees prioritize these architectures to reduce capital expenditure and accelerate vendor onboarding cycles.
- Mobile Applications:Patient-facing interfaces for symptom tracking, medication adherence, or therapeutic content delivery. Home care providers leverage these tools to extend care team reach without proportional staffing increases.
- Embedded Systems:Software integrated within hardware medical devices for closed-loop control or data processing. Siemens Healthcare anchors market position through deep integration with existing imaging hardware installations.
Cloud Computing commands deployment preference; Artificial Intelligence captures R&D investment concentration.
Delivery Mode:
Application criticality determines latency tolerance and infrastructure requirements across care settings.
- Remote Patient Monitoring:Continuous data transmission from ambulatory patients to centralized clinical teams. Pandemic-era infrastructure buildouts in the United States and Germany have expanded reimbursement coverage for these services.
- In-Hospital Use:Point-of-care algorithms deployed within acute care facilities for real-time decision support. Emergency stroke triage applications demand sub-minute latency that shapes technical architecture choices.
- Home Use:Patient-operated software for chronic disease management or post-discharge surveillance. Medical laboratories distribute these tools to extend testing access beyond physical collection sites.
- Standalone Systems:Self-contained software requiring minimal integration with existing IT infrastructure. Smaller clinics in underserved regions favor these deployments to bypass complex interoperability requirements.
In-Hospital Use dominates current revenue; Remote Patient Monitoring is climbing the fastest.
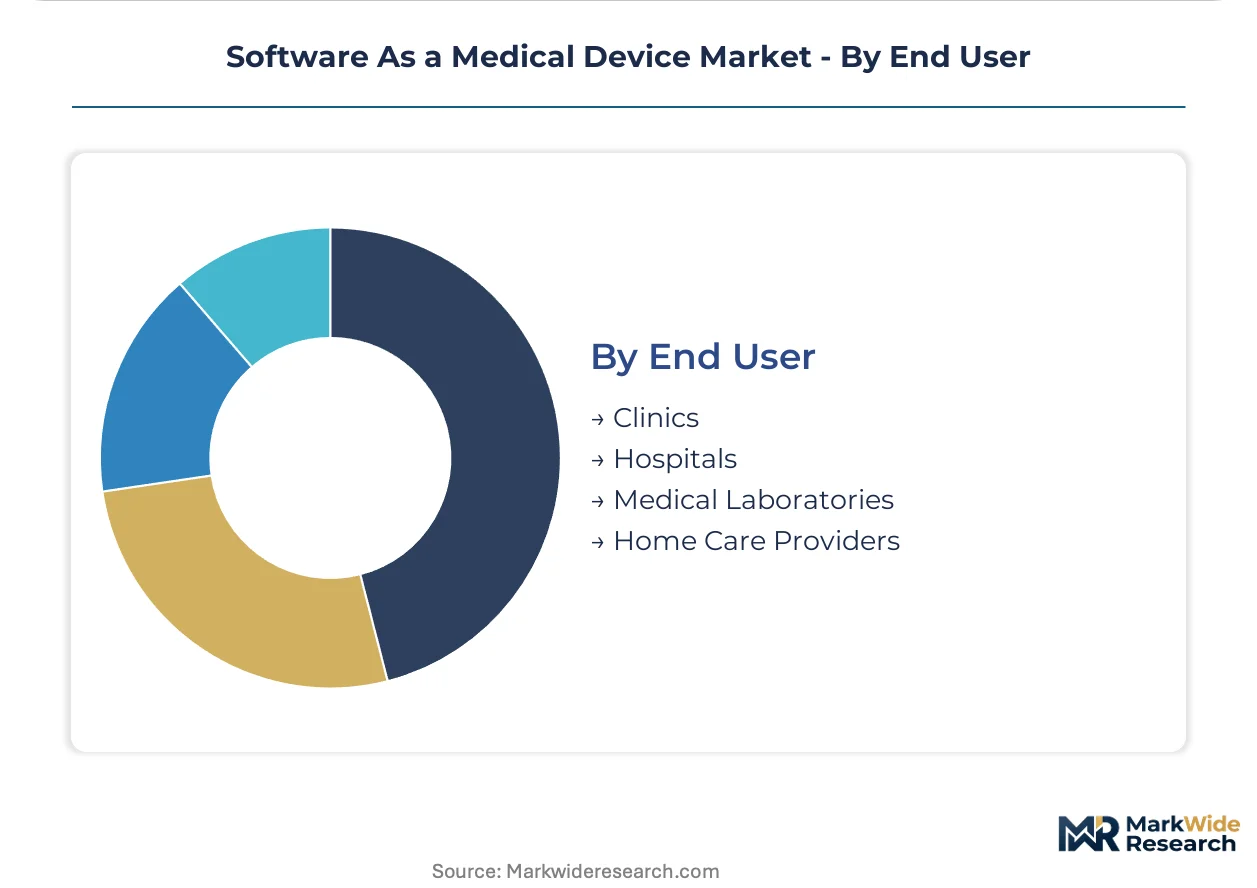
End User:
Customer type dictates purchasing authority, budget cycles, and technical integration complexity.
- Hospitals:Integrated delivery networks with centralized procurement committees evaluating enterprise-scale deployments. Cybersecurity certification and liability insurance coverage have displaced algorithm accuracy as primary selection criteria in the United States.
- Clinics:Outpatient facilities requiring streamlined implementation and lower total cost of ownership. These buyers prioritize standalone systems with minimal IT infrastructure demands.
- Medical Laboratories:Diagnostic service providers embedding software within analytical workflows. These end users demand seamless interoperability with laboratory information systems and electronic health records.
- Home Care Providers:Organizations delivering services in residential settings with distributed workforce models. Mobile application compatibility and offline functionality shape procurement decisions for this segment.
Hospitals anchor procurement volume; Home Care Providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in algorithm-based medical software tilt heavily toward surplus economies with mature regulatory science infrastructure. The United States, Germany, and China generate the bulk of proprietary diagnostic platforms, while import-dependent markets in Southeast Asia and Latin America absorb these technologies through licensing arrangements and cloud-hosted deployments.
United States
FDA pre-certification pathways accelerate commercial timelines for emergency stroke triage algorithms. Hospital procurement committees prioritize cybersecurity certification over raw diagnostic accuracy. Academic medical centers in Boston and Stanford anchor clinical validation studies for multimodal AI systems.
Germany
The digital therapeutics reimbursement catalog validates prescription-grade software for diabetes management and cognitive behavioral therapy. EU MDR software classification rules impose quality management burdens proportional to risk classification. Berlin and Munich host notified body interactions for cardiology monitoring applications.
China
NMPA dedicated AI medical device review guidelines create parallel compliance pathways distinct from FDA frameworks. Multi-site prospective validation studies impose substantial pre-revenue expenditure burdens. Shanghai and Beijing concentrate algorithm development for teleradiology applications targeting rural health networks.
United Kingdom
NHS procurement frameworks favor cloud-native architectures that reduce capital expenditure for integrated delivery networks. MHRA alignment with EU MDR transition timelines creates documentation continuity pressures. London's health tech cluster attracts venture funding for remote patient monitoring platforms.
Japan
PMDA review timelines for machine learning-based devices lag Western regulators, compressing first-mover advantages for domestic developers. METI funding programs subsidize clinical evidence generation for aging-population applications. Osaka and Tokyo medical device clusters prioritize embedded systems integration with existing imaging hardware.
Software As a Medical Device Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying algorithm modules and regulatory compliance services. Market structure concentrates around three to five enterprise-scale vendors with embedded hospital relationships, while dozens of pre-revenue developers compete for niche indications. Two strategic archetypes dominate: cloud-native disruptors leveraging asset-light deployment models, and incumbent device manufacturers extending hardware franchises into software subscriptions. Competitive moves center on strategic partnerships with health systems for real-world evidence generation, and portfolio diversification into adjacent therapeutic areas to amortize regulatory infrastructure costs.
Within the platform integrator tier, Medtronic and Siemens Healthcare occupy positions anchored by embedded systems integration with existing hospital infrastructure. Viz.ai exemplifies the cloud-native archetype, representing the asset-light deployment model that reduces upfront capital expenditure for health system buyers. These three entities span the competitive spectrum from legacy hardware extension to disruptive software-first positioning.
| Leading Market Players |
|---|
| Medtronic |
| Siemens Healthcare |
| Philips |
| GE Healthcare |
| Roche |
| Viz.ai |
| Digital Diagnostics |
| Arterys |
| BrightInsight |
| Others |
Pricing and Supply Chain Analysis
Air freight corridors connecting Frankfurt and Shanghai transmit cost volatility from semiconductor component sourcing directly into subscription pricing tiers for cloud-native diagnostic platforms, concentrating margin pressure on developers lacking embedded hardware partnerships while enabling premium positioning for vertically integrated device manufacturers.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across certification-grade tiers, with FDA-cleared algorithms commanding substantial premiums over CE-marked equivalents in United States markets. Price differentiation rests on cybersecurity certification depth and liability insurance coverage rather than raw diagnostic accuracy metrics. Cost compression in mid-tier SaaS subscriptions is intensifying as integrated delivery networks consolidate vendor lists and demand volume discounts. Small clinic buyers exhibit highest price sensitivity, while academic medical centers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk assessment for machine learning training infrastructure and specialized GPU components. Component sourcing concentrates in Taiwan, South Korea, and United States for semiconductor fabrication, with cloud compute provisioning drawing from hyperscaler data centers across Ireland, Singapore, and Virginia. Regulatory restriction risk emanates from divergent FDA and NMPA validation documentation requirements that fragment commercial timelines. Distribution runs through direct enterprise sales teams supplemented by GPO contracts for health system procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software As a Medical Device represents a high-growth disruption as FDA pre-certification pathways compress commercial timelines and EU MDR software classification rules simultaneously elevate compliance barriers, creating asymmetric opportunity windows for prepared developers.
For Market Incumbents: Build regulatory infrastructure moats by embedding quality management systems that satisfy both FDA Q-Sub requirements and EU notified body expectations simultaneously. Incorporate post-market surveillance capabilities for algorithm drift monitoring to preempt competitive displacement from specialized AI developers. Threat substitution from cloud-native disruptors demands defensive moves into subscription pricing models that match asset-light deployment economics. For New Entrants and Emerging Players: Rural health networks in India present whitespace for teleradiology algorithms that bypass specialist shortage constraints through national telemedicine infrastructure. Target standalone diagnostic applications for small clinics in Latin America where interoperability requirements remain minimal and price sensitivity creates entry points for validated but lower-cost alternatives. Go-to-market execution should leverage channel partnerships with regional distributors possessing existing hospital relationships rather than direct enterprise sales buildout. For Investors and Strategic Acquirers: Pre-revenue developers possessing multi-site prospective validation datasets represent the acquisition archetype with highest strategic optionality across regulatory jurisdictions. Long-term viability assessment over the next decade hinges on ability to amortize clinical evidence generation costs across multiple geographic approvals. Monitor FDA pre-certification program expansion announcements as the critical inflection signal for timeline compression benefits accruing to portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Compresses authorization timelines for validated diagnostic algorithms in emergency stroke triage applications. |
| EU MDR Software Classification | Imposes quality management burdens proportional to risk classification for cardiology monitoring applications. |
| Hospital System Partnership | Generates real-world evidence for algorithm performance across diverse patient populations and clinical settings. |
| Cloud-Native Platform Integration | Reduces upfront capital expenditure for health system buyers and accelerates vendor onboarding cycles. |
| Reimbursement Strategy Development | Validates prescription-grade revenue models through Germany's expanding digital therapeutics catalog coverage. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement records anchors the qualitative findings. Bottom-up triangulation against top-down regulatory pathway analysis ensures segmentation integrity across deployment models and certification tiers.
Calibration against historical authorization timelines and reimbursement adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product function, technical architecture, delivery mode, and end-user type alongside regional regulatory cluster differentiation. CAGRs derive from fitted growth curves incorporating clinical validation pipeline maturity and health system procurement cycle timing.
Practitioners should monitor FDA pre-certification program scope expansion, EU AI Act risk-classification enforcement, and NMPA review guideline updates for early signals of timeline compression or extension. Forecasts reflect assumptions about regulatory science talent availability and health system IT infrastructure standardization that could shift with macroeconomic conditions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Catheter Coatings Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
EEG Amplifiers Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Oxygenator Market
Medical Devices
Organ on a Chip Kit Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Global Microscopy Device Market