
 Primary Aldosteronism Market | 2026-2036
Primary Aldosteronism Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Aldosteronism Market Analytics
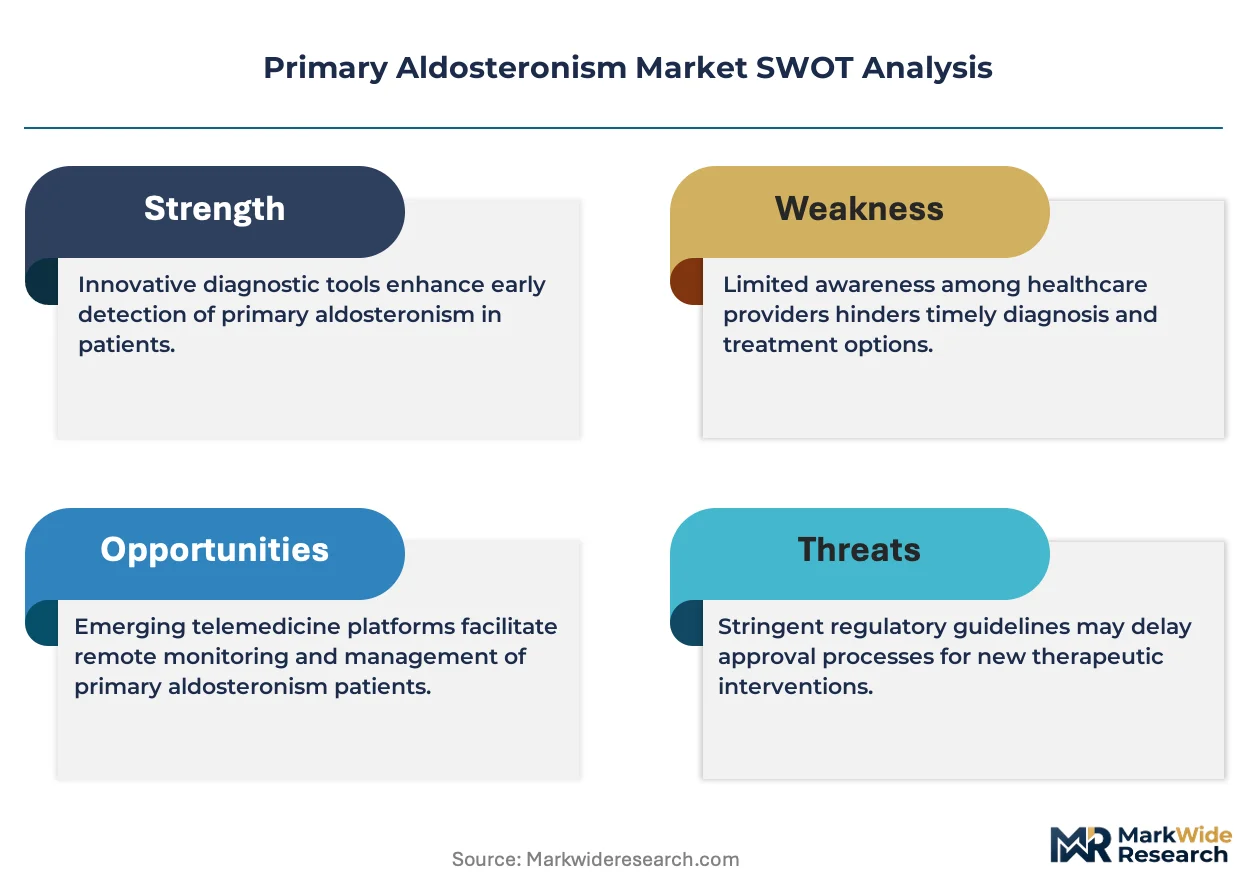
The premium-commodity split in primary aldosteronism care is rebalancing as molecular diagnostics and catheter-based adrenal vein sampling pull away from standard ambulatory renin-aldosterone ratio testing. Novartis AG leverages its mineralocorticoid receptor antagonist portfolio to dominate the branded therapy tier. Pfizer Inc anchors the generic aldosterone antagonist segment through manufacturing scale and hospital formulary penetration.
Primary aldosteronism denotes a group of disorders characterized by autonomous aldosterone hypersecretion from the adrenal cortex, typically quantified through plasma aldosterone concentration exceeding 10 ng/dL with suppressed renin activity. The condition drives resistant hypertension, left ventricular hypertrophy, and chronic kidney injury, making biochemical confirmation and lateralization critical to treatment selection. Aldosterone antagonists command the largest product type share, while the endocrine disorders therapy area grows fastest as screening expands beyond hypertensive populations. Oral delivery mode sustains the dominant position, though injectable formulations gain traction in perioperative adrenal crisis management.
The FDA governs diagnostic assay validation and drug approval pathways for aldosterone-modulating therapies, while the EPA monitors pharmaceutical manufacturing discharge standards affecting active ingredient production economics. Clinical laboratories must adhere to CAP proficiency testing for aldosterone and renin immunoassays to maintain reimbursement eligibility. Stakeholders should monitor how adrenal vein sampling reimbursement policies reshape referral patterns between community hospitals and tertiary centers.
Market Dynamics
Screening protocol expansion at academic medical centers is pulling diagnostic volumes away from community hospitals, restructuring referral economics and catheter-based procedure demand across the care continuum.
Growth Catalysts
- Endocrine Society Guidelines:Updated screening thresholds now capture normotensive patients with adrenal incidentalomas, widening the addressable population for confirmatory testing protocols.
- China:NMPA streamlined diagnostic assay registration pathways, accelerating plasma aldosterone concentration immunoassay approvals for domestic manufacturers.
- Adrenal Vein Sampling:Catheter-based lateralization techniques reduce unnecessary adrenalectomies, improving surgical yield rates at tertiary referral centers.
Market Restraints
- Renin Assay Variability:Inter-laboratory coefficient of variation exceeds 20% for plasma renin activity measurements, creating diagnostic uncertainty and repeat testing burdens.
- Spironolactone Supply:Active pharmaceutical ingredient production concentrates in Indian API manufacturers, exposing formulators to import tariff volatility and customs delays.
- Confirmatory Testing Access:Saline suppression testing requires inpatient observation capacity, which rural hospitals lack, creating geographic diagnostic deserts.
Strategic Opportunities
- Japan:METI reimbursement incentives for rare disease diagnostics create favorable pricing environments for aldosterone-producing adenoma screening programs.
- Liquid Chromatography-Tandem Mass Spectrometry:LC-MS/MS platforms converge with automated sample preparation, enabling same-day aldosterone-to-renin ratios at mid-volume laboratories.
- Direct-to-Consumer Channels:Telemedicine platforms bypass traditional endocrinology referral bottlenecks, capturing hypertensive patients before specialist gatekeeping occurs.
Industry Challenges
- Adrenal Vein Sampling Proficiency:Interventional radiologists require 50+ supervised procedures to achieve technical competency, constraining service expansion at community hospitals.
- Laboratory Information System Integration:Bi-directional interfaces between immunoassay analyzers and electronic health records demand six-month implementation timelines at multi-site health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Aldosteronism Market |
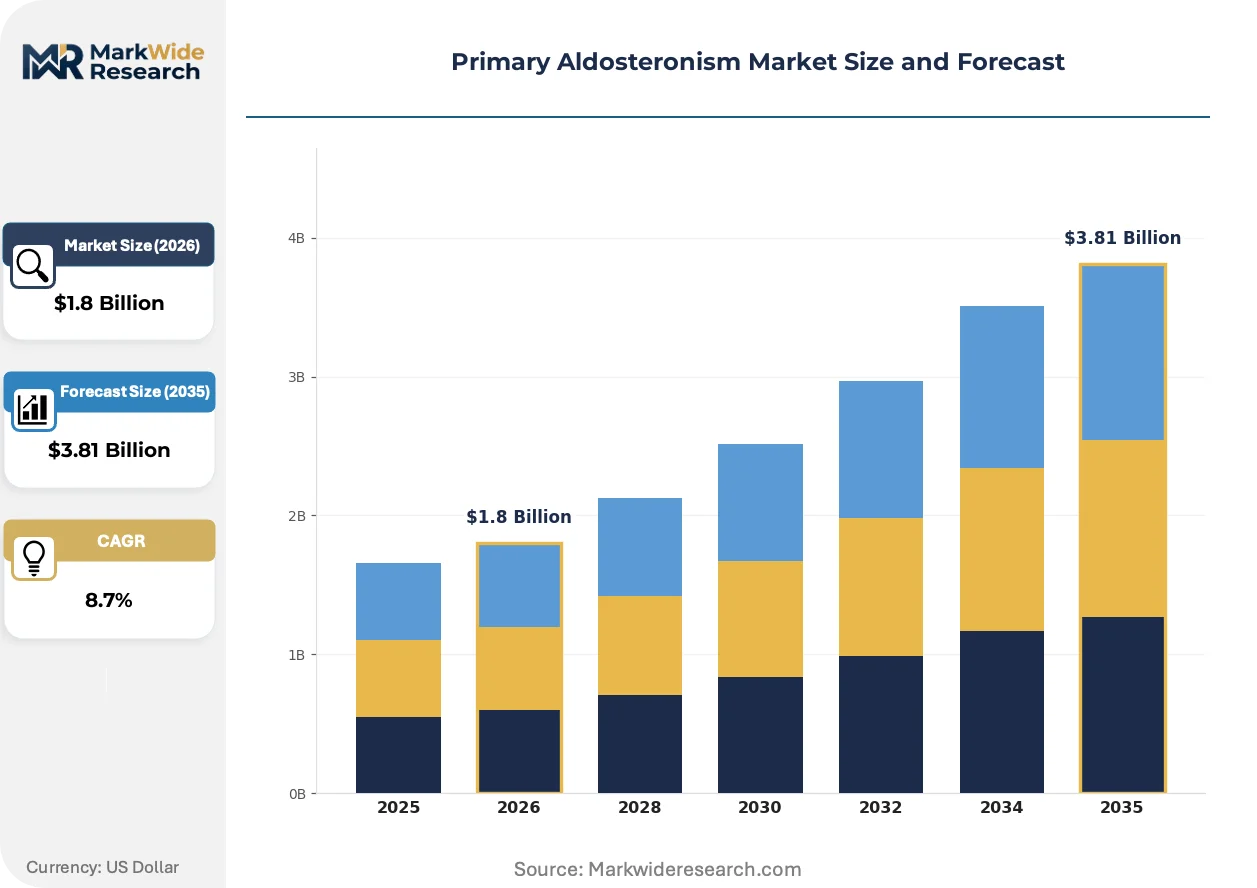
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aldosterone Antagonists, Diuretics, Antihypertensive Agents, Corticosteroids Therapy Area: Hypertension, Cardiovascular Disorders, Kidney Diseases, Endocrine Disorders End User: Hospitals, Clinics, Research Institutions, Homecare Settings Delivery Mode: Oral, Injectable, Transdermal, Inhalation |
| Companies Covered | Novartis AG, Bristol Myers Squibb, Pfizer Inc, Merck & Co., Inc., Sanofi, Sun Pharmaceutical Industries Ltd, Bayer AG, GE Healthcare, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Aldosteronism Market Evolving Landscape
Molecular phenotyping and machine-assisted image analysis are compressing diagnostic timelines while regulatory bodies recalibrate reimbursement frameworks for precision-guided therapy selection.
Machine learning algorithms trained on adrenal CT attenuation values are converging with clinical metadata to predict aldosterone-producing adenoma probability pre-procedurally. Academic medical centers in Germany and South Korea deploy these tools to triage patients toward adrenal vein sampling versus medical management. Radiologists at high-volume centers now incorporate algorithmic outputs into multidisciplinary tumor board decisions, reducing unnecessary invasive procedures.
EMA's Medical Device Regulation reclassifies software-assisted diagnostic algorithms as Class IIa devices, mandating clinical validation studies for plasma aldosterone concentration interpretation tools. European endocrine laboratories face 18-month conformity assessment timelines for algorithm deployment. French and Dutch reference centers are consolidating validation efforts through multi-site prospective registries to distribute regulatory compliance costs.
Self-measured home blood pressure monitoring is displacing office-based hypertension diagnosis as the entry point for primary aldosteronism suspicion. Primary care networks in Australia and Canada now distribute ambulatory devices with automated renin-aldosterone ratio trigger thresholds. Patients with resistant hypertension patterns bypass traditional cardiology referral queues, presenting directly to endocrinology with pre-aggregated biometric data that accelerates confirmatory testing decisions.
Primary Aldosteronism Market Segmentation
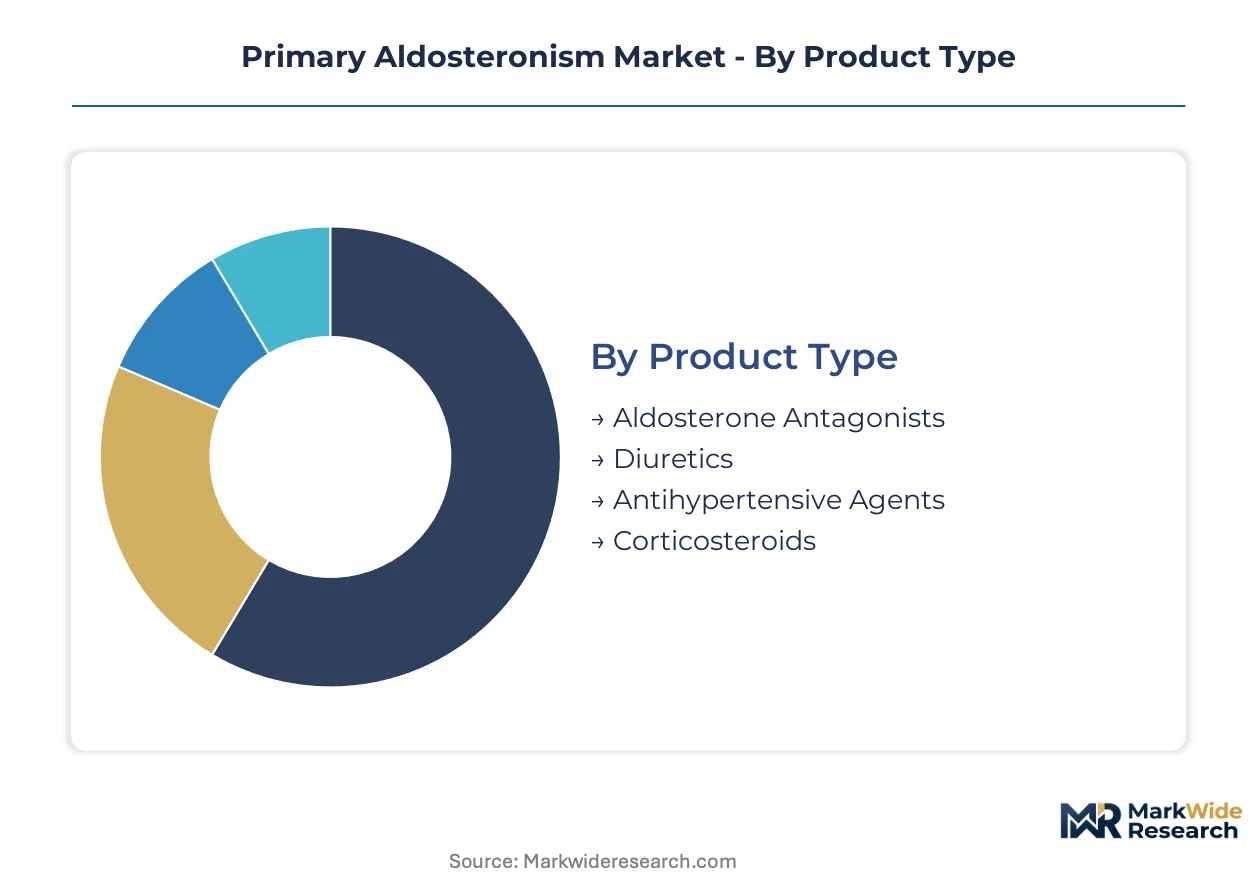
Product differentiation in primary aldosteronism care follows biochemical mechanism and site-of-action specificity, with mineralocorticoid receptor blockade commanding the largest formulation volumes. Segmentation reveals how diagnostic expansion reshapes therapy selection across hospital tiers and outpatient channels.
Product Type:
Active pharmaceutical ingredient sourcing concentrates among Indian and Chinese manufacturers, exposing finished dose formulators to tariff volatility and customs processing delays.
- Aldosterone Antagonists:Mineralocorticoid receptor blockers—spironolactone and eplerenone—constitute the cornerstone of medical management for confirmed lateralized and bilateral disease. Demand clusters at academic medical centers performing adrenal vein sampling, where preoperative medical optimization drives prescription volumes before adrenalectomy referral.
- Diuretics:Thiazide and loop diuretics serve adjunctive roles in volume management and blood pressure control, particularly when mineralocorticoid receptor antagonists prove insufficient. Community hospitals in the United States rely heavily on these agents when confirmatory testing delays access to targeted therapy.
- Antihypertensive Agents:ACE inhibitors and calcium channel blockers address resistant hypertension phenotypes before aldosteronism confirmation.
- Corticosteroids:Dexamethasone-suppressible aldosteronism variants require glucocorticoid therapy at specialized endocrine centers.
Aldosterone antagonists absorb the bulk of installed capacity; corticosteroids are expanding most quickly as genetic screening identifies familial hyperaldosteronism variants.
Therapy Area:
Cost tier differentiation separates chronic disease management protocols from acute intervention pathways, with hospital reimbursement rates varying substantially by diagnostic code assignment.
- Hypertension:Resistant hypertension—defined as blood pressure above goal despite three antihypertensive agents including a diuretic—serves as the primary screening indication for primary aldosteronism. Cardiology practices in Germany and South Korea drive referral volumes through automated renin-aldosterone ratio triggers embedded in electronic health record systems.
- Cardiovascular Disorders:Left ventricular hypertrophy and atrial fibrillation in the setting of suppressed renin activity prompt targeted aldosterone modulation. Tertiary centers in Japan leverage METI reimbursement incentives for rare disease diagnostics to capture these patients before irreversible cardiac remodeling occurs.
- Kidney Diseases:Chronic kidney injury from prolonged aldosterone exposure creates nephrology-endocrinology co-management opportunities.
- Endocrine Disorders:Adrenal incidentaloma evaluation and familial screening protocols widen the addressable population.
Hypertension absorbs the bulk of installed capacity; endocrine disorders are gaining share fastest as screening thresholds capture normotensive patients with adrenal masses.
End User:
Customer type fragmentation reflects the multi-step diagnostic cascade, with each setting commanding distinct procurement specifications and formulary constraints.
- Hospitals:Tertiary and academic medical centers perform saline suppression testing, adrenal vein sampling, and unilateral adrenalectomy. Catheter-based lateralization procedures require interventional radiology infrastructure unavailable at community facilities, concentrating high-value diagnostic and surgical volumes.
- Clinics:Endocrinology and cardiology outpatient practices manage long-term mineralocorticoid receptor antagonist therapy and monitor for gynecomastia, hyperkalemia, and renal function deterioration. Telemedicine platforms in Australia and Canada now bypass traditional referral queues by distributing ambulatory blood pressure devices with automated screening algorithms.
- Research Institutions:Molecular phenotyping studies and machine learning algorithm development occur at reference centers in France and the Netherlands.
- Homecare Settings:Self-measured blood pressure monitoring and oral medication adherence support expand as diagnostic entry points shift outside clinical facilities.
Hospitals absorb the bulk of installed capacity; homecare settings are climbing the fastest as remote patient monitoring reshapes diagnostic entry points.
Delivery Mode:
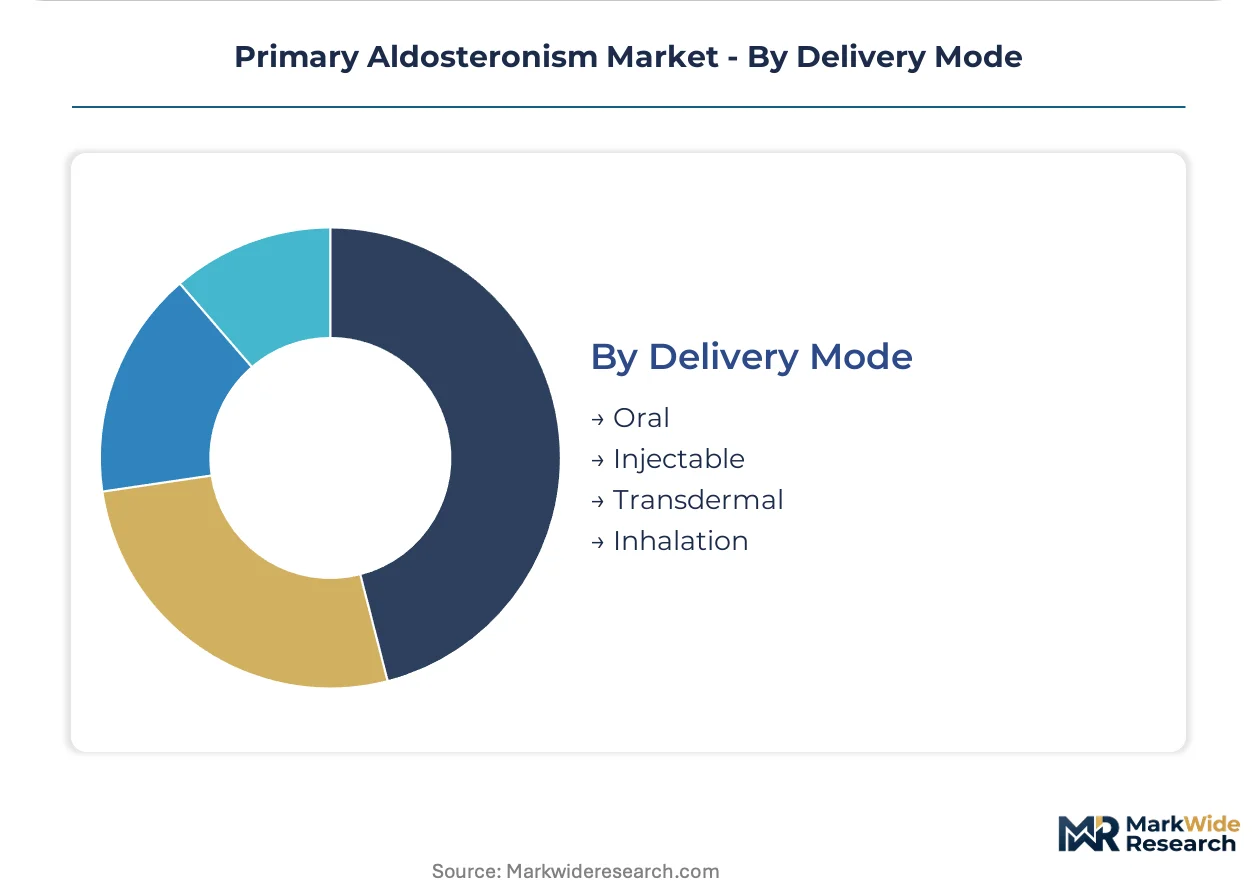
Volume concentration favors oral administration, though acute care applications sustain injectable manufacturing lines at mid-scale pharmaceutical operations.
- Oral:Tablet and capsule formulations dominate chronic maintenance therapy, with once-daily spironolactone and eplerenone enabling adherence in outpatient settings. Hospital formulary penetration by generic manufacturers anchors this segment's cost structure.
- Injectable:Intravenous formulations address perioperative adrenal crisis management and inpatient saline suppression testing protocols. Academic medical centers in the United States maintain stockpiles for emergency mineralocorticoid replacement when oral intake is contraindicated.
- Transdermal:Patch-based delivery remains investigational for aldosterone modulation.
- Inhalation:No established therapeutic role exists for this route in primary aldosteronism management.
Oral delivery absorbs the bulk of installed capacity; injectable formulations are expanding most quickly as perioperative protocol standardization advances at high-volume surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor generates the highest adrenal vein sampling volumes globally, with Massachusetts General Hospital and Brigham and Women's Hospital processing complex lateralization referrals from across New England.
United States
Academic medical centers in Boston, Baltimore, and Houston drive subspecialty referral volumes for catheter-based lateralization procedures. FDA endorsement of targeted mineralocorticoid receptor antagonist therapy after confirmatory testing streamlines reimbursement pathways. The Cleveland Clinic and Mayo Clinic anchor the Midwest diagnostic corridor, processing saline suppression testing and adrenal vein sampling for resistant hypertension cohorts.
Germany
Cardiology practices in Munich and Heidelberg deploy automated renin-aldosterone ratio triggers embedded in electronic health record systems, accelerating screening penetration. EMA's Medical Device Regulation reclassifies software-assisted diagnostic algorithms as Class IIa devices, mandating clinical validation studies. Reference centers in Freiburg and Hamburg consolidate multi-site prospective registries to distribute regulatory compliance costs for machine learning algorithm deployment.
Japan
METI reimbursement incentives for rare disease diagnostics create favorable pricing environments for aldosterone-producing adenoma screening programs at Tokyo and Osaka endocrine centers. Tertiary facilities leverage these incentives to capture cardiovascular disorder patients before irreversible cardiac remodeling occurs. The Kansai region hosts concentrated interventional radiology expertise for adrenal vein sampling technical competency development.
China
NMPA streamlined diagnostic assay registration pathways accelerate plasma aldosterone concentration immunoassay approvals for domestic manufacturers in Shanghai and Beijing. Hospital-based diagnostic protocols widen screening for aldosterone-producing adenomas among hypertensive populations. The Yangtze River Delta corridor concentrates manufacturing capacity for active pharmaceutical ingredients supplying spironolactone formulators.
Australia
Primary care networks distribute ambulatory blood pressure devices with automated renin-aldosterone ratio trigger thresholds, bypassing traditional cardiology referral queues. Patients present directly to Sydney and Melbourne endocrinology practices with pre-aggregated biometric data. The country's national pharmaceutical regulator maintains proficiency testing requirements for aldosterone and renin immunoassays to preserve reimbursement eligibility.
Primary Aldosteronism Market Competitive Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light diagnostic developers across the primary aldosteronism care continuum. The therapy segment concentrates around mineralocorticoid receptor antagonist portfolios, while the diagnostic tier fragments across immunoassay platforms and catheter-based procedure providers. Three archetypes dominate: integrated pharmaceutical-diagnostics conglomerates, generic active pharmaceutical ingredient formulators, and specialized interventional radiology service networks. Competitive dynamics center on hospital formulary penetration and adrenal vein sampling technical competency acquisition.
Within the branded therapy tier, Novartis AG anchors mineralocorticoid receptor antagonist positioning through portfolio breadth. Pfizer Inc exemplifies scale-driven generic manufacturing, supplying spironolactone through hospital formulary penetration. Sun Pharmaceutical Industries Ltd represents Indian API-to-formulation verticality, capturing cost-sensitive markets through manufacturing efficiency. These three entities collectively illustrate how supply chain configuration determines competitive positioning across premium and commodity segments.
| Leading Market Players |
|---|
| Novartis AG |
| Bristol Myers Squibb |
| Pfizer Inc |
| Merck & Co., Inc. |
| Sanofi |
| Sun Pharmaceutical Industries Ltd |
| Bayer AG |
| GE Healthcare |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
EPA pharmaceutical manufacturing discharge standards gate qualified active pharmaceutical ingredient supply and premium-tier pricing access for mineralocorticoid receptor antagonist formulators. Compliance investments concentrate production economics among vertically integrated manufacturers, while tariff exposure on Indian spironolactone API imports compresses margin structures for non-integrated dose formulators.
Pricing Analysis
Value-based pricing anchored to surgical yield improvement and cardiovascular outcome reduction commands premium positioning for catheter-based lateralization procedures at academic medical centers. Three-tier pricing structure across premium, standard, and economy levels separates branded eplerenone from generic spironolactone and compounded alternatives, with FDA certification tier and interventional radiologist technical competency as primary differentiation drivers. Cost compression in the generic tier intensifies because Indian API import tariff volatility and customs delays erode formulator margins. Community hospital procurement committees exhibit highest price sensitivity, while tertiary referral centers prioritize surgical yield metrics over unit cost.
Supply Chain Analysis
Spironolactone active pharmaceutical ingredient supply rests on Indian specialty chemical manufacturers in Hyderabad and Ahmedabad, with secondary concentration among Chinese producers in the Yangtze River Delta. Finished dose formulation draws from domestic capacity in the United States and Germany, with critical dependencies on canrenone precursor chemicals and pharmaceutical-grade lactose excipients. Single-source vulnerability in Indian API production exposes formulators to customs processing delays and import tariff volatility. Distribution runs through hospital group purchasing organizations and specialty pharmacy channels, with academic medical center formularies commanding allocation priority during supply constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interventional radiologist technical competency acquisition bottlenecks constrain adrenal vein sampling service expansion, propping pricing power for high-volume tertiary centers. Supply scarcity in trained proceduralists limits competitive entry and sustains premium-tier procedure economics.
For Market Incumbents: To counter generic spironolactone price erosion and Indian API tariff exposure, Novartis AG and Pfizer Inc should deepen backward integration into captive canrenone production and secure long-term offtake agreements with domestic API manufacturers. Capacity addition in United States pharmaceutical manufacturing corridors reduces import dependency and insulates margin structures from customs volatility.
For New Entrants and Emerging Players: Telemedicine platform partnerships offer the most penetrable channel for bypassing traditional endocrinology referral bottlenecks and capturing hypertensive patients at diagnostic entry points. White-space targets include direct-to-consumer renin-aldosterone ratio screening in Australia and Canada, plus algorithmic diagnostic tool deployment at mid-volume European laboratories seeking EMA Medical Device Regulation compliance pathways.
For Investors and Strategic Acquirers: NMPA streamlined diagnostic assay registration approvals in China are the leading indicator that domestic plasma aldosterone concentration immunoassay manufacturers will consolidate market share from multinational incumbents. Long-term viability over the projection horizon favors acquisition targets with LC-MS/MS platform integration capabilities and automated sample preparation technologies. Watch for METI reimbursement incentive expansions in Japan as the signal for rare disease diagnostic pricing inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Adrenal Vein Sampling Technical Competency Acquisition | Interventional radiology training programs at Massachusetts General Hospital and Brigham and Women's Hospital anchor high-yield referral economics. |
| LC-MS/MS Platform Integration | Same-day aldosterone-to-renin ratio capabilities at Freiburg and Hamburg reference centers compress diagnostic timelines and capture referral volume. |
| Backward Integration into API Production | Domestic canrenone manufacturing insulates formulators from Indian import tariff volatility and customs processing delays. |
| Telemedicine Platform Partnership | Australian and Canadian primary care networks bypass cardiology referral queues with automated screening algorithm deployment. |
| EMA Medical Device Regulation Compliance | Multi-site prospective registries in France and Netherlands distribute algorithm validation costs for software-assisted diagnostic tools. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with interventional radiologists, endocrinology department heads, hospital formulary directors, and pharmaceutical regulatory affairs leads. FDA 510(k) submissions, EMA marketing authorization applications, NMPA diagnostic assay registrations, and CAP proficiency testing records provided structured validation points. Bottom-up patient volume modeling across screening, confirmatory testing, and therapy selection stages converged with top-down pharmaceutical shipment data from customs records and hospital procurement databases.
Data-stream reconciliation across immunoassay analyzer installation records, adrenal vein sampling procedure volumes at tertiary centers, and mineralocorticoid receptor antagonist prescription patterns enabled segmentation modeling by product type, therapy area, end user, and delivery mode across the analysis window. CAGRs derived from procedure volume trajectories, screening guideline adoption curves, and reimbursement policy shifts. Forecast inputs incorporated interventional radiologist training pipeline constraints, EPA pharmaceutical manufacturing discharge compliance timelines, and METI rare disease diagnostic incentive expansions.
Several conditions sit outside the modeled scope, including novel molecular phenotyping technologies without established clinical validation, gene therapy approaches for familial hyperaldosteronism variants, and radical catheter-based procedure automation. Forecasts reflect assumptions about screening guideline adherence rates, adrenal vein sampling reimbursement stability, and API import tariff regimes. A small set of named triggers warrants ongoing watch: NMPA diagnostic assay registration pathway modifications, EMA Medical Device Regulation enforcement intensity, and Indian API manufacturing inspection outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Hematuria Treatment Market
Urology
Renal Cyst Treatment Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Global Bladder Cancer Market
Urology
Global Prostate Health Market
Urology
Europe Urology Devices Market
Urology
Urology Forceps Market
Urology
Botulinum Toxin in Urology Market
Urology
Disposable Ureteroscope Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Prostate Cancer Treatment Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Urology Devices Market
Urology
Global Hydronephrosis Market