
 Urology Surgery Supplies Market | 2026-2036
Urology Surgery Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Urology Surgery Supplies Market Analysis
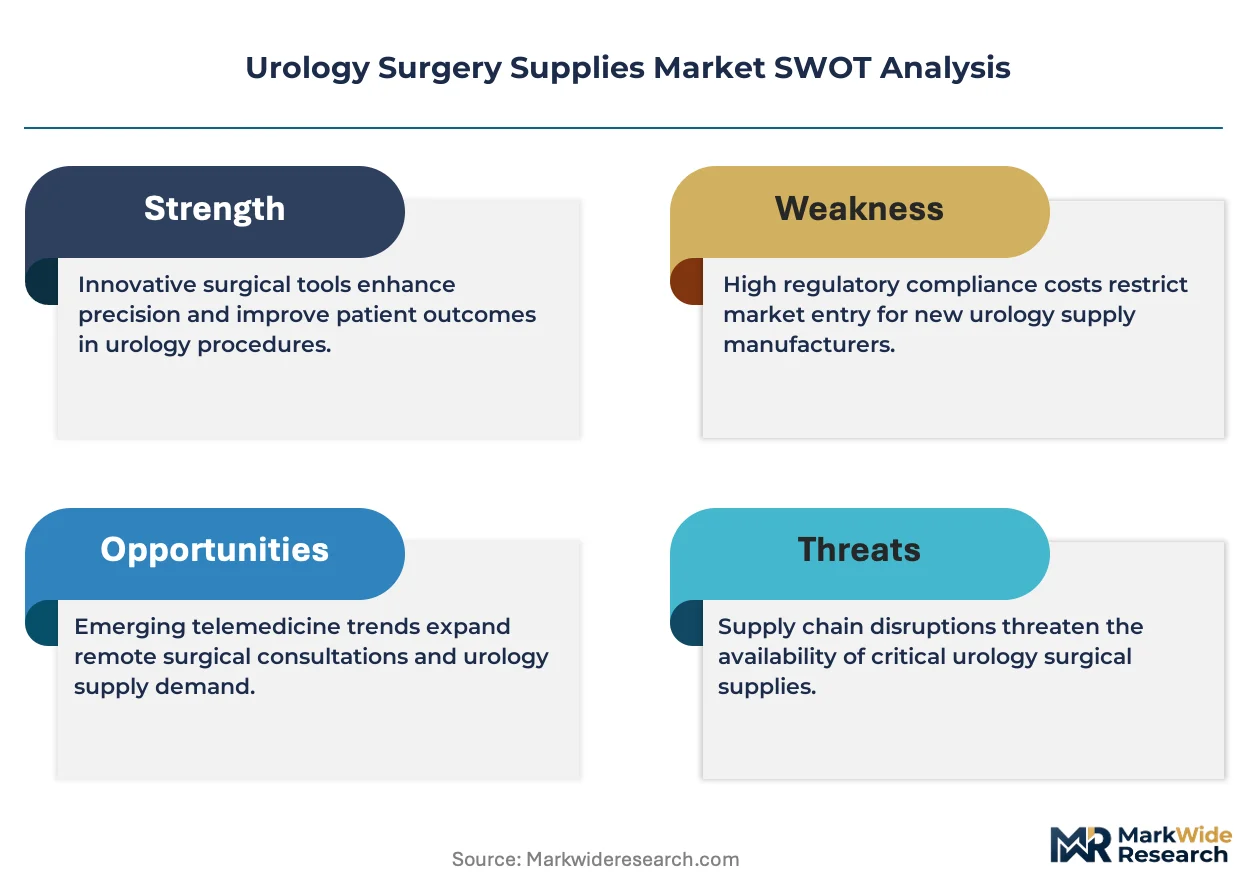
Hospital procurement of urology surgery supplies is tilting toward single-use disposable platforms over reusable instrument sets. Boston Scientific leverages integrated catheter and stent portfolios to capture recurring procedural demand. Medtronic anchors its position through endourology energy systems that pair with proprietary consumable lines. KARL STORZ competes on rigid and flexible endoscope durability, sustaining premium placement in academic medical centers despite higher capital outlay.
Urology surgery supplies encompass instruments, catheters, drainage systems, and sutures engineered for sterile performance during lower and upper urinary tract procedures, with silicone and specialized polymer formulations delivering biocompatibility ratings critical for indwelling applications. Catheters and drainage bags command the largest revenue footprint given replacement frequency and infection-control protocols, while ureteroscopy application segments are expanding fastest as stone disease prevalence climbs and flexible scope technology advances. Metal instrument sets face margin compression from polymer disposables, though titanium alloy retrieval baskets retain pricing power in complex calculus extraction.
FDA 510(k) clearances govern market entry for Class II urology devices in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for reusable endoscopes. Japan's PMDA and METI coordinate on silicone material standards for long-term indwelling catheters, creating divergent compliance pathways across major markets. Stakeholders must monitor evolving sterilization validation rules and reimbursement coding shifts for outpatient versus inpatient urology procedures.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around single-use disposable platforms, compressing the addressable market for reusable metal instrument sets and forcing manufacturers to retool production lines toward polymer-based consumables.
Growth Catalysts
- Ambulatory Surgical Center Expansion:United States outpatient facilities are scaling procurement of disposable urology kits as same-day discharge protocols expand stone extraction and stent placement volumes.
- FDA 510(k) Pathway Acceleration:Streamlined clearance timelines for Class II single-use endoscopic devices are shortening product development cycles and enabling faster commercialization of next-generation scopes.
- Silicone Biocompatibility Standards:Japan's METI and PMDA coordination on long-term indwelling catheter materials is establishing quality benchmarks that premium manufacturers leverage for differentiation.
Market Restraints
- Polymer Raw Material Concentration:Medical-grade silicone and specialized thermoplastic elastomer supply chains cluster in East Asian petrochemical corridors, exposing manufacturers to input cost volatility and logistics disruption.
- EU MDR Clinical Evidence Burden:Stricter post-market surveillance and reusable endoscope validation requirements under the Medical Device Regulation are extending time-to-market and inflating compliance expenditures.
- Capital Equipment Replacement Cycles:Academic medical centers defer rigid endoscope fleet refresh amid budget constraints, delaying revenue recognition for premium scope manufacturers.
Strategic Opportunities
- Underpenetrated Latin American Markets:Brazil's ANVISA harmonization with ISO standards is reducing registration friction, opening procurement channels for mid-tier disposable catheter manufacturers.
- AI-Assisted Stone Detection Convergence:Integration of computer vision algorithms with flexible ureteroscopy systems is creating premium pricing tiers for image-guided retrieval procedures.
- Direct-to-Ambulatory Distribution:Bypassing traditional hospital purchasing committees through specialized distributors serving independent urology clinics is capturing higher-margin recurring consumable revenue.
Industry Challenges
- Sterile Processing Technician Shortage:Healthcare facilities face staffing gaps in high-level disinfection protocols for reusable endoscopes, accelerating the operational shift toward single-use alternatives.
- Legacy EMR Integration Complexity:New digital ureteroscopy platforms with embedded documentation tools require costly interface development with entrenched hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urology Surgery Supplies Market |
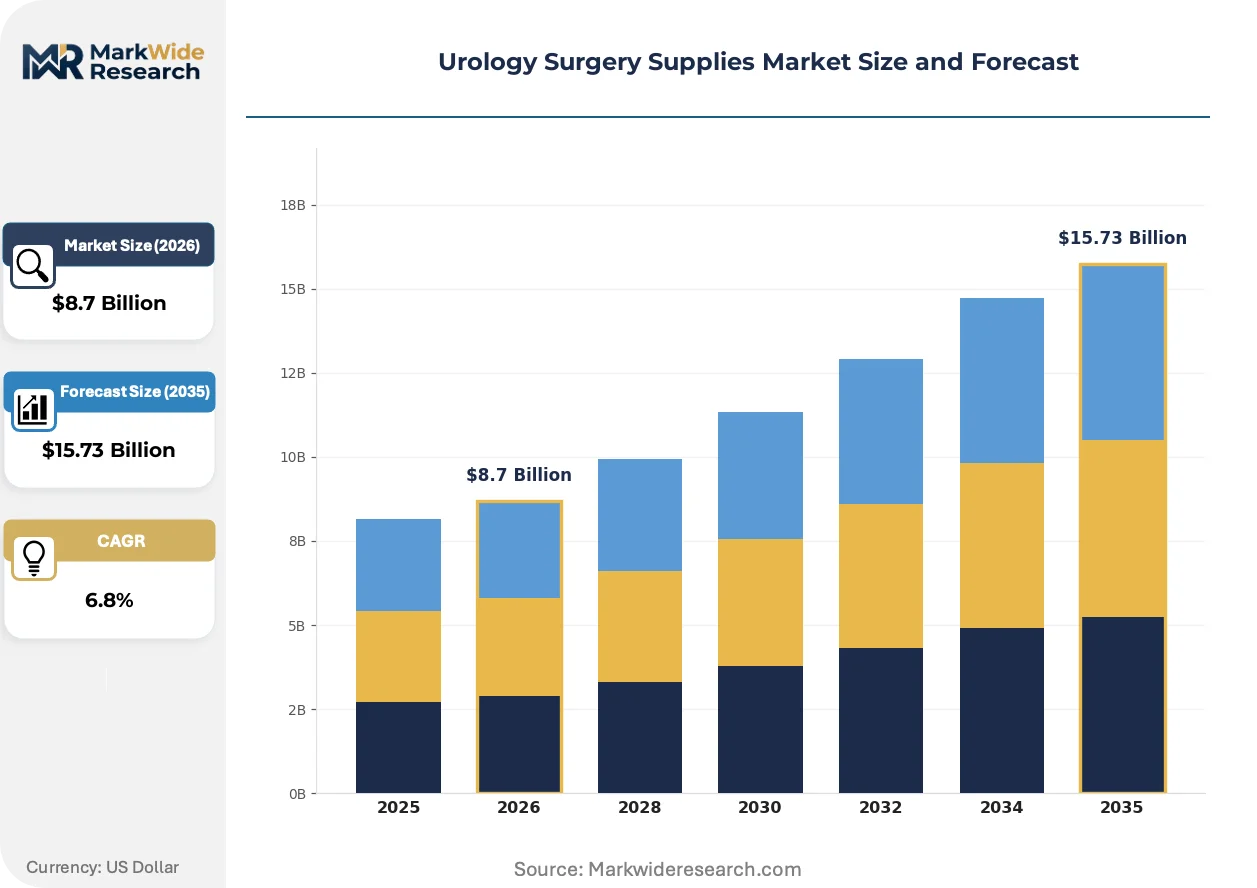
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Catheters, Drainage Bags, Sutures End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Urgent Care Facilities Material: Plastic, Metal, Silicone, Latex Application: Prostatectomy, Nephrectomy, Cystectomy, Ureteroscopy |
| Companies Covered | Boston Scientific Corporation, Medtronic, Olympus Corporation, KARL STORZ, Teleflex Incorporated, Stryker Corporation, Cook Medical, Richard Wolf GmbH, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urology Surgery Supplies Market Emerging Trajectories
Digital integration and material science advances are compressing procedure times while expanding the treatable patient population, with regulatory frameworks racing to keep pace with iterative device improvements.
Single-use digital flexible ureteroscopes are collapsing the economic viability of reusable scope repair and reprocessing services. Ambulatory surgical centers in the United States are adopting these platforms at accelerating pace to eliminate sterilization infrastructure overhead. The shift is compressing service revenue for third-party endoscope repair specialists and redirecting margin capture toward original equipment manufacturers.
EU MDR post-market surveillance requirements are mandating extended clinical follow-up for reusable endoscope durability claims. Manufacturers must now generate real-world performance data across European Union member states, inflating regulatory affairs headcount and documentation burdens. Flexible scope suppliers are responding by accelerating disposable platform development to circumvent reusable device classification.
Hospital value analysis committees are unbundling catheter and stent procurement from procedure pack bundles, forcing suppliers to justify individual component pricing. United States integrated delivery networks are leading this disintermediation, leveraging purchasing scale to extract line-item concessions. The behavioral shift is fragmenting historical account control and elevating price transparency as the primary competitive variable.
Urology Surgery Supplies Market Segmentation
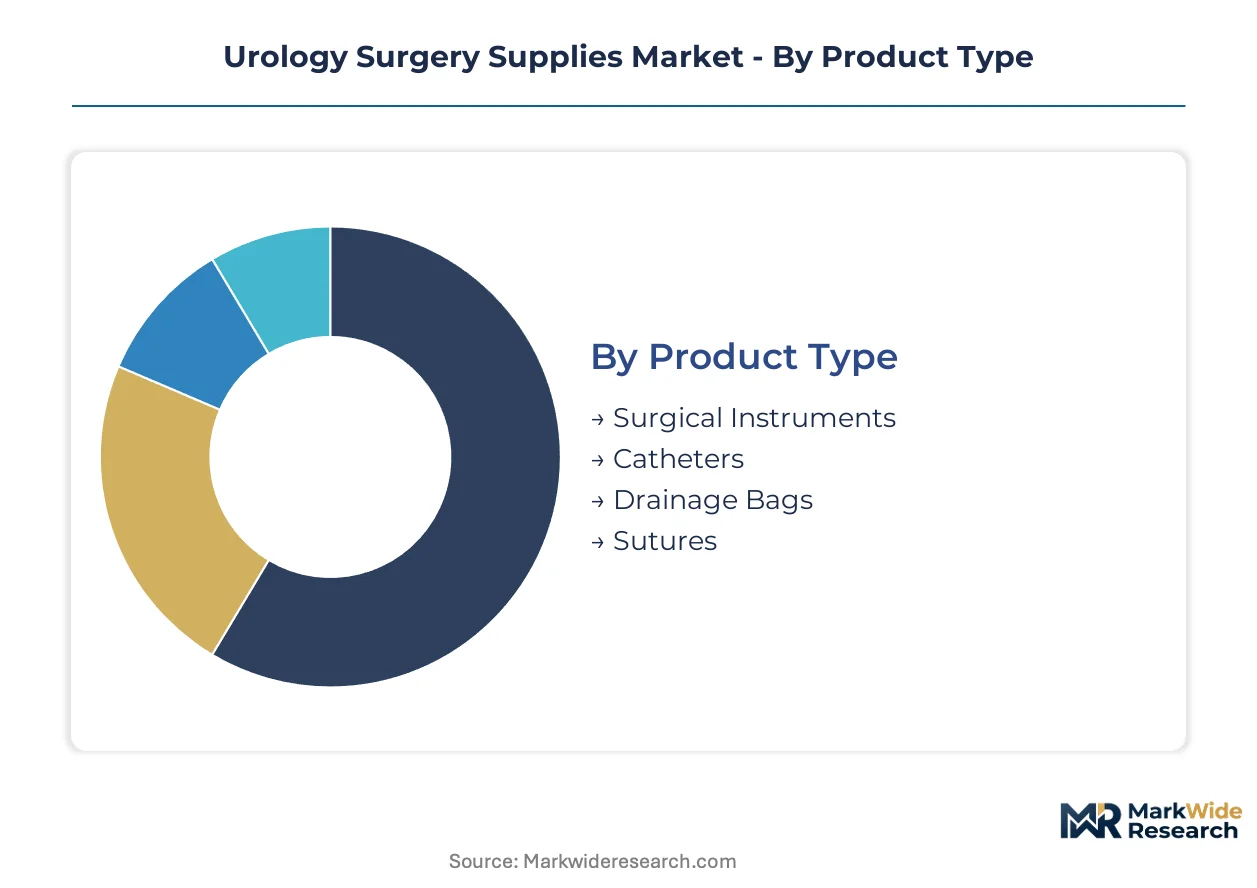
Procurement patterns in urology surgery supplies diverge sharply across clinical settings and procedural requirements. Hospital value analysis committees evaluate segments through distinct lenses: infection control protocols, capital versus consumable trade-offs, and reimbursement alignment.
Product Type:
Use-case spectrum spans acute procedural intervention through chronic drainage management, with material durability and sterility assurance driving category selection.
- Catheters:Silicone and specialized polymer formulations deliver biocompatibility ratings critical for indwelling applications. Demand concentrates in United States ambulatory surgical centers where same-day discharge protocols expand replacement frequency and infection-control procurement.
- Surgical Instruments:Metal instrument sets face margin compression from polymer disposables, though titanium alloy retrieval baskets retain pricing power in complex calculus extraction. Academic medical centers in the United States defer rigid endoscope fleet refresh amid budget constraints.
- Drainage Bags:Command substantial procurement volume given replacement protocols and closed-system infection prevention requirements.
- Sutures:Absorbable and non-absorbable variants align with tissue approximation needs across open and laparoscopic urological procedures.
The dominant share belongs to Catheters, while Surgical Instruments is closing the gap fastest through single-use platform conversion.
End User:
Customer type determines procurement authority structure and volume concentration, with facility scale dictating vendor relationship complexity.
- Hospitals:Integrated delivery networks in the United States unbundle catheter and stent procurement from procedure pack bundles, forcing suppliers to justify individual component pricing through line-item concessions.
- Ambulatory Surgical Centers:Scaling procurement of disposable urology kits as same-day discharge protocols expand stone extraction and stent placement volumes, eliminating sterilization infrastructure overhead.
- Outpatient Clinics:Smaller procurement scale limits vendor negotiation leverage, concentrating purchasing through group purchasing organizations.
- Urgent Care Facilities:Emergency urological intervention capabilities drive spot procurement of drainage and catheterization supplies.
Hospitals retain the dominant procurement volume, though Ambulatory Surgical Centers is expanding most quickly through outpatient procedure migration.
Material:
Margin structure varies with raw material concentration and regulatory validation burden across polymer and metal supply chains.
- Silicone:Japan's METI and PMDA coordination on long-term indwelling catheter materials establishes quality benchmarks that premium manufacturers leverage for differentiation in biocompatibility-sensitive applications.
- Plastic:Medical-grade thermoplastic elastomer supply chains cluster in East Asian petrochemical corridors, exposing manufacturers to input cost volatility and logistics disruption.
- Metal:Titanium alloys sustain premium placement in retrieval basket applications requiring structural integrity for complex calculus extraction.
- Latex:Declining share amid allergy sensitivity protocols and silicone substitution in indwelling applications.
Silicone commands the dominant material share, while Plastic is gaining fastest through single-use disposable platform proliferation.
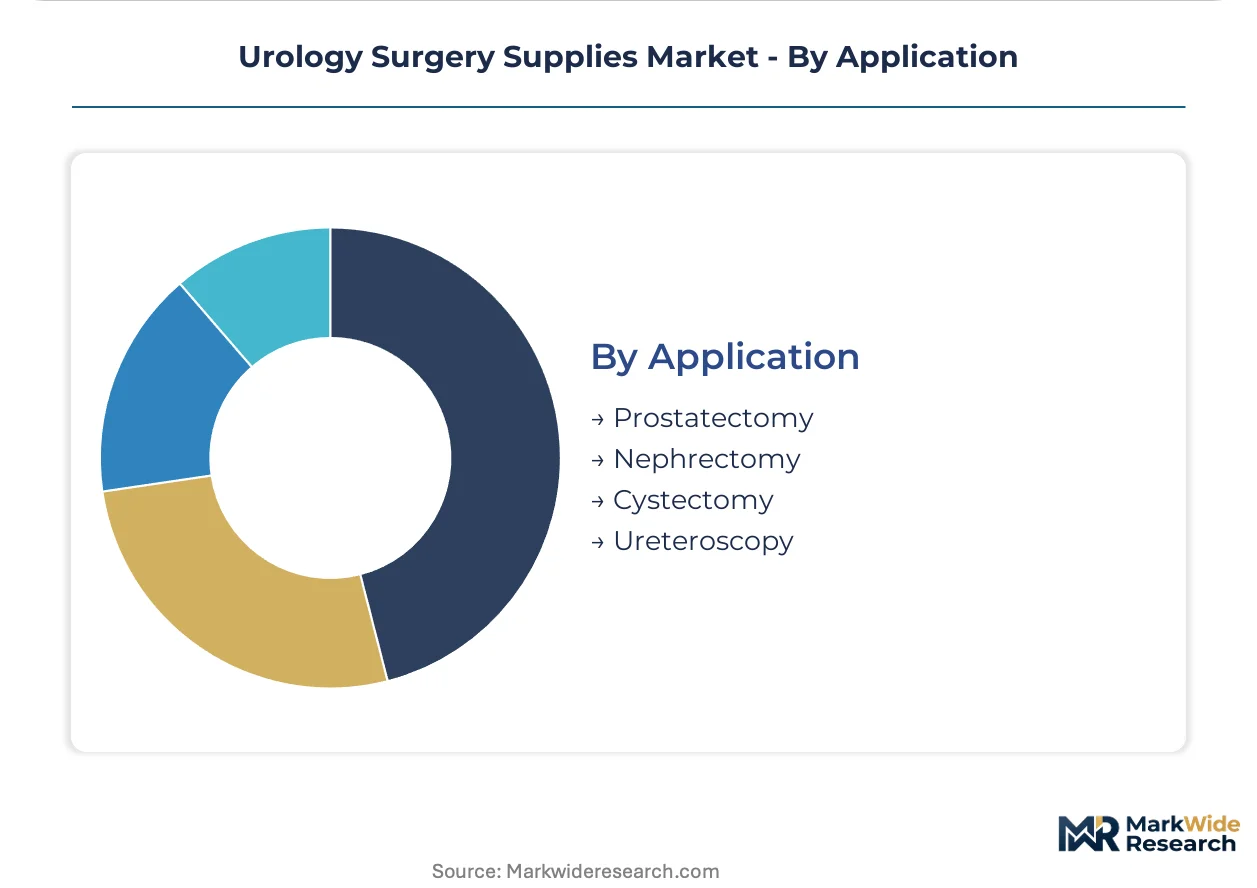
Application:
Procedural volume and technology intensity create divergent growth trajectories across upper and lower urinary tract interventions.
- Ureteroscopy:Flexible scope technology advances and stone disease prevalence expansion are accelerating segment growth, with AI-assisted stone detection integration creating premium pricing tiers for image-guided retrieval procedures.
- Prostatectomy:Minimally invasive robotic and laparoscopic approaches sustain instrument and consumable demand in United States aging demographic markets.
- Nephrectomy:Partial and radical procedures drive specialized clamp, stapler, and energy system requirements.
- Cystectomy:Urinary diversion reconstruction sustains demand for bowel anastomosis and stoma management supplies.
Ureteroscopy holds the steepest expansion trajectory, while Prostatectomy maintains the largest procedural volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways for Class II single-use endoscopic devices anchor procurement velocity in the United States, where outpatient urology migration and aging demographics concentrate demand. Divergent regulatory frameworks across Japan, Germany, China, and Brazil shape distinct compliance burdens and market entry timelines.
United States
Integrated delivery networks unbundle catheter and stent procurement from procedure pack bundles, forcing line-item pricing concessions. CMS reimbursement shifts favor ambulatory surgical centers for stone extraction and stent placement. Boston and Minneapolis medical device clusters house headquarters of dominant suppliers.
Germany
Academic medical centers in Baden-Württemberg and Bavaria sustain premium placement for rigid and flexible endoscope durability despite capital budget constraints. EU MDR post-market surveillance requirements mandate extended clinical follow-up for reusable endoscope claims. Stuttgart and Tuttlingen industrial corridors concentrate precision endoscope manufacturing.
Japan
METI and PMDA coordination on silicone material standards for long-term indwelling catheters establishes quality benchmarks that premium manufacturers leverage. Aging demographics expand chronic urological condition prevalence. Tokyo and Osaka metropolitan areas concentrate procurement authority for university hospitals.
China
NMPA regulatory harmonization with ISO standards accelerates domestic catheter and drainage system approvals. Provincial hospital procurement centralization in Jiangsu and Zhejiang provinces drives volume consolidation. Yangtze River Delta manufacturing clusters supply medical-grade polymer feedstocks.
Brazil
ANVISA harmonization with ISO standards reduces registration friction for mid-tier disposable catheter manufacturers. Private hospital networks in São Paulo and Rio de Janeiro expand minimally invasive urology service lines. Southeast regional distributors capture growing outpatient clinic procurement.
Urology Surgery Supplies Market Vendor Landscape
Diversified medical technology conglomerates and specialized endoscopy manufacturers split the market into distinct capability tiers. Consolidation pressure intensifies as hospital procurement departments reduce vendor counts. Three strategic archetypes dominate: integrated catheter-stent portfolio holders, endourology energy system suppliers, and rigid-flexible endoscope durability specialists. M&A activity targets disposable platform capabilities, while geographic expansion into Latin American markets accelerates.
Within the diversified conglomerate tier, Boston Scientific Corporation and Medtronic exemplify integrated portfolio strategies that pair capital equipment with recurring consumable revenue. KARL STORZ anchors the specialized endoscope durability segment, representing German precision manufacturing heritage. These three entities occupy positions that reflect divergent responses to the single-use disposable transition reshaping procurement patterns.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Olympus Corporation |
| KARL STORZ |
| Teleflex Incorporated |
| Stryker Corporation |
| Cook Medical |
| Richard Wolf GmbH |
| Becton, Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
East Asian petrochemical corridors concentrate medical-grade silicone and thermoplastic elastomer production, anchoring margin capture with original equipment manufacturers who command premium placement through FDA-cleared single-use platforms. Hospital value analysis committees exploit this concentration by unbundling procedure packs and extracting line-item concessions, compressing distributor margins while elevating price transparency.
Pricing Analysis
Geographic price spreads separate United States ambulatory surgical centers from European academic medical centers, with the former absorbing premium single-use digital ureteroscope pricing to eliminate sterilization overhead. Three-tier pricing structure across premium, standard, and economy levels aligns with FDA clearance tier, brand heritage, and bundled service intensity. Cost compression in standard-tier catheters is intensifying because integrated delivery networks leverage purchasing scale for line-item concessions. Ambulatory surgical centers exhibit highest price sensitivity due to thin procedure margins, while academic medical centers retain lowest sensitivity given research funding insulation.
Supply Chain Analysis
Export-control regimes on advanced imaging sensors and precision optics limit component flows from specific jurisdictions, forcing scope manufacturers toward dual-sourcing strategies. Manufacturing gravity centers on Germany for rigid endoscope precision, Japan for silicone material refinement, and China for polymer extrusion and drainage system assembly. Raw material dependencies include medical-grade silicone, thermoplastic elastomer, and titanium alloy feedstocks. Single-source vulnerability concentrates in East Asian petrochemical corridors exposed to logistics disruption. Distribution runs through specialized distributors serving ambulatory surgical centers and group purchasing organizations capturing hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use platform economics are displacing reusable instrument service revenue, with interoperability between digital ureteroscopy systems and hospital electronic medical records emerging as the decisive ecosystem battleground.
For Market Incumbents: Pre-empt disposable platform commoditization by deepening proprietary energy system integration with consumable lines, locking hospital accounts through embedded software documentation tools. Third-party endoscope repair specialists represent a substitute threat requiring monitoring. Backward integration into medical-grade silicone compounding secures input cost stability. For New Entrants and Emerging Players: Brazilian private hospital networks present the most penetrable expansion corridor, with ANVISA harmonization reducing registration friction for mid-tier catheter manufacturers. Direct-to-ambulatory distribution bypassing traditional hospital purchasing committees captures higher-margin recurring consumable revenue in independent urology clinics. For Investors and Strategic Acquirers: Capital is best deployed toward disposable platform specialists with FDA 510(k) clearance momentum and ambulatory surgical center distribution infrastructure. Long-term viability hinges on software-enabled procedure documentation integration. The signal to watch is CMS reimbursement coding shifts accelerating outpatient migration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Streamlined Class II clearance timelines compress competitive response windows for single-use scopes. |
| Ambulatory Distribution Partnership | Specialized distributors serving independent clinics capture recurring consumable revenue streams. |
| Software Companion Development | Embedded EMR integration tools lock hospital accounts through workflow dependency creation. |
| Silicone Material Backward Integration | In-house compounding secures medical-grade polymer supply against East Asian logistics volatility. |
| CE Marking Pathway Investment | EU MDR clinical evidence capabilities differentiate premium manufacturers from compliance-lagged competitors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, ambulatory surgical center administrators, biomedical engineers, GPO contracts managers, and urology clinic operators. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, hospital procurement contract repositories, and EU MDR post-market surveillance filings. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Calibration anchored volume and value outputs to disclosed regulatory filings, procurement contract values, and manufacturer production capacity across the modeling period. Segmentation dimensions spanned product type, end-user facility scale, material composition, and procedural application intensity. CAGRs were derived from procedure volume trajectories, replacement frequency protocols, and pricing elasticity assumptions specific to disposable platform conversion rates and ambulatory migration patterns.
Practitioners should monitor FDA guidance shifts on single-use device validation, CMS reimbursement coding changes, and East Asian petrochemical logistics indices for early signals of forecast deviation. Material shifts in EU MDR clinical evidence requirements or ambulatory surgical center accreditation standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Urology Forceps Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Continence Care Market
Urology
Urology Lasers Market
Urology
Disposable Ureteroscope Market
Urology
Urology Robotic Surgery Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Cystectomy Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Suprapubic Catheters Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market