
 Nordic Urinary Catheters Market | 2026-2036
Nordic Urinary Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic Urinary Catheters Market Analytics
Silicone is rebalancing product economics as Nordic providers phase out latex in favor of biocompatible alternatives. Coloplast A/S anchors its position through deep specialization in intermittent catheter systems for self-catheterization users. Wellspect HealthCare leverages hydrophilic coating technology to differentiate its LoFric portfolio across Swedish and Danish hospital contracts. B. Braun SE competes on manufacturing scale, sustaining broad supply relationships with Norway's regional health authorities.
Nordic urinary catheters are flexible tubular devices, typically 6-18 French in diameter, inserted through the urethra to drain urine from the bladder; they are manufactured from silicone, latex, or polyvinyl chloride via extrusion and tip-forming processes, with hydrophilic coatings applied to reduce insertion friction and urethral trauma during intermittent or indwelling use. Intermittent catheters dominate volume due to patient preference for single-use disposal protocols in Swedish and Finnish home care programs. Foley catheters retain margin concentration in hospital critical care, where two-way and three-way balloon designs command premium positioning through infection control bundling.
The EU Medical Device Regulation and national health technology assessment bodies in Sweden, Denmark, and Norway shape product registration timelines and reimbursement eligibility for coated catheter technologies. CE marking requirements under MDR intensify clinical evidence demands, filtering market access toward manufacturers with established notified body relationships. Stakeholders must monitor how Norway's regional health trust procurement consolidations reshape contract structures for multi-year catheter supply agreements.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines for silicone and hydrophilic coated catheter technologies, filtering competitive positioning toward manufacturers with established notified body relationships and clinical evidence portfolios.
Growth Catalysts
- Home care infrastructure:Denmark's decentralized municipal health services are embedding intermittent catheter protocols into chronic care pathways for spinal cord injury patients.
- MDR compliance premium:CE marking under the EU Medical Device Regulation is creating tiered market access where biocompatible silicone formulations capture preferential reimbursement positioning.
- Swedish procurement consolidation:Regional hospital networks are standardizing on hydrophilic-coated single-use systems through multi-year supply agreements.
Market Restraints
- Medical-grade silicone supply:Raw material concentration among European chemical suppliers exposes manufacturers to input cost volatility and allocation constraints.
- Notified body capacity:MDR transition has thinned EU certification infrastructure, extending technical documentation review cycles for new catheter submissions.
- Reusable catheter persistence:Environmental pressure groups in Norway are advocating sterilizable alternatives that threaten single-use volume economics.
Strategic Opportunities
- Finnish home care penetration:Underdeveloped intermittent catheter adoption in rural municipalities offers whitespace for self-catheterization education programs.
- Telehealth integration:Remote patient monitoring platforms are creating digital prescription channels that bypass traditional hospital procurement.
- Green procurement mandates:Swedish county council sustainability criteria are favoring manufacturers with ISO 14001-certified production and recyclable packaging.
Industry Challenges
- Polymer engineering talent:Specialized expertise in hydrophilic coating chemistry and extrusion process control remains scarce across Nordic manufacturing bases.
- Legacy system integration:Hospital IT infrastructure in Norway's regional health trusts requires manual bridging to connect catheter utilization data with electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic Urinary Catheters Market |
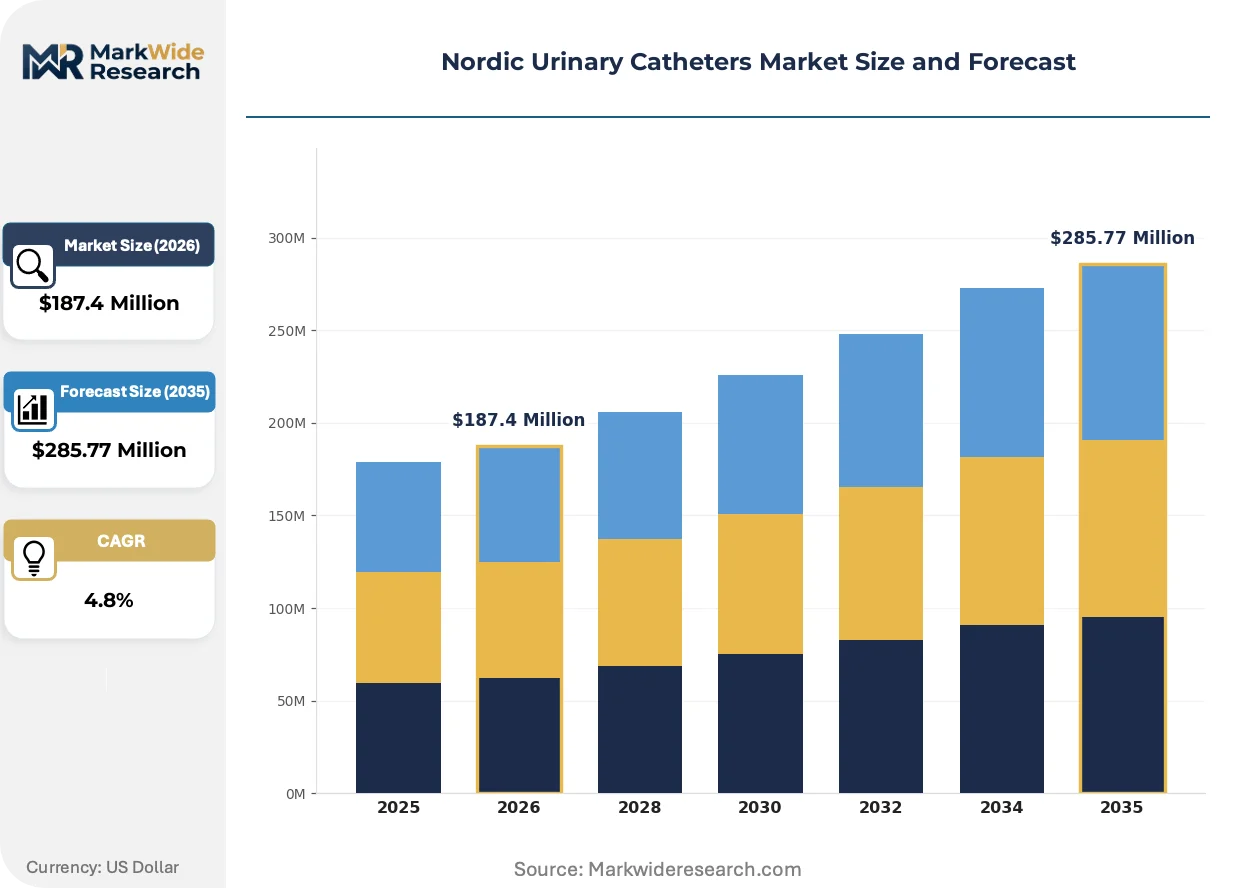
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermittent Catheters, Foley Catheters, External Catheters, Coude Catheters Material: Latex, Silicone, Polyvinyl Chloride, Hydrophilic Coated End User: Hospitals, Home Care, Long-term Care Facilities, Rehabilitation Centers Distribution Channel: Online Retail, Pharmacies, Direct Sales, Hospital Supply |
| Companies Covered | B. Braun SE, Teleflex Incorporated, Coloplast A/S, Becton, Dickinson and Company, Hollister Incorporated, Wellspect HealthCare, ConvaTec Group Plc, Dentsply Sirona, BACTIGUARD, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic Urinary Catheters Market Evolving Landscape
Coating chemistry and connected health infrastructure are redefining product value propositions across Nordic catheter markets, shifting competitive differentiation from material cost toward clinical outcome documentation and patient adherence metrics.
Closed-system intermittent catheter designs with integrated collection bags are automating infection risk reduction for immunocompromised users in Swedish home care programs. Coloplast's SpeediCath Compact system has established reference pricing for this configuration. Hospital procurement committees are automating preference toward systems with documented UTI reduction rates.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic clinical follow-up for hydrophilic coated devices. Manufacturers must maintain vigilance databases tracking adverse events across Swedish, Danish, and Norwegian patient populations. This regulatory architecture most heavily impacts indwelling catheter portfolios where long-term implantation data is sparse.
Patient-directed purchasing is fragmenting traditional supply relationships in Denmark's municipal home care sector. Individuals with spinal cord injuries are selecting catheter brands through personal health budgets rather than accepting hospital-assigned products. This behavioral shift concentrates in Copenhagen and Aarhus metropolitan regions where direct-to-patient distribution channels have achieved regulatory clearance.
Nordic Urinary Catheters Market Segmentation
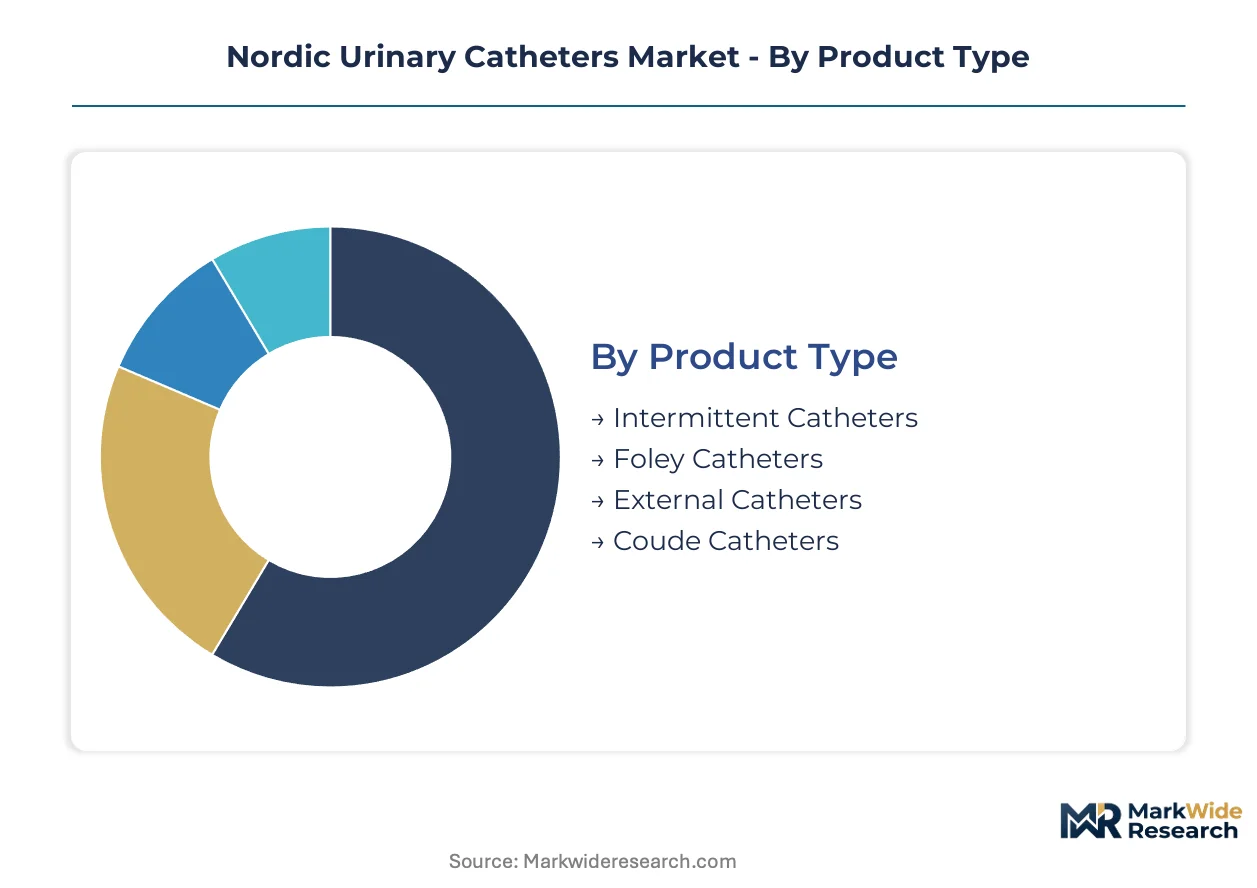
Nordic urinary catheter procurement operates through distinct technical and channel pathways. Segmentation reveals how intermittent self-catheterization protocols, silicone material transitions, and decentralized home care infrastructure reshape demand patterns across Denmark, Sweden, Norway, and Finland.
Product Type:
Standalone intermittent systems dominate patient-directed purchasing, while indwelling designs embed within hospital infection control bundles.
- Intermittent Catheters:Single-use hydrophilic-coated tubes, typically 8-14 French, designed for self-catheterization protocols. Swedish county councils and Denmark's municipal health services concentrate procurement through multi-year tenders favoring closed-system designs with integrated collection bags.
- Foley Catheters:Indwelling two-way or three-way balloon designs for continuous drainage. Norwegian regional health trusts and Finnish university hospitals anchor demand through critical care bundling with UTI surveillance systems.
- External Catheters:Condom-style sheaths for male urinary management. Home care programs in rural Denmark and coastal Norway apply these for ambulatory patients with intact bladder reflexes.
- Coude Catheters:Angled-tip designs navigating prostatic obstruction. Urology departments at Sweden's Karolinska University Hospital and Denmark's Rigshospitalet specify these for benign prostatic hyperplasia cases.
Intermittent catheters lead volumes today; closed-system configurations are gaining share fastest.
Material:
Cost tiers separate premium biocompatible formulations from commodity alternatives facing MDR compliance pressure.
- Silicone:Inert polymer tubing with superior biocompatibility and reduced encrustation risk. Sweden's medical device procurement networks and Norway's regional health authorities prioritize silicone for long-term indwelling applications under EU MDR biocompatibility standards.
- Hydrophilic Coated:Polymer surfaces activated by saline or water to reduce insertion friction. Danish spinal cord injury programs and Finnish home care services specify these for patient self-catheterization to minimize urethral trauma.
- Latex:Natural rubber formulations now restricted by allergy protocols. Remaining demand concentrates in legacy hospital contracts transitioning to synthetic alternatives.
- Polyvinyl Chloride:Rigid plastic tubing for short-term drainage. Cost-sensitive procurement in Finland's municipal health centers and Norway's nursing homes maintains limited PVC volume.
Silicone commands premium positioning; hydrophilic coated variants are expanding most quickly.
End User:
Customer type determines reimbursement pathway and product specification complexity.
- Hospitals:Acute care institutions with centralized procurement. Swedish county council purchasing consortia and Norway's four regional health trusts standardize on hydrophilic-coated single-use systems through framework agreements.
- Home Care:Decentralized municipal health services managing chronic patients. Denmark's 98 municipalities and Finland's welfare regions drive intermittent catheter volume through personal health budgets and direct-to-patient distribution.
- Long-term Care Facilities:Nursing homes and residential care settings. Staff-assisted catheterization in Swedish äldreboenden and Danish plejehjem favors pre-lubricated designs reducing handling steps.
- Rehabilitation Centers:Post-acute facilities retraining bladder function. Spinal cord injury units at Sweden's Sunnaas Hospital and Denmark's Hornbæk Neurorehabilitation Center prescribe intermittent protocols for independence training.
Home care channels lead volume expansion; hospital procurement retains value concentration.
Distribution Channel:
Supply concentration varies from direct manufacturer relationships to fragmented retail pharmacy networks.
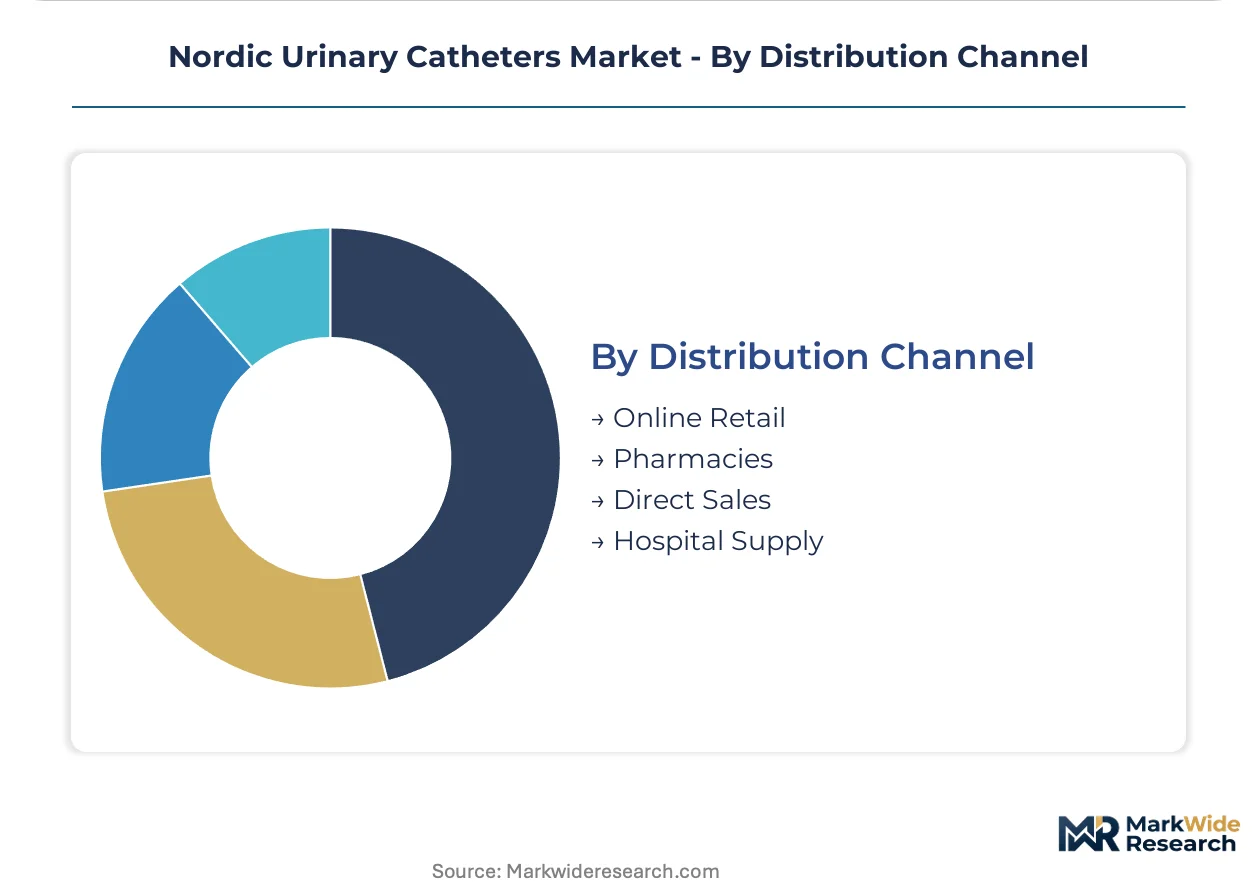
- Direct Sales:Manufacturer-to-institution contracts bypassing intermediaries. Coloplast and Wellspect HealthCare maintain dedicated account teams for Swedish county council and Norwegian regional health trust tenders.
- Hospital Supply:Group purchasing organizations aggregating demand. Denmark's Amgros and Norway's Sykehusinnkjøp HF coordinate multi-hospital framework agreements.
- Pharmacies:Community and hospital pharmacy dispensing. Finnish municipal pharmacies and Swedish Apoteket AB handle prescription intermittent catheters for home care patients.
- Online Retail:Direct-to-patient platforms with regulatory clearance. Danish personal health budget holders in Copenhagen and Aarhus metropolitan regions increasingly select brands through certified e-commerce channels.
Hospital supply dominates contract value; online retail channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's county council procurement networks anchor Nordic catheter demand through standardized hydrophilic-coated system tenders. Denmark's municipal health infrastructure decentralizes purchasing authority across 98 municipalities. Norway's regional health trust consolidations reshape multi-year supply contract structures.
Sweden
Swedish county councils concentrate intermittent catheter procurement through framework agreements favoring closed-system designs with integrated collection bags. The EU Medical Device Regulation's CE marking requirements filter market access toward manufacturers with established notified body relationships. Stockholm's Karolinska University Hospital and Gothenburg's Sahlgrenska University Hospital set specification standards that cascade through regional purchasing consortia.
Denmark
Denmark's 98 municipalities drive patient-directed purchasing through personal health budgets for spinal cord injury users. The Danish Medicines Agency enforces MDR compliance timelines for hydrophilic coated products entering home care channels. Copenhagen and Aarhus metropolitan regions host the densest concentration of direct-to-patient distribution platforms with regulatory clearance.
Norway
Norway's four regional health trusts consolidate acute care procurement for Foley catheter systems bundled with UTI surveillance technology. Sykehusinnkjøp HF coordinates multi-hospital framework agreements that standardize silicone material specifications. Bergen's Haukeland University Hospital and Oslo University Hospital anchor critical care demand for two-way and three-way balloon designs.
Finland
Finnish welfare regions present whitespace for intermittent catheter education programs in rural municipalities with underdeveloped self-catheterization adoption. The Finnish Medicines Agency Fimea oversees MDR transition compliance for hydrophilic coated devices entering home care. Helsinki University Hospital and Tampere University Hospital anchor urology department demand for Coude-tip designs navigating prostatic obstruction cases.
Nordic Urinary Catheters Market Competitive Landscape
Global majors compete with regional champions across material specialization and coating chemistry dimensions. The vendor base stratifies into three tiers: diversified medical device conglomerates with broad urology portfolios, mid-scale specialists focused on intermittent catheter systems, and regional distributors with notified body relationships accelerating MDR compliance. Market structure rewards backward integration into medical-grade silicone supply and captive hydrophilic coating chemistry capabilities. Two dominant competitive moves include strategic partnerships with Nordic hospital supply organizations and portfolio diversification into closed-system intermittent designs.
Within the regional specialist tier, Coloplast A/S and Wellspect HealthCare occupy positions exemplifying deep specialization in self-catheterization systems. B. Braun SE represents the scale-driven conglomerate archetype with manufacturing breadth serving Norway's regional health authorities. Among these, Danish and Swedish-originated entities anchor positions through proximity to county council and municipal procurement networks.
| Leading Market Players |
|---|
| B. Braun SE |
| Teleflex Incorporated |
| Coloplast A/S |
| Becton, Dickinson and Company |
| Hollister Incorporated |
| Wellspect HealthCare |
| ConvaTec Group Plc |
| Dentsply Sirona |
| BACTIGUARD |
| Others |
Value Network & Pricing Analysis
MDR certification tiers bifurcate Nordic catheter economics, with CE-marked silicone and hydrophilic-coated systems commanding 40-60% premiums over legacy latex alternatives while concentrating procurement toward manufacturers with established notified body relationships. This tier divergence manifests in supply chain configurations where Swedish county councils and Norwegian regional health trusts mandate dual-qualified suppliers, forcing distributors to maintain parallel inventory streams across compliance grades.
Pricing Analysis
Medical-grade silicone feedstock pass-through dominates Nordic catheter pricing dynamics, with European chemical suppliers transmitting polymer cost volatility directly to device manufacturers. Pricing stratifies across premium, standard, and economy tiers where MDR biocompatibility certification and hydrophilic coating chemistry anchor premium positioning. Cost compression in latex-alternative segments intensifies as Danish municipal buyers consolidate volume through framework agreements. Hospital procurement committees exhibit lowest price sensitivity, prioritizing infection control documentation over per-unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Swedish county councils and Norway's Sykehusinnkjøp HF mandate multi-supplier qualification for silicone tubing and hydrophilic coating chemistries, preventing single-source dependency despite concentrated European polymer production. Supply chains draw from Germany, France, and Belgium for medical-grade silicone resins, with coating substrates sourced from specialized chemical processors in Switzerland and the Netherlands. Single-source vulnerability concentrates in hydrophilic polymer formulations where patent-protected surface technologies limit qualified suppliers. Distribution runs through hospital supply organizations and direct manufacturer contracts, with Danish municipal channels fragmenting toward pharmacy and certified e-commerce endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nordic urinary catheters function as a stable compounder anchored by irreversible home care infrastructure expansion across Denmark's 98 municipalities and Sweden's county council networks.
For Market Incumbents: Deepen backward integration into medical-grade silicone supply to insulate margin structures from European chemical supplier allocation constraints. Fortify notified body relationships ahead of MDR post-market surveillance intensification for indwelling portfolios, where long-term implantation data gaps expose compliance vulnerability. Prioritize closed-system intermittent catheter capacity expansion to capture Swedish procurement standardization toward integrated collection bag designs. For New Entrants and Emerging Players: Capture Finnish rural municipality whitespace through spinal cord injury self-catheterization education partnerships, where intermittent protocol penetration lags Swedish and Danish benchmarks. Exploit telehealth-integrated prescription channels bypassing traditional hospital procurement in Denmark's personal health budget segments. Lead with ISO 14001-certified production credentials to satisfy Swedish county council sustainability mandates in green procurement evaluations. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR compliance costs and notified body capacity constraints strand sub-scale manufacturers without clinical evidence portfolios. Frame long-term viability around compound annual expansion in home care channels rather than hospital volume concentration. Target acquisition profiles emphasizing hydrophilic coating chemistry captive capabilities and established Nordic GPO contract relationships. Monitor Norwegian regional health trust procurement consolidation announcements as inflection signals for multi-year supply agreement restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR biocompatibility documentation filters market access toward notified body-anchored manufacturers. |
| Hospital System Partnership | Swedish county council framework agreements standardize hydrophilic-coated system specifications across regional networks. |
| Backward Integration | In-house medical-grade silicone extrusion insulates margin structures from European polymer supplier volatility. |
| Software Companion Development | Telehealth-integrated adherence tracking creates digital prescription channels bypassing traditional procurement. |
| Reimbursement Strategy | Personal health budget eligibility in Danish municipalities fragments supply relationships toward patient-directed purchasing. |
Research Methodology
Coverage spans Denmark, Sweden, Norway, and Finland, with primary inputs from each Nordic market's hospital procurement committees, municipal health service directors, spinal cord injury rehabilitation clinicians, and medical device regulatory affairs specialists. Secondary validation draws from EU MDR guidance documents, Swedish county council tender databases, Norwegian regional health trust supply agreements, and Danish Medicines Agency registration filings. Bottom-up demand modeling across intermittent, Foley, and external catheter segments triangulates against top-down health expenditure data from national statistical institutes.
Rate-of-change decomposition separates volume expansion in home care channels from value migration toward hydrophilic-coated and closed-system configurations across the projection horizon. Segmentation dimensions include product type, material formulation, end-user setting, and distribution channel, with regional regulatory cluster effects modeled separately. CAGRs derive from logistic diffusion curves fitted to intermittent catheter protocol adoption rates and silicone material substitution patterns. Forecast inputs incorporate EU MDR transition timelines and Norwegian regional health trust consolidation schedules.
Notified body capacity constraints, medical-grade silicone supply disruptions, and Finnish home care penetration delays are the dominant revision risks to demand assumptions. Deviation in MDR post-market surveillance enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Genitourinary Cancers Treatment Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Urology Lasers Market
Urology
India Urology Device Market
Urology
Varicocele Treatment Market
Urology
Single Use Cystoscope Market
Urology
Ureterorenoscopes Market
Urology
Primary Aldosteronism Market
Urology
North America Bladder Disorders Market
Urology
Obstructive Uropathy Treatment Market
Urology
India Urology Market
Urology
Ureteral Obstruction Market
Urology
Urology Ultrasound Market
Urology
Global Castrate Resistant Prostate Cancer Market