
 Checkpoint Inhibitor Refractory Cancer Market | 2026-2036
Checkpoint Inhibitor Refractory Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Checkpoint Inhibitor Refractory Cancer Market Analysis
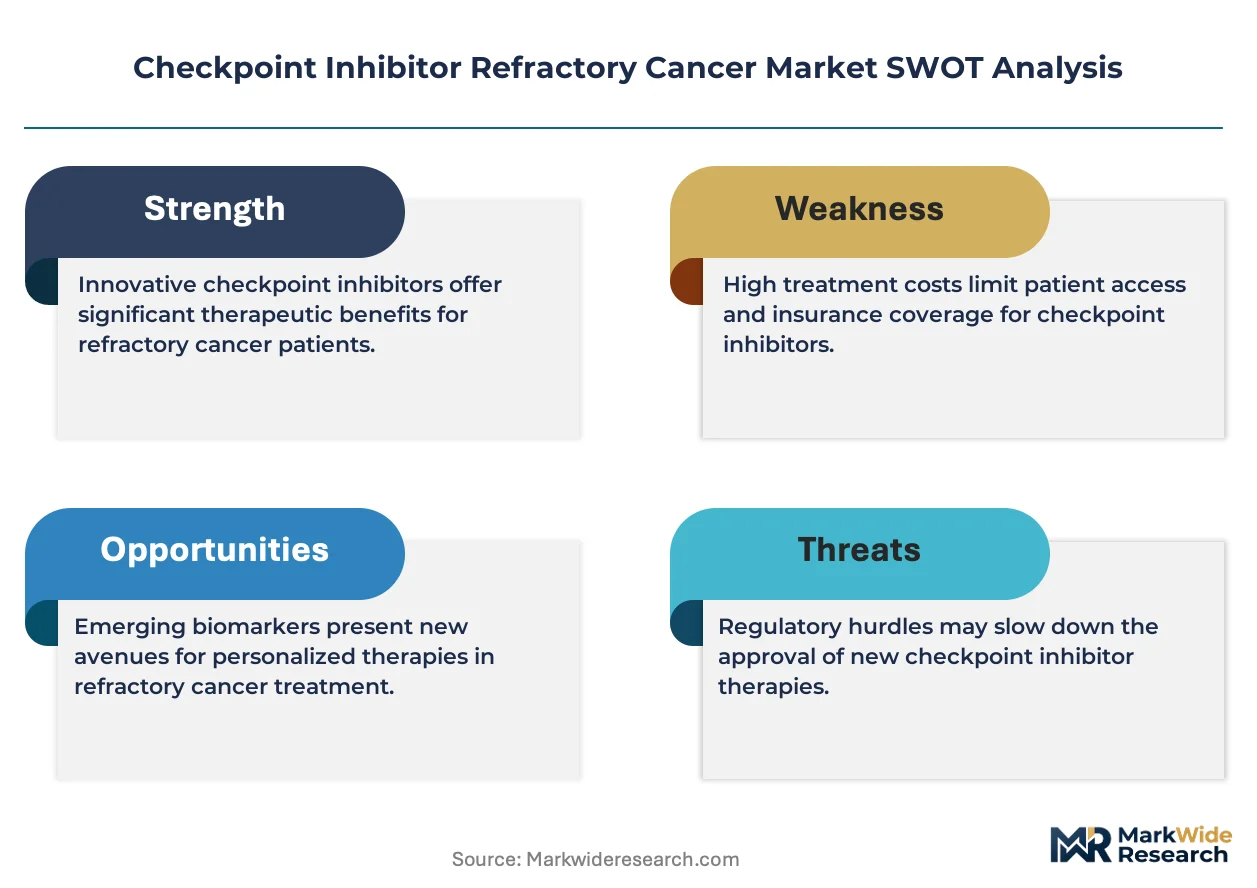
FDA Breakthrough Therapy Designation is reorganizing which developers can command physician trust and payer coverage in refractory settings. Bristol Myers Squibb leverages its established immuno-oncology infrastructure to sustain trial recruitment across melanoma and lung indications. Roche anchors its position through companion diagnostic integration that matches refractory patients to targeted combinations. Merck & Co. competes by extending its PD-1 franchise into novel combination regimens for non-responders.
Checkpoint inhibitor refractory cancer denotes malignancies that progress despite prior anti-PD-1 or anti-CTLA-4 therapy, requiring agents that activate alternative immune pathways such as LAG-3, TIGIT, or personalized neoantigen approaches. The primary purpose is to restore anti-tumor immunity in patients who have exhausted first-line immunotherapy options. Combination therapy commands the deepest investment pipelines as developers stack mechanisms to overcome resistance. Monoclonal antibodies retain the largest current revenue base, though small molecules targeting intracellular immune checkpoints represent the fastest-emerging modality. Intravenous delivery dominates hospital and clinic administration, while subcutaneous formulations are gaining traction in outpatient settings seeking reduced chair time.
The FDA, EMA, and China's NMPA each enforce distinct evidentiary thresholds for refractory cancer approvals, with the FDA's accelerated pathway permitting earlier commercial entry based on single-arm response data. These divergent standards fragment trial design and launch sequencing across jurisdictions. Payers in Europe and the United States increasingly demand head-to-head survival data before granting premium reimbursement for second-line immunotherapy. Stakeholders must monitor which regulatory body first validates a novel mechanism, as that geography typically anchors global pricing and indication expansion.
Market Dynamics
The central structural force reshaping this market is the FDA's accelerated approval pathway, which compresses commercial entry timelines for breakthrough combination therapies and forces developers to pre-position manufacturing and payer contracting before confirmatory data readouts.
Growth Catalysts
- Regulatory Innovation:The FDA's Breakthrough Therapy Designation shortens development cycles for refractory indications, enabling earlier physician access to novel mechanisms targeting LAG-3 and TIGIT pathways.
- Companion Diagnostic Integration:Biomarker-driven patient stratification is expanding addressable populations by identifying non-responders most likely to benefit from alternative immune checkpoint blockade.
- Specialized Treatment Infrastructure:Major oncology centers in the United States are building dedicated refractory cancer units that streamline trial enrollment and combination therapy administration.
Market Restraints
- Biologics Manufacturing Concentration:Contract development and manufacturing organizations in the United States and Switzerland control critical capacity for complex antibody production, creating supply bottlenecks for novel combinations.
- Reimbursement Evidence Requirements:CMS and major commercial payers now mandate head-to-head overall survival data before granting premium pricing for second-line immunotherapy, extending time-to-revenue for new entrants.
- Patient Pool Fragmentation:Refractory status varies across tumor types, complicating trial design and limiting the scalability of single-mechanism approaches across oncology indications.
Strategic Opportunities
- Subcutaneous Formulation Development:Outpatient administration models in Germany and the United Kingdom are creating pull for reduced chair-time delivery systems that shift care from infusion centers to community oncology practices.
- Personalized Neoantigen Platforms:Convergence of next-generation sequencing and AI-driven epitope prediction is opening individualized vaccine approaches for patients with exhausted PD-1 pathways.
- China Market Entry:The NMPA's evolving priority review pathways for innovative oncology therapies offer early-mover advantages for developers with refractory-specific clinical data packages.
Industry Challenges
- Immuno-oncology Talent Scarcity:Experienced clinical investigators capable of designing resistance-mechanism trials are concentrated at fewer than twenty academic medical centers worldwide, constraining trial velocity.
- Combination Therapy Complexity:Stacking multiple biologics creates unpredictable pharmacokinetic interactions and toxicity profiles that extend dose-finding phases and complicate regulatory filings.
- Legacy Trial Infrastructure:Existing electronic data capture systems at many sites lack flexibility to accommodate adaptive trial designs required for rapid biomarker-driven patient selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Checkpoint Inhibitor Refractory Cancer Market |
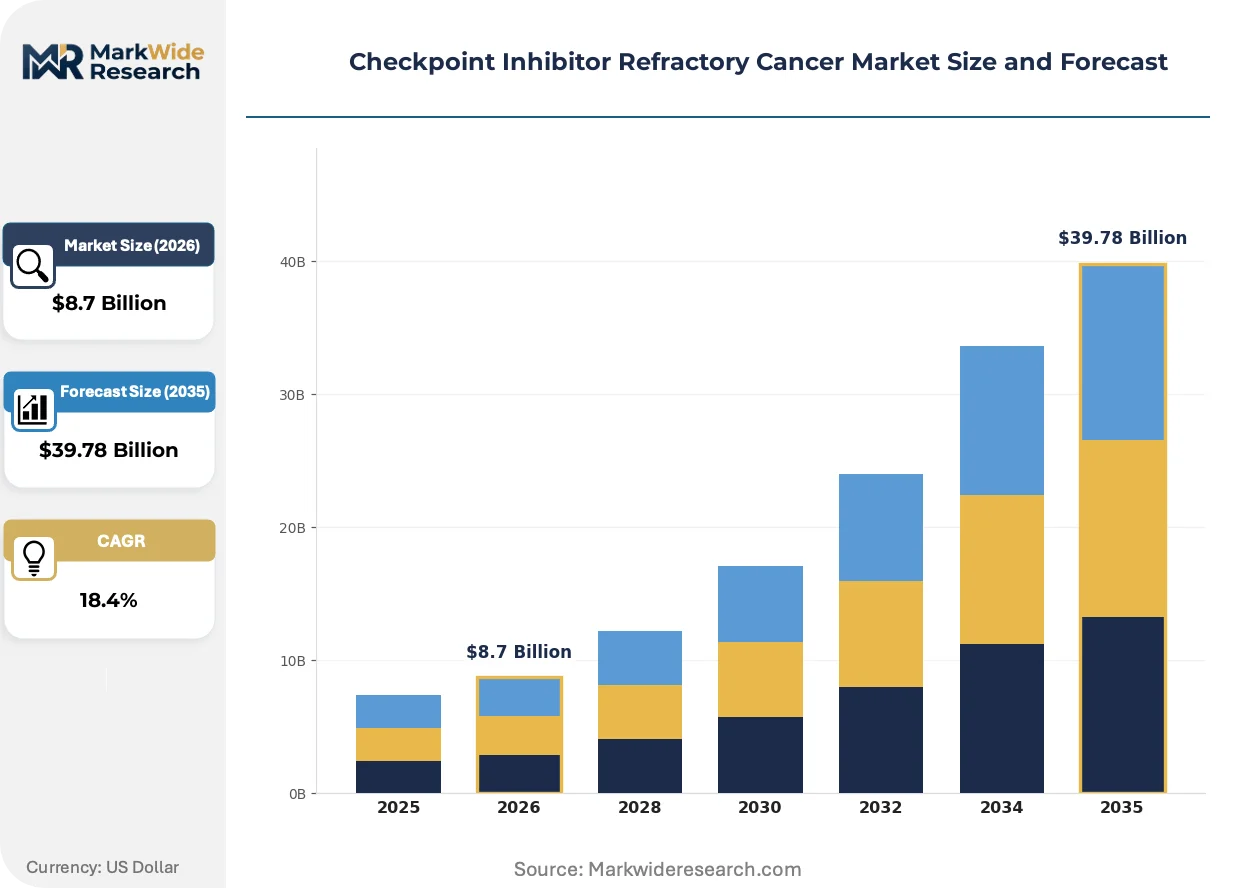
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Melanoma, Non-Small Cell Lung Cancer, Head and Neck Cancer, Renal Cell Carcinoma End User: Oncology Clinics, Research Institutes, Hospitals, Homecare Settings Product Type: Monoclonal Antibodies, Combination Therapy, Small Molecules, Vaccines Delivery Mode: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | Roche, MacroGenics, Bristol Myers Squibb, Innovent Biologics, Adaptimmune, Merck & Co., Gilead Sciences, Exelixis, Iovance Biotherapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Checkpoint Inhibitor Refractory Cancer Market Emerging Trajectories
Bi-modal therapy development is fragmenting traditional oncology pipelines as developers simultaneously pursue targeted small molecules and immune-modulating biologics for overlapping refractory populations.
Bispecific antibodies engaging dual immune checkpoints are fragmenting the monoclonal antibody paradigm by enabling single-agent activity against T-cell exhaustion mechanisms that required previous combination regimens. Academic medical centers in Boston and Houston are adopting these constructs for early-phase trials at twice the rate of standard antibody combinations. The technology is fragmenting competitive moats by reducing the IP complexity of multi-target blockade.
The EMA's adaptive pathway pilot for oncology therapies is compressing conditional marketing authorization timelines, forcing sponsors to commit to post-authorization evidence generation before full dataset maturity. This regulatory innovation pressures smaller developers to secure European commercial partnerships earlier in development. Combination therapies with companion diagnostics face the steepest evidentiary requirements under this framework.
Oncology purchasing committees are consolidating vendor relationships for refractory therapy portfolios, replacing fragmented single-product contracts with mechanism-class agreements that span multiple indications. Hospital systems in the United States are leading this consolidation, using volume commitments across melanoma, lung, and renal cell carcinoma to extract pricing concessions. The shift is most visible in integrated delivery networks that own both specialty pharmacy and infusion center assets.
Checkpoint Inhibitor Refractory Cancer Market Segmentation
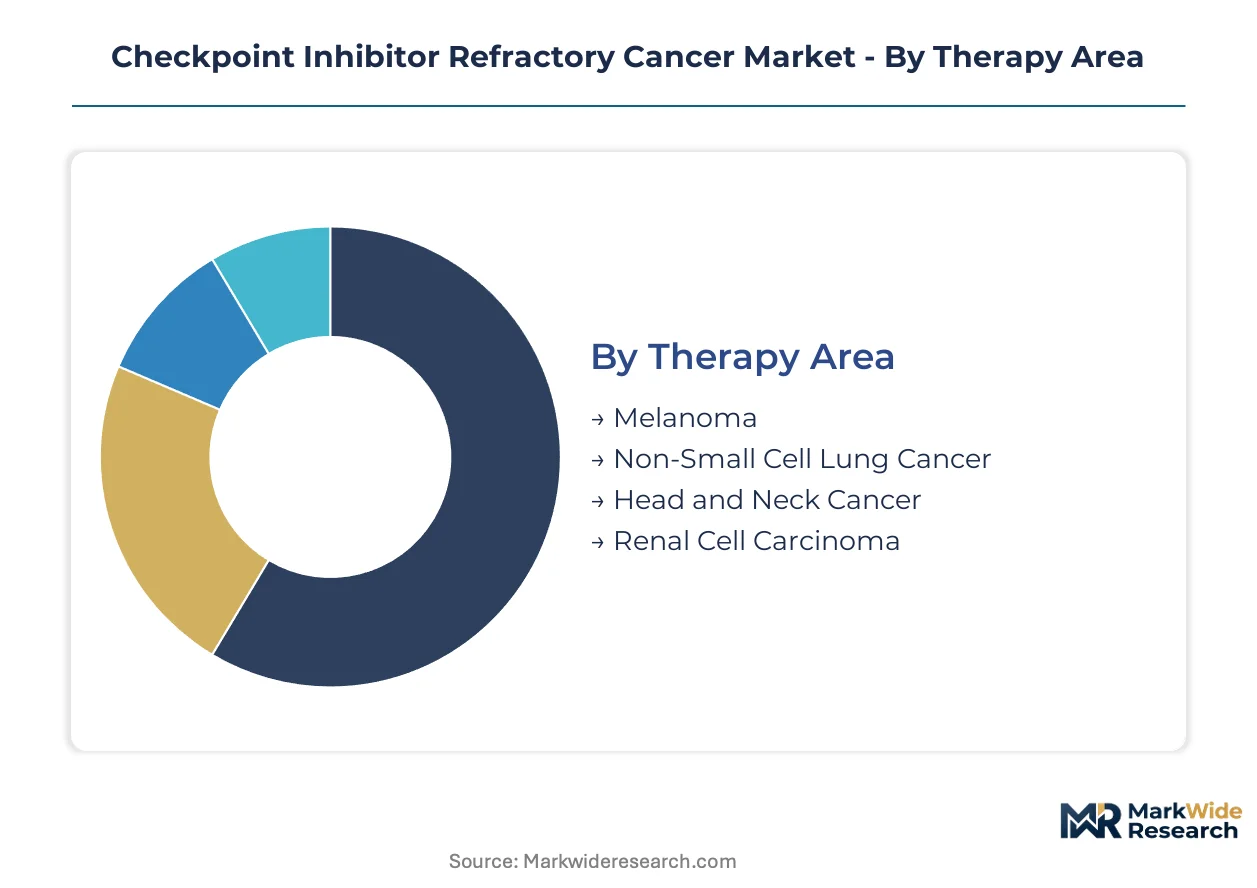
Checkpoint inhibitor refractory cancer treatment stratifies across four critical dimensions that determine reimbursement pathways, clinical trial design, and manufacturing scale. Each segmentation layer reveals distinct margin architectures and competitive entry points for developers targeting exhausted PD-1 pathways.
Therapy Area:
Melanoma commands the deepest margin pools due to established biomarker infrastructure and concentrated specialist referral networks, while lung cancer volumes anchor manufacturing scale commitments.
- Melanoma:Refractory melanoma patients exhibit the highest density of actionable mutations and established LAG-3 combination protocols. United States academic centers in Boston and Houston drive demand concentration through dedicated resistance mechanism trials, though payer scrutiny intensifies for third-line regimens.
- Non-Small Cell Lung Cancer:NSCLC refractory populations represent the largest addressable volume across oncology indications. China's NMPA priority review pathway accelerates entry for TIGIT-targeting combinations, while European EMA adaptive pathways demand earlier companion diagnostic commitments.
- Head and Neck Cancer:Squamous cell carcinomas of the head and neck show heterogeneous resistance patterns requiring individualized neoantigen approaches.
- Renal Cell Carcinoma:RCC refractory status often emerges after sequential VEGF and checkpoint inhibition, creating demand for novel cytokine modulation.
The dominant share belongs to Non-Small Cell Lung Cancer, while Melanoma is closing the gap fastest through biomarker-enriched trial designs.
End User:
Institutional purchasing power concentrates in integrated delivery networks that own infusion capacity, shifting procurement decisions away from individual physicians toward committee-based mechanism-class contracting.
- Oncology Clinics:Community oncology practices in Germany and the United Kingdom are expanding subcutaneous administration capacity to reduce hospital dependency. These sites prioritize reduced chair-time protocols that shift revenue from infusion centers to specialty pharmacy dispensing.
- Hospitals:United States hospital systems with captive specialty pharmacy assets leverage volume commitments across melanoma, lung, and renal indications to extract pricing concessions from manufacturers.
- Research Institutes:Academic medical centers conduct early-phase trials for bispecific antibodies and personalized neoantigen platforms.
- Homecare Settings:Subcutaneous formulation advances enable administration outside traditional clinical infrastructure.
Oncology Clinics capture the highest patient throughput, though Hospitals are expanding their refractory service lines most aggressively through vertical integration into specialty pharmacy.
Product Type:
Biologics manufacturing complexity creates margin tiering that favors developers with captive antibody production capacity over those dependent on contract manufacturing organizations.
- Monoclonal Antibodies:Established anti-PD-1 and emerging anti-LAG-3 antibodies retain the largest current revenue base. FDA Breakthrough Therapy Designation compresses development timelines for refractory indications, though confirmatory survival data requirements extend time-to-revenue.
- Combination Therapy:Stacked checkpoint blockade commands the deepest investment pipelines as developers pursue simultaneous LAG-3 and TIGIT inhibition. Pharmacokinetic unpredictability extends dose-finding phases and complicates regulatory filings across FDA, EMA, and NMPA jurisdictions.
- Small Molecules:Intracellular immune checkpoint inhibitors represent the fastest-emerging modality with oral bioavailability advantages.
- Vaccines:Personalized neoantigen platforms converge next-generation sequencing with AI-driven epitope prediction for individualized approaches.
Monoclonal Antibodies maintain revenue leadership, while Combination Therapy is climbing the fastest through mechanism-stacking investment intensity.
Delivery Mode:
Administration route determines site-of-care economics and patient compliance profiles, with subcutaneous advances threatening traditional intravenous revenue models in outpatient settings.
- Intravenous:Hospital and clinic administration dominates current revenue through established infusion center infrastructure. United States oncology centers maintain this preference for complex combination regimens requiring monitoring.
- Subcutaneous:Outpatient models in Germany and the United Kingdom create pull for reduced chair-time delivery systems. Community oncology practices favor these formulations for patient convenience and capacity optimization.
- Oral:Small molecule immune modulators enable administration outside clinical settings.
- Topical:Localized delivery for cutaneous metastases in refractory melanoma.
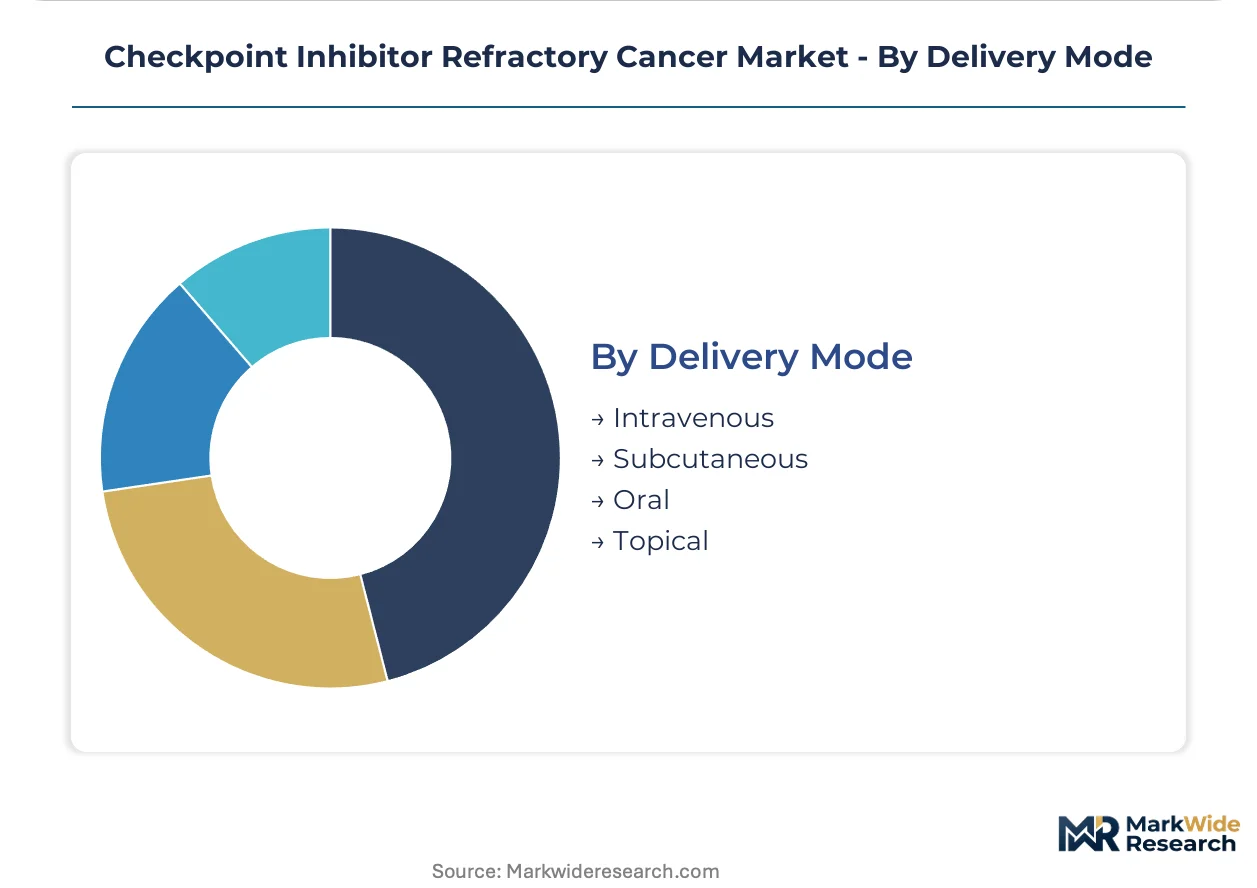
Intravenous delivery retains institutional dominance, while Subcutaneous formulations are gaining share fastest through outpatient practice expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist treatment centers and late-stage trial infrastructure concentrate demand among United States academic medical centers, German university hospitals, and Chinese tertiary oncology facilities, with reimbursement pathways and regulatory approval timelines determining geographic entry sequencing for refractory combination therapies.
United States
Memorial Sloan Kettering Cancer Center and MD Anderson anchor clinical trial recruitment for LAG-3 and TIGIT combinations. FDA Breakthrough Therapy Designation compresses development timelines for refractory melanoma and lung indications. The Boston-Houston corridor dominates bispecific antibody early-phase enrollment through dedicated resistance mechanism research units.
Germany
Community oncology practices in Bavaria and North Rhine-Westphalia expand subcutaneous administration capacity to reduce hospital dependency. EMA adaptive pathway pilots compress conditional marketing authorization timelines for companion diagnostic-linked combinations. The Munich-Düsseldorf axis leads outpatient refractory care model adoption through integrated cancer center networks.
China
NMPA priority review pathways accelerate entry for domestic and multinational developers with refractory-specific data packages. Shanghai and Beijing tertiary oncology centers concentrate TIGIT-targeting combination trials for non-small cell lung cancer. The Yangtze River Delta region anchors manufacturing scale commitments for novel checkpoint inhibitors.
United Kingdom
NHS England's Cancer Drugs Fund creates conditional reimbursement mechanisms for refractory immunotherapy combinations pending survival data maturity. The London-Oxford-Cambridge triangle concentrates academic investigator sites for personalized neoantigen platform trials. Manchester and Birmingham expand community infusion capacity for reduced chair-time protocols.
Switzerland
Swissmedic's rapid authorization procedures for breakthrough oncology therapies attract European headquarters placement for refractory-focused developers. Basel and Zurich anchor companion diagnostic manufacturing and precision medicine infrastructure. The country's contract development organizations supply critical antibody production capacity for global combination therapy pipelines.
Checkpoint Inhibitor Refractory Cancer Market Vendor Landscape
Player mix skews toward established immuno-oncology platforms with captive manufacturing infrastructure and emerging biotechs specializing in resistance mechanism biology. Large-cap pharmaceutical developers leverage PD-1 franchise extensions into novel combinations, while mid-scale innovators concentrate on bispecific constructs and personalized neoantigen approaches. Competitive moves center on companion diagnostic integration partnerships and subcutaneous formulation licensing to capture outpatient administration economics.
Among established immuno-oncology developers, Bristol Myers Squibb, Roche, and Merck & Co. exemplify platform-scale archetypes with integrated diagnostic and therapeutic portfolios. Roche represents the companion diagnostic-anchored model through biomarker-driven patient stratification systems. Bristol Myers Squibb occupies a position emphasizing melanoma and lung indication depth with established resistance mechanism trial infrastructure. Merck & Co. sits within the PD-1 franchise extension archetype, pursuing novel combination regimens for non-responders through mechanism-stacking approaches.
| Leading Market Players |
|---|
| Roche |
| MacroGenics |
| Bristol Myers Squibb |
| Innovent Biologics |
| Adaptimmune |
| Merck & Co. |
| Gilead Sciences |
| Exelixis |
| Iovance Biotherapeutics |
| Others |
Supply Flow & Price Mechanics
Biologics manufacturing scale economies in the United States and Switzerland establish minimum efficient scale thresholds that concentrate supply among contract development organizations with captive antibody production capacity, simultaneously elevating price floors for novel checkpoint inhibitor combinations and compressing margins for developers lacking backward integration into manufacturing infrastructure.
Pricing Analysis
Cost-plus contracts with biologics manufacturers index active pharmaceutical ingredient costs to fermentation batch yields and purification efficiency metrics. Pricing stratifies across premium, standard, and economy tiers based on companion diagnostic bundling and infusion center administration requirements. Cost compression in second-line regimens is intensifying because CMS and commercial payers mandate head-to-head survival data before granting premium reimbursement. Community oncology practices exhibit the highest price sensitivity due to thin specialty pharmacy margins, while integrated delivery networks with captive infusion assets negotiate mechanism-class volume discounts across melanoma and lung indications.
Supply Chain Analysis
The United States and Switzerland anchor mammalian cell culture capacity for monoclonal antibody production, while China concentrates fill-finish operations and secondary packaging for Asian distribution. Critical inputs draw from German stainless-steel bioreactor engineering, Singaporean single-use technology platforms, and Irish downstream processing equipment. Single-source vulnerability concentrates in viral vector supply for personalized neoantigen platforms. Distribution runs through specialty pharmacy networks with cold-chain custody requirements, shifting downstream control toward hospital systems with integrated dispensing assets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Checkpoint inhibitor refractory cancer treatment is approaching a platform-economics inflection where companion diagnostic interoperability determines formulary placement, with FDA-EMA diagnostic harmonization creating ecosystem lock-in advantages for developers with pre-positioned biomarker infrastructure.
For Market Incumbents: Secure companion diagnostic exclusivity through locked-in partnerships with sequencing platform providers, insulating against emerging entrants with AI-driven epitope prediction capabilities. Lock in subcutaneous formulation licensing agreements with German and United Kingdom community oncology networks before biosimilar pressure commoditizes intravenous administration revenue pools. Backward integration into viral vector manufacturing reduces single-source dependency for personalized neoantigen pipeline candidates. For New Entrants and Emerging Players: FDA Breakthrough Therapy Designation fast-tracks provide regulatory validation shortcuts for bispecific antibodies targeting dual checkpoint exhaustion mechanisms. White-space concentration sits with TIGIT-PD-1 combinations for non-small cell lung cancer in China, where NMPA priority review accelerates commercial entry ahead of EMA adaptive pathway timelines. Go-to-market positioning through academic medical center research institute partnerships in Boston and Houston anchors early-phase investigator relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors developers with validated resistance mechanism biology platforms over single-asset monoclonal antibody plays. Long-term viability hinges on manufacturing scale flexibility across batch and continuous processing modalities. Acquisition target archetypes include bispecific antibody specialists with IND-ready TIGIT constructs and companion diagnostic co-development agreements. The signal to watch is EMA conditional marketing authorization conversion rates for LAG-3 combinations, indicating regulatory risk appetite for single-arm response data.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Biomarker-driven patient stratification expands addressable refractory populations for Roche and Bristol Myers Squibb. |
| Subcutaneous Formulation Development | Reduced chair-time protocols shift revenue from United States infusion centers to German community oncology practices. |
| Breakthrough Therapy Designation Pursuit | FDA accelerated approval compresses commercial entry timelines for LAG-3 and TIGIT-targeting combinations. |
| China NMPA Priority Review Entry | Early-mover advantages accrue to developers with refractory-specific clinical data packages in Shanghai and Beijing. |
| Personalized Neoantigen Platform Buildout | AI-driven epitope prediction converges with next-generation sequencing for individualized vaccine approaches. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA Breakthrough Therapy Designation records, EMA adaptive pathway submissions, ClinicalTrials.gov protocol registrations, and formulary database entries. Primary interviews engaged drug development executives at immuno-oncology platforms, regulatory affairs leads navigating multi-jurisdictional filings, hospital procurement managers at integrated delivery networks, and payer access specialists at major commercial insurers. Bottom-up patient-flow modeling triangulates against top-down manufacturer revenue disclosures and therapy area prescription audits.
Segmentation dimensions modeled span therapy area, end-user institution type, product modality, and delivery route across the projection horizon. Treatment line stratification distinguishes first-refractory from multiply-refractory populations, while regional regulatory clusters capture FDA, EMA, and NMPA pathway heterogeneity. Compound annual growth rates derive from patient incidence projections, therapy penetration curves, and pricing elasticity assumptions calibrated to payer reimbursement policy shifts. Forecast inputs incorporate biomarker testing adoption rates and manufacturing capacity expansion timelines for mammalian cell culture.
Decision-makers should treat outputs as directional under assumptions of sustained FDA accelerated approval pathway stability and continued companion diagnostic co-development incentives; material deviation in regulatory evidentiary thresholds or reimbursement policy would warrant model refresh. Specific risk factors include EMA conditional marketing authorization revocation patterns, CMS national coverage determination reversals for second-line immunotherapy, and biologics manufacturing contamination events at contract development organizations. Recalibration cycles align with material shifts in regulatory pathway precedents, payer formulary policy, and manufacturing capacity utilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Glioma Therapeutics Market