
 Penile Cancer Market | 2026-2036
Penile Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Penile Cancer Market Outlook
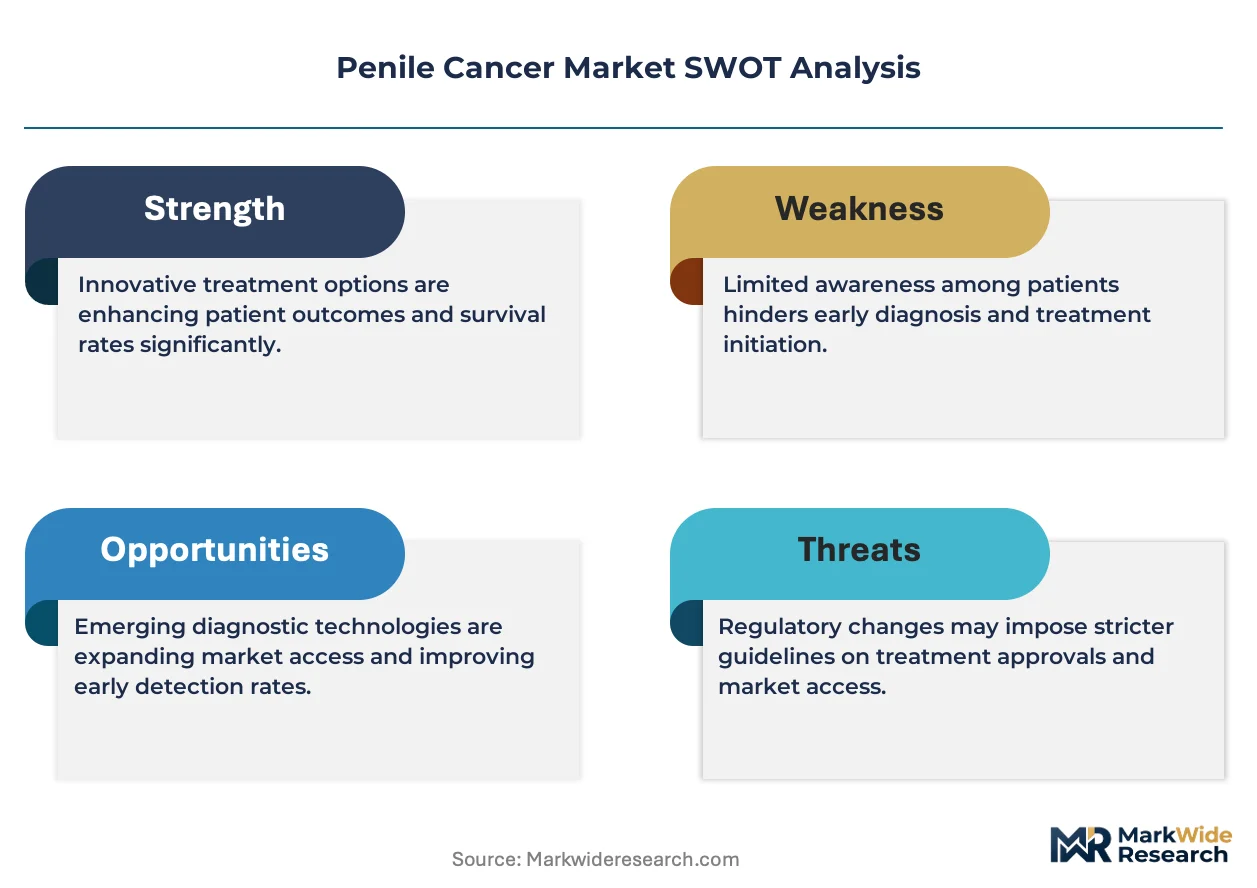
Academic medical centers are redrawing procurement priorities for penile cancer therapeutics, shifting volume toward institutions with dedicated sarcoma and genitourinary programs. F. Hoffmann-La Roche Ltd. anchors its position through deep vertical integration in diagnostic companion testing. AstraZeneca PLC leverages extensive immuno-oncology portfolios to compete in combination therapy trials. Pfizer Inc. sustains manufacturing scale across cytotoxic and targeted agent categories.
Penile cancer encompasses malignant neoplasms arising from penile epithelial tissue, predominantly squamous cell carcinoma originating in the glans or foreskin, with staging based on depth of invasion and nodal involvement. The condition demands multidisciplinary management integrating surgical excision, lymph node assessment, and systemic therapy to preserve organ function and control metastatic spread. Immunotherapy represents the fastest-growing product type as checkpoint inhibitors expand into HPV-related malignancies with favorable toxicity profiles. Hospitals dominate the application landscape, absorbing complex surgical cases and infused regimens that require inpatient monitoring. Intravenous delivery mode captures the largest volume share, though oral agents are gaining ground in maintenance settings where patient convenience drives protocol design.
The FDA's orphan drug designation program and EMA's PRIME pathway for rare cancers accelerate market access for novel penile cancer therapies, while WHO classification updates standardize histopathological reporting across jurisdictions. These frameworks elevate evidence requirements for reimbursement but simultaneously reduce development timelines for qualifying sponsors. Stakeholders must monitor evolving biomarker definitions and companion diagnostic partnerships that increasingly determine formulary placement and prescribing pathways.
Market Dynamics
The penile cancer therapeutic landscape is restructuring around accelerated regulatory pathways that compress development timelines for rare oncology indications. FDA's orphan drug incentives and EMA's PRIME designation are redrawing competitive entry sequences, favoring sponsors with pre-positioned diagnostic partnerships and existing immuno-oncology infrastructure.
Growth Catalysts
- HPV-related malignancy protocols:Checkpoint inhibitors are expanding into virally-driven penile squamous cell carcinoma subtypes, with PD-1/PD-L1 blockade demonstrating durable responses in previously refractory populations. Academic medical centers in the United States are prioritizing these combinations in first-line metastatic settings.
- EMA PRIME pathway acceleration:The European Medicines Agency's priority medicines scheme reduces regulatory review timelines for rare cancer therapies, enabling faster market access for novel systemic agents targeting advanced penile cancer stages.
- Multidisciplinary tumor boards:Dedicated uro-oncology centers in Germany and Japan are institutionalizing integrated surgical-medical oncology workflows that standardize neoadjuvant systemic therapy adoption and expand eligible patient pools for organ-sparing approaches.
Market Restraints
- Platinum agent supply concentration:Cisplatin and carboplatin active pharmaceutical ingredient manufacturing concentrates in Chinese and Indian chemical synthesis facilities, exposing formulation sponsors to geopolitical disruption and quality variability risks.
- Small patient cohort enrollment:The ultra-rare incidence of penile cancer creates statistical powering challenges for randomized controlled trials, forcing reliance on single-arm studies that complicate payer value demonstration.
- Surgical modality substitution:Mohs micrographic surgery and laser excision techniques for early-stage disease limit addressable populations for systemic therapy developers, compressing the targetable metastatic and locally advanced segments.
Strategic Opportunities
- Brazilian public health system penetration:ANVISA's expanded access programs for oncology medicines create a pathway for biosimilar and originator systemic agents to reach underserved penile cancer populations through the Sistema Único de Saúde network.
- Companion diagnostic co-development:PD-L1 expression assays and HPV genotyping platforms are converging with therapeutic development, enabling biomarker-selected enrollment that de-risks clinical programs and accelerates regulatory approval.
- Home infusion channel expansion:Oral targeted agents and subcutaneous immunotherapy formulations are enabling outpatient maintenance protocols that reduce hospital bed utilization and align with patient preference for community-based care delivery.
Industry Challenges
- Uro-oncology specialist scarcity:Fellowship-trained genitourinary surgical oncologists and medical oncologists with penile cancer expertise concentrate in tertiary referral centers, creating access bottlenecks that delay definitive staging and treatment initiation.
- Inguinal lymph node dissection complexity:Sentinel lymph node biopsy technique standardization remains incomplete across institutions, generating staging heterogeneity that complicates cross-trial comparison and real-world evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Penile Cancer Market |
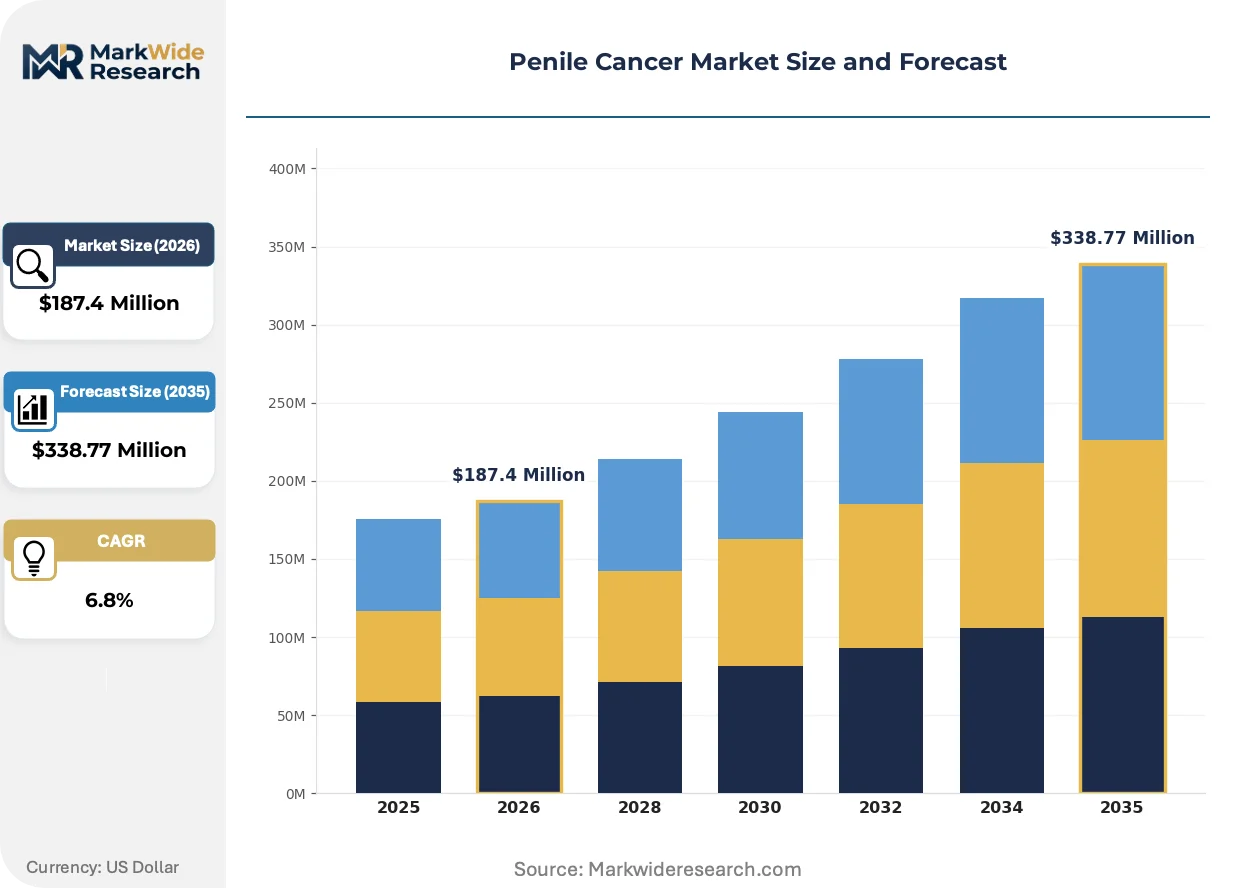
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Surgical Treatments Application: Hospitals, Clinics, Research Laboratories, Home Care End User: Oncologists, Urologists, Gynecologists, General Practitioners Delivery Mode: Intravenous, Oral, Topical, Subcutaneous |
| Companies Covered | F. Hoffmann-La Roche Ltd., AstraZeneca PLC, Pfizer Inc., GlaxoSmithKline plc, Sanofi S.A., Novartis AG, Bristol-Myers Squibb Company, Eli Lilly and Company, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Penile Cancer Market Strategic Shifts
Checkpoint inhibitor development is fragmenting the penile cancer systemic therapy landscape, displacing cytotoxic chemotherapy from later-line settings and enabling organ-sparing surgical approaches through neoadjuvant response. Diagnostic-therapeutic pairing is tightening as biomarker definitions mature.
Neoadjuvant immunotherapy protocols are fragmenting established treatment sequences in penile cancer management. Anti-PD-1 agents administered prior to definitive surgery are generating pathological complete response rates that enable penile-preserving procedures. Major cancer centers in the United States and Germany are adopting these regimens, compressing the historical dominance of upfront radical surgery and expanding the addressable population for systemic therapy developers.
REACH authorization requirements for hazardous pharmaceutical intermediates are tightening manufacturing compliance burdens for platinum-based cytotoxic agents used in penile cancer regimens. European contract manufacturing organizations are absorbing capital costs for containment infrastructure upgrades. Small-molecule targeted therapy sponsors with synthetic routes avoiding heavy metal catalysis are gaining competitive positioning in EU supply negotiations.
Academic medical center procurement committees are consolidating vendor relationships for penile cancer therapeutics around institutions with integrated diagnostic-pathology-oncology platforms. University hospitals in Japan are prioritizing suppliers offering companion testing bundled with therapeutic access. Community oncology practices without embedded molecular pathology capabilities are losing referral volume to these consolidated centers.
Penile Cancer Market Segmentation
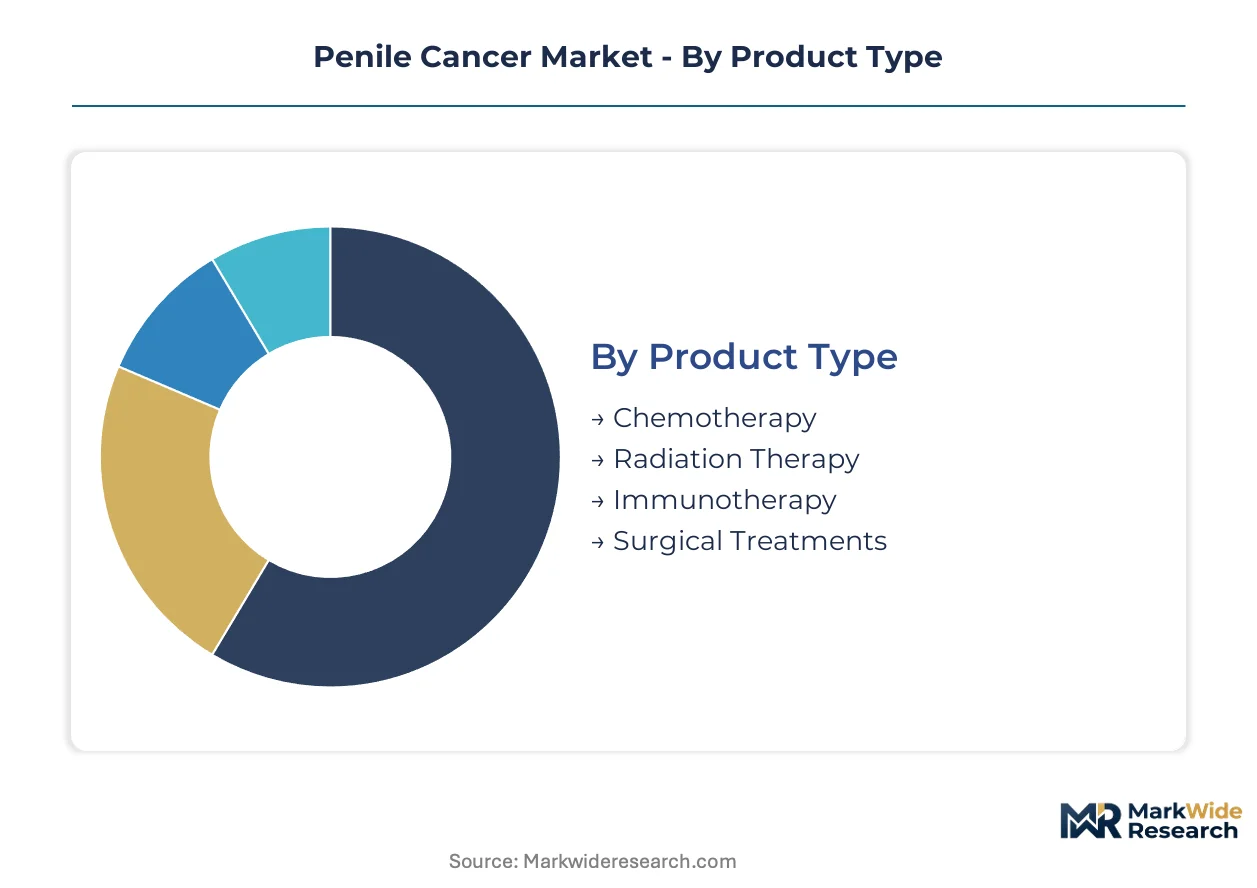
Penile cancer treatment selection hinges on staging, HPV status, and institutional capabilities. Segmentation reveals where value concentrates across therapeutic modalities and care settings, guiding resource allocation for manufacturers and providers.
Product Type:
Margin pools concentrate in systemic agents with biomarker-selected eligibility and neoadjuvant positioning.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways demonstrate durable responses in HPV-positive and PD-L1-high subtypes. Academic medical centers in the United States and Germany are prioritizing pembrolizumab and nivolumab combinations in first-line metastatic protocols, with neoadjuvant trials expanding organ-sparing surgical candidacy.
- Chemotherapy:Platinum-based regimens (cisplatin, carboplatin, TIP combination) retain foundational status for fit patients with advanced nodal disease. Supply concentration in Asian active pharmaceutical ingredient facilities creates vulnerability, while REACH authorization requirements in Europe are elevating manufacturing compliance costs for sponsors.
- Radiation Therapy:External beam and brachytherapy approaches serve organ-preservation goals for select T1-T2 lesions.
- Surgical Treatments:Partial and total penectomy with lymphadenectomy remains curative for localized disease, limiting systemic therapy addressability.
The dominant share belongs to Chemotherapy, while Immunotherapy is closing the gap fastest.
Application:
Volume distribution tracks complexity gradients in surgical staging and infused regimen administration.
- Hospitals:Tertiary centers with dedicated uro-oncology programs absorb complex inguinal lymph node dissections, sentinel node mapping, and inpatient chemotherapy protocols. These institutions command procurement leverage through bundled diagnostic-therapeutic contracts and multidisciplinary tumor board standardization.
- Clinics:Outpatient oncology clinics manage stable patients on oral targeted agents and subcutaneous immunotherapy, capturing maintenance-phase volume as protocols shift toward community-based delivery.
- Research Laboratories:Academic pathology and molecular diagnostic facilities support biomarker characterization and clinical trial enrollment.
- Home Care:Home infusion services and oral therapy self-administration are gaining traction for selected maintenance regimens.
Hospitals retain the volume leadership position, though Clinics are expanding share most rapidly.
End User:
Prescribing authority concentrates with specialists possessing fellowship training in genitourinary malignancies.
- Oncologists:Medical oncologists with genitourinary subspecialty expertise direct systemic therapy selection, including neoadjuvant immunotherapy protocols and metastatic combination regimens. Their institutional affiliations determine formulary access and clinical trial participation rates.
- Urologists:Fellowship-trained urologic oncologists perform definitive surgical staging and often co-manage systemic therapy decisions in multidisciplinary models.
- Gynecologists:Limited involvement centers on vulvar cancer overlap protocols and rare gender-diverse patient presentations.
- General Practitioners:Primary role in initial lesion recognition and urgent referral to specialized centers.
Oncologists command the dominant prescriber role, with Urologists deepening systemic therapy co-management fastest.
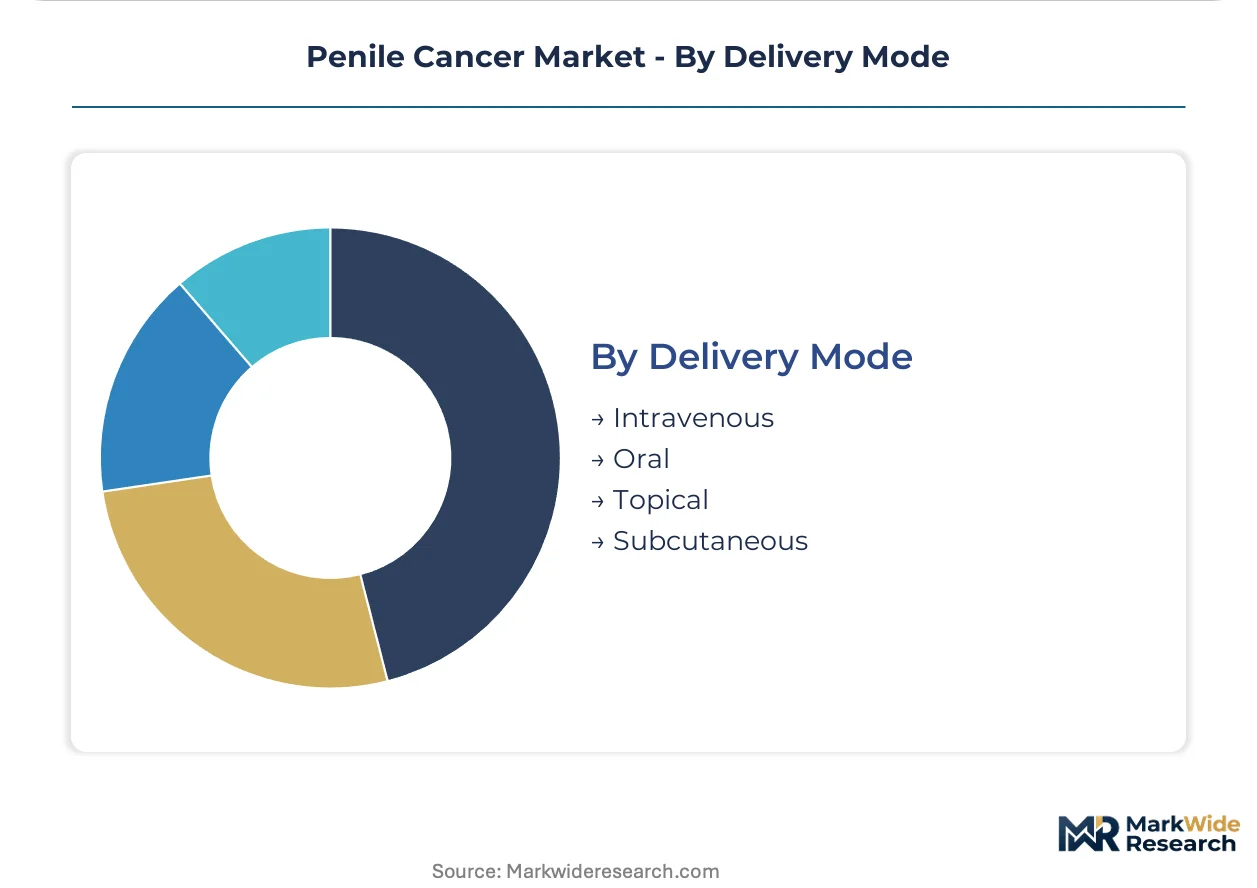
Delivery Mode:
Route selection reflects pharmacokinetic requirements, treatment intent, and patient functional status.
- Intravenous:Infused platinum agents and checkpoint inhibitors require hospital or infusion center administration with monitoring capabilities. This route captures the largest current volume share, anchored by cytotoxic backbone regimens and pembrolizumab's established positioning.
- Oral:Targeted agents and selected maintenance protocols enable outpatient convenience, with uptake constrained by limited approved oral options in this indication.
- Topical:Imiquimod and fluorouracil applications serve superficial Tis lesions, representing a narrow segment with minimal systemic therapy overlap.
- Subcutaneous:Emerging formulations of immunotherapy agents promise reduced infusion chair time and community administration feasibility.
Intravenous administration holds the leading share, while Subcutaneous delivery is advancing most quickly toward commercial relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized uro-oncology centers in the United States, Germany, and Japan concentrate procurement authority for penile cancer therapeutics. Hospital-based oncology departments in these markets drive adoption of combination regimens and neoadjuvant protocols. Regulatory pathways in each geography reshape competitive entry sequences for rare disease developers.
United States
Academic medical centers with dedicated sarcoma and genitourinary programs anchor demand for checkpoint inhibitors and companion diagnostic testing. The FDA's accelerated approval pathways for rare disease therapies compress development timelines, enabling faster market access for novel systemic agents. Major cancer clusters in Houston, New York City, and Boston institutionalize multidisciplinary tumor boards that standardize neoadjuvant immunotherapy adoption.
Germany
University hospitals with integrated diagnostic-pathology-oncology platforms command procurement leverage through bundled contracts. REACH authorization requirements for hazardous pharmaceutical intermediates elevate manufacturing compliance costs for platinum-based cytotoxic agents, favoring sponsors with synthetic routes avoiding heavy metal catalysis. The EMA's PRIME pathway reduces regulatory review timelines, accelerating access for qualifying therapies.
Japan
Specialized uro-oncology centers prioritize suppliers offering companion testing bundled with therapeutic access. PMDA's orphan drug designation program aligns with global regulatory incentives for rare cancer indications. Tokyo and Osaka metropolitan areas concentrate fellowship-trained genitourinary surgical oncologists who direct systemic therapy selection.
Brazil
ANVISA's expanded access programs for oncology medicines create pathways for systemic agents to reach underserved populations through the Sistema Único de Saúde network. Public health system penetration opportunities concentrate in São Paulo and Rio de Janeiro, where referral centers manage complex inguinal lymph node dissections. Biosimilar sponsors gain positioning through volume tenders.
United Kingdom
NHS England's specialized commissioning frameworks concentrate penile cancer treatment in designated supra-regional centers. NICE technology appraisals determine reimbursement for novel systemic therapies, elevating evidence requirements for single-arm studies. London and Manchester academic networks drive clinical trial enrollment for HPV-related malignancy protocols.
Penile Cancer Market Competitive Environment
Player mix skews toward large-cap pharmaceutical conglomerates with pre-positioned immuno-oncology infrastructure and diagnostic partnerships. Market structure concentrates around sponsors capable of navigating accelerated regulatory pathways while maintaining manufacturing scale across cytotoxic and targeted agent categories. Three archetypes dominate: vertically integrated diagnostic-therapeutic developers, broad oncology portfolio holders, and precision medicine specialists with biomarker-selected trial capabilities. Competitive moves center on companion diagnostic co-development agreements and neoadjuvant protocol positioning in major academic centers.
Within the diagnostic-therapeutic integration tier, F. Hoffmann-La Roche Ltd. and AstraZeneca PLC exemplify archetypes combining companion testing with therapeutic access. Pfizer Inc. occupies a position representing manufacturing scale across multiple modality categories. These Basel-based, Cambridge-based, and New York-based entities anchor competitive dynamics through their institutional affiliations with major cancer centers and existing infrastructure in rare oncology indications.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca PLC |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Checkpoint inhibitor substitution for platinum-based cytotoxic agents simultaneously redraws procurement geography toward Western biologics manufacturing hubs and compresses pricing power for generic chemotherapy sponsors. This generational shift concentrates margin capture with immuno-oncology developers while exposing cisplatin and carboplatin suppliers to cost pressure from REACH compliance and API sourcing vulnerability.
Pricing Analysis
Technology-generation pricing gaps separate neoadjuvant checkpoint inhibitors from legacy platinum doublets and emerging subcutaneous formulations. Three-tier pricing structure across premium biologics, standard cytotoxics, and economy generics dominates hospital procurement negotiations. Price differentiation rests on companion diagnostic bundling and biomarker-selected eligibility criteria. Pricing pressure stems from biosimilar entry into mature cytotoxic categories. Community oncology practices exhibit highest price sensitivity, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled biologics have intensified following port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes. Active pharmaceutical ingredient manufacturing for platinum agents concentrates in China and India, with formulation finishing in Germany and the United States. Supply chain risk centers on single-source dependency for carboplatin precursor chemicals. Distribution runs through hospital-centric procurement networks with limited wholesaler intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic service layers and biomarker testing protocols are expanding faster than therapeutic hardware, creating recurring revenue attachments that reshape stakeholder economics. This service-attach dynamic elevates vendors with integrated diagnostic-pathology platforms over pure-play drug manufacturers.
For Market Incumbents: Compound defensive positioning through captive supply of PD-L1 expression assays and HPV genotyping platforms that lock in formulary placement. Deepen backward integration into diagnostic development to offset margin compression from checkpoint inhibitor commoditization. Prioritize neoadjuvant protocol sponsorship at major cancer centers to secure organ-sparing surgical adoption pathways.
For New Entrants and Emerging Players: Differentiate on subcutaneous immunotherapy formulations that enable community-based administration and reduce hospital infusion chair dependency. Target the Brazilian public health system through ANVISA expanded access programs where originator and biosimilar systemic agents remain underpenetrated. Lead with home infusion channel partnerships that align with patient preference for outpatient maintenance delivery.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision medicine specialists with biomarker-selected trial capabilities and existing diagnostic partnerships. Long-term viability hinges on regulatory navigation expertise across FDA accelerated approval and EMA PRIME pathways. Acquisition targets should demonstrate embedded molecular pathology capabilities. Watch neoadjuvant pathological complete response rates as the signal indicating which therapeutic platforms will capture organ-sparing surgical volume.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | PD-L1 assay bundling with pembrolizumab access secures formulary placement at university hospitals. |
| Neoadjuvant Protocol Sponsorship | First-line metastatic trials at MD Anderson and Memorial Sloan Kettering establish organ-sparing surgical standards. |
| Subcutaneous Formulation Development | Reduced infusion chair time opens community oncology clinics to immunotherapy maintenance protocols. |
| Brazilian SUS Network Penetration | ANVISA expanded access programs reach underserved penile cancer populations through public tenders. |
| REACH-Compliant Manufacturing Investment | European contract manufacturing organizations absorb containment infrastructure costs for platinum agents. |
Study Parameters
Desk research of FDA orphan drug designations, EMA PRIME pathway decisions, and ClinicalTrials.gov enrollment data preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from formulary databases, WHO classification updates, and SEC 10-K oncology segment disclosures. Bottom-up patient flow modeling and top-down therapeutic category sizing were triangulated to constrain variance.
Variance decomposition across product type, treatment line, administration route, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against overall market trajectory. Forecast inputs incorporated biomarker prevalence assumptions, neoadjuvant protocol adoption curves, and companion diagnostic penetration rates throughout the projection horizon.
Material uncertainties — regulatory pathway delays, biomarker definition revisions, and platinum API supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about checkpoint inhibitor expansion timelines and surgical modality substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
LAMEA Transrectal Ultrasound Market
Urology
Ureter Cancer Treatment Market
Urology
Voiding Cystourethrogram Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Ureterorenoscopes Market
Urology
Cystoscope Market
Urology
Renal Cyst Treatment Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Urology Lasers Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Genitourinary Cancers Treatment Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Uropathy Treatment Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Single Use Cystoscope Market