
 Global Behavioral/Mental Health Software Market | 2026-2036
Global Behavioral/Mental Health Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Behavioral/Mental Health Software Market Foresight
Interoperable FHIR-based data exchange is rewriting how behavioral health platforms integrate with acute care systems. Epic Systems Corporation leverages its dominance in hospital EHR networks to extend into behavioral workflows. Netsmart Technologies anchors its position through specialized tools for community mental health centers.
Behavioral and mental health software comprises clinical, administrative, and patient-facing applications designed to document diagnoses, coordinate care episodes, and deliver therapeutic interventions through digital interfaces. Cloud-based deployment leads solution type distribution due to lower infrastructure overhead and faster implementation cycles, while teletherapy platforms represent the fastest-expanding category as synchronous virtual visits become standard in routine psychiatric practice. Patient engagement tools command concentrated margin pools through recurring subscription structures tied to outcome measurement protocols.
The FDA regulates clinical decision support modules as software-as-medical-device when diagnostic recommendations drive patient management, while HIPAA security rules govern cloud data architectures and state-level telehealth licensing boards determine cross-border practitioner eligibility. The EU AI Act introduces additional conformity requirements for algorithmic risk stratification tools deployed in European member states. Stakeholders must monitor divergence between federal interoperability mandates and fragmented state prescribing regulations for controlled substances via telehealth.
Market Dynamics
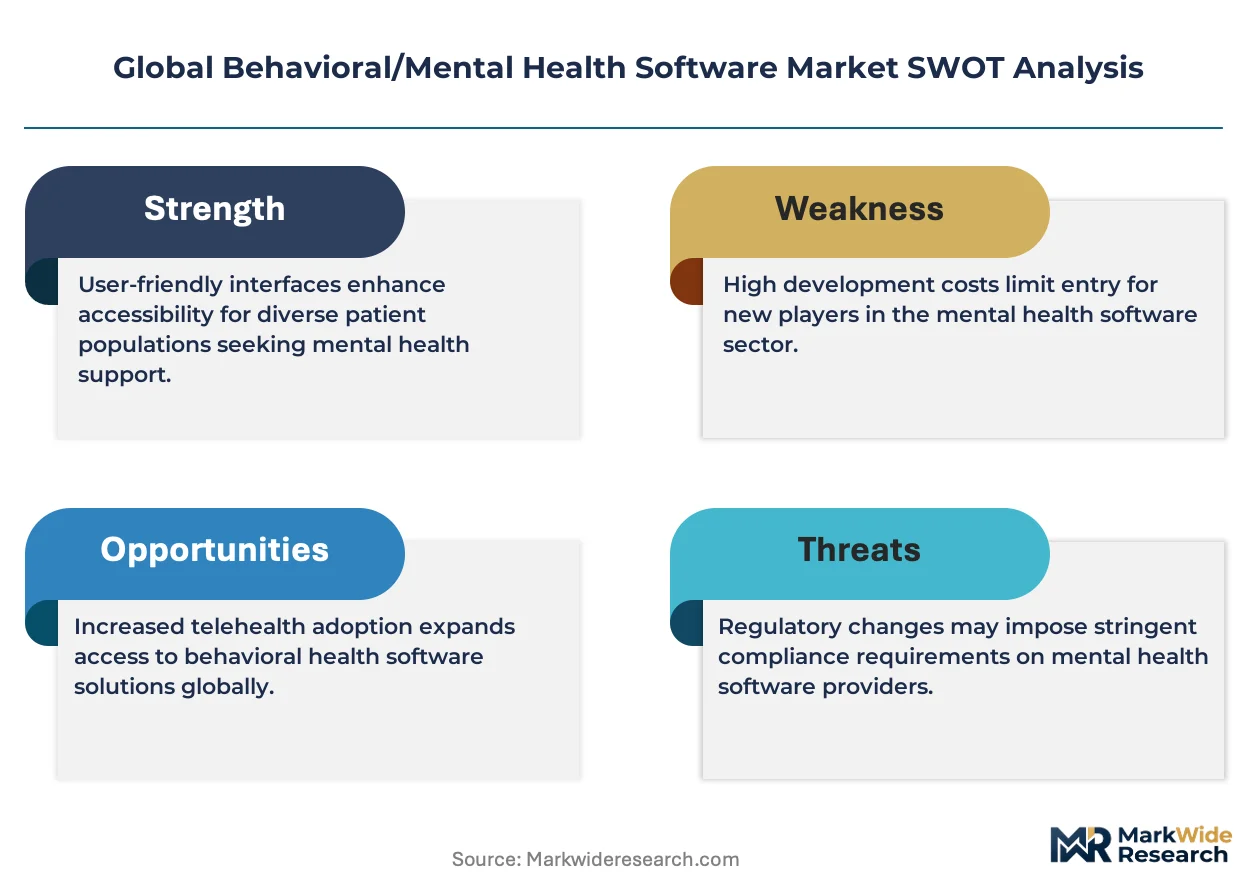
Interoperability mandates from federal payers and the FDA's software-as-medical-device framework are forcing vendors to rebuild their data architectures around FHIR standards, compressing implementation timelines and raising compliance costs simultaneously.
Growth Catalysts
- Employer-sponsored mental health benefits:Large US corporations now bundle behavioral platforms into workforce wellness programs, creating enterprise procurement pipelines that bypass traditional healthcare IT sales cycles.
- HIPAA interoperability mandates:The 21st Century Cures Act enforcement requires EHR systems to expose behavioral health data through standardized APIs, opening previously siloed records to third-party applications.
- Cloud-native architectures:Containerized deployment models reduce infrastructure overhead for community mental health centers, accelerating adoption among cash-constrained providers.
Market Restraints
- State-level telehealth licensing:Cross-border practitioner credentialing remains fragmented across 50 US state boards, restricting platform scalability and forcing redundant compliance investments.
- Controlled substance prescribing:The Ryan Haight Act and its telehealth flexibilities create regulatory uncertainty for platforms integrating e-prescribing workflows for Schedule II medications.
- Data localization requirements:EU GDPR and emerging national privacy frameworks in India and China mandate regional server infrastructure, raising capital requirements for global vendors.
Strategic Opportunities
- Substance use disorder integration:Platforms combining medication-assisted treatment tracking with peer support networks address the opioid crisis response funding now flowing through SAMHSA block grants.
- AI risk stratification tools:Natural language processing applied to clinical notes enables predictive models for suicide prevention, though EU AI Act conformity requirements add deployment complexity.
- Medicaid expansion states:Behavioral health carve-outs in managed care contracts create procurement windows for platforms demonstrating HEDIS measure improvements.
Industry Challenges
- Clinical informaticist scarcity:Vendors struggle to hire staff capable of mapping psychiatric diagnostic codes to quality metrics required by value-based reimbursement contracts.
- Legacy EHR integration:Proprietary data formats from dominant hospital systems resist standard FHIR exchange, requiring expensive custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Behavioral/Mental Health Software Market |
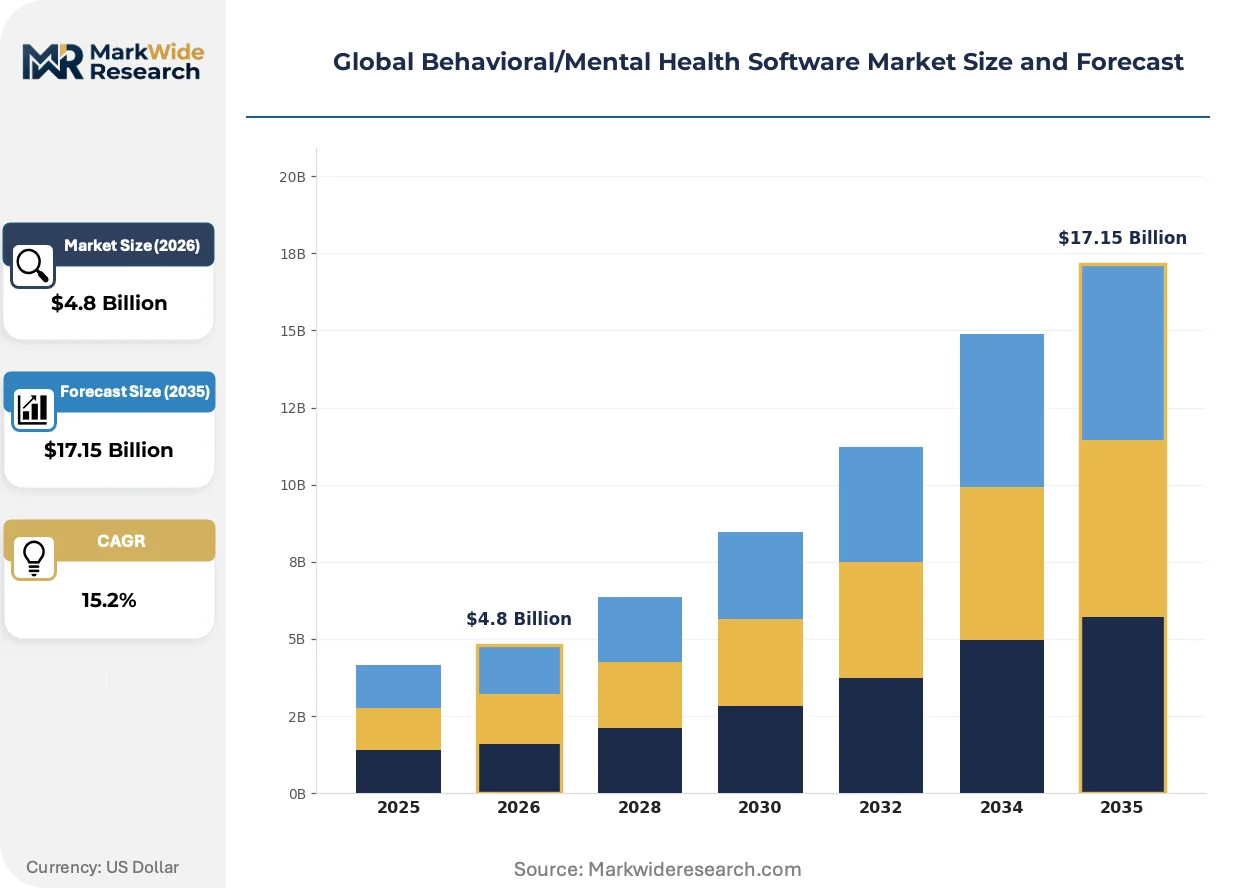
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $17.15 Billion |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Web-Based Solution Type: Electronic Health Records, Teletherapy Platforms, Patient Engagement Tools, Clinical Decision Support, Care Coordination Application: Stress Management, Cognitive Behavioral Therapy, Addiction Treatment, Mood Disorder Assistance, Psychological Assessment End User: Psychiatrists, Psychologists, Mental Wellness Clinics, Counseling Centers, Employee Assistance Programs |
| Companies Covered | Oracle Cerner Corporation, Epic Systems Corporation, Netsmart Technologies, Qualifacts, Welligent, Core Solutions, AdvancedMD, Meditab Software, NextGen Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Behavioral/Mental Health Software Market Shifts & Advancements
Digital therapeutic modalities are displacing traditional session-based billing models, while regulatory clarity around software-as-medical-device classification is accelerating clinical validation investments across the vendor landscape.
Natural language processing engines trained on psychiatric interview transcripts are digitizing the documentation burden that previously consumed 25-30% of clinician time. Community mental health centers in the United States are deploying these tools fastest, driven by productivity pressures under capitated Medicaid contracts. The technology is digitizing clinical workflows previously resistant to automation due to the unstructured nature of therapy notes.
The EU AI Act's risk-based classification system imposes conformity assessment requirements on algorithmic diagnostic aids deployed in European member states. Vendors must now maintain technical documentation and human oversight protocols for tools previously marketed as decision support. Behavioral health platforms with predictive suicide risk models face the strictest compliance obligations, prompting some to geofence functionality or pursue notified body certification.
Corporate benefits administrators are consolidating vendor relationships through single-platform contracts that bundle employee assistance programs, coaching, and clinical therapy. This procurement concentration displaces the fragmented point solutions that dominated the 2015-2022 market expansion. The shift is most visible among Fortune 500 employers in the United States, where total rewards teams now evaluate behavioral health vendors on medical cost trend reduction rather than utilization metrics alone.
Global Behavioral/Mental Health Software Market Segmentation
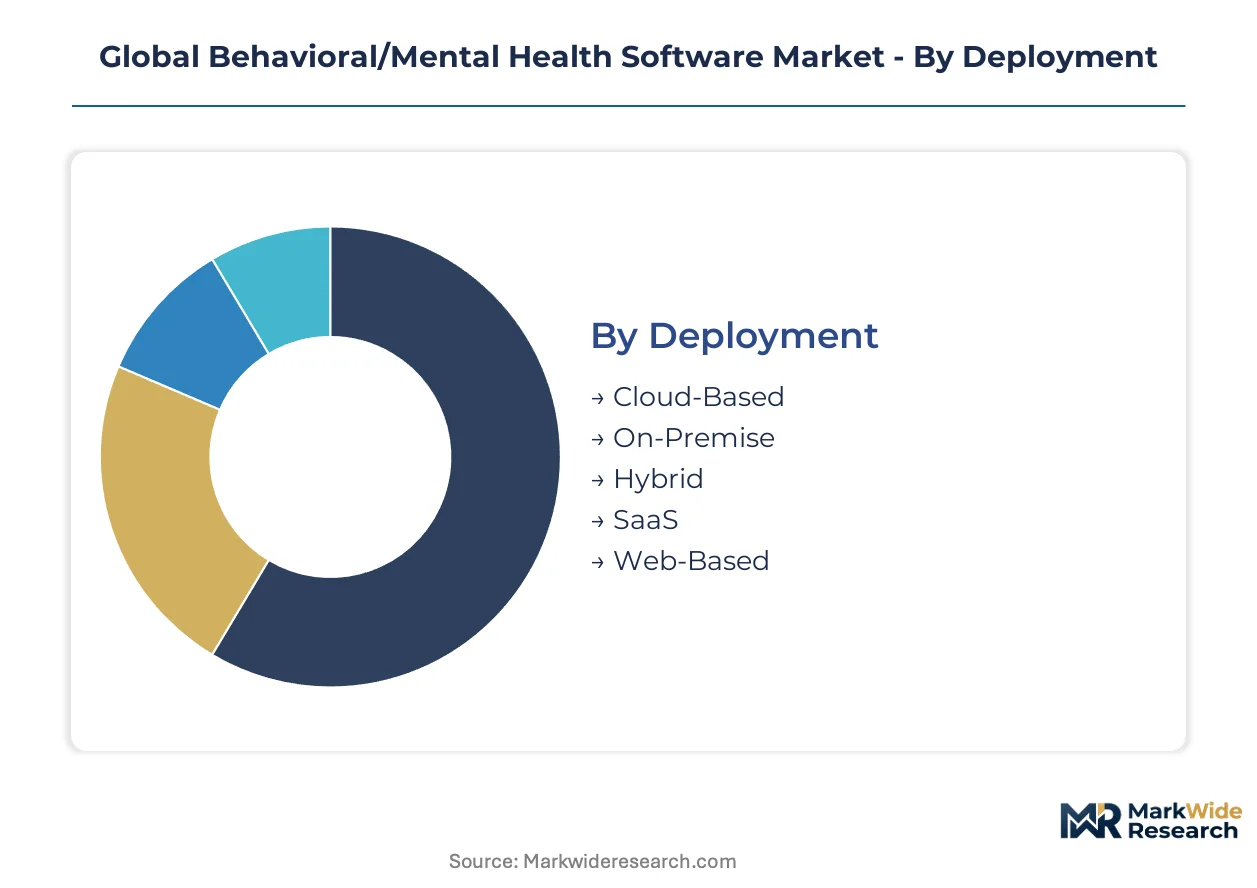
Behavioral and mental health software vendors architect product portfolios around distinct deployment models, clinical workflows, and purchaser economics. Segmentation clarity determines pricing architecture, sales cycle design, and regulatory compliance pathways across psychiatric practice settings.
Deployment:
Cloud-native infrastructure spans single-tenant hospital deployments through multi-tenant SaaS offerings serving distributed counseling networks.
- Cloud-Based:Multi-tenant architectures with automatic scaling support community mental health centers lacking dedicated IT staff. US-based federally qualified health centers drive procurement volume under HRSA infrastructure grants requiring HIPAA-compliant hosting.
- On-Premise:Air-gapped server installations serve state psychiatric hospitals and correctional facilities with strict data sovereignty requirements. Veterans Health Administration medical centers mandate on-premise deployments for PTSD treatment records.
- Hybrid:Split architectures keep sensitive patient identifiers on local servers while pushing analytics workloads to public cloud instances. Large health systems in Germany adopt this model to satisfy GDPR data localization while accessing AI diagnostic tools.
- SaaS:Subscription licensing with per-clinician monthly fees dominates private practice adoption. US psychologist groups purchase these solutions through GPO contracts negotiated by state professional associations.
- Web-Based:Browser-accessible platforms with minimal client-side installation serve rural telehealth deployments. Indian counseling startups leverage lightweight web clients to reach tier-2 and tier-3 city populations with inconsistent broadband.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
Solution Type:
Functional modules map to distinct revenue models: perpetual licenses for documentation systems, per-session fees for virtual care platforms, and outcome-based subscriptions for engagement tools.
- Electronic Health Records:Structured data capture for psychiatric diagnoses, medication histories, and treatment plans with CCHIT certification requirements. US academic medical centers demand Epic and Cerner interoperability for behavioral health integration projects.
- Teletherapy Platforms:Synchronous video infrastructure with waiting room management, session recording, and billing code automation. UK NHS Talking Therapies programs expanded procurement following NICE guidelines endorsing digitally delivered CBT.
- Patient Engagement Tools:Asynchronous messaging, mood tracking diaries, and homework assignment portals extending therapeutic contact between sessions. Australian private insurers now reimburse these as adjunct services under mental health care plans.
- Clinical Decision Support:Algorithmic risk scoring and medication interaction alerts regulated as software-as-medical-device when driving diagnostic conclusions. FDA 510(k) clearance timelines stretch 12-18 months for suicide prevention algorithms.
- Care Coordination:Referral management and cross-provider communication hubs addressing fragmented behavioral health episodes. Medicaid managed care organizations in expansion states require these capabilities for HEDIS compliance.
Electronic Health Records command the largest installed base; Teletherapy Platforms are climbing the fastest.
Application:
Clinical use cases determine user interface design, outcome measurement protocols, and payer reimbursement eligibility across therapeutic modalities.
- Stress Management:Biofeedback integration and mindfulness protocol libraries targeting workplace wellness contracts. Corporate procurement through US employee assistance programs favors solutions with wearable device connectivity.
- Cognitive Behavioral Therapy:Structured session worksheets, thought record templates, and between-session homework tracking. IAPT services in England mandate digital CBT platforms meeting NICE technology appraisal standards.
- Addiction Treatment:Medication-assisted therapy tracking, peer support network integration, and relapse prediction algorithms. SAMHSA block grant funding flows to platforms demonstrating abstinence outcomes in US opioid response programs.
- Mood Disorder Assistance:Longitudinal symptom monitoring for depression and bipolar conditions with provider alert thresholds. German statutory health insurers reimburse these as digital health applications following BfArM fast-track approval.
- Psychological Assessment:Validated instrument administration, automated scoring, and interpretive report generation. Forensic psychiatry units in Canada require platforms with audit trails admissible in provincial competency hearings.
Addiction Treatment attracts the steepest public investment; Mood Disorder Assistance shows the strongest payer traction.
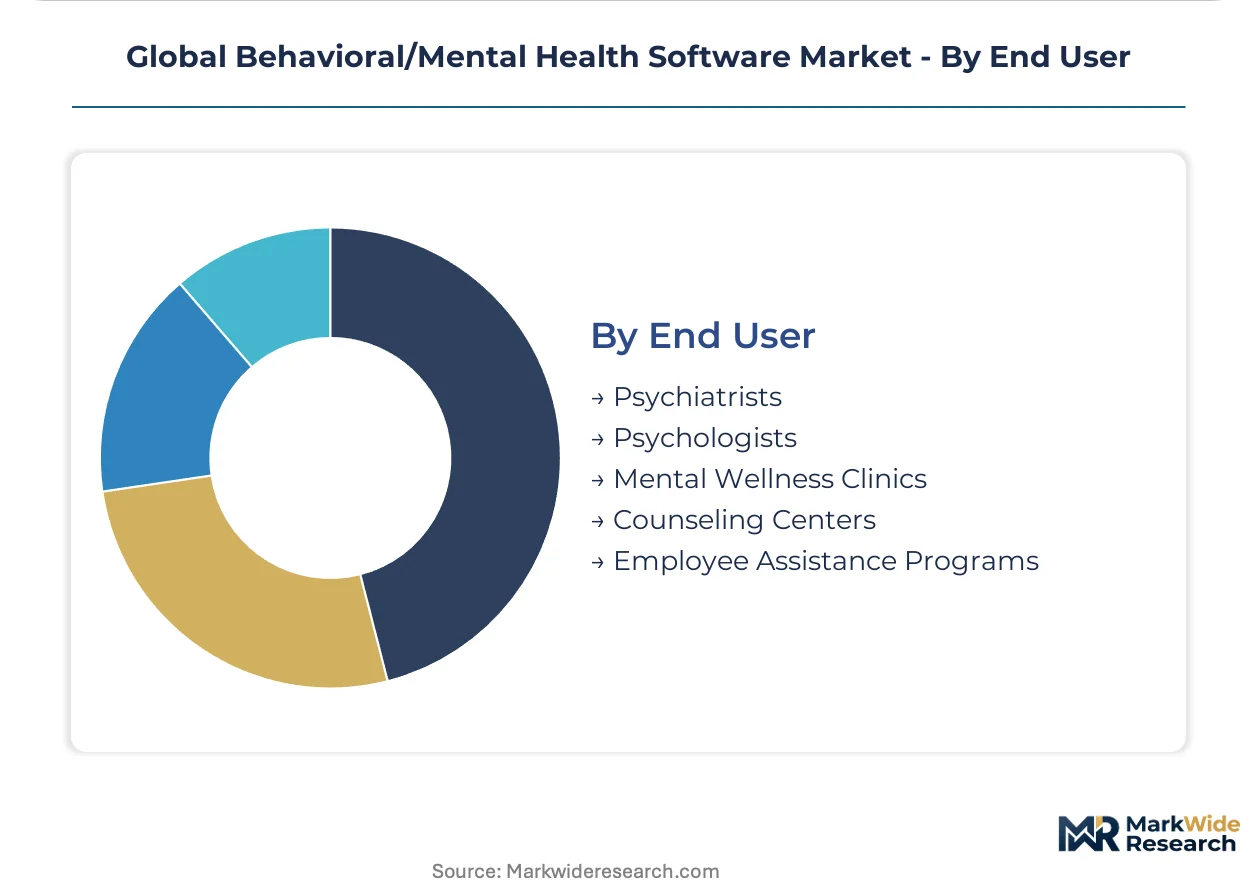
End User:
Purchaser categories span prescribing clinicians, non-prescribing therapists, institutional providers, and employer-sponsored benefit administrators with divergent procurement authority.
- Psychiatrists:Medical doctors requiring e-prescribing integration, prior authorization workflows, and medication management modules. US state Medicaid programs credential these providers for telehealth reimbursement at higher rates than other specialties.
- Psychologists:Doctoral-level practitioners emphasizing psychological testing, therapy documentation, and outcome measurement without prescribing functionality. Australian Medicare rebates for psychological services drive platform adoption in private practice.
- Mental Wellness Clinics:Multi-disciplinary outpatient facilities integrating psychiatric, psychological, and social work services. Community health centers in Brazil's SUS system deploy these platforms for universal mental health coverage expansion.
- Counseling Centers:University and employee-focused settings with high session volume, brief treatment models, and crisis intervention protocols. US college counseling centers face 30% demand surges post-pandemic, accelerating platform procurement.
- Employee Assistance Programs:Employer-contracted services delivering short-term counseling, referral management, and supervisor consultation. Fortune 500 total rewards teams consolidate vendor relationships through single-platform contracts spanning coaching through clinical therapy.
Employee Assistance Programs are gaining share fastest; Mental Wellness Clinics retain the deepest workflow integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based vendors export cloud-based behavioral health platforms to healthcare systems across Germany, Australia, and the United Kingdom, establishing a dominant trade corridor in digital therapeutic infrastructure.
United States
Employer-sponsored mental health benefits and Medicaid managed care expansion drive procurement volume. HIPAA interoperability mandates from the 21st Century Cures Act force EHR vendors to expose behavioral data through standardized APIs. Epic Systems Corporation anchors development activity in Madison, Wisconsin, extending hospital network dominance into psychiatric workflows.
Germany
Statutory health insurer reimbursement for digital health applications accelerates platform adoption among outpatient psychotherapists. The BfArM fast-track approval process for DiGA-classified tools creates regulatory clarity absent in neighboring markets. Berlin and Munich host clusters of behavioral health startups targeting mood disorder assistance modules for BARMER and TK insurance contracts.
United Kingdom
NHS Talking Therapies program procurement drives demand for digitally delivered CBT platforms meeting NICE technology appraisal standards. NHS England's interoperability framework mandates FHIR-based data exchange between Improving Access to Psychological Services providers and acute trusts. London-based vendors concentrate on IAPT-compliant workflow automation for anxiety and depression pathways.
Australia
Medicare rebates for psychological services and private insurer coverage of patient engagement tools expand addressable market size. The TGA regulates clinical decision support modules with diagnostic claims as software-as-medical-device. Sydney and Melbourne counseling networks deploy cloud-native platforms to reach rural populations under the Better Access mental health initiative.
India
Tier-2 and tier-3 city counseling startups leverage lightweight web-based platforms to address mental health access gaps. The CDSCO oversees software-as-medical-device classification for algorithmic diagnostic tools entering clinical use. Bengaluru's health-tech cluster incubates teletherapy platforms targeting corporate employee assistance programs for IT services exporters.
Global Behavioral/Mental Health Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around hospital EHR incumbents and fragmenting among point-solution vendors. Epic Systems Corporation and Oracle Cerner Corporation leverage installed base dominance to extend into behavioral workflows, while Netsmart Technologies and Qualifacts anchor specialized positions in community mental health and federally qualified health center segments. Three archetypes define competitive positioning: EHR-integrated suite providers, standalone behavioral specialists, and employer-facing wellness platforms. M&A activity concentrates EHR vendors acquiring teletherapy capabilities, while strategic partnerships between cloud infrastructure providers and clinical workflow vendors accelerate FHIR-compliant data architecture deployment.
Within the EHR-integrated tier, Epic Systems Corporation and Oracle Cerner Corporation represent scale-driven positions leveraging hospital network relationships to cross-sell behavioral modules. Netsmart Technologies exemplifies the specialist archetype, occupying a position focused on community mental health center workflows and state-level Medicaid procurement channels. These three anchors demonstrate how vendor origin—Wisconsin-based Epic, Kansas City-based Cerner, and Kansas-based Netsmart—shapes geographic concentration of development resources and sales coverage priorities across US provider markets.
| Leading Market Players |
|---|
| Oracle Cerner Corporation |
| Epic Systems Corporation |
| Netsmart Technologies |
| Qualifacts |
| Welligent |
| Core Solutions |
| AdvancedMD |
| Meditab Software |
| NextGen Healthcare |
| Others |
Supply & Pricing Matrix
Trans-Pacific data center cabling corridors from Singapore to Los Angeles carry escalating bandwidth costs that compress margins for cloud-native behavioral health platforms, concentrating pricing power among vendors with captive server infrastructure while forcing price differentiation between latency-sensitive teletherapy modules and asynchronous engagement tools.
Pricing Analysis
Cloud-generation pricing gaps separate legacy on-premise perpetual licenses from containerized SaaS tiers and emerging serverless microservices architectures. Three-tier pricing structure across enterprise, mid-market, and safety-net provider levels reflects certification complexity for FDA software-as-medical-device modules versus standard documentation tools. Cost compression in the mid-market tier is intensifying because Epic Systems and Oracle Cerner bundle behavioral modules at marginal cost to hospital EHR contracts. Federally qualified health centers exhibit highest price sensitivity due to HRSA grant dependency, while Fortune 500 employers show lowest sensitivity when purchasing through consolidated total rewards contracts.
Supply Chain Analysis
Upstream compute infrastructure feeds from hyperscaler data center clusters in the United States, Ireland, and Singapore, with specialized GPU provisioning for AI diagnostic models drawing from Taiwan Semiconductor and NVIDIA supply allocations. Cloud-native behavioral health platforms rest on AWS, Azure, and Google Cloud backbone dependencies alongside niche HIPAA-compliant hosting providers like ClearDATA and Datica. Single-source vulnerability concentrates in FHIR interoperability middleware where Epic's proprietary APIs resist standard data exchange. Distribution runs through direct enterprise sales teams for hospital systems, value-added resellers for community mental health centers, and benefits administration platforms for employer-sponsored contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The behavioral and mental health software market sits in early-cycle expansion as employer-sponsored benefit penetration accelerates platform adoption ahead of traditional healthcare IT procurement cycles.
For Market Incumbents: Harden API control points by embedding proprietary FHIR extensions that resist commoditized data exchange, while acquiring teletherapy point-solution vendors before they achieve critical mass in Medicaid managed care channels. Vertical integration into cloud infrastructure through dedicated hosting subsidiaries defends margin position against hyperscaler pricing leverage. For New Entrants and Emerging Players: Pursue white-space opportunities in substance use disorder platforms combining medication-assisted treatment tracking with peer support networks, where SAMHSA block grant funding creates procurement windows outside established EHR vendor relationships. Target Indian corporate employee assistance programs for IT services exporters, leveraging lightweight web-based deployment to bypass infrastructure-heavy competitive requirements. For Investors and Strategic Acquirers: Specialist clinical decision support vendors with FDA 510(k) clearance for suicide prevention algorithms offer the strongest acquisition target archetype given regulatory moats and EU AI Act conformity complexity that deters new market entry. Long-term viability hinges on demonstrating outcome measurement capabilities that secure value-based reimbursement contracts. Watch for HEDIS measure adoption rates in Medicaid expansion states as the inflection signal separating platforms with durable provider relationships from those dependent on discretionary wellness spending.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Interoperability Certification | HIPAA 21st Century Cures Act compliance unlocks third-party data exchange revenue streams. |
| FDA Software-as-Medical-Device Clearance | Regulatory pathway validates clinical decision support modules for diagnostic reimbursement eligibility. |
| Cloud Infrastructure Partnership | Hyperscaler alliances reduce latency for synchronous teletherapy deployments across rural geographies. |
| Employer Benefits Platform Integration | Fortune 500 total rewards consolidation creates enterprise procurement bypassing traditional hospital IT cycles. |
| AI Risk Stratification Development | Natural language processing on psychiatric notes enables predictive suicide prevention tool differentiation. |
Research Methodology
A spread of perspectives from behavioral health CIOs, clinical informaticists, Medicaid managed care contracting officers, and employer benefits administrators converged on the working assumptions underlying this analysis. Primary fieldwork with these stakeholders combined with secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and hospital procurement contract disclosures. Bottom-up sizing of vendor-reported deployment metrics triangulated against top-down estimates derived from employer-sponsored benefit penetration rates and Medicaid expansion enrollment data.
Demand-supply balance modeling across the projection horizon incorporated deployment model segmentation by cloud-native versus on-premise architecture, solution type by clinical versus administrative functionality, and end-user category by institutional provider versus employer-sponsored purchaser. CAGRs emerged from weighted average growth trajectories across these dimensions, with specific inputs including telehealth utilization rates from CMS Medicare claims and HEDIS measure adoption timelines in Medicaid managed care contracts.
Sensitivities concentrate around FDA enforcement discretion shifts for software-as-medical-device classification, state-level telehealth prescribing flexibilities for controlled substances, and EU AI Act conformity timeline delays for algorithmic diagnostic tools. Cross-checking against SAMHSA block grant disbursement patterns and employer medical cost trend data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Heart Failure Software Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
Digital Health Market