
 Prescribed Health Apps Market | 2026-2036
Prescribed Health Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Prescribed Health Apps Market Outlook
Project finance tied to outcomes-based reimbursement contracts is narrowing the competitive field for smaller developers. Epic Systems Corporation leverages its dominance in electronic health records to embed prescribed apps directly into clinical workflows. Cerner Corporation sustains its position through deep integration with hospital pharmacy systems. Medtronic competes by anchoring its app portfolio to connected medical devices with regulatory clearance.
Prescribed health apps are software applications requiring clinician authorization before patient use, typically featuring dose tracking algorithms, biometric integration, and clinical decision support protocols designed to manage specific disease states. Chronic disease monitoring leads the product type segment due to recurring data collection requirements and payer willingness to fund remote patient management. Mental health support represents the fastest-expanding category as digital cognitive behavioral therapy gains reimbursement parity in several markets. Telehealth services within the functionality dimension command premium positioning where real-time clinician oversight is mandated by prescribing protocols.
The FDA regulates prescription digital therapeutics through its software-as-a-medical-device pathway, while HIPAA governs data exchange between apps and covered entities, creating compliance barriers for unvalidated platforms. European markets operate under the MDR framework, which classifies higher-risk health apps as Class IIa or IIb medical devices requiring notified body certification. Stakeholders must monitor evolving reimbursement codes and interoperability standards that determine whether prescribed apps achieve sustainable utilization within health system formularies.
Market Dynamics
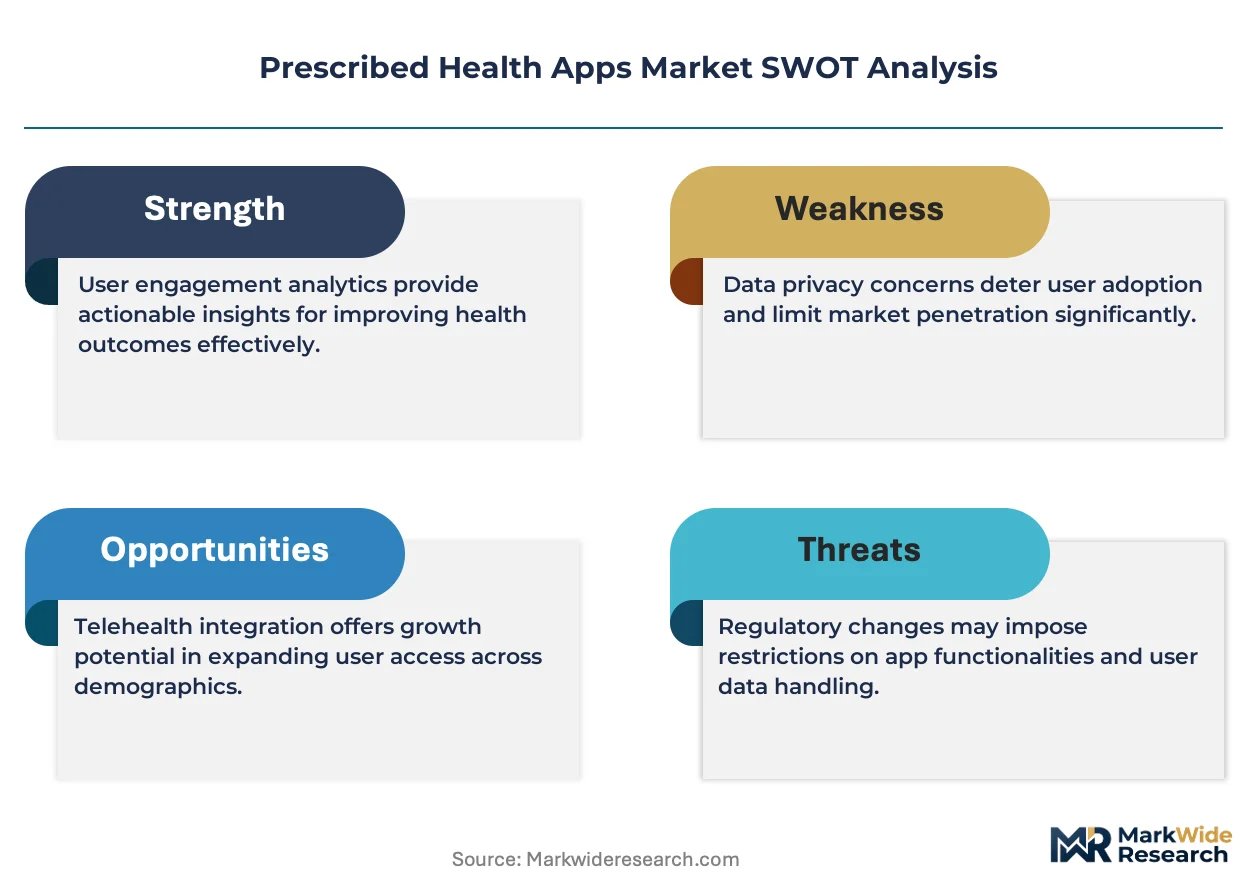
Outcomes-based reimbursement contracts are compressing commercial timelines for developers, forcing clinical validation before formulary inclusion rather than after market entry. Payers now demand real-world evidence thresholds that favor established platforms with existing electronic health record integrations.
Growth Catalysts
- FDA Software-as-a-Medical-Device Framework:The pathway accelerates regulatory clarity for prescription-grade applications, reducing time-to-reimbursement for chronic disease management platforms.
- Integrated Delivery Networks:Hospital systems in the United States are embedding digital therapeutics into standard care protocols for diabetes and behavioral health, creating institutional demand pull.
- Biometric Sensor Convergence:Continuous glucose monitors and wearable cardiac devices are feeding data streams directly into prescribed apps, enabling closed-loop therapeutic adjustments.
Market Restraints
- HIPAA Compliance Architecture:Data exchange protocols between applications and covered entities impose technical barriers that unvalidated platforms cannot surmount without substantial infrastructure investment.
- Notified Body Bottlenecks:European MDR Class IIa and IIb certification queues are extending commercialization timelines for higher-risk mental health and cardiovascular applications.
- Specialized Clinical Validation Costs:Randomized controlled trials required for prescription status consume capital that seed-stage developers cannot access, concentrating development among well-capitalized entities.
Strategic Opportunities
- Pediatric Indication Expansion:Regulatory pathways for adolescent mental health and early-onset diabetes management remain underdeveloped relative to adult populations.
- Remote Patient Monitoring Bundles:Medicare reimbursement codes for chronic care management are enabling combined device-plus-app service models that single-product vendors cannot replicate.
- AI-Augmented Cognitive Behavioral Therapy:Machine learning personalization layered onto evidence-based protocols is differentiating premium-tier mental health applications from generic wellness tools.
Industry Challenges
- Interoperability Engineering Talent:Developers with simultaneous expertise in HL7 FHIR standards and clinical workflow design command compensation premiums that strain mid-cap hiring budgets.
- Formulary Integration Complexity:Health system pharmacy and therapeutics committees require 18-24 month evaluation cycles that delay utilization even after regulatory clearance and payer contracting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescribed Health Apps Market |
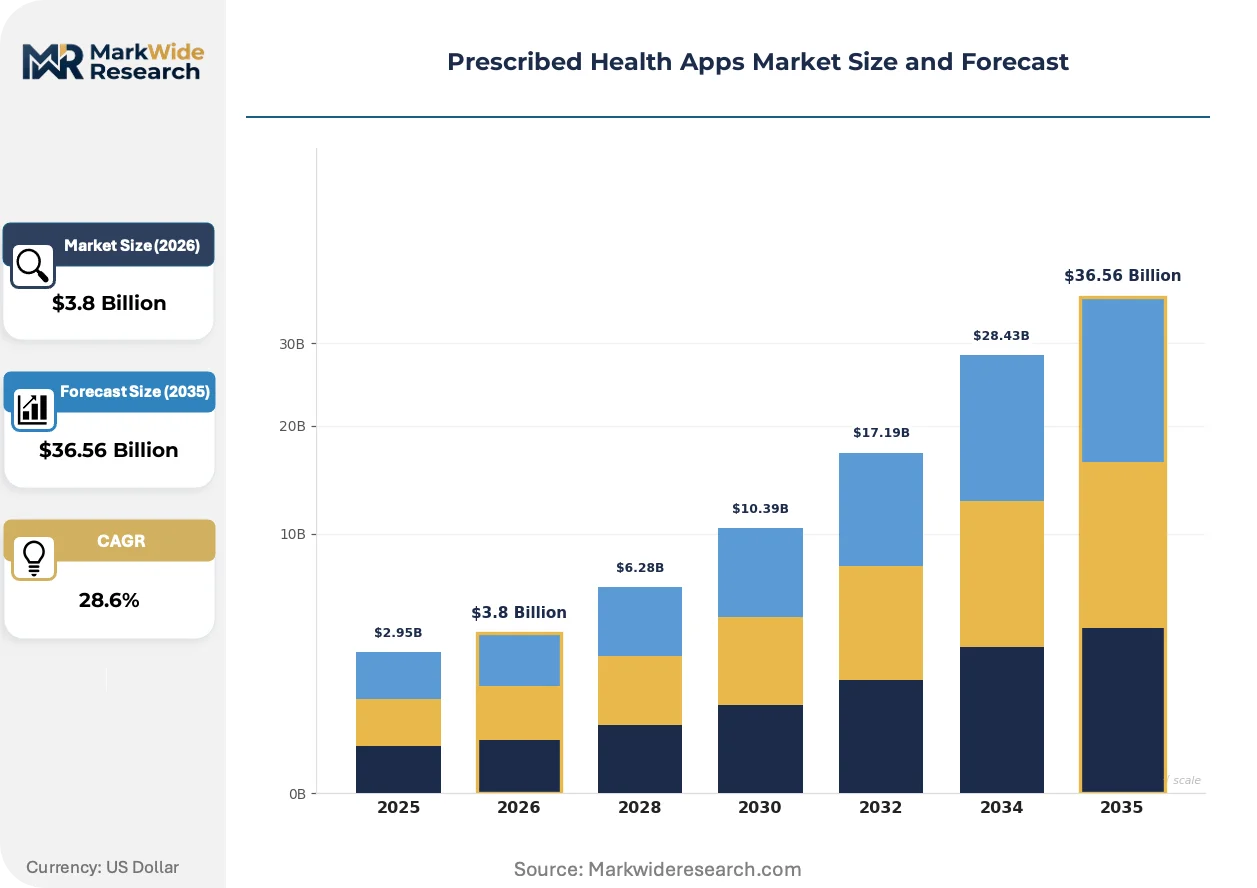
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication Management, Chronic Disease Monitoring, Mental Health Support, Exercise Tracking End User: Patients, Healthcare Providers, Caregivers, Employers Functionality: Medication Reminders, Symptom Tracking, Telehealth Services, Health Education Delivery Mode: Mobile Apps, Web Platforms, Wearable Devices, Desktop Applications |
| Companies Covered | Epic Systems Corporation, Cerner Corporation, Allscripts Healthcare Solutions, Athenahealth, Philips Healthcare, Siemens Healthineers, Medtronic, IBM Watson Health, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescribed Health Apps Market Strategic Shifts
Clinical decision support algorithms are migrating from standalone tools to embedded modules within electronic health record interfaces, collapsing the distinction between prescribing software and documenting outcomes.
Generative artificial intelligence is hybridizing with structured cognitive behavioral therapy protocols to produce adaptive intervention content that adjusts to patient response patterns in real time. Mental health platforms serving integrated delivery networks are deploying these hybrid systems to reduce clinician oversight hours while maintaining therapeutic fidelity. The compression of content production costs is enabling smaller developers to compete on personalization depth rather than scale.
Europe's MDR enforcement is tightening classification boundaries between wellness applications and prescription digital therapeutics, forcing recertification of borderline products previously marketed as lifestyle tools. Notified bodies are demanding clinical evidence packages that mirror pharmaceutical trial structures, elevating compliance costs substantially. Developers with existing Class IIb clearances are extending their regulatory infrastructure to capture market share from repositioning competitors.
Hospital procurement committees are unbundling app licensing from device sales, separating software subscriptions from hardware revenue streams that previously cross-subsidized clinical validation. This unbundling pressures pure-play software vendors to demonstrate independent cost-effectiveness through patient outcome metrics. The shift is most pronounced in United States integrated delivery networks where pharmacy benefit managers now scrutinize app-based interventions with the same actuarial rigor applied to drug formularies.
Prescribed Health Apps Market Segmentation
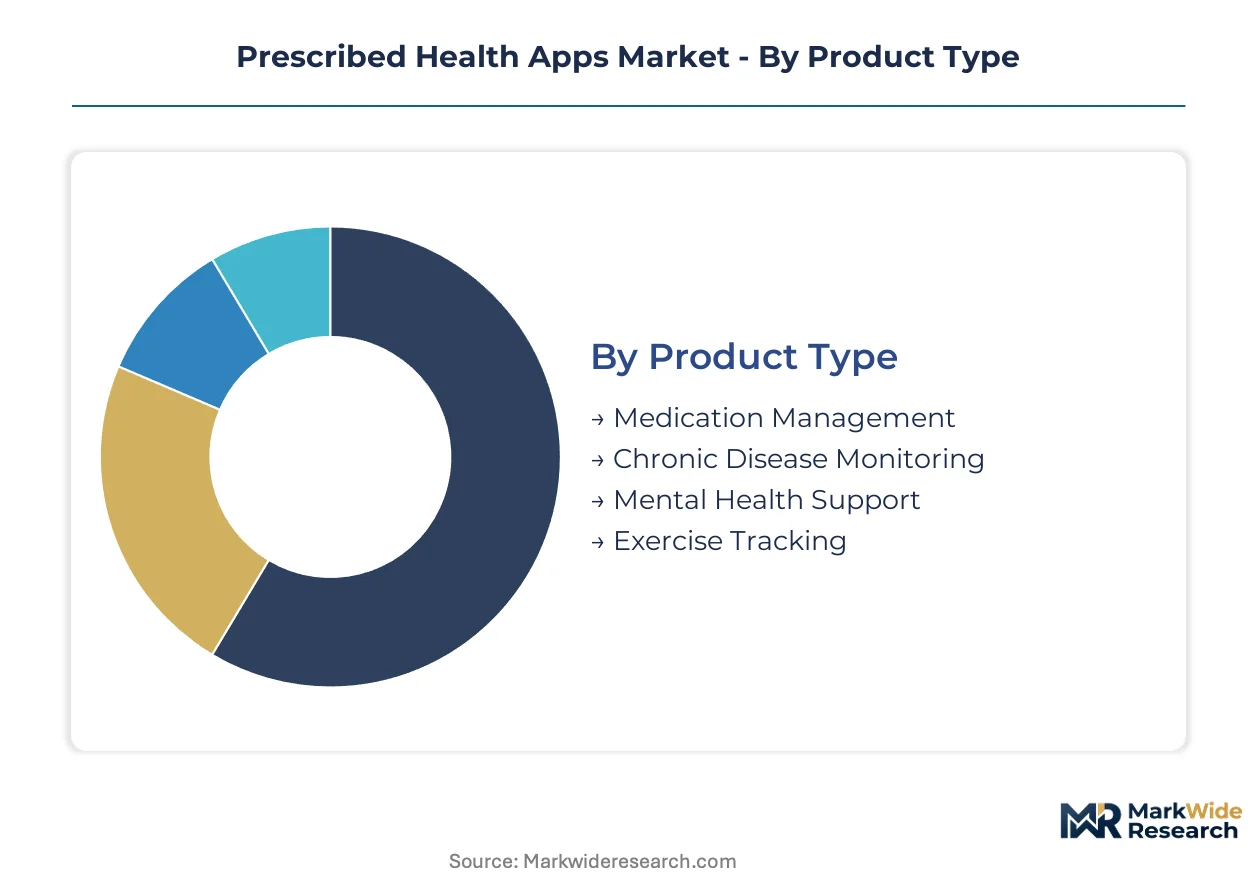
Segmentation in prescribed health apps determines reimbursement pathways, regulatory classification, and integration complexity with hospital systems. Product type and functionality dimensions drive divergent clinical validation requirements and payer contracting strategies across developer portfolios.
Product Type:
Application purpose defines the clinical evidence threshold and prescriber authorization protocols required for formulary inclusion.
- Medication Management:Dose tracking algorithms and drug interaction engines synchronize with pharmacy information systems. Demand clusters in integrated delivery networks managing polypharmacy in elderly populations, where adverse event reduction justifies premium reimbursement.
- Chronic Disease Monitoring:Biometric data ingestion from connected glucose meters and blood pressure cuffs enables closed-loop therapeutic adjustments. United States payers reimburse these platforms through remote patient management codes when outcomes data demonstrates hospitalization reduction.
- Mental Health Support:Digital cognitive behavioral therapy modules with clinician oversight dashboards.
- Exercise Tracking:Rehabilitation protocol adherence tools for post-surgical recovery programs.
Chronic disease monitoring commands the established base. The steepest expansion runs through mental health support.
End User:
Customer archetype shapes interface complexity, data sharing permissions, and liability frameworks governing clinical decision support outputs.
- Patients:Direct-to-prescribed-app users managing their own condition data through clinician-sanctioned interfaces. United States diabetes management programs show strongest adoption where copay elimination removes cost barriers to sustained engagement.
- Healthcare Providers:Clinicians prescribing apps as adjunctive therapy within electronic health record workflows. Epic Systems embeds these tools directly into order sets, reducing friction in authorization and monitoring protocols.
- Caregivers:Family members receiving delegated access to patient dashboards for dependent monitoring.
- Employers:Self-insured corporations subsidizing behavioral health apps as workforce productivity investments.
Healthcare providers anchor the revenue foundation. Patients are climbing the fastest as direct-to-consumer prescription pathways mature.
Functionality:
Feature depth determines whether apps qualify as software-as-a-medical-device under FDA pathways or remain wellness-adjacent tools.
- Medication Reminders:Push notification systems with adherence logging and refill synchronization. Demand concentrates in Medicare Advantage plans targeting medication noncompliance as a preventable cost driver.
- Telehealth Services:Real-time video consultation modules embedded within prescribing protocols. United States integrated delivery networks mandate this functionality for behavioral health apps to maintain therapeutic oversight without in-person visits.
- Symptom Tracking:Patient-reported outcome capture with algorithmic severity scoring.
- Health Education:Condition-specific content libraries with personalized progression pathways.
Telehealth services capture premium positioning. Medication reminders hold the volume base as standard-of-care infrastructure.
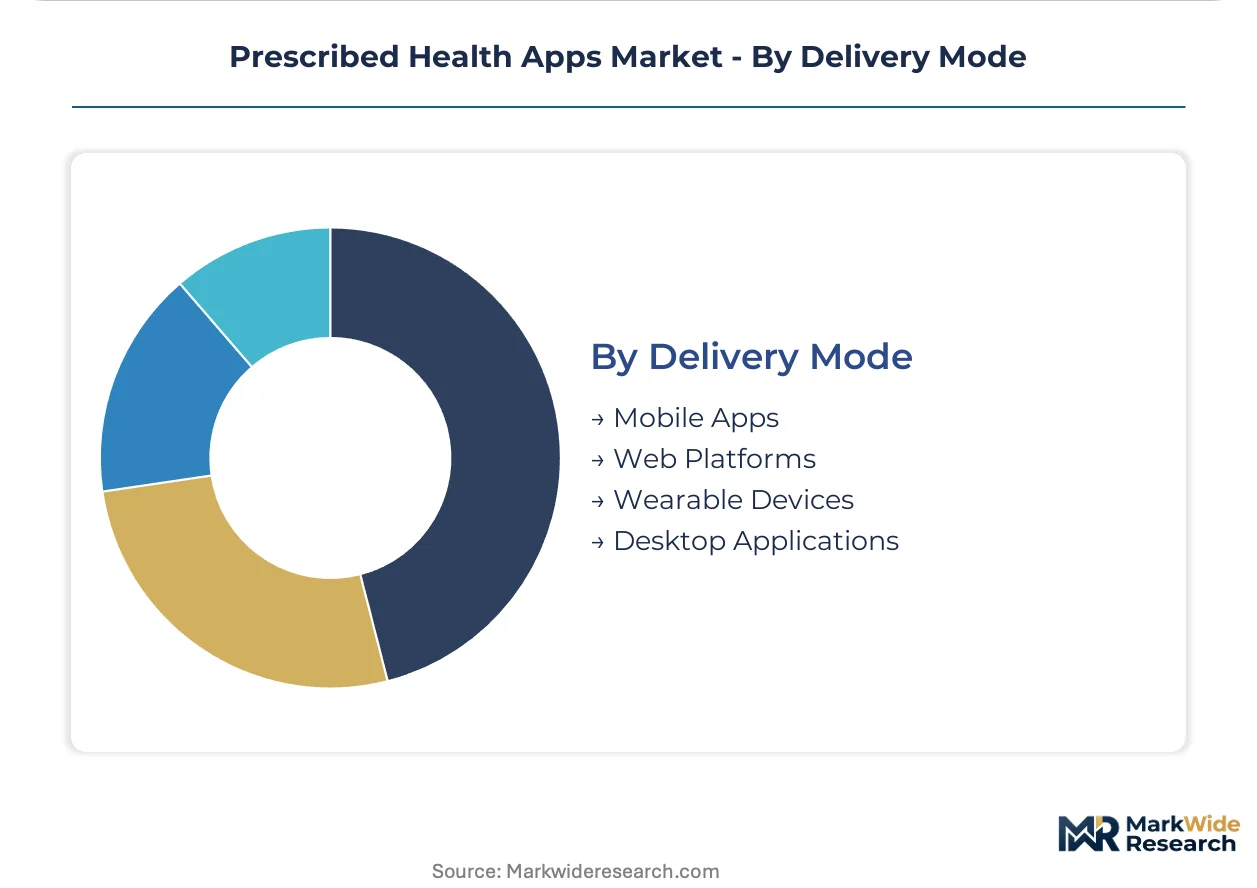
Delivery Mode:
Hardware dependency influences certification complexity, data security architecture, and procurement channel strategy.
- Mobile Apps:Smartphone-native platforms distributed through controlled pharmacy benefit channels. United States hospital systems require these to integrate with Epic and Cerner workflows for seamless prescription-to-activation handoffs.
- Wearable Devices:Smartwatch and dedicated sensor form factors enabling continuous biometric streaming. FDA clearance for these as software-as-a-medical-device accelerates when paired with Class II hardware already under regulatory review.
- Web Platforms:Browser-accessible dashboards for caregiver and clinical oversight roles.
- Desktop Applications:Institutional deployments in hospital pharmacy and therapeutics committee settings.
Mobile apps dominate utilization. Wearable devices are gaining share fastest as sensor convergence enables closed-loop therapeutic models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement policy divergence is fragmenting commercialization pathways across national health systems. Payer willingness to fund prescription-grade applications varies sharply, creating geographic arbitrage opportunities for developers with modular regulatory dossiers. The United States, Germany, United Kingdom, Japan, and Australia concentrate the majority of deployed digital therapeutic programs.
United States
Integrated delivery networks in Texas and California are embedding digital therapeutics into diabetes management protocols. FDA's software-as-a-medical-device pathway accelerates clearance timelines for chronic disease platforms. The Boston-Cambridge corridor houses the densest cluster of digital health startups pursuing prescription status through randomized controlled trials.
Germany
DiGA (Digitale Gesundheitsanwendungen) fast-track reimbursement creates immediate revenue visibility for validated mental health applications. BfArM maintains strict evidentiary standards that favor developers with existing pharmaceutical trial expertise. Berlin and Munich host competing clusters of regulatory consultants and digital therapeutic developers serving the statutory health insurance system.
United Kingdom
NHS England's Innovation Accelerator program channels digital therapeutic pilots into integrated care systems across Greater Manchester and the West Midlands. MHRA operates a parallel regulatory track for software-as-a-medical-device that references FDA determinations where appropriate. London's digital health ecosystem specializes in cognitive behavioral therapy platforms targeting IAPT (Improving Access to Psychological Therapies) procurement frameworks.
Japan
PMDA's 2021 guidance on SaMD classification clarified reimbursement eligibility for prescription digital therapeutics in hypertension management. Tokyo and Osaka academic medical centers are conducting multi-site trials for depression and insomnia applications. The government's Society 5.0 initiative directs public research funding toward AI-augmented therapeutic content.
Australia
TGA's software-based medical device framework aligns with IMDRF guidelines, reducing regulatory friction for US and EU-cleared products entering the market. Melbourne and Sydney hospital networks are piloting remote patient monitoring bundles that combine prescribed apps with wearable cardiac sensors. The Medical Research Future Fund allocates capital toward digital mental health interventions for rural and indigenous populations.
Prescribed Health Apps Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct value capture layers. Electronic health record incumbents leverage workflow integration to gatekeep prescription activation, while medical device manufacturers anchor app portfolios to hardware revenue streams. The field stratifies into three archetypes: infrastructure-integrated platforms, device-tethered systems, and standalone digital therapeutics. Consolidation pressure intensifies as pharmacy benefit managers demand outcome guarantees that only capitalized entities can underwrite.
Within the infrastructure-integrated tier, Epic Systems Corporation and Cerner Corporation exemplify channel-control strategies. Medtronic occupies a position representing device-tethered digital therapeutic models. These anchors illustrate how competitive positioning depends on whether prescription flow originates from EHR order sets, connected device ecosystems, or direct clinician solicitation.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| Athenahealth |
| Philips Healthcare |
| Siemens Healthineers |
| Medtronic |
| IBM Watson Health |
| McKesson Corporation |
| Others |
Value Chain & Pricing Dynamics
Specialized clinical validation talent clusters in the Boston-Cambridge corridor and Berlin, concentrating development cost structures in these hubs and pushing margin capture toward integrated delivery networks with captive formulary control. This geographic concentration of regulatory expertise creates pricing power asymmetries between well-capitalized developers and seed-stage entrants.
Pricing Analysis
FDA software-as-a-medical-device certification grade creates the primary spread between prescription-grade platforms and wellness-adjacent tools. Three-tier pricing structure across premium, standard, and economy levels reflects clinical evidence depth, with randomized controlled trial-backed digital therapeutics commanding subscription premiums. Pricing pressure stems from pharmacy benefit managers applying drug-formulary actuarial rigor to app-based interventions. Hospital systems show lowest price sensitivity where outcomes-based contracts guarantee hospitalization reduction, while standalone mental health platforms face acute sensitivity in direct-to-consumer channels.
Supply Chain Analysis
Export controls on AI-enabled clinical decision support algorithms limit technology flows between United States and Chinese development centers, fragmenting code-base architectures. Supply concentrates in United States, Germany, and United Kingdom for regulatory consulting and clinical validation services, with India emerging for back-end engineering. Raw material dependencies include cloud compute infrastructure, biometric sensor hardware, and HL7 FHIR interoperability middleware. Single-source vulnerability runs through Epic Systems and Cerner electronic health record gateways that gatekeep prescription activation. Distribution runs through hospital pharmacy and therapeutics committees with 18-24 month evaluation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positions. Switching costs for integrated delivery networks compound as clinical workflows embed prescribed apps into standard order sets.
For Market Incumbents: Entrench formulary position by deepening Epic and Cerner workflow integration while acquiring specialized clinical validation firms to compress competitor trial timelines. Emerging AI-augmented therapy platforms threaten to displace protocol fidelity with generative personalization, making certification investment in pediatric indications the critical defensive lever.
For New Entrants and Emerging Players: Pursue adolescent mental health and early-onset diabetes management where regulatory pathways remain underdeveloped relative to adult populations. Remote patient monitoring bundles combining prescribed apps with wearable cardiac sensors represent the most penetrable white space, given Medicare reimbursement code alignment. Go-to-market execution should anchor to integrated delivery network pilot programs rather than direct payer contracting.
For Investors and Strategic Acquirers: Capital is best deployed toward device-tethered digital therapeutic archetypes with existing Class IIb clearances and regulatory infrastructure extensible to repositioning competitors. Long-term viability over a multi-year horizon hinges on demonstrated outcomes data sufficient for pharmacy benefit manager outcome guarantees. The signal to watch is unbundling velocity in hospital procurement committees separating software licensing from hardware revenue streams.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Accelerates time-to-reimbursement through regulatory clarity for chronic disease management platforms. |
| Hospital System Partnership | Secures formulary inclusion through embedded Epic workflow integration and P&T committee validation. |
| Software Companion Development | Enables closed-loop therapeutic adjustments by pairing apps with connected glucose monitors and cardiac wearables. |
| Reimbursement Strategy | Aligns with Medicare remote patient monitoring codes and outcomes-based payer contracting requirements. |
| CE Marking Pathway | Opens European DiGA fast-track reimbursement through BfArM evidentiary standards for mental health applications. |
Study Parameters
A spread of perspectives from digital therapeutic developers, FDA regulatory consultants, hospital pharmacy and therapeutics committee members, and payer formulary directors converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, DiGA directory entries, CMS Medicare reimbursement code databases, and hospital procurement contract records. Bottom-up developer revenue estimates triangulated against top-down payer expenditure tracking across integrated delivery networks.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation modeling across product type, end user archetype, functionality depth, and delivery mode dimensions. CAGRs derived from logistic adoption curves calibrated to historical formulary inclusion timelines and reimbursement code expansion patterns. Forecast inputs incorporated biometric sensor convergence rates and AI-augmented therapy protocol maturation trajectories.
Sensitivities concentrate around FDA software-as-a-medical-device pathway evolution, European MDR notified body capacity constraints, and integrated delivery network unbundling velocity. Forecasts reflect documented assumptions on clinical validation cost trajectories and payer willingness-to-fund thresholds. Material shifts in HIPAA compliance architecture or pharmacy benefit manager outcome guarantee requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Medical Animation Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Cardiovascular Digital Solutions Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Healthcare Navigation Platform Market
Digital Health Solutions
AI in Patient Engagement Market
Digital Health Solutions
Behavioral Mental Health Care Software Market
Digital Health Solutions
Global Patient Engagement Solution Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
Distance Health Technologies Market