
 Eclinical Solutions Market | 2026-2036
Eclinical Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Eclinical Solutions Market Intelligence
North American software infrastructure investment is repositioning how trial data flows across sponsor-CRO networks. Oracle Corporation leverages its Cerner acquisition to anchor hospital-centric EHR-to-EDC pipelines. Medidata Solutions sustains dominance in cloud-native randomization and trial supply management through R&D intensity in AI-assisted monitoring. Veeva Systems differentiates by controlling the document-management layer that precedes data lock, extending its footprint from CRM into clinical operations.
Eclinical solutions encompass software platforms that digitize clinical trial workflows, including electronic data capture with audit-trail integrity, real-time randomization, and regulatory-compliant data repositories designed for FDA 21 CFR Part 11 and EMA Annex 11 validation. These systems eliminate paper-based source verification, compress database-lock timelines, and enable remote monitoring of multi-site studies across geographies. Cloud-based deployment now leads the deployment dimension as sponsors prioritize elastic compute for global trials, while SaaS models capture the fastest expansion by converting perpetual licenses to recurring revenue streams. EDC and CDMS product types hold the deepest margin pools due to their position as workflow-critical infrastructure with high switching costs.
FDA's 21 CFR Part 11 and EMA's Annex 11 guidelines mandate electronic signature validation and audit trails, directly shaping platform architecture and vendor qualification requirements. The EU AI Act and FDA's emerging guidance on AI/ML in clinical decision support are forcing vendors to build explainability layers into analytics tools. Stakeholders must monitor how regulators reconcile algorithmic trial oversight with existing GxP frameworks before committing to multi-year platform roadmaps.
Market Dynamics
Decentralized trial architectures are restructuring data infrastructure requirements, forcing sponsors to rebuild connectivity layers around patient-centric endpoints rather than site-centric workflows.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit-trail mandates compel pharmaceutical sponsors to replace paper-based source verification with validated EDC platforms, accelerating platform procurement cycles.
- AI-assisted monitoring:Machine learning algorithms embedded in clinical data management systems compress query resolution timelines and enable risk-based site monitoring, reducing manual data review overhead.
- United States demand concentration:Major CROs and biopharma sponsors headquartered in the US drive disproportionate platform investment, creating anchor demand that shapes vendor product roadmaps.
Market Restraints
- Specialized talent scarcity:Shortage of professionals qualified in GxP validation and FDA 21 CFR Part 11 compliance extends implementation timelines and inflates service costs.
- Legacy system entrenchment:Decades of institutional data locked in on-premise Oracle and IBM databases create switching friction that slows cloud migration.
- Input cost volatility:Cybersecurity infrastructure and cloud compute pricing fluctuations strain SaaS vendor margin structures, pressuring subscription pricing.
Strategic Opportunities
- EU AI Act compliance:Explainability requirements for algorithmic trial oversight create first-mover advantage for vendors building interpretable AI layers into analytics tools.
- Japan's PMDA digitalization:Regulatory momentum toward electronic submission formats opens whitespace for EDC platforms configured to Japanese pharmaceutical workflows.
- Direct-to-patient data capture:Wearable and mobile health device integration enables continuous outcome monitoring outside traditional site visits, expanding addressable trial designs.
Industry Challenges
- Multi-system integration complexity:Sponsors struggle to harmonize EDC, CTMS, and eTMF platforms from different vendors, creating data silos that undermine centralized oversight.
- GxP validation timeline compression:Compressed study start-up windows force rushed platform qualification, elevating audit risk and protocol deviation rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eclinical Solutions Market |
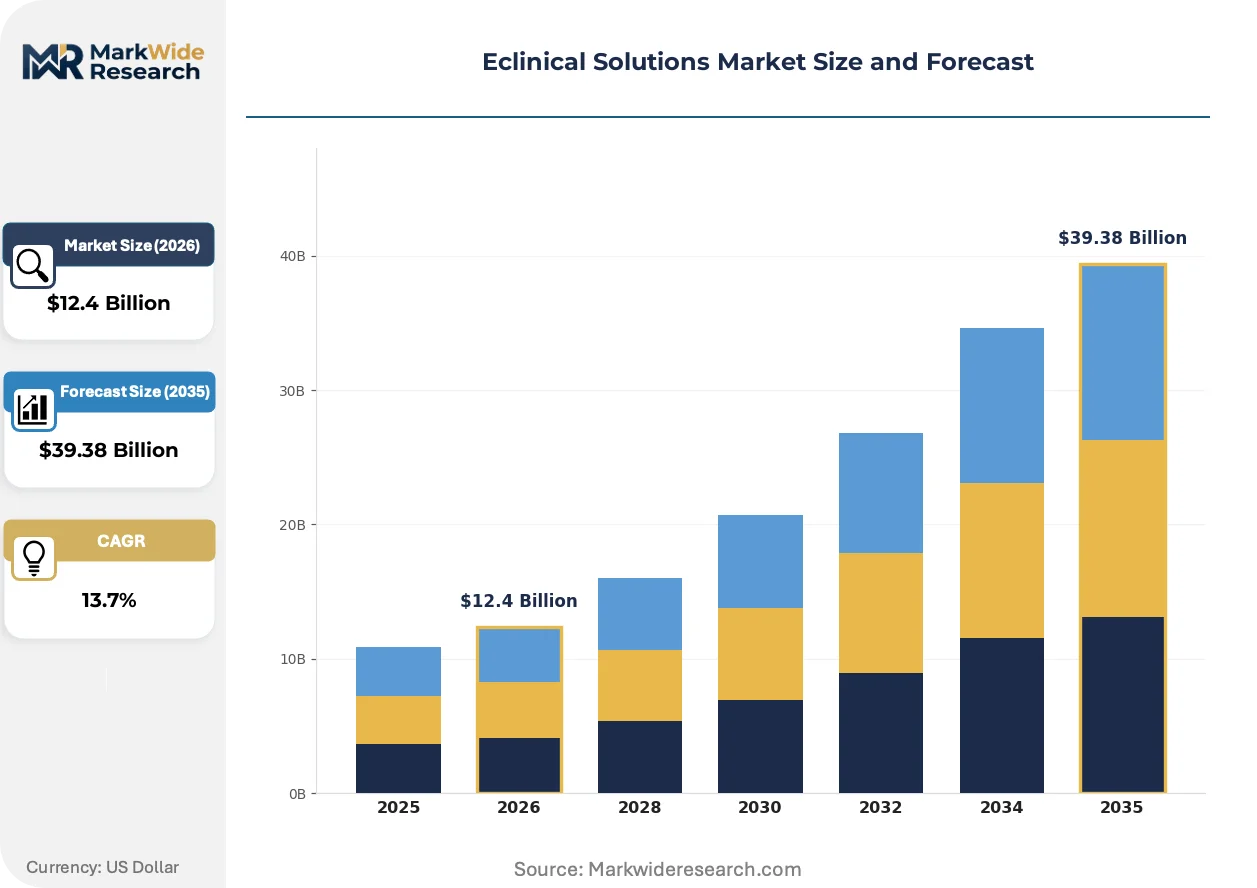
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $39.38 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EHR, CDMS, EDC, RTSM Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Clinical Research Organizations, Hospitals, Academic Institutions, Pharma Companies Solution: Data Management, Patient Recruitment, Compliance Solutions, Analytics Tools |
| Companies Covered | Oracle Corporation, Medidata Solutions, Veeva Systems, eClinical Solutions LLC, IQVIA, Parexel International Corporation, Dassault Systèmes, Clario, Signant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eclinical Solutions Market Strategic Shifts & Innovations
Real-world data pipelines and algorithmic oversight tools are converging to redefine how clinical evidence is generated, validated, and submitted to regulators.
Electronic data capture technology is converging with patient-facing mobile applications to enable decentralized trial execution. Mid-tier biotech sponsors are deploying these hybrid platforms at accelerated pace to access geographically dispersed patient populations. The structural consequence is a compression in database-lock timelines as source data flows directly from participants rather than through site coordinators.
EMA's Annex 11 guidelines on computerized systems are tightening validation requirements for cloud-hosted clinical applications. Vendors must now demonstrate data integrity controls across multi-tenant infrastructure, elevating compliance engineering costs. European sponsors are responding by consolidating vendor relationships to reduce qualification burden, favoring platforms with pre-validated infrastructure.
Subscription-based procurement is displacing perpetual license models across sponsor finance functions. Large pharmaceutical buyers are negotiating enterprise-wide EDC access rather than study-specific contracts, compressing vendor sales cycles but pressuring per-seat pricing. This shift is most visible in United States-based sponsor organizations where finance teams prioritize operational expenditure predictability.
Eclinical Solutions Market Segmentation
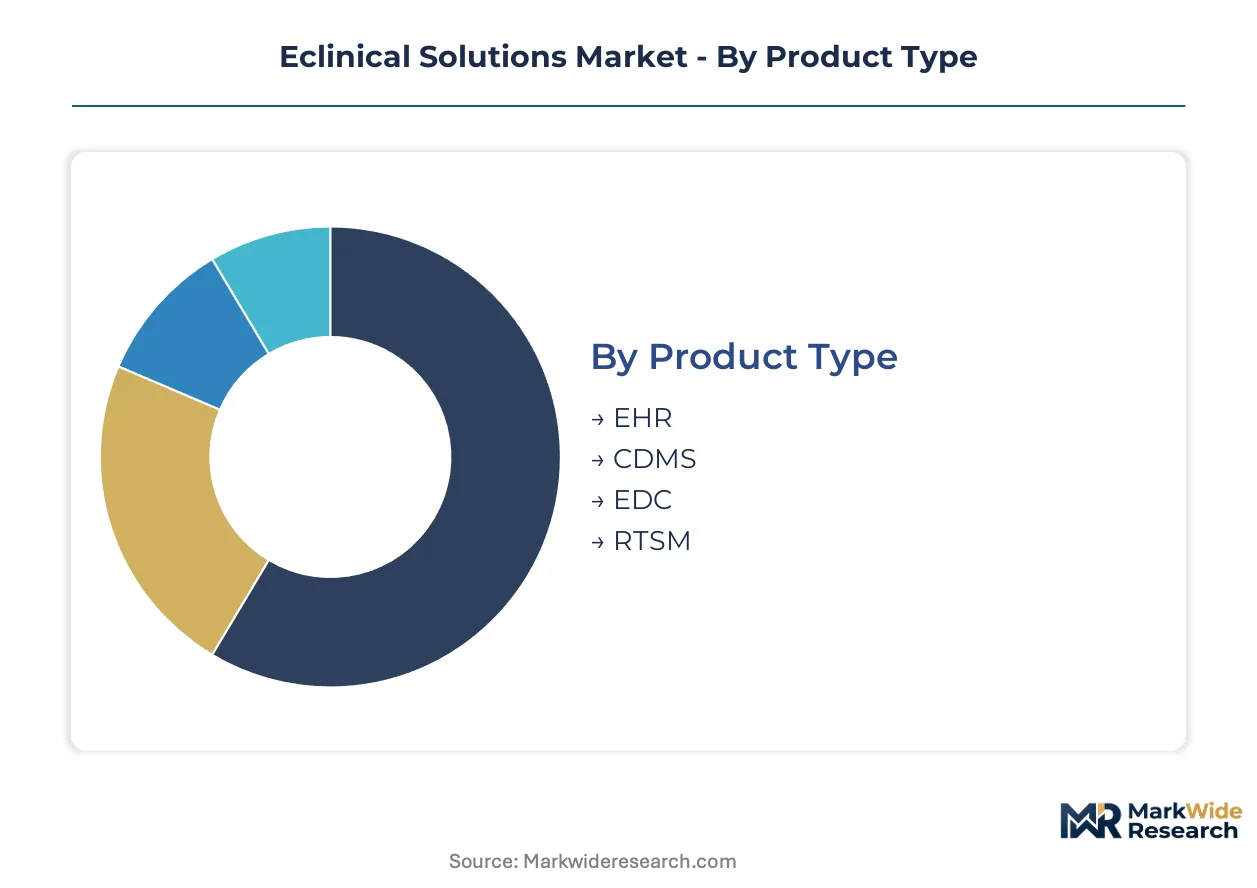
Eclinical solutions fragment across four functional dimensions that determine procurement patterns and margin structures. Product type and deployment mode together dictate validation burden and total cost of ownership for pharmaceutical sponsors.
Product Type:
FDA 21 CFR Part 11 and EMA Annex 11 impose distinct validation requirements across product categories, with EDC and CDMS carrying the heaviest audit-trail documentation burdens.
- EDC:Electronic data capture platforms enforce audit-trail integrity and electronic signature validation at the point of data entry. Pharma companies in the United States anchor demand as they replace paper source verification with validated digital workflows to compress database-lock timelines.
- CDMS:Clinical data management systems centralize query resolution and discrepancy management across multi-site studies. CROs drive procurement of cloud-native configurations to enable risk-based monitoring and reduce manual data review overhead.
- EHR:Electronic health record integration modules bridge hospital information systems with trial databases.
- RTSM:Randomization and trial supply management tools automate patient allocation and investigational product distribution.
Leading the category by volume: EDC. Growing fastest: CDMS.
Deployment:
Cost tier stratification separates enterprise pharmaceutical buyers from mid-tier biotech sponsors, with subscription models displacing perpetual licenses across finance functions.
- Cloud-Based:Multi-tenant infrastructure delivers elastic compute for global trials with automated scaling across geographies. United States-based sponsors prioritize this configuration for operational expenditure predictability and reduced internal IT overhead.
- SaaS:Subscription pricing converts capital expenditure to recurring revenue, compressing vendor sales cycles while pressuring per-seat pricing. Large pharmaceutical buyers negotiate enterprise-wide access rather than study-specific contracts.
- Hybrid:Mixed deployments retain sensitive patient data on-premises while pushing analytics workloads to cloud infrastructure.
- On-Premises:Legacy installations persist where institutional data remains locked in decades-old Oracle and IBM databases.
Dominant by revenue: Cloud-Based. Steepest expansion trajectory: SaaS.
End User:
Customer type determines feature requirements, with CROs prioritizing multi-study efficiency while academic institutions demand simplified interfaces.
- Clinical Research Organizations:Multi-sponsor service providers require platform configurations that segregate data across competing pharmaceutical clients. FDA 21 CFR Part 11 compliance documentation is non-negotiable for audit readiness.
- Pharma Companies:Sponsor organizations drive the deepest platform customization for protocol-specific workflows.
- Hospitals:Site-centric buyers emphasize EHR interoperability and reduced coordinator training burden.
- Academic Institutions:Budget-constrained researchers favor streamlined configurations with minimal validation overhead.
Primary volume anchor: Clinical Research Organizations. Fastest adoption climb: Pharma Companies.
Solution:
Application maturity varies sharply, with data management representing workflow-critical infrastructure and analytics tools still proving return on investment.
- Data Management:Core infrastructure for electronic capture, storage, and regulatory submission of clinical evidence. EMA Annex 11 tightening on cloud-hosted applications elevates compliance engineering costs for vendors.
- Compliance Solutions:Validation documentation and audit-trail maintenance tools address FDA 21 CFR Part 11 mandates.
- Patient Recruitment:Direct-to-patient engagement platforms integrate wearable and mobile health device data.
- Analytics Tools:AI-assisted monitoring and predictive risk scoring remain nascent as regulators develop guidance on algorithmic trial oversight.
Highest revenue concentration: Data Management. Gaining share fastest: Patient Recruitment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud computing infrastructure investment in the United States anchors geographic demand concentration for validated clinical platforms. Regulatory frameworks in Germany and Japan are tightening validation requirements for multi-tenant trial applications. India's software engineering clusters are emerging as delivery centers for platform customization and compliance documentation services.
United States
Major CROs and biopharma sponsors headquartered in Massachusetts and North Carolina drive disproportionate EDC procurement volume. FDA's 21 CFR Part 11 mandates electronic signature validation and audit-trail integrity, compelling sponsors to replace paper-based source verification. The Research Triangle Park cluster in North Carolina hosts concentrated platform implementation teams serving multi-site oncology trials.
Germany
Mid-sized pharmaceutical sponsors in Bavaria and Baden-Württemberg are consolidating vendor relationships to reduce qualification burden under EMA Annex 11. The EU AI Act's explainability requirements for algorithmic trial oversight are forcing vendors to build interpretable AI layers into analytics tools. Heidelberg's biotechnology corridor is witnessing accelerated adoption of cloud-native randomization platforms for precision medicine studies.
Japan
PMDA's regulatory momentum toward electronic submission formats is opening whitespace for EDC platforms configured to Japanese pharmaceutical workflows. The country's national pharmaceutical regulator is aligning validation requirements with ICH E6(R2) guidelines for risk-based quality management. Tokyo's pharmaceutical headquarters cluster is driving demand for bilingual compliance documentation and localized audit-trail architectures.
India
Global CROs operating in Hyderabad and Bangalore are expanding delivery centers for clinical data management and regulatory writing services. CDSCO's digitalization initiatives are streamlining trial approval timelines, attracting sponsor investment in local platform infrastructure. The Genome Valley biotech cluster near Hyderabad is emerging as a hub for decentralized trial execution using mobile health device integration.
United Kingdom
Post-Brexit regulatory divergence is creating dual validation requirements for sponsors running parallel EU and UK trials. The Medicines and Healthcare products Regulatory Agency is maintaining alignment with EMA Annex 11 while developing distinct guidance on AI-assisted monitoring. London's financial and life sciences convergence is driving enterprise-wide SaaS procurement models among multinational pharmaceutical sponsors.
Eclinical Solutions Market Key Industry Players
Global majors compete with regional champions across platform deployment modes and compliance documentation depth. The vendor base stratifies into three tiers: enterprise infrastructure providers with hospital-centric EHR pipelines, cloud-native specialists in randomization and trial supply management, and document-management platforms extending from CRM into clinical operations. Dominant competitive moves include strategic partnerships with academic medical centers and portfolio diversification into patient-facing mobile applications.
Within the enterprise infrastructure tier, Oracle Corporation and IQVIA exemplify scale-driven platform consolidation. Cloud-native specialists are represented by Medidata Solutions and Veeva Systems, which occupy positions emphasizing R&D intensity in AI-assisted monitoring and regulatory-compliant data repositories respectively. These named entities anchor archetype positioning rather than exhaust competitive coverage.
| Leading Market Players |
|---|
| Oracle Corporation |
| Medidata Solutions |
| Veeva Systems |
| eClinical Solutions LLC |
| IQVIA |
| Parexel International Corporation |
| Dassault Systèmes |
| Clario |
| Signant Health |
| Others |
Cost & Logistics Intelligence
Enterprise-SaaS bifurcation from mid-tier subscription tiers creates distinct margin architectures across the Eclinical Solutions Market, with FDA 21 CFR Part 11 validation costs embedding into premium pricing while unvalidated configurations compete on per-seat economics. This divergence manifests in supply chain concentration: validated infrastructure providers cluster in United States technology corridors, whereas customization and compliance documentation services flow from India's software engineering clusters.
Pricing Analysis
Validation-bundled service tiers separate FDA 21 CFR Part 11-compliant configurations from stripped-down entry offerings, with audit-trail documentation and electronic signature modules unbundled only at lower price points. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, customization scope, and after-sales implementation support. Pricing pressure stems from cybersecurity infrastructure cost inflation and cloud compute pricing volatility squeezing SaaS vendor margins. Mid-tier biotech sponsors exhibit highest price sensitivity, prioritizing operational expenditure predictability over feature depth, while large pharmaceutical buyers negotiate enterprise-wide access with least sensitivity to per-seat rates.
Supply Chain Analysis
Single-source vulnerability sits with United States-based hyperscale cloud infrastructure for validated multi-tenant deployments, with secondary concentration in Germany for EMA Annex 11-compliant hosting. The vendor ecosystem draws from India's software engineering clusters for platform customization, Ireland's regulatory writing centers for compliance documentation, and Singapore's data sovereignty facilities for Asia-Pacific trial hosting. Supply chain risk centers on regulatory divergence between FDA and EMA validation timelines creating dual-qualification burdens. Distribution runs through direct enterprise sales teams serving pharmaceutical sponsors, supplemented by CRO channel partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Eclinical Solutions Market functions as a cost-of-compliance story where FDA 21 CFR Part 11 validation requirements erect barrier-to-entry moats that favor incumbents with pre-validated infrastructure and documented audit-trail architectures.
For Market Incumbents: Extend platform consolidation into patient-facing mobile applications to capture decentralized trial workflows before mid-tier competitors achieve feature parity. Defend against cloud-native entrants by deepening EHR-to-EDC pipeline control through hospital system partnerships. Prioritize EU AI Act explainability engineering as a certification lever that delays unqualified competitors.
For New Entrants and Emerging Players: Direct-to-patient data capture channels offer the most penetrable white space, as wearable and mobile health device integration remains underdeveloped among established vendors. Target Japan's PMDA digitalization momentum for regulatory-first market entry, exploiting bilingual compliance documentation gaps. Pursue CRO service provider partnerships as the primary go-to-market angle to bypass direct sponsor sales cycle disadvantages.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native CDMS specialists given AI-assisted monitoring regulatory clarity as the catalyst. Long-term viability over a multi-year horizon favors platforms with pre-validated multi-tenant infrastructure and recurring SaaS revenue concentration. Watch FDA guidance publication timelines on algorithmic trial oversight as the inflection signal for analytics tool valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidating EDC, CTMS, and eTMF workflows reduces sponsor data silos and qualification burden. |
| Regulatory Approval Pathway | FDA 21 CFR Part 11 pre-validation accelerates pharmaceutical sponsor procurement cycles and platform lock-in. |
| Strategic Partnership | Academic medical center alliances anchor hospital-centric EHR-to-EDC pipeline development. |
| Product Launch | Patient-facing mobile applications enable decentralized trial execution and geographic patient expansion. |
| Acquisition of Specialist Firm | AI-assisted monitoring capabilities address EMA Annex 11 explainability requirements under EU AI Act. |
Research Approach
Multi-period observation of FDA 21 CFR Part 11 validation timelines, cloud infrastructure procurement patterns, and CRO platform adoption rates anchored the trend analysis, supplemented by interviews with clinical data management executives, regulatory affairs leads at pharmaceutical sponsors, GxP validation specialists, and CRO procurement officers. Secondary validation drew from FDA 510(k) filings, EMA qualification documentation, ClinicalTrials.gov protocol registrations, and hyperscaler healthcare cloud disclosures. Bottom-up segmentation modeling triangulated against top-down pharmaceutical R&D expenditure allocations.
Input-output matrices mapped deployment mode adoption curves to end-user procurement patterns across the projection horizon, with segmentation dimensions spanning product type, deployment configuration, customer archetype, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted penetration modeling. Forecast inputs incorporated pharmaceutical sponsor SaaS conversion rates and CDSCO digitalization initiative timelines.
The model holds under stable FDA and EMA regulatory convergence; deviation in AI/ML guidance divergence or cloud infrastructure tariff escalation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Cardiovascular Digital Solutions Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
United Kingdom Digital Health Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Artificial Intelligence in Medicine Market