
 Care Coordination Software Market | 2026-2036
Care Coordination Software Market Size, Share, and Industry Trends Forecast 2026-2036
Care Coordination Software Market Insights
Subscription-based financing and software-as-a-service leasing is narrowing the competitive field for smaller health IT vendors seeking enterprise contracts. Epic Systems Corporation leverages its captive EHR install base to extend into care coordination modules across academic medical centers. Oracle Health sustains competitive pressure through backward integration into cloud infrastructure and database layers. Athenahealth differentiates via its asset-light, billing-aligned deployment model that reduces upfront capital barriers for mid-sized physician groups.
Care coordination software comprises digital platforms that aggregate patient data across multiple care settings to orchestrate transitions, referrals, and follow-up protocols through automated workflows and real-time alerts. Core functional parameters include HL7 FHIR compliance for data exchange, role-based access controls, and longitudinal patient record assembly spanning acute, ambulatory, and post-acute encounters. Cloud-based deployments lead current revenue contribution due to lower total cost of ownership and faster implementation cycles, while EHR integration represents the fastest-growing integration level as health systems prioritize unified data architectures over fragmented third-party connectors. Home health agencies emerge as an expanding end-user segment driven by hospital-at-home reimbursement expansion and post-discharge monitoring requirements.
The Office of the National Coordinator for Health IT enforces interoperability rules under the 21st Century Cures Act that penalize information blocking and mandate standardized API access, directly reshaping product development roadmaps and procurement criteria. HIPAA security rule compliance and state-level Medicaid managed care contracting requirements create additional certification layers that filter vendor eligibility. Stakeholders must monitor evolving federal reimbursement policies for remote patient monitoring and hospital-at-home programs, as these payment models determine which care coordination features health systems prioritize in their technology investments.
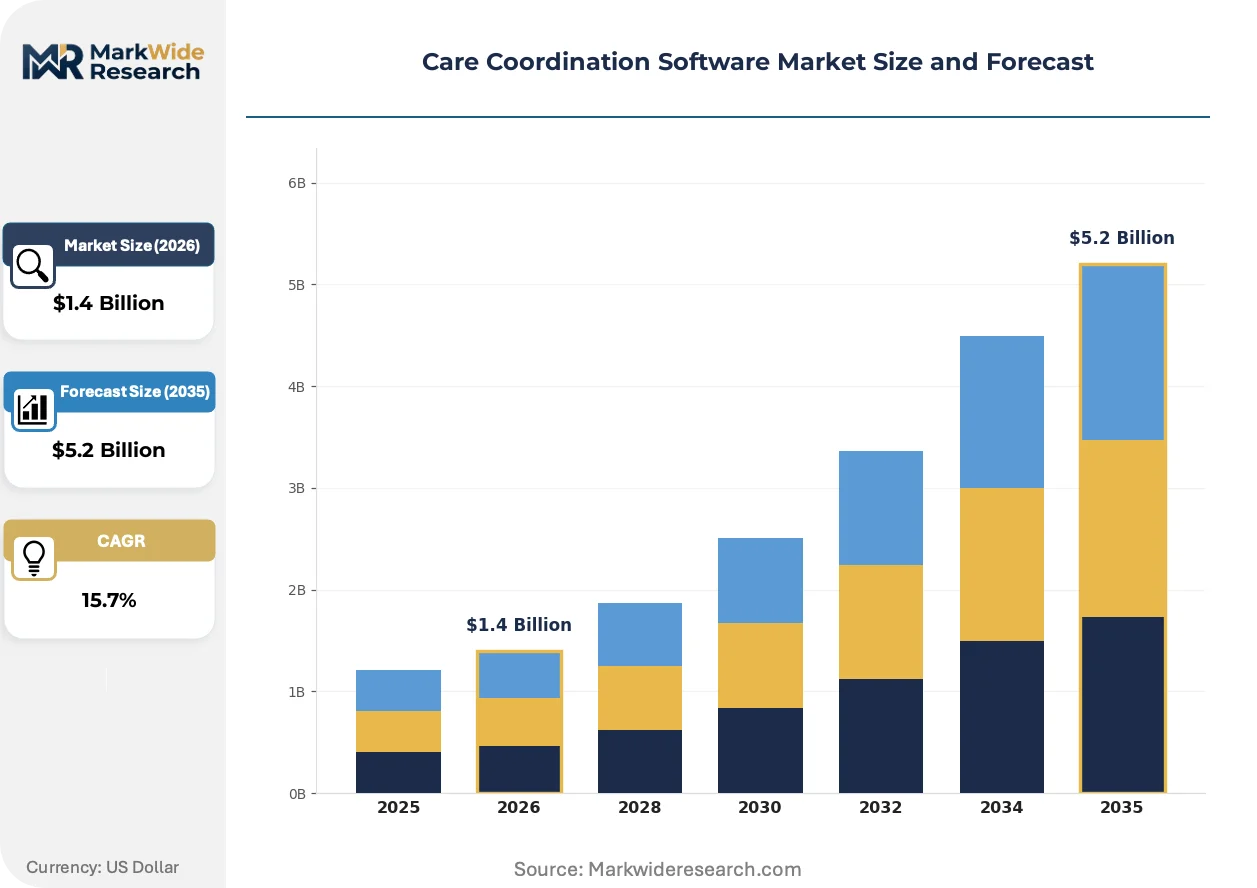
Market Dynamics
Cloud migration pressure from the 21st Century Cures Act's interoperability mandates is compressing vendor consolidation timelines while hospital networks abandon legacy on-premise installations for API-first architectures.
Growth Catalysts
- HL7 FHIR standardization:The ONC's information blocking rules under the 21st Century Cures Act compel health systems to replace proprietary data exchange protocols with standardized APIs, accelerating platform replacement cycles.
- Hospital-at-home reimbursement:CMS expansion of acute care at home waivers creates demand for remote monitoring integration within care coordination workflows across post-acute settings.
- Medicaid managed care consolidation:Texas and California's shift toward integrated delivery network contracting bundles care coordination software procurement into enterprise EHR decisions.
Market Restraints
- Legacy system technical debt:Decades-old HL7 v2 interfaces in community hospitals require expensive middleware layers that inflate total cost of ownership for cloud migration projects.
- Specialized clinical informaticist scarcity:Health systems in rural geographies face hiring gaps for FHIR implementation and workflow optimization roles, delaying deployment timelines.
- Interoperability certification friction:ONC's evolving certification criteria create procurement uncertainty as vendors race to maintain compliant status across multiple program years.
Strategic Opportunities
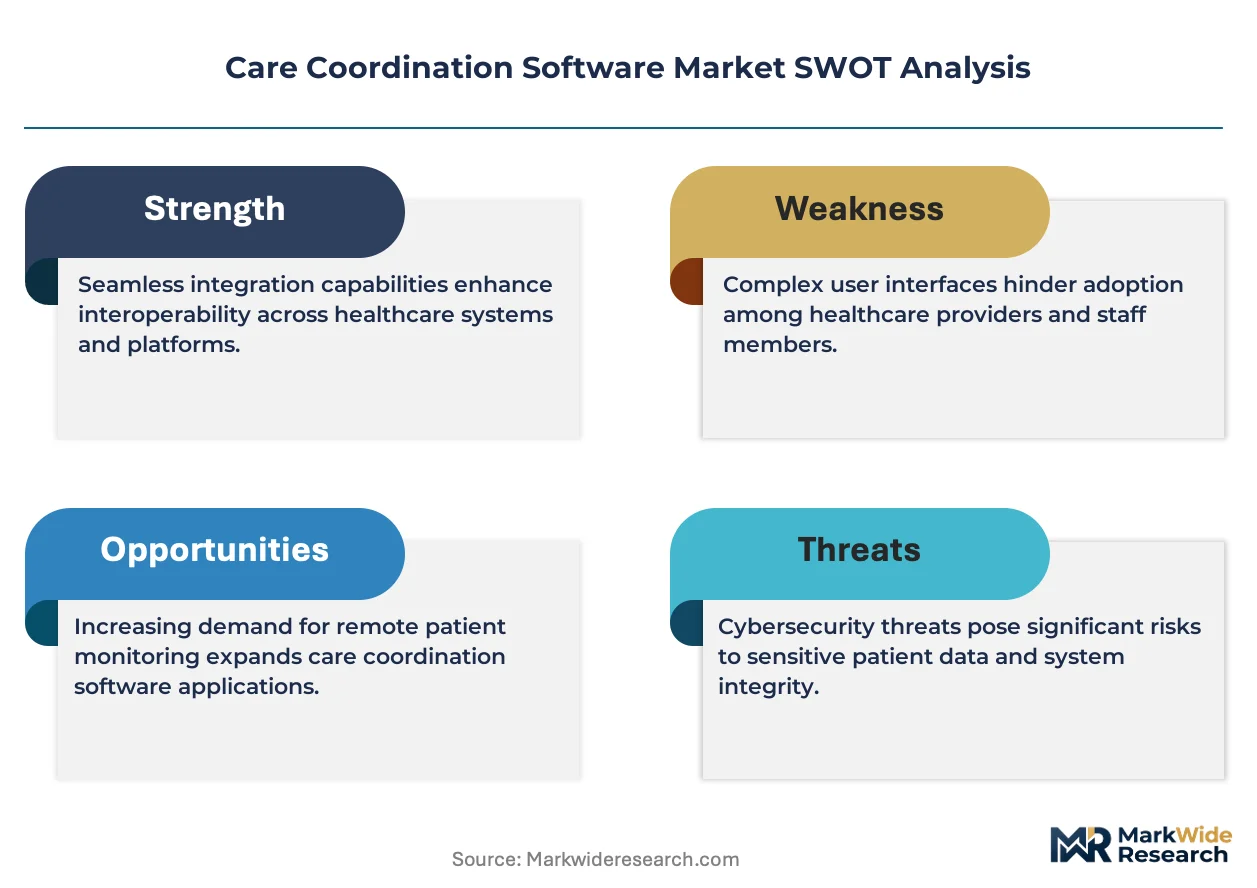
- Behavioral health integration:Untapped demand exists for care coordination platforms that bridge physical and mental health records across state Medicaid programs.
- Social determinants data layer:Emerging requirements for housing, transportation, and food security tracking within referral workflows create feature differentiation potential.
- Remote patient monitoring convergence:Integration of biometric device streams with care transition protocols opens new subscription revenue models for chronic disease management.
Industry Challenges
- Workflow reconfiguration complexity:Care teams resist abandoning established referral fax-and-phone habits despite digital platform availability, requiring sustained change management investment.
- Multi-stakeholder data governance:Disputes over patient record ownership between hospitals, skilled nursing facilities, and home health agencies stall information sharing agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Care Coordination Software Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $5.2 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Mobile Applications End User: Hospitals, Clinics, Home Health Agencies, Rehabilitation Centers Deployment: Web-based, Mobile-based, Client-server, Hosted Solutions Integration Level: Third-party Integrations, EHR Integration, API Integration, Custom Integrations |
| Companies Covered | Epic Systems Corporation, Oracle Health, Allscripts Healthcare Solutions, Athenahealth, eClinicalWorks, Koninklijke Philips, IBM Corporation, Optum, NextGen Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Care Coordination Software Market Trends and Innovations
Artificial intelligence and ambient documentation tools are embedding directly into care coordination workflows, compressing documentation burden while raising new questions about algorithmic accountability in clinical handoffs.
Natural language processing engines are virtualizing the extraction of unstructured clinical notes into structured referral data elements. Hospital networks in California are deploying these tools to automate prior authorization submissions. This compression of manual chart review is virtualizing administrative staffing models and reallocating nursing labor toward direct patient engagement.
The ONC's information blocking provisions under the 21st Century Cures Act now carry civil monetary penalties for health systems that restrict data exchange. This enforcement mechanism is accelerating API-first procurement criteria across integrated delivery networks. Vendors without certified FHIR endpoints are losing eligibility for enterprise contracts in Texas and Florida hospital systems.
Mid-sized physician groups are abandoning perpetual license software purchases in favor of subscription models that bundle implementation support. This shift displaces capital expenditure approval processes with operational budgeting frameworks. The change is most visible in Texas multispecialty groups where private equity consolidation has centralized technology procurement decisions.
Care Coordination Software Market Segmentation
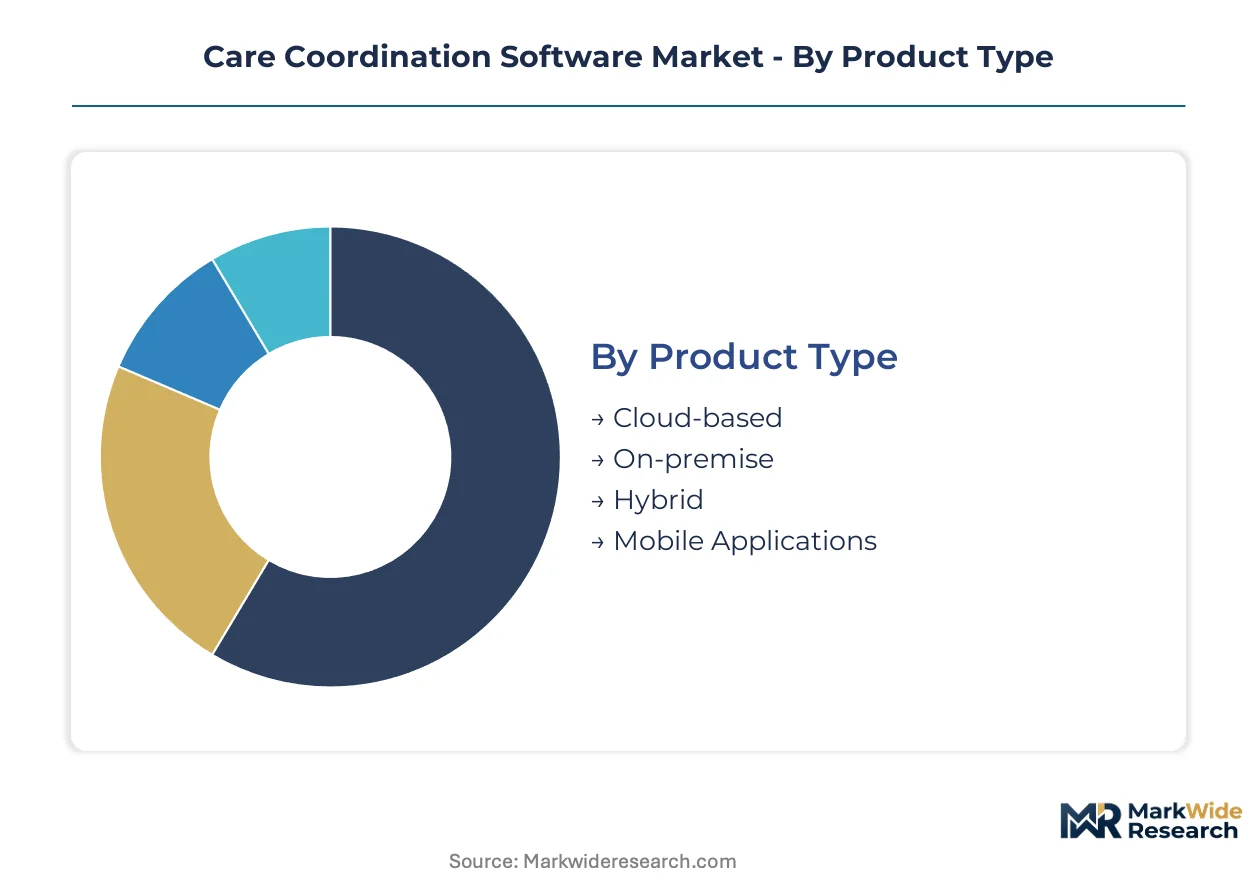
Segmentation in care coordination software reveals how procurement decisions fragment across technical architectures and care delivery settings. Each dimension carries distinct after-sales service intensity, from cloud platforms requiring continuous uptime guarantees to on-premise installations demanding periodic middleware upgrades.
Product Type:
After-sales service intensity varies sharply across deployment architectures, with cloud-based vendors absorbing infrastructure maintenance burdens while on-premise installations shift operational risk to internal IT teams.
- Cloud-based:Multi-tenant SaaS architectures with automatic FHIR compliance updates and 99.9% uptime SLAs. Hospital networks in California concentrate procurement here, driven by CMS interoperability deadlines that compress implementation windows.
- On-premise:Legacy server installations requiring dedicated hardware and periodic HL7 interface engine upgrades. Texas community hospitals retain these systems due to capital budget cycles that predate subscription financing adoption.
- Hybrid:Split architectures keeping sensitive data on local servers while routing interoperability through cloud gateways. Appeals to Medicaid managed care plans with mixed risk tolerance.
- Mobile Applications:Native iOS and Android tools for field-based care teams. Home health agencies in Florida deploy these for real-time visit documentation and secure messaging.
Cloud-based deployments hold the largest share; momentum sits with hybrid architectures as security-conscious providers seek intermediate risk postures.
End User:
Customer complexity scales with organizational size, from single-physician clinics needing plug-and-play onboarding to integrated delivery networks demanding enterprise workflow reconfiguration.
- Hospitals:Acute care facilities requiring 24/7 command center dashboards for discharge planning and bed management. Academic medical centers in California drive demand for AI-augmented prior authorization modules.
- Clinics:Ambulatory settings with lighter IT staffing, prioritizing EHR-embedded coordination tools over standalone platforms. Mid-sized multispecialty groups in Texas favor billing-aligned deployment models.
- Home Health Agencies:Post-acute providers managing remote patient monitoring integration and hospital-at-home reimbursement documentation. Fastest-expanding segment under CMS waiver expansion.
- Rehabilitation Centers:Skilled nursing and long-term acute care facilities tracking therapy schedules and insurance authorization timelines. Concentrated in states with bundled payment mandates.
Hospitals hold the largest share; home health agencies are climbing the fastest as reimbursement shifts toward post-acute settings.
Deployment:
Volume concentration follows accessibility tradeoffs, with browser-based tools capturing broad adoption while client-server installations retreat to regulated environments with strict data sovereignty requirements.
- Web-based:Browser-accessible platforms requiring no local installation, enabling rapid rollout across distributed care teams. Dominates mid-sized physician group procurement in Texas and Florida.
- Mobile-based:Smartphone and tablet-optimized interfaces for point-of-care documentation. Home health nurses in California rely on these for offline-capable visit capture with cellular sync.
- Client-server:Traditional two-tier architectures with thick client applications. Persists in rural hospitals with intermittent broadband connectivity and strict state Medicaid security requirements.
- Hosted Solutions:Single-tenant cloud deployments with dedicated virtual infrastructure. Appeals to county health departments and public hospital systems with procurement restrictions on shared environments.
Web-based deployment holds the largest share; mobile-based options show steepest expansion trajectory as field-based care models proliferate.
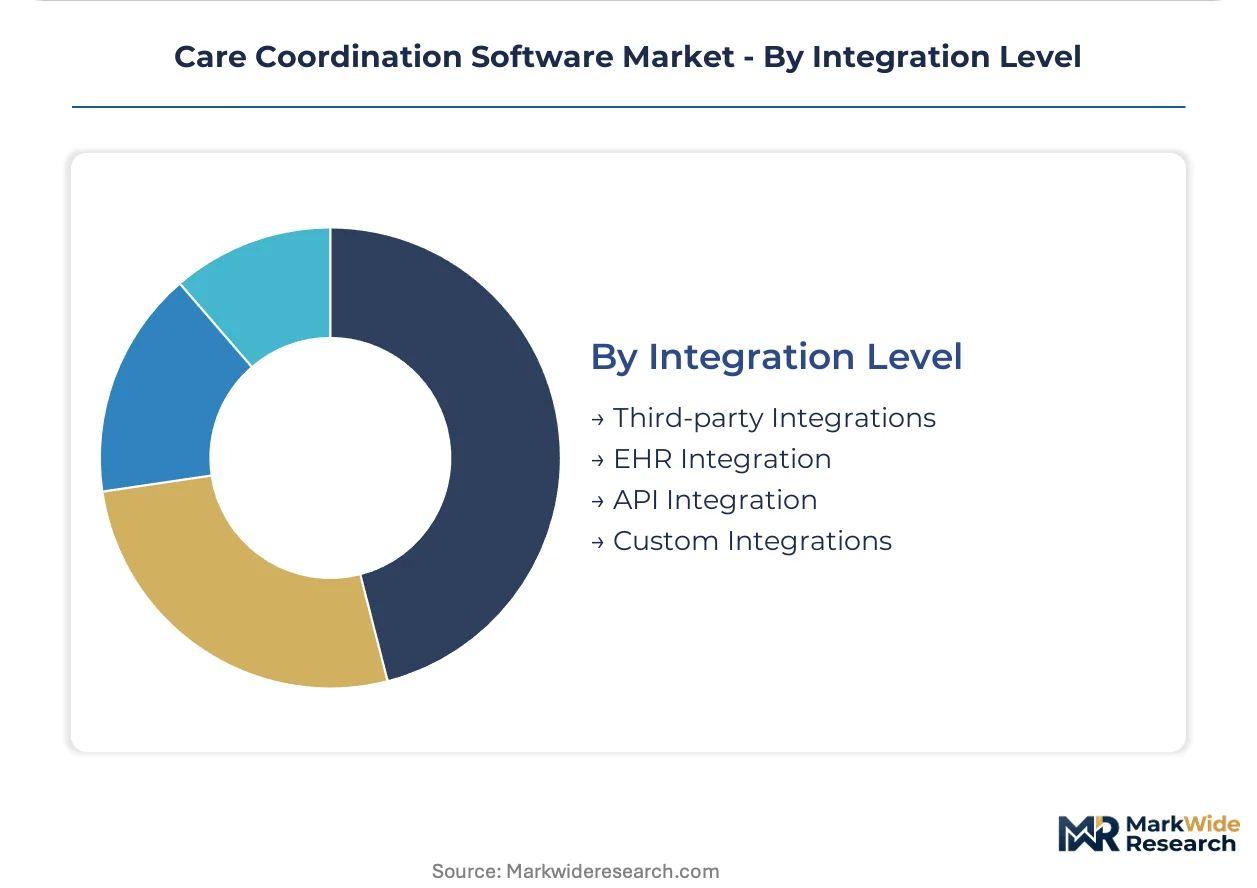
Integration Level:
Margin structures diverge based on technical complexity, with custom integration projects commanding premium professional services fees while standardized API connections compete on subscription pricing.
- Third-party Integrations:Pre-built connectors to ancillary systems such as laboratory information management and radiology PACS. Community hospitals leverage these to extend legacy EHR functionality.
- EHR Integration:Native embedding within Epic, Cerner, or MEDITECH workflows through SMART on FHIR apps. Academic medical centers prioritize unified data architectures over fragmented toolsets.
- API Integration:Direct RESTful and HL7 FHIR endpoint connections for health information exchange networks. Required for ONC certification compliance under 21st Century Cures Act enforcement.
- Custom Integrations:Bespoke middleware development for proprietary legacy systems or unique state Medicaid reporting requirements. Concentrated in large integrated delivery networks with heterogeneous technology estates.
EHR Integration holds the largest share; API Integration is gaining share fastest as interoperability mandates harden procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in California and Texas eclipses that of Florida and New York, where fragmented payer markets compress vendor margins. Hospital network consolidation in the West and Southwest concentrates procurement decisions into fewer hands. Medicaid managed care expansion in the South creates volume opportunity without corresponding pricing leverage.
United States
Integrated delivery networks in California and Texas bundle care coordination software into enterprise EHR contracts, squeezing standalone vendor margins. The 21st Century Cures Act's information blocking penalties enforce FHIR compliance deadlines that accelerate replacement cycles. Academic medical centers in Boston and Palo Alto pilot AI-augmented prior authorization modules.
United Kingdom
NHS England's integrated care systems consolidate commissioning power across regional footprints, favoring vendors with proven interoperability at scale. The NHS Long Term Plan mandates digitized referral management by 2025, forcing legacy system retirements. London-based trusts and Greater Manchester's devolved health system lead procurement volume.
Germany
Hospital federations in North Rhine-Westphalia and Bavaria negotiate collective software licensing to offset Gematik's electronic health record infrastructure costs. The Digital Healthcare Act enables prescribed health apps to enter statutory reimbursement, expanding addressable market for coordination platforms. Berlin's Charité university hospital anchors pilot programs for cross-sector care pathways.
India
Corporate hospital chains in Maharashtra and Karnataka deploy cloud-based coordination tools to manage medical tourism patient journeys across multiple cities. The National Digital Health Mission's health ID infrastructure creates foundational interoperability layer for private platform integration. Apollo and Max Healthcare networks in Delhi-NCR drive enterprise contract volumes.
Australia
Primary health networks in New South Wales and Victoria coordinate aged care transitions under My Aged Care program requirements, generating demand for post-acute workflow tools. The Australian Digital Health Agency enforces FHIR-based secure messaging standards that filter vendor eligibility. Sydney's eHealth NSW anchors statewide procurement frameworks.
Care Coordination Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the integration layer. The vendor base stratifies between EHR-native incumbents with captive install bases and standalone coordination platforms competing on speed-to-implement. Three archetypes dominate: EHR-extenders leveraging existing workflows, cloud-native challengers selling subscription agility, and infrastructure-backed conglomerates bundling compute with application layers. Consolidation pressure manifests through enterprise procurement bundling and API certification barriers that exclude point-solution vendors.
Among EHR-extender archetypes, Epic Systems Corporation and Oracle Health exemplify contrasting scale strategies. Epic leverages its captive academic medical center footprint to embed coordination modules within unified data architectures. Oracle anchors its position through backward integration into cloud infrastructure layers, bundling database and compute with application workflows. Athenahealth occupies the mid-market vector with billing-aligned deployment models that reduce capital barriers for physician groups. These three represent the competitive tension between closed-ecosystem depth and open-platform accessibility.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| Allscripts Healthcare Solutions |
| Athenahealth |
| eClinicalWorks |
| Koninklijke Philips |
| IBM Corporation |
| Optum |
| NextGen Healthcare |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on cloud infrastructure hyperscalers determines both pricing tier spreads and supply chain shape in care coordination software, as vendor margins compress under AWS and Azure compute pricing power while procurement officers negotiate multi-year enterprise commitments.
Pricing Analysis
Enterprise health system buyers anchor a three-tier pricing structure across premium, standard, and economy levels in care coordination software. Price differentiation rests on FHIR certification grade and after-sales service intensity, with ONC-certified platforms commanding premium positioning over uncertified alternatives. Pricing pressure stems from subscription fatigue among mid-sized physician groups consolidating vendor relationships. Safety-net hospitals and rural critical access facilities exhibit highest price sensitivity, while integrated delivery networks in California and Texas demonstrate lowest sensitivity due to bundled EHR procurement budgets.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for hardware-dependent deployment models, though pure software vendors face minimal direct exposure. Cloud infrastructure concentrates in the United States, Ireland, and Singapore, with compute and storage services drawing from hyperscaler data center networks. Raw material dependencies include silicon for edge devices, lithium for mobile hardware, and rare earth elements for server components. Single-source vulnerability sits with AWS, Microsoft Azure, and Google Cloud Platform for underlying infrastructure. Distribution runs through direct enterprise sales teams and health IT value-added resellers serving regional hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists in care coordination software as Medicaid managed care expansion creates niche demand for behavioral health and social determinants tracking modules that incumbent EHR platforms underserve.
For Market Incumbents: Harden API-first architecture investments to defend against cloud-native challengers exploiting FHIR implementation gaps. Deepen backward integration into data analytics layers to capture recurring revenue from population health contracts. Prioritize certification maintenance across multiple ONC program years to preserve enterprise eligibility. For New Entrants and Emerging Players: Rural health systems in the Mountain West represent underpenetrated territory where legacy technical debt and informaticist scarcity delay incumbent deployments. Target home health agencies in Florida and Texas with mobile-first, hospital-at-home reimbursement documentation tools. Pursue channel partnerships with regional health IT consultants possessing existing Medicaid managed care relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with proven FHIR interoperability and captive install bases. Long-term viability across the next decade hinges on successful navigation of AI accountability frameworks and algorithmic clinical decision support regulations. Acquisition target archetype: standalone coordination platforms with certified API endpoints and concentrated presence in post-acute settings. Monitor CMS reimbursement policy shifts for remote patient monitoring and hospital-at-home programs as primary inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification Investment | ONC compliance deadlines in Texas and California filter vendor eligibility for enterprise contracts. |
| Behavioral Health Module Development | State Medicaid programs in New York and Illinois create procurement demand for integrated mental health workflows. |
| Social Determinants Data Layer Integration | Housing and transportation tracking requirements differentiate platforms for accountable care organizations. |
| Remote Patient Monitoring Convergence | Biometric device streaming opens subscription revenue models for chronic disease management vendors. |
| Cloud Infrastructure Partnership | Hyperscaler alliances reduce compute costs and accelerate implementation timelines for mid-market buyers. |
Research Methodology
Desk research of SEC filings, hospital procurement databases, and CMS Medicare cost reports preceded structured interviews with chief medical information officers, health IT procurement directors, and FHIR implementation specialists. Primary fieldwork encompassed conversations with GPO contracts managers and post-acute care operations leaders across California, Texas, and Florida health systems. Secondary validation drew from ONC certification records, state Medicaid managed care contracting disclosures, and interoperability standards documentation. Bottom-up and top-down triangulation reconciled vendor-reported subscription metrics with health system technology expenditure surveys.
Assumptions held fixed include continued enforcement of 21st Century Cures Act information blocking penalties and stable CMS reimbursement for hospital-at-home waivers; variables included pace of AI regulatory framework development and state-level Medicaid managed care consolidation timelines. Segmentation dimensions modeled encompassed deployment architecture, organization size, integration complexity, end-user setting, and regional adoption pattern. CAGRs were derived from logarithmic trend fitting across historical expenditure data and projected procurement cycle replacements. Industry-specific forecast inputs included EHR replacement timelines and FHIR implementation completion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native challengers or hyperscaler platform entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Global Physical Therapy Software Market
Digital Health Solutions
Econsent in Healthcare Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Amblyopia Treatment Softwares Market