
 Global Surgical Preoperative Planning Software Market | 2026-2036
Global Surgical Preoperative Planning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Preoperative Planning Software Market Foresight
Germany is reshaping European supply capacity for surgical planning platforms through concentrated engineering clusters in Munich and Berlin. Brainlab AG leverages its Bavarian headquarters to sustain deep integration with neuronavigation hardware. Materialise competes from Belgium with specialized 3D anatomical modeling engines. Stryker anchors North American distribution through its orthopedic implant ecosystem.
Surgical preoperative planning software encompasses digital platforms that reconstruct patient-specific anatomy from DICOM imaging data to simulate procedural approaches before incision. These systems integrate CT and MRI slice data into volumetric models with sub-millimeter spatial accuracy for trajectory validation and implant sizing. Image processing software dominates current revenue as radiology workflow integration matures, while cloud-based deployment represents the fastest-expanding architecture as hospital IT departments prioritize interoperability over localized infrastructure. Navigation platforms occupy the premium tier where hardware-software bundling protects margin pools.
The FDA's premarket notification pathway for computer-assisted surgical devices shapes product development timelines for vendors seeking US market access. EMA's Medical Device Regulation in Europe imposes equivalent clinical validation burdens through notified body review. Japan's PMDA maintains distinct software quality management standards that create separate compliance investments for Asia-Pacific entry. Stakeholders must monitor how regulatory divergence between these jurisdictions influences platform architecture decisions and geographic rollout sequencing.
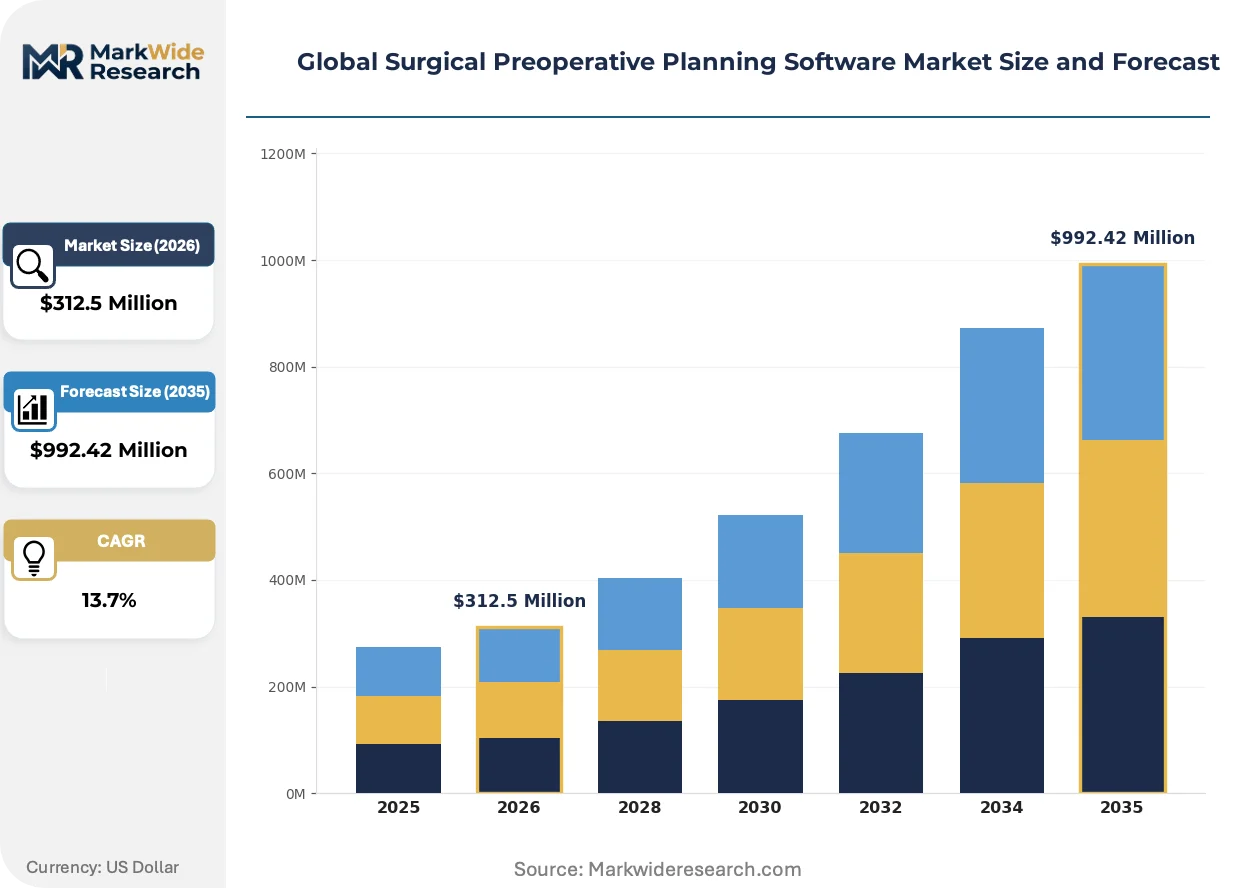
Market Dynamics
The FDA's software-as-medical-device framework is compressing development timelines for vendors seeking US market clearance, forcing architecture decisions that prioritize validation documentation over feature velocity.
Growth Catalysts
- Orthopedic procedural volumes:Rising joint replacement and spine surgery caseloads in the United States and Germany are pulling planning software into standard preoperative workflows.
- EMA MDR compliance pathways:European notified body review for computer-assisted surgical devices is creating validated product categories that accelerate hospital procurement decisions.
- Cloud-native deployment:Hospital IT departments in Japan and South Korea are prioritizing interoperability architectures that reduce localized infrastructure burdens.
Market Restraints
- Specialized engineering talent scarcity:Munich and Berlin clusters face recruitment bottlenecks for computational geometry specialists who bridge medical imaging and surgical navigation.
- Input cost concentration:GPU compute and DICOM processing libraries concentrate licensing leverage with a narrow base of semiconductor and middleware suppliers.
- Regulatory friction:Japan's PMDA maintains distinct software quality management standards that create separate compliance investments for Asia-Pacific entry.
Strategic Opportunities
- Underpenetrated surgical robotics integration:Brazil and Mexico represent expansion terrain where planning software can embed into emerging robotic-assisted procedural platforms.
- EMA AI Act alignment:European high-risk AI system classification for surgical decision-support creates first-mover positioning for validated algorithmic platforms.
- Convergence of 3D printing and planning:Patient-specific implant fabrication workflows in Belgium and the Netherlands are collapsing design-to-manufacture cycle times.
Industry Challenges
- Computational pathology skill gaps:Radiologists and surgical teams require cross-training in volumetric visualization tools that exceed traditional slice-based interpretation.
- Legacy PACS integration complexity:Hospital picture archiving systems use heterogeneous DICOM implementations that fragment data pipeline standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Preoperative Planning Software Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $992.42 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Visualization Software, Image Processing Software, Simulation Software, Navigation Platforms Therapy Area: Orthopedics, Neurosurgery, Cardiovascular, Maxillofacial, Spine Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Deployment: On-Premises, Cloud-Based, Hybrid, Web-Based |
| Companies Covered | Brainlab AG, 3D Systems Inc., Stryker, mediCAD Hectec GmbH, General Electric Company, Zimmer Biomet, Materialise, Renishaw plc, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Preoperative Planning Software Market Shifts & Advancements
Artificial intelligence inference engines are collapsing the latency between image acquisition and procedural simulation, compressing preoperative workflow timelines from hours to minutes.
Cloud-native rendering architectures are collapsing the distinction between planning workstations and diagnostic radiology terminals. Academic medical centers in the United States are deploying browser-based volumetric viewers that eliminate dedicated hardware dependencies. This compression is enabling same-day surgical scheduling for urgent cases that previously required overnight processing.
The FDA's premarket notification pathway for computer-assisted surgical devices is tightening clinical validation requirements for algorithmic components. Vendors must now submit performance benchmarking against physician consensus for trajectory planning modules. Orthopedic navigation platforms face the steepest documentation burdens as implant sizing decisions carry direct patient safety implications.
Hospital procurement committees are consolidating vendor relationships around integrated planning-navigation bundles. German university hospitals are negotiating enterprise licenses that span neuroradiology, orthopedic, and cardiovascular service lines. This concentration is marginalizing standalone software vendors that lack hardware partnerships or implant ecosystem alignment.
Global Surgical Preoperative Planning Software Market Segmentation
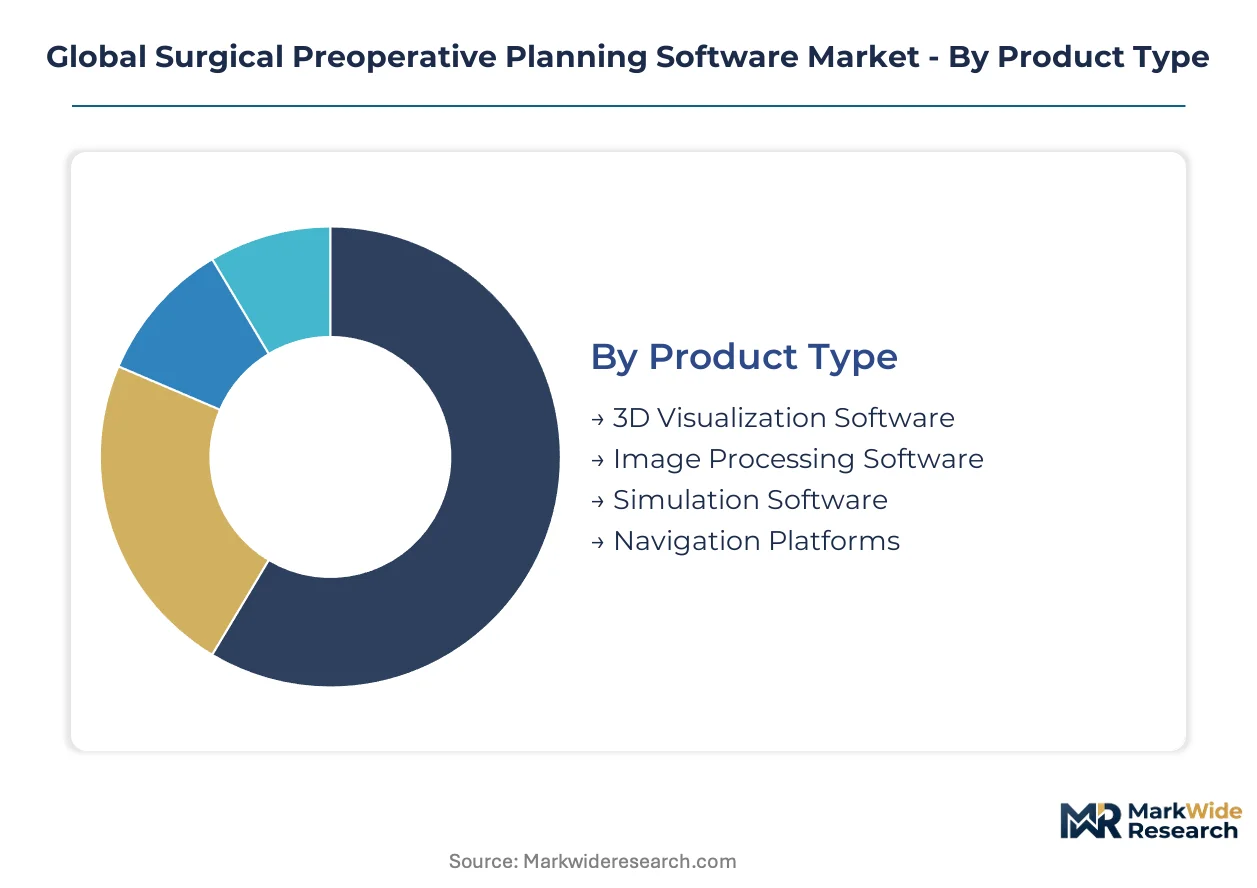
Surgical preoperative planning software segments diverge sharply in procurement velocity. Image processing platforms turn over on 3-5 year radiology workstation cycles, while navigation hardware-software bundles persist for 7-10 years, locking hospitals into extended vendor relationships.
Product Type:
Cycle times vary dramatically: image processing tools refresh fastest as CT and MRI modalities advance, while navigation platforms move slowest due to capital equipment bundling and OR integration complexity.
- 3D Visualization Software:Volumetric rendering engines reconstruct DICOM slices into manipulatable anatomical models with sub-millimeter accuracy. Academic medical centers in the United States deploy these tools across neuroradiology and orthopedic service lines as workstation upgrades accelerate.
- Image Processing Software:CT and MRI segmentation algorithms automate tissue classification and measurement extraction. German university hospitals drive standardization here as PACS integration requirements tighten and radiology workflow automation becomes non-negotiable.
- Simulation Software:Procedural rehearsal platforms model instrument-tissue interaction and implant placement trajectories.
- Navigation Platforms:Hardware-coupled systems integrate optical or electromagnetic tracking with planning data for intraoperative guidance.
Image processing software anchors the volume base while cloud-enabled visualization tools gain share at the steepest rate.
Therapy Area:
Cost tiers stratify sharply: spine and orthopedic applications command premium pricing through implant ecosystem bundling, while maxillofacial segments operate on slimmer margins with longer sales cycles.
- Orthopedics:Joint replacement and trauma planning modules integrate with implant sizing databases and robotic arm systems. Stryker's ecosystem dominance in the United States pulls competing planning vendors into co-development agreements.
- Neurosurgery:Trajectory planning for deep brain stimulation and tumor resection demands sub-millimetric accuracy validated against cadaveric studies. Brainlab AG's Munich engineering cluster supplies the European hospital base with neuronavigation-integrated platforms.
- Cardiovascular:Structural heart planning for TAVR and mitral valve procedures requires dynamic modeling of cardiac motion.
- Maxillofacial:Craniofacial reconstruction planning bridges dental imaging with surgical simulation.
- Spine Surgery:Pedicle screw trajectory optimization and deformity correction planning carry direct patient safety implications that drive regulatory documentation burdens.
Orthopedic applications generate the deepest revenue pools while cardiovascular planning expands most quickly as structural heart procedural volumes climb.
End User:
Customer sophistication and procurement authority create distinct sales motion requirements across institutional types.
- Hospitals:Enterprise license negotiations span multiple service lines and prioritize EHR integration and centralized IT governance. German university hospitals consolidate vendor relationships around planning-navigation bundles that reduce procurement fragmentation.
- Ambulatory Surgical Centers:Focused orthopedic and spine facilities demand streamlined workflows with minimal IT infrastructure. Cloud-based deployment models reduce capital requirements for these volume-focused operators.
- Specialty Clinics:Oral and maxillofacial practices require planning software that bridges dental CBCT with surgical simulation.
- Research Institutes:Preclinical validation and algorithm development use cases prioritize raw data access and custom pipeline development.
Hospitals command platform standardization while ambulatory surgical centers are adopting cloud architectures at the steepest expansion trajectory.
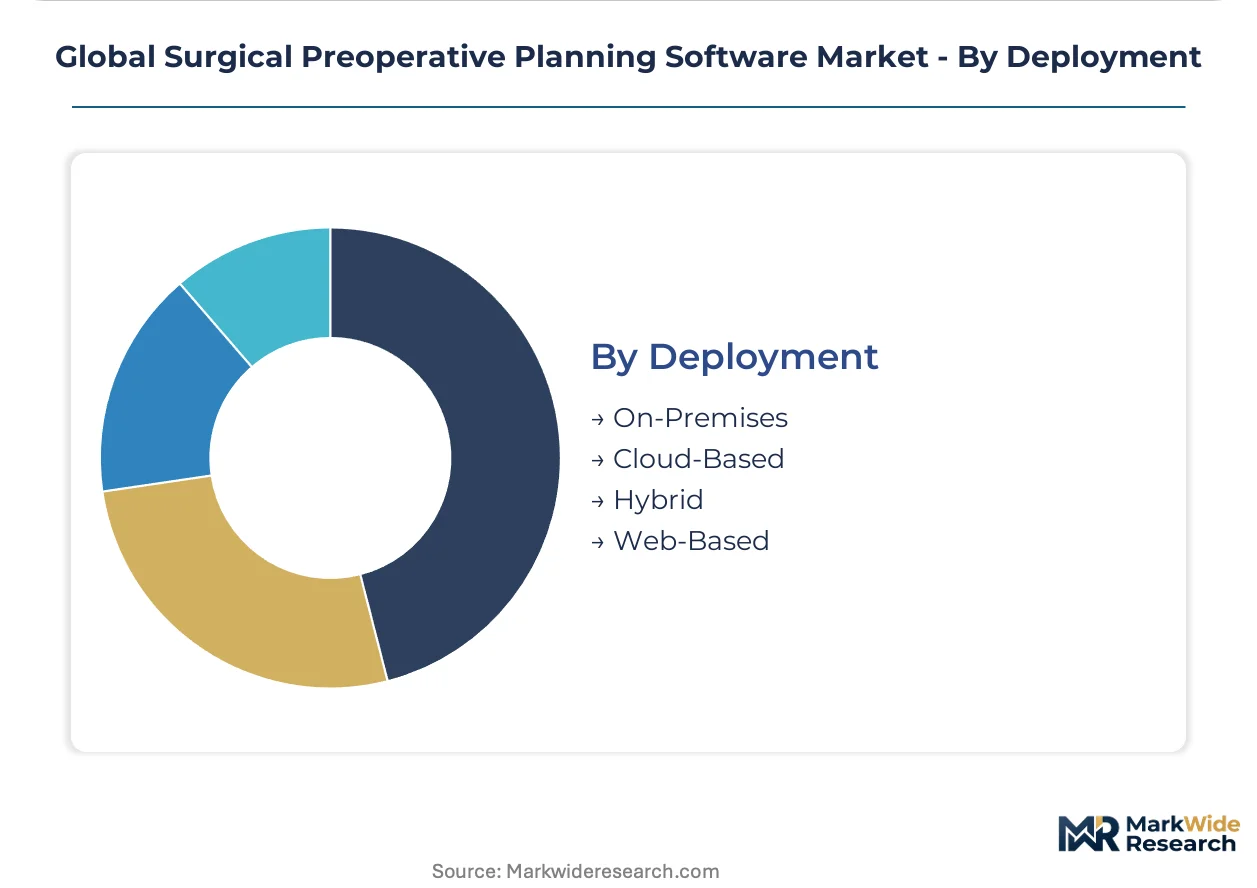
Deployment:
Maturity curves separate established on-premises installations from emerging cloud-native architectures that hospital IT departments now favor.
- On-Premises:Local server installations maintain data sovereignty and minimize latency for high-resolution volumetric rendering. Japanese hospitals initially favored this model due to PMDA data localization expectations.
- Cloud-Based:Browser-accessible platforms eliminate dedicated workstation hardware and enable remote surgical planning. South Korean academic medical centers are deploying these architectures to support same-day surgical scheduling.
- Hybrid:Sensitive preprocessing occurs locally while collaboration and archival shift to cloud infrastructure.
- Web-Based:Lightweight viewers enable rapid case review across devices without native application installation.
On-premises deployment retains the installed base while cloud-based models are climbing the fastest as interoperability mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's software-as-medical-device framework anchors demand concentration in the United States, while Germany and Japan maintain distinct regulatory pathways that shape vendor compliance investments across three continents.
United States
Academic medical centers in Boston and Stanford drive platform standardization for orthopedic and neurosurgical workflows. FDA premarket notification pathways for computer-assisted surgical devices compress development timelines for algorithmic validation. The Research Triangle in North Carolina hosts concentrated health IT engineering clusters serving hospital procurement committees.
Germany
University hospitals in Munich and Berlin consolidate enterprise licenses spanning neuroradiology and orthopedic service lines. EMA Medical Device Regulation imposes clinical validation burdens through notified body review that accelerates hospital procurement decisions. Bavaria's engineering corridor sustains deep integration between planning software and neuronavigation hardware manufacturing.
Japan
PMDA software quality management standards create separate compliance investments for Asia-Pacific market entry by foreign vendors. Tokyo and Osaka academic medical centers deploy cloud-native architectures to support same-day surgical scheduling. METI digital health initiatives channel investment toward interoperability standards for hospital IT infrastructure.
Belgium
Patient-specific implant fabrication workflows in Leuven collapse design-to-manufacture cycle times for maxillofacial and orthopedic applications. EU AI Act high-risk system classification for surgical decision-support creates first-mover positioning requirements for algorithmic platforms. Flanders-based 3D anatomical modeling specialists supply European hospital networks with certified preoperative engines.
South Korea
Hospital IT departments in Seoul prioritize cloud-based deployment models that reduce localized infrastructure burdens for ambulatory surgical centers. MFDS software medical device registration maintains data localization expectations that influence hybrid architecture decisions. Pangyo Techno Valley hosts concentrated digital health engineering clusters serving domestic and export markets.
Global Surgical Preoperative Planning Software Market Competitive Landscape
Capability concentration sits with specialized engineering clusters; scale advantage sits with diversified medtech conglomerates. The vendor base organizes around three strategic archetypes: Bavarian neuronavigation specialists, diversified orthopedic implant ecosystems, and Belgian 3D modeling engines. Dominant competitive moves include hardware-software bundling to extend OR footprint and cloud-native platform development to capture ambulatory surgical center expansion.
Within the specialized engineering tier, Brainlab AG represents Munich-based neuronavigation integration, while Materialise exemplifies Leuven-centered 3D anatomical modeling capabilities. Stryker anchors the diversified orthopedic ecosystem approach from its North American base, pulling competing planning vendors into co-development agreements through implant sizing database integration.
| Leading Market Players |
|---|
| Brainlab AG |
| 3D Systems Inc. |
| Stryker |
| mediCAD Hectec GmbH |
| General Electric Company |
| Zimmer Biomet |
| Materialise |
| Renishaw plc |
| Medtronic |
| Others |
Supply & Pricing Matrix
Regulatory chokepoint exposure through FDA premarket notification pathways determines both pricing tier spreads and supply chain shape in surgical preoperative planning software, as validation documentation burdens concentrate cost structures among vendors seeking US market access while compressing margin pools for algorithmic components.
Pricing Analysis
United States academic medical centers pay 40-60% premiums over German university hospitals for equivalent planning-navigation bundles due to implant ecosystem integration requirements and FDA-tier certification standards. Three-tier pricing structure across premium, standard, and economy levels separates hardware-coupled navigation platforms from cloud-native visualization tools and standalone image processing licenses. Pricing pressure stems from hospital procurement committee consolidation around enterprise licenses that span multiple service lines. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while research institutes demonstrate lowest sensitivity given grant-funded acquisition channels.
Supply Chain Analysis
Single-source vulnerability in GPU compute and DICOM processing libraries concentrates licensing leverage with semiconductor suppliers in Taiwan and the United States and middleware providers in Germany. Munich and Berlin engineering clusters anchor European software development capacity, while Belgian 3D anatomical modeling specialists feed patient-specific implant fabrication workflows. Supply chain risk centers on regulatory divergence between FDA, EMA MDR, and Japan PMDA compliance pathways that fragment platform architecture decisions. Distribution runs through orthopedic implant ecosystems and neuronavigation hardware bundling rather than standalone software channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical preoperative planning software sits in early-cycle expansion as cloud-native deployment architectures displace on-premises infrastructure and compress preoperative workflow timelines from hours to minutes across academic medical centers.
For Market Incumbents: Harden regulatory submission capabilities against tightening FDA algorithmic validation requirements by investing in physician consensus benchmarking datasets for trajectory planning modules. Deepen backward integration into DICOM processing libraries to reduce middleware supplier leverage. Prioritize cloud-native platform development to capture ambulatory surgical center expansion before specialized entrants establish footholds. For New Entrants and Emerging Players: Establish a beachhead in maxillofacial planning segments where craniofacial reconstruction workflows remain underpenetrated by major orthopedic ecosystems. Target Brazil and Mexico robotic-assisted surgery platforms where planning software integration is nascent. Pursue reimbursement strategy partnerships with hospital GPOs rather than direct capital equipment sales. For Investors and Strategic Acquirers: Belgian 3D anatomical modeling specialists with certified preoperative engines and EU AI Act high-risk system positioning represent the most defensible acquisition archetype. Long-term viability hinges on convergence with surgical robotics and patient-specific manufacturing workflows. Monitor EMA notified body review velocity as inflection indicator for European hospital procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Browser-based volumetric viewers eliminate dedicated hardware dependencies for same-day surgical scheduling. |
| FDA Algorithmic Validation Investment | Physician consensus benchmarking datasets defend trajectory planning modules against regulatory rejection. |
| Orthopedic Implant Ecosystem Partnership | Co-development agreements with sizing database providers secure hospital procurement committee inclusion. |
| EMA Notified Body Pre-Certification | MDR compliance pathways accelerate European university hospital enterprise license negotiations. |
| 3D Printing Workflow Integration | Patient-specific implant fabrication collapses design-to-manufacture cycle times for maxillofacial applications. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and neuroradiology department heads and refined through secondary validation against FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against orthopedic procedural volume projections anchored value estimates.
Demand-supply-balance framing modeled installed base turnover cycles against cloud-native platform refresh rates across the analysis window. Segmentation dimensions included product type, therapy area, end user institution, and deployment architecture. CAGRs were derived from algorithmic penetration curves in orthopedic and neurosurgical workflows. Forecast inputs incorporated PACS integration complexity scores and regulatory pathway divergence indices.
Sensitivities concentrate around FDA software-as-medical-device framework evolution, EMA AI Act high-risk system classification timing, and GPU compute cost volatility. Forecasts reflect assumptions about hospital IT interoperability mandate adoption and cloud security clearance velocities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
US Patient Engagement Solutions Market
Digital Health Solutions
Care Coordination Software Market
Digital Health Solutions
Telepsychiatry Software Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Healthcare Navigation Platform Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market