
 Distance Health Technologies Market | 2026-2036
Distance Health Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Distance Health Technologies Market Outlook
Clinical-grade diagnostic accuracy in remote monitoring hardware is redrawing competitive boundaries across the Distance Health Technologies landscape. Teladoc Health leverages its virtual care infrastructure to anchor enterprise contracts with large health systems. Koninklijke Philips N.V. sustains technology leadership in connected monitoring devices through deep FDA 510(k) clearance experience. Siemens Healthineers GmbH competes by extending imaging analytics into cloud-native telemedicine workflows.
Distance health technologies encompass integrated hardware-software systems that transmit physiological data, enable synchronous virtual consultations, and algorithmically triage patient conditions using FDA-cleared software algorithms and ISO 13485-compliant device manufacturing. These systems serve to decentralize care delivery, reduce acute hospital utilization, and enable continuous chronic disease management outside traditional clinical settings. Remote monitoring devices currently occupy the largest revenue pool within product type segmentation, while AI analytics within technology segmentation captures the fastest expansion trajectory as predictive algorithms gain regulatory acceptance. The subscription-based delivery model dominates enterprise procurement channels, though pay-per-use structures are gaining traction among smaller provider networks seeking variable cost alignment.
FDA digital health pre-certification programs, HIPAA interoperability mandates, and emerging state-level telehealth parity laws collectively shape product development roadmaps and market access conditions for technology developers. The Centers for Medicare & Medicaid Services maintains pivotal influence through reimbursement code valuations that directly determine provider willingness to adopt remote monitoring platforms. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic software, as classification determinations will dictate capital requirements and time-to-market for next-generation platforms.
Market Dynamics
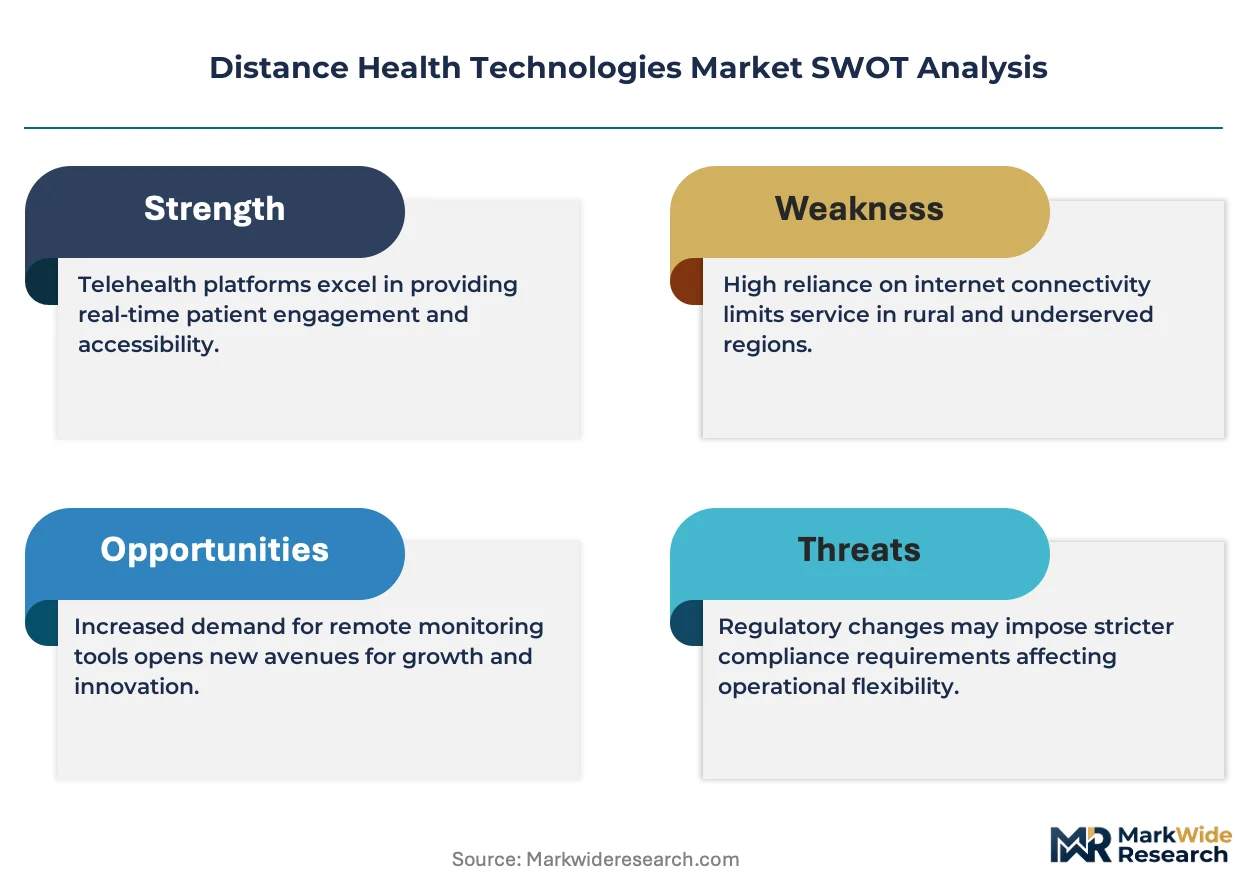
Medicare reimbursement expansion for remote therapeutic monitoring is compressing provider adoption cycles and redrawing competitive boundaries across hardware-software integration tiers.
Growth Catalysts
- Remote therapeutic monitoring codes:CMS reimbursement valuations for RTM services are pulling capital into connected device deployments at cardiology and pulmonology practices.
- Chronic disease management programs:Hospital networks are scaling RPM infrastructure to reduce acute utilization for heart failure and COPD populations.
- AI-enabled diagnostic software:FDA pre-certification pathways for algorithmic triage tools are shortening regulatory timelines for predictive analytics platforms.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry capacity constraints are creating lead time volatility for biosensor chipsets in connected monitoring devices.
- HIPAA interoperability mandates:Compliance costs for health data exchange standards are elevating platform development expenses for mid-tier vendors.
- Clinical validation requirements:FDA 510(k) clearance timelines for novel physiological monitoring algorithms are extending capital lock-up periods.
Strategic Opportunities
- Rural health clinic networks:Federally qualified health centers in underserved counties present deployment white space for asynchronous telemedicine platforms.
- Behavioral health integration:Convergence of RPM devices with digital therapeutics for depression and anxiety management is opening reimbursement-adjacent revenue pools.
- State-level telehealth parity laws:Mandates for commercial payer reimbursement equivalence are expanding addressable provider bases beyond Medicare-dependent segments.
Industry Challenges
- ISO 13485 quality management certification:Device manufacturers face 12-18 month implementation timelines to meet medical device quality system requirements.
- Legacy EHR integration complexity:Health systems struggle to normalize streaming physiological data into existing Epic and Cerner workflow architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distance Health Technologies Market |
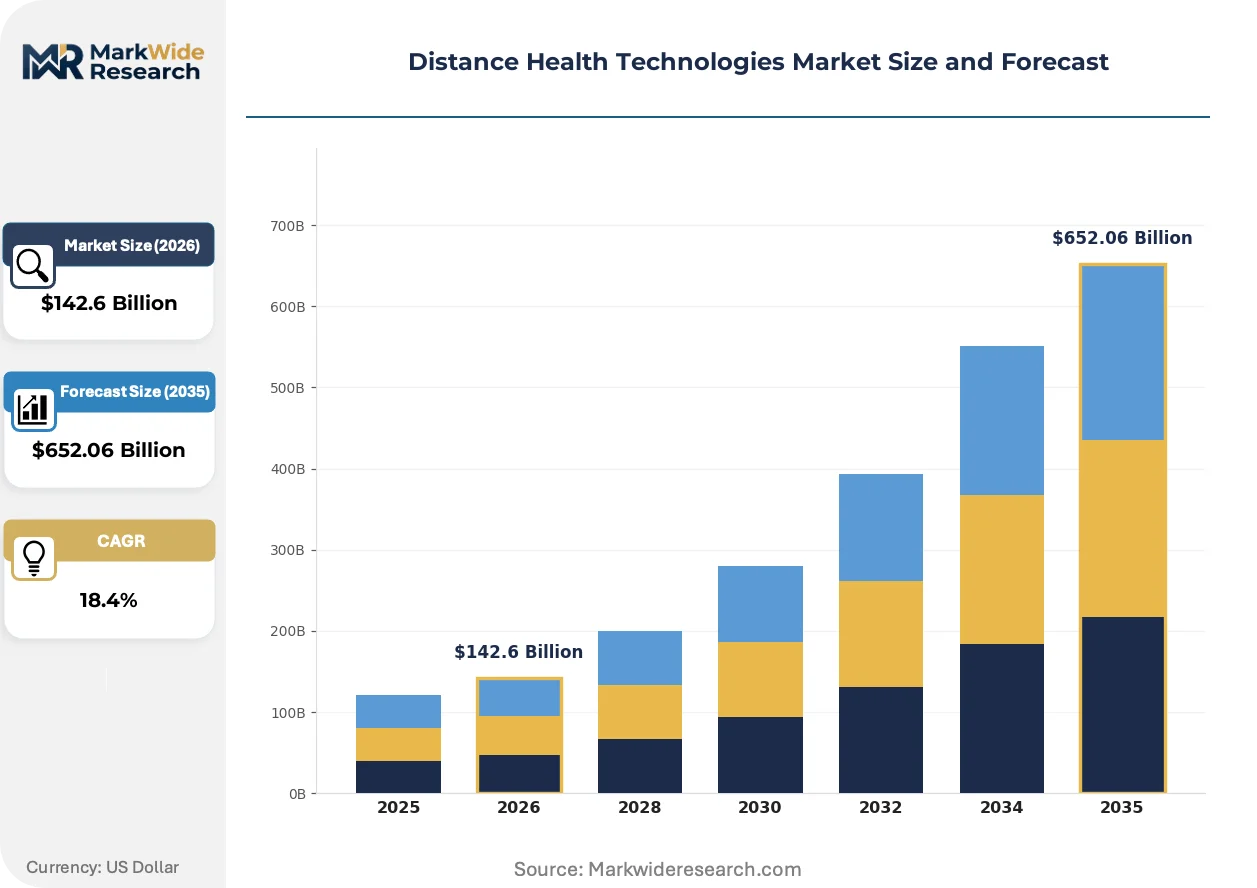
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $652.06 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telemedicine Platforms, Remote Monitoring Devices, Mobile Health Applications, Virtual Care Solutions Technology: Cloud Computing, AI Analytics, IoT Connectivity, Blockchain Security End User: Patients, Healthcare Providers, Insurance Companies, Pharmaceutical Firms Delivery Model: Subscription-Based, Pay-Per-Use, Freemium, On-Premise |
| Companies Covered | Teladoc Health, Inc., Medtronic Plc, Koninklijke Philips N.V., Siemens Healthineers GmbH, TytoCare Ltd., OMRON Healthcare, Inc., Rudolf Riester GmbH, Health Recovery Solutions, Masimo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distance Health Technologies Market Strategic Shifts
Algorithmic triage capabilities are compressing the traditional diagnostic chain and forcing hardware vendors to recalibrate around software-centric value capture.
Continuous glucose monitoring technology is decomposing the point-of-care testing infrastructure that has dominated diabetes management for decades. Endocrinology practices are adopting factory-calibrated sensors at accelerating velocity. This shift is decomposing the revenue model built on discrete test strip consumption and specialized clinic visits.
FDA's evolving guidance on artificial intelligence-enabled diagnostic software is creating classification uncertainty for developers of predictive cardiac event algorithms. The industrial consequence is capital rationing toward de novo pathways rather than 510(k) predicates. Cloud-native RPM platforms with embedded machine learning are most affected and are responding by front-loading clinical validation studies.
Hospital procurement committees are unbundling remote monitoring contracts from traditional medical device purchasing frameworks. Value analysis teams now separate hardware acquisition from software subscription negotiations, with IT governance committees taking control of analytics platform selection. This pattern is most visible in multi-hospital systems across Texas and Florida where capital allocation authority has shifted from clinical service lines to centralized digital transformation offices.
Distance Health Technologies Market Segmentation
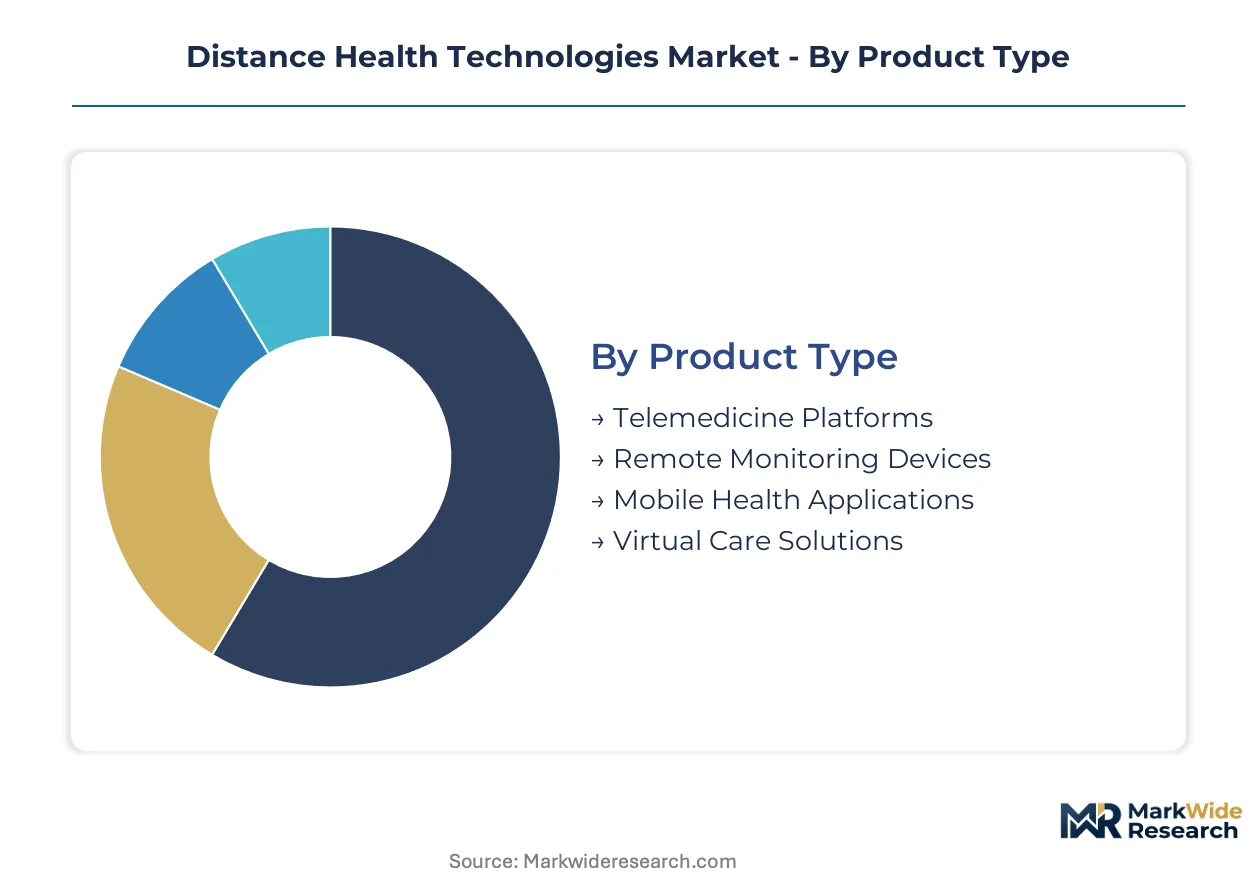
Distance health technologies fragment across four distinct dimensions that determine procurement pathways and margin structures. Product type and delivery model govern enterprise sales cycles, while technology and end-user orientation shape R&D allocation and regulatory strategy.
Product Type:
Enterprise procurement channels favor hardware-software bundles for chronic disease management, while direct-to-consumer channels drive mobile application adoption. Health system value analysis committees now separate device acquisition from platform subscriptions.
- Remote Monitoring Devices:Connected biosensors and wearable physiological trackers transmit continuous data streams for heart failure and COPD management. Hospital networks in Texas and Florida deploy these through centralized digital transformation offices rather than cardiology service lines.
- Telemedicine Platforms:Synchronous video consultation infrastructure with embedded EHR integration and scheduling workflows. Federally qualified health centers in rural counties adopt these for specialist access where geographic barriers limit in-person care.
- Mobile Health Applications:Patient-facing software for medication adherence and symptom tracking running on consumer smartphones.
- Virtual Care Solutions:Comprehensive service bundles combining remote monitoring, asynchronous messaging, and care coordination for integrated delivery networks.
Remote Monitoring Devices dominate installed base. AI Analytics is where expansion concentrates.
Technology:
Cloud-native architectures reduce capital requirements for mid-tier vendors, while edge computing investments concentrate among device manufacturers seeking real-time triage capabilities.
- AI Analytics:FDA-cleared predictive algorithms for cardiac event detection and glucose trend forecasting. Developers front-load clinical validation studies as classification uncertainty around de novo pathways extends regulatory timelines.
- IoT Connectivity:Low-power wide-area networks and Bluetooth protocols enabling seamless data transmission from home-based sensors to cloud platforms. Taiwan-based foundry constraints create lead time volatility for chipset procurement.
- Cloud Computing:Scalable infrastructure for data storage, processing, and API-based EHR integration.
- Blockchain Security:Distributed ledger applications for consent management and audit trails in multi-party data exchanges.
Cloud Computing anchors current deployments. AI Analytics is climbing the fastest as predictive tools gain regulatory acceptance.
End User:
Reimbursement policy divergence creates distinct purchasing behaviors across user categories, with Medicare-dependent providers prioritizing RTM-eligible platforms over cash-pay alternatives.
- Healthcare Providers:Hospital systems and physician practices purchasing enterprise licenses for population health management. CMS reimbursement code valuations directly determine willingness to adopt remote monitoring platforms.
- Patients:Direct consumers selecting applications and devices for personal chronic disease tracking. Factory-calibrated continuous glucose monitors displace point-of-care testing infrastructure among diabetes patients.
- Insurance Companies:Payers contracting for telemedicine networks to reduce emergency department utilization.
- Pharmaceutical Firms:Life science companies deploying digital therapeutics and remote trial monitoring for decentralized clinical studies.
Healthcare Providers dominate installed base. Pharmaceutical Firms represent emerging demand concentration.
Delivery Model:
Pricing structures align with customer scale and capital availability, with subscription models capturing enterprise commitment and variable structures reducing barriers for independent practices.
- Subscription-Based:Annual or multi-year contracts with predictable recurring revenue for platform vendors. Health system IT governance committees control analytics platform selection separately from hardware negotiations.
- Pay-Per-Use:Transactional pricing tied to consultation minutes or monitoring episodes. Smaller provider networks in underserved counties favor this structure for cost alignment with variable patient volumes.
- Freemium:Basic functionality at no cost with premium features unlocked through upgrade.
- On-Premise:Licensed software deployed within customer data centers for security-sensitive environments.
Subscription-Based dominates enterprise procurement. Pay-Per-Use is gaining share fastest among independent practice networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor technology-exporting economies while import-dependent markets accelerate domestic platform development to reduce healthcare infrastructure gaps.
United States
Medicare reimbursement expansion for remote therapeutic monitoring codes drives hospital network procurement at scale. FDA digital health pre-certification programs compress regulatory timelines for AI-enabled diagnostic software. The Texas Medical Center and Florida hospital systems concentrate deployment authority within centralized digital transformation offices.
Germany
Industrial automation expertise translates into connected device manufacturing for European hospital networks. EU Medical Device Regulation (MDR) compliance requirements elevate quality system investments for ISO 13485 certification. The Baden-Württemberg medical technology cluster anchors production of FDA-cleared biosensor platforms.
China
Domestic chronic disease burden accelerates NMPA-cleared remote monitoring adoption across tier-one hospital networks. National Health Commission guidelines on internet-based medical services enable cross-provincial telemedicine licensing. The Yangtze River Delta biotechnology corridor concentrates cloud-native RPM platform development.
Japan
Aging demographics compress adoption cycles for home-based physiological monitoring among prefectural health systems. PMDA streamlined review pathways for software-as-medical-device products reduce time-to-market for algorithmic triage tools. The Kansai medical device manufacturing belt sustains production of ISO 13485-compliant connected sensors.
India
Federally qualified health centers in underserved districts present deployment white space for asynchronous telemedicine platforms. CDSCO medical device rules for software-based products create classification clarity for AI analytics vendors. The Karnataka health technology startup ecosystem concentrates telemedicine platform development for rural clinic networks.
Distance Health Technologies Market Competitive Environment
Listed leaders compete with private specialists across hardware-software integration tiers, producing a bifurcated structure where scale advantages concentrate in enterprise contract capture while agility advantages dominate niche therapeutic verticals. The vendor base organizes around three strategic archetypes: virtual care infrastructure operators, connected device manufacturers with deep regulatory clearance experience, and cloud-native analytics platforms. M&A activity concentrates on tuck-in acquisitions of FDA-cleared algorithm developers, while strategic partnerships between hardware vendors and health system IT departments reshape procurement committee influence.
Among North American-listed virtual care operators, Teladoc Health, Inc. occupies a position exemplifying enterprise contract scale with large health systems. European industrial conglomerates anchor the connected device tier, with Koninklijke Philips N.V. representing sustained technology leadership through accumulated FDA 510(k) clearance experience. Siemens Healthineers GmbH exemplifies the imaging-to-telemedicine extension archetype, competing by translating diagnostic analytics expertise into cloud-native workflow platforms.
| Leading Market Players |
|---|
| Teladoc Health, Inc. |
| Medtronic Plc |
| Koninklijke Philips N.V. |
| Siemens Healthineers GmbH |
| TytoCare Ltd. |
| OMRON Healthcare, Inc. |
| Rudolf Riester GmbH |
| Health Recovery Solutions |
| Masimo Corporation |
| Others |
Value Chain & Pricing Dynamics
Foundry-scale economies in Taiwan-based semiconductor manufacturing concentrate biosensor chipset supply and establish price floors for connected monitoring hardware. This capacity concentration cascades through device assembly tiers, compressing margins for mid-tier vendors while anchoring premium pricing for FDA-cleared platforms with captive supply arrangements.
Pricing Analysis
Hospital system procurement committees anchor subscription-based pricing for enterprise RPM platforms, separating hardware acquisition from analytics software negotiations. Price differentiation rests on FDA 510(k) clearance tier and ISO 13485 certification status, with cleared platforms commanding premium positioning over wellness-grade alternatives. Pricing pressure stems from Medicare reimbursement code compression as CMS recalibrates RTM valuations. Independent cardiology practices exhibit highest price sensitivity, while multi-hospital systems in Texas and Florida prioritize interoperability over unit cost.
Supply Chain Analysis
Strategic stockpiling of biosensor chipsets has replaced just-in-time preferences as Taiwan foundry capacity constraints extend lead time volatility for device manufacturers. Component sourcing concentrates in Taiwan, South Korea, and China for MEMS sensors and low-power wireless modules. Raw material dependencies include silicon wafers, lithium-ion cells, and medical-grade polymers. Single-source vulnerability around Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through health system GPO contracts and direct vendor relationships with hospital IT governance committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medicare reimbursement expansion for remote therapeutic monitoring codes is compressing adoption cycles and creating high-growth disruption for platforms with regulatory clearance. This inflection rewards vendors with pre-established FDA 510(k) portfolios and punishes late entrants facing extended validation timelines.
For Market Incumbents: Consolidate algorithm development capabilities through tuck-in acquisitions of FDA-cleared cardiac event detection specialists. Deepen vertical integration into biosensor manufacturing to offset Taiwan foundry concentration risk. Lock hospital system procurement committees into multi-year enterprise subscriptions before CMS reimbursement recalibration. For New Entrants and Emerging Players: Asynchronous telemedicine deployment gaps in rural Federally qualified health centers present the most penetrable white space. Target behavioral health integration where RPM convergence with digital therapeutics remains underdeveloped. Lead with pay-per-use pricing to align with independent practice variable cost structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native RPM platforms with embedded AI analytics and established hospital system contracts. Five-to-ten year viability favors vendors with de novo FDA pathway experience over 510(k) predicate dependence. Watch FDA classification determinations for AI-enabled diagnostic software as the primary inflection signal for capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market access for connected monitoring devices in cardiology and pulmonology practices. |
| Hospital System Partnership | Secures enterprise procurement through centralized digital transformation offices in multi-hospital networks. |
| Software Companion Development | Enables algorithmic triage capabilities that compress diagnostic chains and capture analytics revenue. |
| CE Marking Pathway | Opens European hospital network procurement governed by EU MDR compliance requirements. |
| Reimbursement Strategy | Aligns platform design with CMS remote therapeutic monitoring code valuations and state parity laws. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) databases, CMS Medicare reimbursement filings, and hospital GPO contract records. Interviews with biomedical engineers, hospital purchasing committee members, RPM platform executives, and GPO contracts managers inform demand-side validation. Top-down market sizing triangulates against bottom-up installed base estimates across remote monitoring device and telemedicine platform segments.
Segmentation dimensions modeled include product type, technology tier, end-user category, and delivery model across the projection horizon. CAGRs derive from regression analysis of historical adoption curves weighted by reimbursement policy inflections. Forecast inputs incorporate FDA pre-certification program expansion rates and Medicare RTM code utilization trajectories.
Forecasts assume regulatory continuity in FDA digital health guidance and CMS reimbursement frameworks; material policy shifts would require re-modeling. Revision becomes warranted when FDA classification determinations for AI-enabled diagnostic software cross thresholds that extend capital lock-up periods.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
Global Digital Medicines Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Connected Healthcare Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Healthcare Digital Experience Platform Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Mobile Health (Mhealth) Market