
 Behavioral Mental Health Care Software Market | 2026-2036
Behavioral Mental Health Care Software Market Size, Share, and Industry Trends Forecast 2026-2036
Behavioral Mental Health Care Software Market Intelligence
The 21st Century Cures Act is consolidating demand around interoperable behavioral health platforms that exchange data across care settings. Epic Systems Corporation leverages its dominant hospital network footprint to anchor enterprise-wide behavioral health deployments. Netsmart Technologies, Inc. specializes in post-acute and human services workflows, competing for state-level Medicaid contracts. Qualifacts Systems Inc. sustains its position through cloud-native architecture tailored to mid-market community providers.
Behavioral mental health care software comprises clinical, administrative, and analytics modules designed to manage patient intake, treatment planning, medication tracking, and outcomes measurement across psychiatric and substance-use care settings. Cloud-based deployment dominates new procurement cycles, while integrated suites that unify patient management with billing and reporting functionality capture the deepest workflow penetration. Standalone scheduling tools retain relevance only in small private practices with limited IT resources.
FDA oversight of clinical decision support modules, HIPAA security rule enforcement by the Office for Civil Rights, and state-level Medicaid agency certification requirements collectively shape product development roadmaps and market access conditions. The CMS interoperability mandates for payer-to-payer data exchange will force legacy on-premise vendors toward API-first architectures. Stakeholders must monitor how federal parity enforcement shifts procurement criteria toward outcomes-reporting capabilities.
Market Dynamics
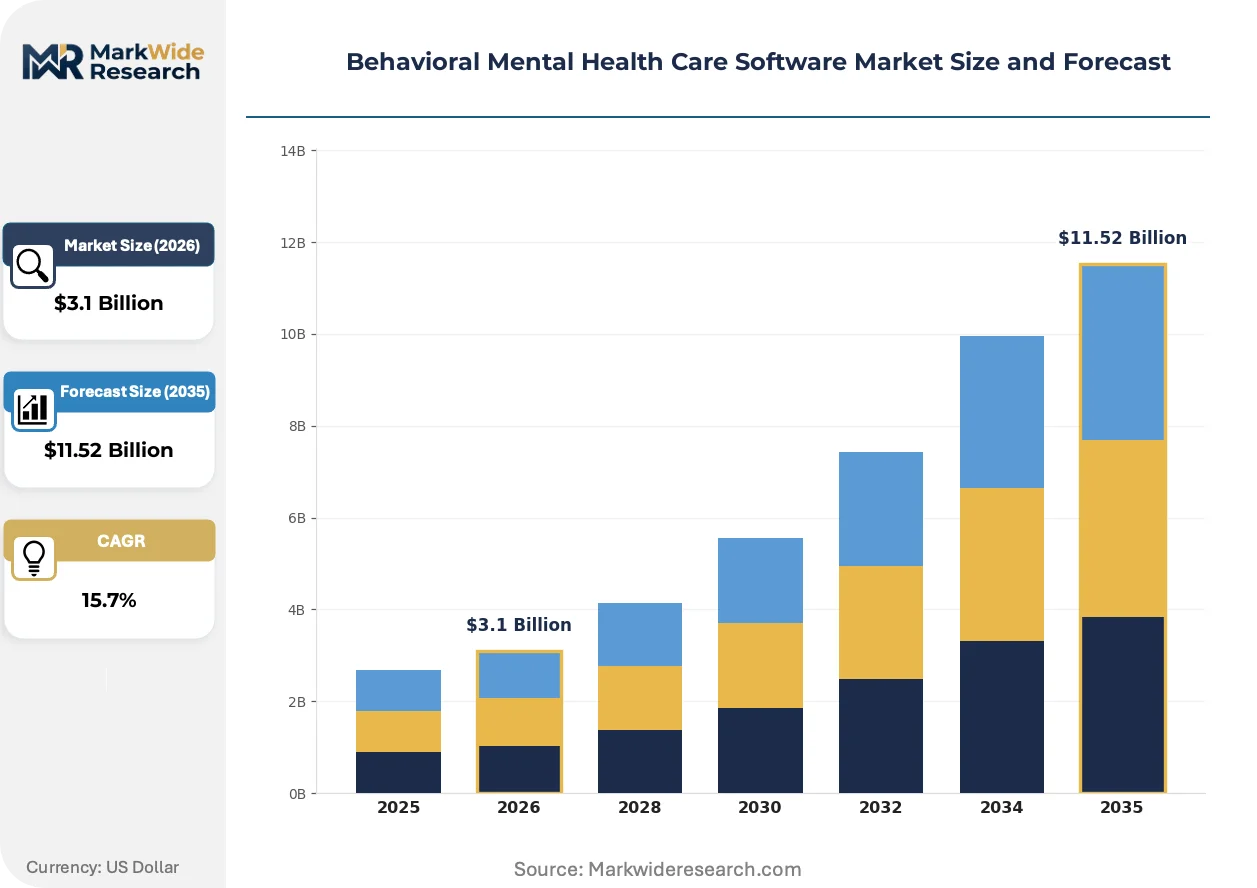
The 21st Century Cures Act and CMS interoperability mandates are compressing procurement cycles around API-first platforms, forcing legacy on-premise vendors to rearchitect or exit while cloud-native specialists capture Medicaid and community health center contracts.
Growth Catalysts
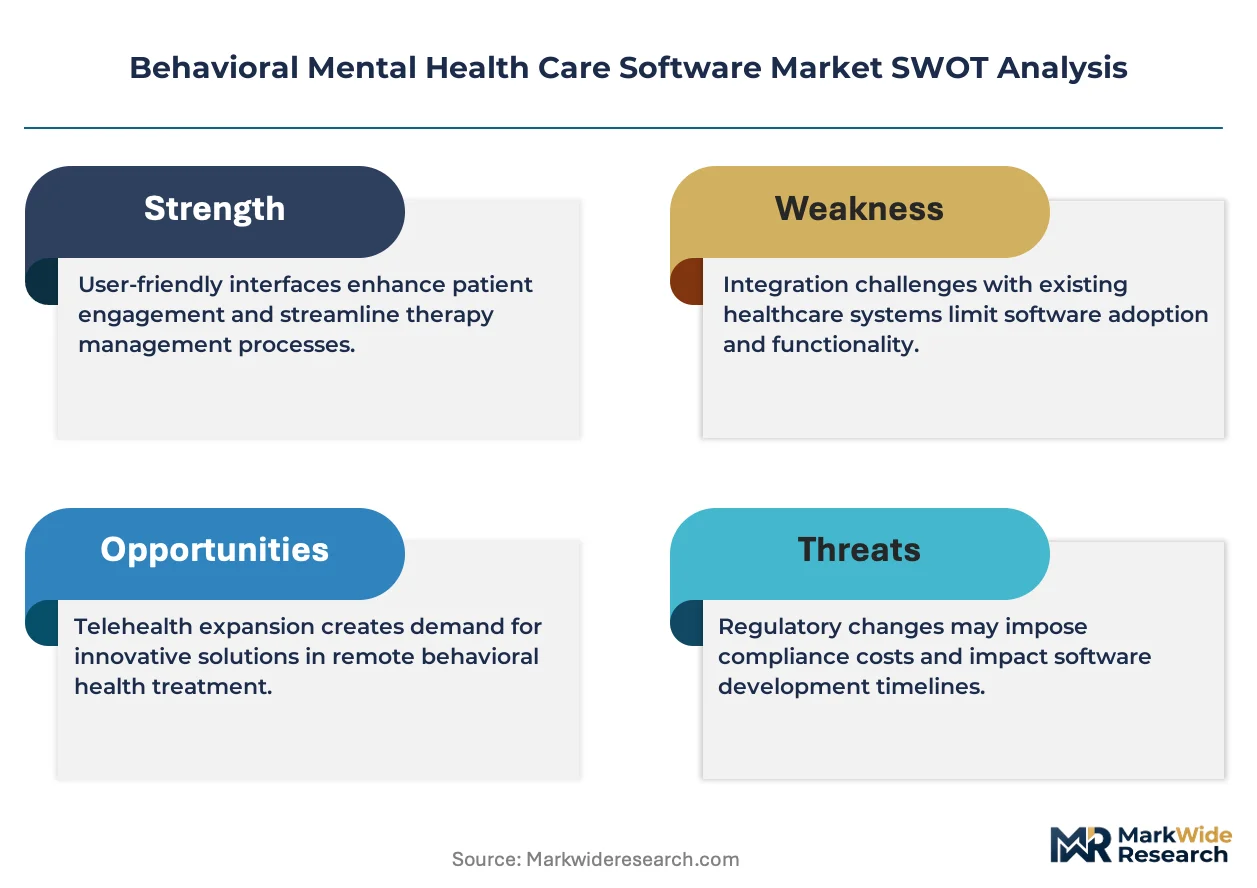
- Federal Parity Enforcement:The Mental Health Parity and Addiction Equity Act intensification is mandating behavioral health coverage equivalence, compelling payers to invest in outcomes-tracking software that demonstrates compliance across commercial and Medicaid plans.
- Community Health Center Digital Expansion:Federally Qualified Health Centers are receiving capital infusions for integrated care models, driving demand for unified EHR-behavioral health platforms that bridge primary and psychiatric workflows.
- Machine Learning Risk Stratification:Predictive algorithms embedded in clinical decision support modules are flagging suicide risk and substance-use relapse patterns, accelerating adoption among crisis intervention and inpatient psychiatric units.
Market Restraints
- HIPAA Security Rule Compliance Costs:OCR enforcement actions against behavioral health providers for encryption and access-control failures are elevating vendor liability premiums and implementation timelines.
- State Medicaid Certification Fragmentation:Each state maintains distinct technical and clinical requirements for behavioral health module approval, forcing vendors to maintain fifty-plus certification tracks.
- Legacy Data Migration Complexity:Decades of unstructured clinical notes and medication histories in on-premise systems resist standardized extraction, delaying cloud transitions for mid-market community providers.
Strategic Opportunities
- Substance-Use Disorder Integration:The opioid settlement fund disbursements are creating dedicated procurement pools for medication-assisted treatment platforms that coordinate prescribing, counseling, and peer support workflows.
- School-Based Mental Health Mandates:State legislation requiring K-12 behavioral health screening is opening a channel previously served by paper-based tools, favoring tablet-native assessment platforms with parent portal integration.
- Telehealth-First Architecture:CMS permanent reimbursement parity for virtual behavioral health sessions is enabling purpose-built platforms that optimize for asynchronous messaging and video-based group therapy.
Industry Challenges
- Clinical Informatics Talent Scarcity:Behavioral health organizations lack staff capable of configuring FHIR-based data exchanges and interpreting predictive model outputs, creating implementation bottlenecks.
- Interoperability Testing Burden:Each health system demands custom API validation against its specific EHR configuration, consuming vendor engineering resources without standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Behavioral Mental Health Care Software Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $11.52 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise, Cloud-Based, Integrated, Standalone End User: Clinics, Hospitals, Private Practices, Telehealth Providers Functionality: Patient Management, Billing, Reporting, Scheduling Deployment: Public Cloud, Private Cloud, Hybrid, Local Server |
| Companies Covered | Oracle (Cerner Corporation), Epic Systems Corporation, Netsmart Technologies, Inc., Welligent, Inc., Valant Medical Solutions Inc., Qualifacts Systems Inc., Core Solutions, Inc., Meditab Software, Inc., Credible Behavioral Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Behavioral Mental Health Care Software Market Strategic Shifts & Innovations
Natural language processing and ambient documentation tools are compressing clinician administrative burden, while regulatory pressure on algorithmic transparency is reshaping how predictive modules get deployed across care settings.
Natural language processing engines trained on psychiatric encounter transcripts are automating progress note generation and diagnostic code extraction. Community mental health centers and large group practices are deploying these tools at scale to reclaim two to three hours of daily documentation time per clinician. This compression of administrative overhead is automating the traditional medical scribe function and redirecting clinical capacity toward direct patient engagement.
The FDA's emerging guidance on clinical decision support software is tightening oversight of predictive algorithms that flag suicide risk or recommend medication adjustments. Behavioral health platform vendors must now document training data provenance and model performance across demographic subgroups. Enterprise procurement committees are responding by requiring algorithmic impact assessments before contract execution.
Consolidated billing and outcomes-reporting requirements are compressing vendor selection cycles around integrated suite providers. State Medicaid agencies and large employer plans are replacing point-solution contracts with single-vendor accountability for both clinical functionality and value-based performance metrics. This preference consolidation is most visible in California and New York, where regional health plan mergers have concentrated purchasing power among three to five dominant payers.
Behavioral Mental Health Care Software Market Segmentation
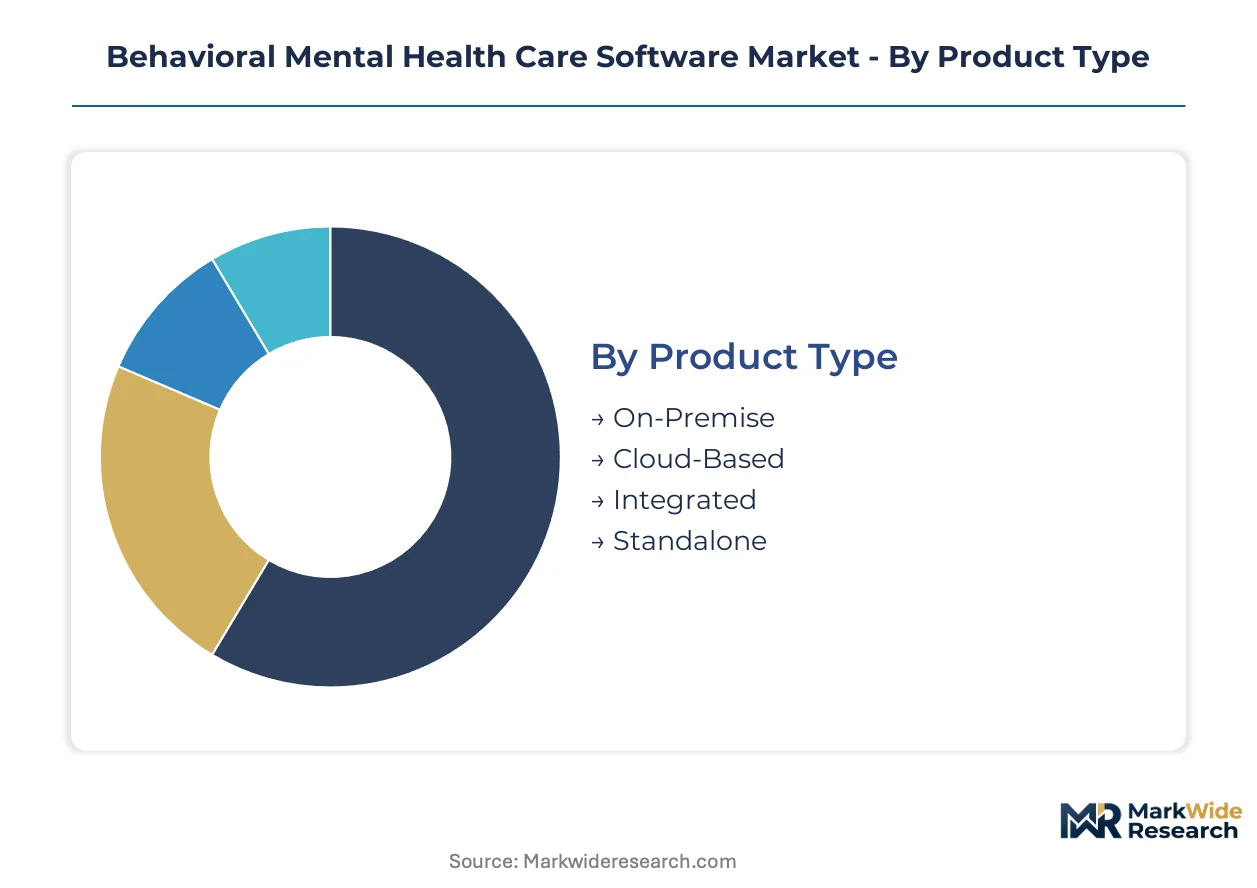
Behavioral mental health care software procurement cycles vary sharply by infrastructure maturity, with legacy on-premise installations driving replacement demand while cloud-native platforms capture new facility openings. Understanding segment boundaries clarifies where vendors must architect for migration versus greenfield deployment.
Product Type:
Upgrade momentum concentrates in installations reaching end-of-life, where technical debt and interoperability mandates force architectural decisions.
- On-Premise:Legacy server installations running within facility data centers retain dominance at state psychiatric hospitals and correctional health systems with stringent air-gapping requirements. HIPAA Security Rule enforcement and CMS interoperability deadlines are accelerating replacement timelines, with most organizations targeting hybrid or full cloud transitions rather than refreshes.
- Cloud-Based:Multi-tenant SaaS architectures with automatic updates and API-first integration dominate new procurement at Federally Qualified Health Centers and community mental health organizations. California and Texas Medicaid agencies now mandate cloud certification for new vendor approvals, consolidating demand around platforms with HITRUST and SOC 2 Type II attestations.
- Integrated:Unified suites combining clinical, billing, and outcomes modules capture enterprise hospital deployments seeking single-vendor accountability for value-based contracts.
- Standalone:Point solutions for scheduling or medication management persist only in small private practices with limited IT staffing and no interoperability requirements.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to Integrated.
End User:
Customer type determines pricing tolerance, implementation complexity, and the depth of regulatory compliance required in platform configuration.
- Clinics:Outpatient mental health and substance-use treatment centers require workflow optimization for high patient volumes with rotating clinician schedules. New York and Massachusetts clinics are prioritizing platforms with embedded quality reporting for state Medicaid incentive programs.
- Hospitals:Inpatient psychiatric units and emergency departments demand real-time bed management, involuntary hold documentation, and 24/7 crisis intake protocols. Academic medical centers in Illinois and Pennsylvania are driving adoption of predictive risk stratification modules.
- Private Practices:Solo and small-group behavioral health providers prioritize low-touch implementation and per-provider pricing models over advanced interoperability.
- Telehealth Providers:Purpose-built virtual care platforms optimize for asynchronous messaging, video group therapy, and cross-state licensure compliance.
Revenue concentration sits with Hospitals; Telehealth Providers are climbing the fastest.
Functionality:
Module selection follows organizational maturity, with basic administrative tools preceding clinical decision support and outcomes analytics.
- Patient Management:Core electronic health record functionality encompassing intake assessments, treatment plans, progress notes, and medication tracking forms the non-negotiable foundation. Florida community health centers are upgrading from paper-based systems to cloud-native patient management as a condition of federal capital grants.
- Billing:Revenue cycle management with behavioral health-specific coding, prior authorization automation, and denial management addresses the complexity of parity compliance. Ohio and Georgia Medicaid programs now require real-time eligibility verification as a certification prerequisite.
- Reporting:Outcomes measurement and quality dashboards satisfy federal parity documentation requirements and value-based contract terms.
- Scheduling:Calendar optimization with waitlist management and automated reminders reduces no-show rates in high-volume outpatient settings.
Procurement frequency runs highest for Patient Management; steepest expansion trajectory belongs to Reporting.
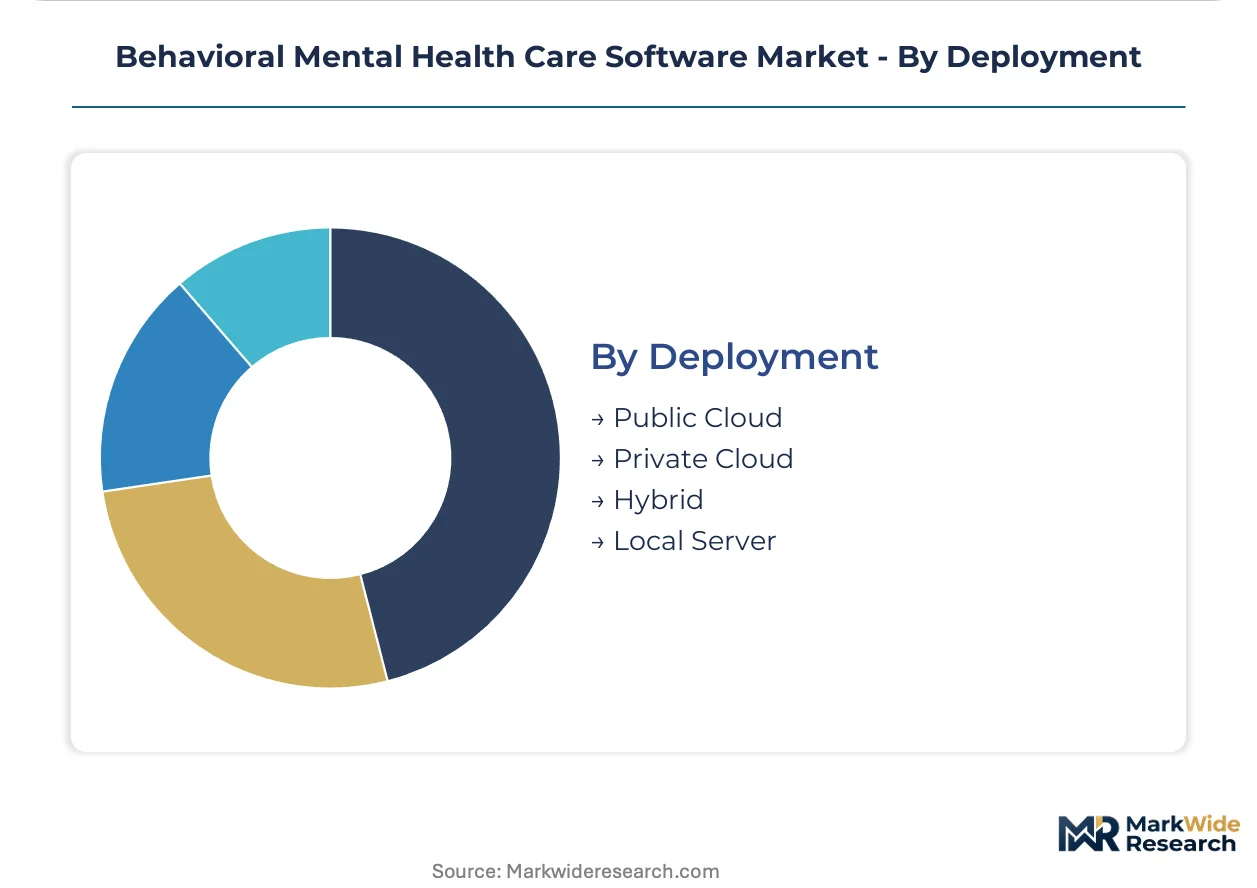
Deployment:
Infrastructure topology decisions reflect data sovereignty requirements, existing capital investments, and workforce technical capacity.
- Public Cloud:Shared infrastructure operated by hyperscale providers delivers cost efficiency and elastic scaling for variable patient volumes. Arizona and Colorado behavioral health startups are defaulting to public cloud for speed-to-market and minimal capital expenditure.
- Private Cloud:Dedicated single-tenant environments hosted by specialized healthcare cloud providers address enhanced security requirements without full on-premise burden. Virginia and Maryland facilities serving federal employee health plans favor private cloud for FedRAMP-aligned controls.
- Hybrid:Split architectures maintain sensitive patient data on local servers while leveraging cloud analytics and backup.
- Local Server:Fully on-premise installations persist where network connectivity is unreliable or institutional policy mandates physical data control.
Contract volume centers on Public Cloud; Hybrid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of behavioral health software procurement, while development and headquarters activity clusters in technology corridors. European markets trail in adoption velocity due to fragmented national reimbursement systems.
United States
Federally Qualified Health Centers in California and Texas drive cloud-native platform demand through federal capital grants. The 21st Century Cures Act mandates interoperability standards that compress vendor selection cycles. Massachusetts and New York health systems anchor enterprise deployments for integrated care models.
United Kingdom
NHS England's Long Term Plan expands talking therapies and digital mental health services, creating procurement pools for outcome-tracking platforms. The UK Health Security Agency enforces cybersecurity standards for patient data processing. London-based health tech clusters concentrate startup activity for CBT and crisis intervention applications.
Germany
Statutory health insurers reimburse digital health applications under the Digital Care Act, opening behavioral health software to 73 million insured lives. The Federal Institute for Drugs and Medical Devices regulates clinical decision support modules as medical devices. Berlin and Munich health tech ecosystems host scale-ups specializing in depression and anxiety management platforms.
Canada
Provincial health authorities in Ontario and British Columbia fund integrated mental health and substance-use programs, driving demand for unified EHR-behavioral health systems. Health Canada oversees medical device classification for diagnostic algorithms. Toronto's MaRS Discovery District anchors startup concentration for indigenous and youth-focused mental health tools.
Australia
The Medicare Benefits Schedule funds telehealth psychiatric consultations permanently, accelerating purpose-built virtual care platform adoption. The Therapeutic Goods Administration regulates software as medical devices for diagnostic and therapeutic claims. Melbourne and Sydney digital health hubs concentrate vendors serving rural and remote access initiatives.
Behavioral Mental Health Care Software Market Key Industry Players
The competitive structure tilts toward enterprise EHR incumbents with hospital network anchoring power. Market concentration remains moderate, with specialized behavioral health vendors competing for Medicaid and community health center contracts against generalist platforms adding psychiatric modules. Two strategic archetypes dominate: hospital-system-anchored enterprise suites and cloud-native specialists targeting mid-market community providers. Competitive moves center on API-first architecture investments and state-level certification acquisitions.
Among the enterprise-tier anchors, Epic Systems Corporation and Oracle (Cerner Corporation) occupy positions leveraging existing hospital network relationships to extend into behavioral health workflows. Netsmart Technologies, Inc. exemplifies the specialization archetype, focusing on post-acute and human services segments where state Medicaid procurement processes favor dedicated vendors over generalists.
| Leading Market Players |
|---|
| Oracle (Cerner Corporation) |
| Epic Systems Corporation |
| Netsmart Technologies, Inc. |
| Welligent, Inc. |
| Valant Medical Solutions Inc. |
| Qualifacts Systems Inc. |
| Core Solutions, Inc. |
| Meditab Software, Inc. |
| Credible Behavioral Health |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure cost indices from hyperscale providers cascade through behavioral health software supply chains, compressing margins for vendors while creating pricing stratification between API-first platforms and legacy on-premise installations. This cost pressure feeds into buyer procurement cycles, with Federally Qualified Health Centers and state Medicaid agencies demanding outcome-linked pricing models that tie vendor compensation to measurable clinical results.
Pricing Analysis
Value-based pricing anchored to patient outcome metrics and care coordination throughput dominates enterprise contracts, with Massachusetts and California health systems leading adoption. Three-tier pricing structure across premium, standard, and economy levels separates integrated suite providers from standalone modules and basic scheduling tools. Cost compression in the mid-market tier is intensifying because cloud-native entrants undercut legacy vendors on implementation timelines. Small private practices exhibit highest price sensitivity, while academic medical centers prioritize algorithmic capability over per-seat cost.
Supply Chain Analysis
API development talent rests on concentrated pools in California, Massachusetts, and Texas technology corridors, creating recruitment bottlenecks for vendors outside these clusters. Cloud compute capacity, cybersecurity certification infrastructure, and FHIR interoperability testing environments constitute critical input dependencies. Single-source vulnerability runs through hyperscale cloud providers, where service disruptions propagate across multi-tenant SaaS deployments. Distribution runs through direct enterprise sales teams for hospital systems and value-added resellers serving community health center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first architectures are displacing legacy on-premise installations across behavioral health software procurement, with the 21st Century Cures Act interoperability mandates accelerating this technology transition.
For Market Incumbents: Deploy certification acquisition as the primary lever to defend Medicaid contract positions against cloud-native specialists. Pursue backward integration into FHIR testing infrastructure to reduce interoperability validation costs. Counter Epic Systems Corporation and Oracle hospital network anchoring by deepening state-level agency relationships. For New Entrants and Emerging Players: Community health center procurement officers represent the most accessible channel partner type for bypassing entrenched vendor relationships. Target Federally Qualified Health Center digital expansion grants in Texas and Florida as the most penetrable segment. Lead with tablet-native assessment platforms featuring parent portal integration to capture school-based mental health mandates. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native mid-market specialists with existing HITRUST certification in California and New York. Five-to-ten year viability hinges on algorithmic transparency compliance and predictive model performance documentation. Watch FDA clinical decision support guidance enforcement intensity as the primary inflection indicator for platform valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Migration | CMS interoperability mandates force legacy vendors toward rearchitecture or market exit. |
| State Medicaid Certification Acquisition | California and Texas agencies now mandate cloud certification for vendor approvals. |
| Predictive Algorithm Transparency Investment | FDA guidance requires documented training data provenance across demographic subgroups. |
| School-Based Mental Health Channel Development | K-12 screening mandates in multiple states open previously paper-based procurement pools. |
| Substance-Use Disorder Workflow Integration | Opioid settlement fund disbursements create dedicated medication-assisted treatment procurement. |
Research Approach
Document review covered FDA clinical decision support guidance, CMS interoperability rulemaking, and state Medicaid certification requirements, complemented by interviews with behavioral health software product executives, hospital CIOs, community health center IT directors, and state Medicaid agency procurement officers. Secondary sources included SEC 10-K filings, HITRUST certification databases, and GPO contract repositories. Bottom-up deployment estimates and top-down market sizing underwent cross-validation.
Revenue and installation base outputs reflect segmented modeling across deployment topology, organization size tier, functionality module depth, and regional adoption pattern throughout the forecast period. CAGRs derived from regression analysis against historical procurement velocity and policy implementation timelines. Forecast inputs incorporated cloud migration cost curves and federal parity enforcement intensity indices.
Caveats apply where FDA algorithmic oversight expansion or state Medicaid certification requirement changes could materially shift the outlook. Forecasts reflect assumptions about interoperability mandate compliance deadlines and cloud infrastructure cost trajectories. A small set of named triggers—OCR enforcement action frequency, CMS reimbursement rule updates, and hyperscale cloud pricing adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Surgical Planning Software Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Amblyopia Treatment Softwares Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Digital Health Market
Digital Health Solutions
Heart Failure Software Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
Global Mhealth Solutions Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market