
 Heart Failure Software Market | 2026-2036
Heart Failure Software Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Failure Software Market Analysis
A shortage of specialized cardiac data scientists is unwinding deployment timelines for enterprise heart failure platforms. Medtronic leverages its implantable device ecosystem to anchor recurring software revenue streams. Philips Healthcare competes through deep integration with acute care workflows and imaging archives. Abbott specializes in algorithm refinement for hemodynamic monitoring, sustaining clinical validation advantages.
Heart failure software encompasses digital platforms that aggregate, analyze, and visualize patient physiological data to support clinical decision-making in chronic cardiac care. These systems typically process streaming inputs from implantable sensors, wearable electrocardiograms, and patient-reported symptom scores through cloud-native architectures with sub-minute alerting thresholds. Telehealth Solutions and Remote Monitoring Tools occupy the largest revenue pools as health systems prioritize post-acute readmission reduction. AI-Driven Solutions represent the fastest-expanding technology segment, though Cloud-Based Applications still dominate total deployment volume due to lower infrastructure barriers.
FDA digital health premarket pathways and HIPAA interoperability mandates shape product design priorities for US market entrants, while EMA's Medical Device Regulation extends clinical evidence requirements across European submissions. The EU AI Act introduces risk-classification obligations for diagnostic algorithms that will force restructuring of quality management systems. Stakeholders must monitor how reimbursement coding for remote therapeutic monitoring evolves against tightening cybersecurity standards for connected cardiac devices.
Market Dynamics
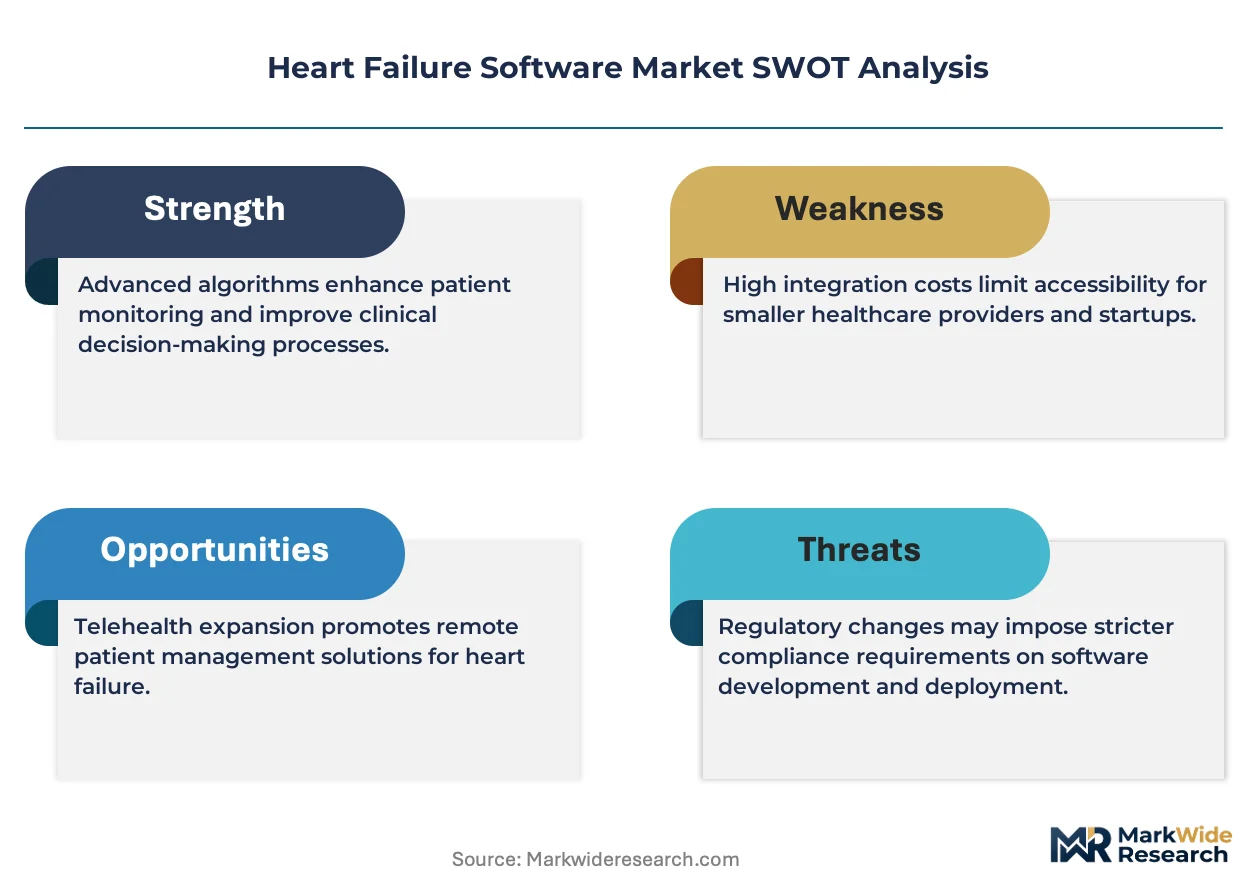
FDA's evolving digital health premarket guidance is compressing algorithm validation timelines while forcing restructuring of quality management systems across connected cardiac platforms. Hospital procurement committees now mandate cloud-native architectures with sub-minute alerting thresholds as standard contract terms.
Growth Catalysts
- Integrated care reimbursement:Germany's statutory health insurers now fully reimburse connected heart failure management programs, accelerating hospital system procurement of remote monitoring suites.
- HIPAA interoperability mandates:The US Department of Health and Human Services requires standardized data exchange protocols, forcing platform vendors to prioritize API-first architectures that accelerate enterprise deployment.
- Implantable sensor miniaturization:Advances in battery-efficient hemodynamic sensing enable continuous pulmonary artery pressure monitoring without patient action, expanding addressable chronic cohorts.
Market Restraints
- Specialized talent scarcity:Cardiac data scientists with both clinical domain knowledge and machine learning engineering skills command premium compensation that extends platform development timelines by 8-14 months.
- EMA MDR clinical evidence requirements:The European Medical Device Regulation demands prospective validation studies for algorithm-driven diagnostic outputs, inflating regulatory submission costs and delaying EU market entry.
- Legacy EHR integration friction:Proprietary data formats in entrenched hospital information systems force expensive custom middleware development for each enterprise deployment.
Strategic Opportunities
- Post-acute readmission reduction:Medicare's Hospital Readmissions Reduction Program penalties create budget authority for remote therapeutic monitoring investments in US health systems.
- EU AI Act risk-classification:Early compliance with high-risk system obligations positions vendors for preferential contracting with European integrated care networks seeking liability protection.
- Wearable ECG convergence:Integration of consumer-grade atrial fibrillation detection with clinical heart failure platforms opens ambulatory monitoring channels beyond traditional implantable device candidates.
Industry Challenges
- Algorithm drift management:Continuous learning systems require governance frameworks that satisfy FDA predetermined change control plans while maintaining clinical validation integrity across software updates.
- Cybersecurity certification complexity:State-level hospital breach notification laws layer atop HIPAA security rules, forcing redundant compliance audits for multi-state health system deployments.
- Interoperability testing burden:Each new EHR integration requires validation against hundreds of data field mappings, consuming engineering resources that could accelerate feature development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Failure Software Market |
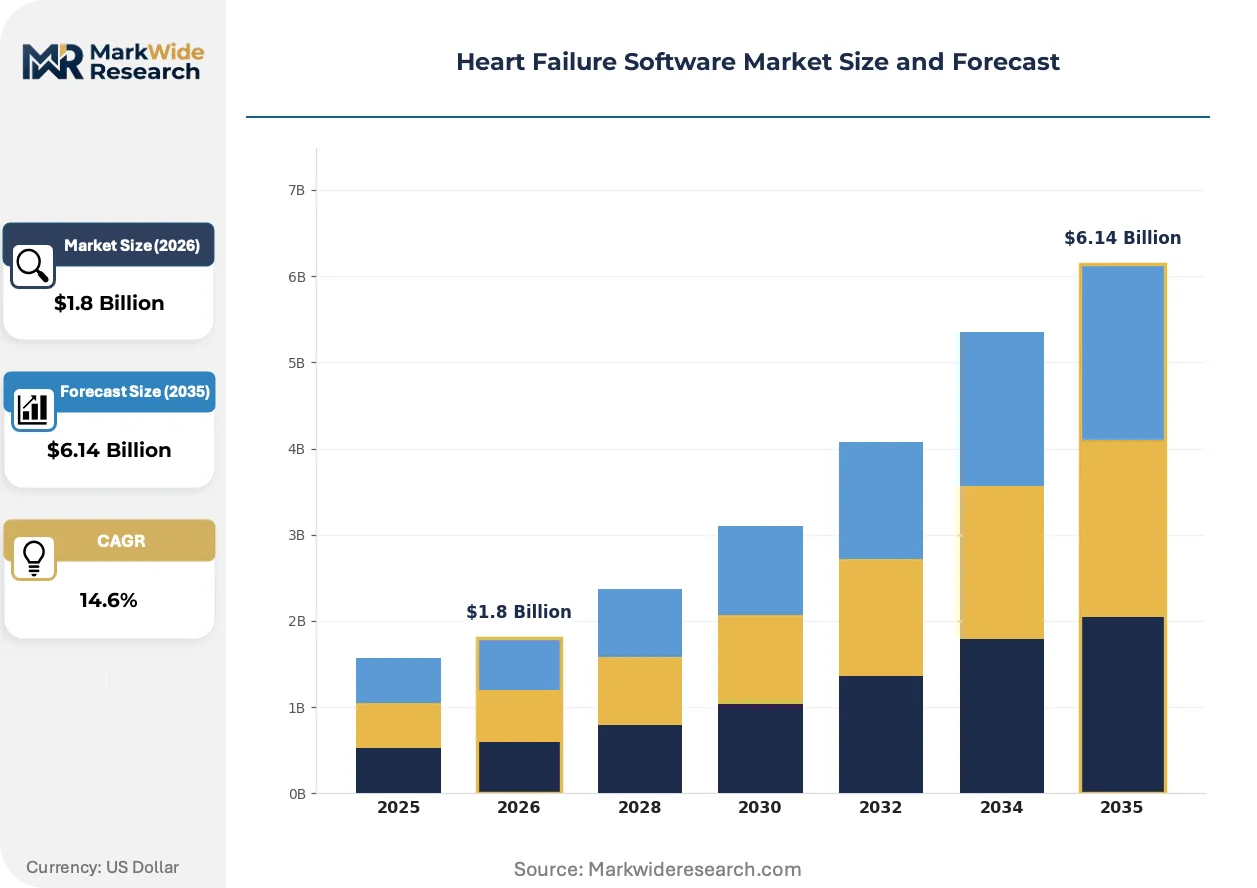
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telehealth Solutions, Mobile Applications, Data Analytics Platforms, Remote Monitoring Tools End User: Healthcare Providers, Payers, Patients, Research Institutions Technology: AI-Driven Solutions, Cloud-Based Applications, Wearable Devices, Mobile Health Technology Deployment: On-Premises, Cloud-Based, Hybrid Solutions, SaaS |
| Companies Covered | Medtronic, Philips Healthcare, GE HealthCare, Cerner Corporation, Abbott, Siemens Healthineers, Boston Scientific, CitiusTech Inc., Axis Clinical Software, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Failure Software Market Emerging Trajectories
Algorithmic decision support is fragmenting traditional clinical workflow hierarchies as autonomous monitoring systems assume triage functions previously reserved for specialist cardiologists. Three concurrent developments are compressing technology adoption cycles and reshaping vendor competitive requirements.
Edge computing architectures for implantable devices are fragmenting the historical cloud-centralization model in cardiac remote monitoring. Device manufacturers now process arrhythmia detection and hemodynamic alerts within the implant itself, reducing latency to under 30 seconds for critical events. Hospital systems in Germany and the Netherlands are prioritizing these distributed systems for their resilience against network outages.
The EU AI Act's high-risk system classification is forcing restructuring of quality management systems for diagnostic algorithms across European submissions. Manufacturers must now maintain post-market surveillance systems with automated adverse event detection and human oversight protocols. This regulatory friction most heavily affects cloud-native platforms seeking CE marking for predictive analytics modules.
Hospital procurement committees are consolidating vendor relationships around integrated platform ecosystems rather than point solutions. Acute care networks now demand unified dashboards combining implantable data, wearable inputs, and patient-reported outcomes within single procurement contracts. This concentration is most visible in US integrated delivery networks with Medicare Advantage risk contracts exceeding 50,000 covered lives.
Heart Failure Software Market Segmentation
Heart failure software vendors structure product portfolios around distinct technology architectures and customer workflows. Procurement patterns diverge sharply between acute care networks seeking enterprise integration and ambulatory providers prioritizing rapid deployment.
Product Type:
Telehealth Solutions and Remote Monitoring Tools concentrate demand in US hospital systems managing Medicare Advantage risk contracts. Mobile Applications and Data Analytics Platforms show stronger traction in European ambulatory settings with integrated care reimbursement.
- Telehealth Solutions:These platforms combine synchronous video consultation with asynchronous symptom triage for decompensating patients. US integrated delivery networks with Medicare Advantage contracts exceeding 50,000 lives prioritize these systems for readmission reduction.
- Remote Monitoring Tools:Systems processing streaming data from implantable hemodynamic sensors with sub-minute alerting thresholds. German statutory health insurers now fully reimburse connected heart failure management programs built on these platforms.
- Mobile Applications:Patient-facing tools for symptom logging and medication adherence tracking.
- Data Analytics Platforms:Enterprise systems aggregating multi-source cardiac data for population health management.
Remote Monitoring Tools command the established base. The steepest expansion runs through Telehealth Solutions.
End User:
Payers and Research Institutions operate on longer procurement cycles with heavier compliance documentation. Healthcare Providers and Patients represent the volume concentration, though their technical requirements diverge substantially.
- Healthcare Providers:Hospital systems and cardiology practices requiring EHR-integrated workflows with FDA-validated algorithm outputs. These customers dominate procurement of cloud-native architectures with sub-minute alerting thresholds.
- Payers:Insurance entities and Medicare Advantage plans funding remote therapeutic monitoring programs. Their purchasing decisions hinge on actuarial evidence of readmission reduction rather than clinical workflow optimization.
- Patients:Individual chronic heart failure cohorts accessing consumer-grade monitoring applications.
- Research Institutions:Academic medical centers conducting prospective validation studies for algorithm-driven diagnostic tools.
Healthcare Providers anchor current revenue concentration. Payers are climbing the fastest as risk-based contracting expands.
Technology:
Cloud-Based Applications dominate deployment volume due to lower infrastructure barriers. AI-Driven Solutions attract premium pricing despite requiring more extensive FDA premarket validation.
- AI-Driven Solutions:Machine learning systems for predictive decompensation detection and automated triage recommendations. The EU AI Act's high-risk system classification is forcing restructuring of quality management systems for these platforms across European submissions.
- Cloud-Based Applications:Web-native platforms with API-first architectures enabling rapid enterprise deployment. HIPAA interoperability mandates from the US Department of Health and Human Services accelerate procurement of these systems.
- Wearable Devices:Consumer and clinical-grade sensors for continuous physiologic monitoring.
- Mobile Health Technology:Cellular-connected devices enabling patient-generated data transmission.
Cloud-Based Applications represent the volume foundation. AI-Driven Solutions are gaining share fastest amid algorithmic decision support adoption.
Deployment:
On-Premises and Hybrid Solutions retain preference in health systems with restrictive data residency policies. SaaS and Cloud-Based models capture new deployments through faster implementation timelines.
- On-Premises:Locally hosted systems meeting stringent hospital cybersecurity requirements. These installations persist in US health systems with state-level breach notification laws layering atop HIPAA security rules.
- SaaS:Subscription-based delivery with vendor-managed infrastructure and automatic feature updates. Hospital procurement committees increasingly mandate these arrangements for reduced IT overhead.
- Cloud-Based:Third-party hosted deployments with elastic scaling for variable patient cohorts.
- Hybrid Solutions:Architectures combining local data processing with cloud analytics for sensitive cardiac information.
SaaS commands the established base. Cloud-Based deployment is expanding most quickly among new health system entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German health systems deploy heart failure software primarily for integrated care contract compliance, while US hospitals prioritize readmission reduction algorithms. Japanese providers emphasize implantable device integration with domestic sensor manufacturers. Demand patterns diverge sharply between reimbursement-driven European procurement and risk-contracting American integrated delivery networks.
United States
Medicare Advantage plans exceeding 50,000 covered lives drive procurement of cloud-native remote monitoring suites with sub-minute alerting thresholds. The FDA's evolving digital health premarket guidance compresses algorithm validation timelines for diagnostic tools. Hospital systems across the Southeast and Midwest accelerate enterprise deployments to capture Hospital Readmissions Reduction Program incentives.
Germany
Statutory health insurers now fully reimburse connected heart failure management programs, accelerating procurement of remote patient monitoring infrastructure. The EU AI Act's high-risk system classification forces restructuring of quality management systems for algorithm-driven platforms. Medical technology clusters in Bavaria and North Rhine-Westphalia anchor validation studies for CE-marked diagnostic modules.
Netherlands
Integrated care networks prioritize edge computing architectures for resilience against network outages in cardiac remote monitoring deployments. EMA Medical Device Regulation demands prospective validation studies for algorithm outputs, inflating regulatory submission costs. Healthcare technology procurement concentrates in the Randstad region around university medical centers with established remote therapeutic monitoring programs.
Japan
PMDA regulatory pathways shape design priorities for implantable sensor integration with domestic cardiac device manufacturers. METI industrial policy supports edge computing miniaturization for battery-efficient hemodynamic sensing. Medical device development clusters in the Kanto region around Tokyo drive convergence between consumer-grade wearables and clinical heart failure platforms.
United Kingdom
NHS integrated care boards allocate capital for telehealth solutions combining synchronous video consultation with asynchronous symptom triage. MHRA post-Brexit regulatory frameworks diverge from EU MDR requirements for clinical evidence submission. Digital health procurement concentrates in London and the Southeast around academic medical centers conducting prospective validation studies.
Heart Failure Software Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the heart failure software market. Medtronic and Philips Healthcare anchor the upper tier through implantable device ecosystems and acute care workflow integration respectively. Three archetypes define competitive positioning: implantable device manufacturers extending into software services, acute care technology vendors leveraging imaging archives, and pure-play algorithm specialists refining predictive analytics. Dominant competitive moves include strategic partnerships with health systems for enterprise deployment and portfolio diversification into wearable ECG convergence.
Among implantable device manufacturers with software extension strategies, Medtronic exemplifies the recurring revenue archetype through its cardiac rhythm management ecosystem. Philips Healthcare occupies a position within the acute care integration tier, leveraging deep workflow embedding with hospital imaging archives. Abbott represents the hemodynamic monitoring specialization vector, sustaining clinical validation advantages through algorithm refinement for pulmonary artery pressure sensing.
| Leading Market Players |
|---|
| Medtronic |
| Philips Healthcare |
| GE HealthCare |
| Cerner Corporation |
| Abbott |
| Siemens Healthineers |
| Boston Scientific |
| CitiusTech Inc. |
| Axis Clinical Software, Inc. |
| Others |
Supply Flow & Price Mechanics
Cloud-native platform scale economies in cardiac remote monitoring concentrate supply among vendors with established hospital system footprints, compressing price floors for mid-tier entrants while sustaining premium capture for FDA-validated algorithm suites. This concentration amplifies pricing power for integrated device-software ecosystems against point-solution competitors.
Pricing Analysis
Long-term SaaS subscription contracts dominate hospital procurement, with three-tier pricing structure across premium, standard, and economy levels differentiated by FDA validation tier and EHR integration depth. Price differentiation hinges on algorithm regulatory status and cloud architecture latency guarantees. Cost compression in standard tiers intensifies because HIPAA interoperability mandates force engineering investment into API-first architectures. Medicare Advantage plans with 50,000-plus covered lives show lowest price sensitivity; ambulatory cardiology practices exhibit highest.
Supply Chain Analysis
Inventory lead times for implantable hemodynamic sensors stretch 12-18 months due to battery-efficient miniaturization complexity, tethering downstream software vendors to device manufacturer release cycles. Component supply concentrates in the United States, Germany, and Japan for sensor hardware and cloud infrastructure. Raw material dependencies include medical-grade lithium cells, biocompatible polymers, and edge computing chipsets. Single-source vulnerability runs through domestic cardiac device manufacturers controlling proprietary data protocols. Distribution runs through hospital procurement committees and GPO contracts for enterprise deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heart failure software market represents high-growth disruption as FDA digital health premarket guidance compresses algorithm validation timelines and EU AI Act risk-classification restructures quality management obligations.
For Market Incumbents: Fortify implantable device ecosystem lock-in through exclusive cloud-native platform partnerships with integrated delivery networks. Deepen backward integration into edge computing chipsets to secure sensor miniaturization capacity. Prioritize FDA predetermined change control plans to outpace emerging algorithm specialists on update velocity.
For New Entrants and Emerging Players: Lead with wearable ECG convergence for ambulatory heart failure monitoring in European integrated care networks where statutory reimbursement lowers customer acquisition cost. Target Netherlands and Germany health systems seeking liability protection under EU AI Act high-risk system compliance. Pursue white-label algorithm licensing to acute care technology vendors lacking native predictive analytics.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play algorithm specialists with CE-marked diagnostic modules and established post-market surveillance infrastructure. Long-term viability rests on vendors navigating both FDA premarket pathways and EMA MDR clinical evidence requirements without capital depletion. Watch reimbursement coding evolution for remote therapeutic monitoring as the inflection signal for enterprise deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Accelerates market access for algorithm-driven diagnostic tools under evolving digital health guidance. |
| CE Marking Pathway | Enables European commercialization through EMA MDR compliance and EU AI Act risk-classification adherence. |
| Hospital System Partnership | Secures recurring SaaS revenue through integrated delivery network procurement consolidation. |
| Software Companion Development | Extends implantable device ecosystems into continuous monitoring with sub-minute alerting thresholds. |
| Reimbursement Strategy | Captures Medicare Advantage risk contract budgets and German statutory health insurer program funding. |
Methodological Framework
The analysis maps telehealth solutions, remote monitoring tools, AI-driven platforms, and cloud-native applications, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and cardiac data scientists. Primary interviews with these stakeholders combine with secondary validation against FDA 510(k) filings, EMA CE marking databases, CMS Medicare reimbursement schedules, and hospital procurement records. Bottom-up deployment volume estimates triangulate with top-down addressable chronic cohort sizing.
Consistency checks validated outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product architecture, end-user workflow, technology stack, and deployment model, with regional adoption patterns for US Medicare Advantage networks and German integrated care systems. CAGRs derive from algorithm penetration curves and reimbursement policy trajectory. Forecast inputs incorporate implantable sensor miniaturization roadmaps and EU AI Act implementation timelines.
Underlying assumptions cover regulatory pathway stability and hospital IT modernization budgets, with deviation risk concentrated in FDA premarket guidance revisions and EMA MDR clinical evidence requirement inflation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
US Digital Health Market
Digital Health Solutions
Europe Digital Therapeutic (Dtx) Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Digital Health Tracking Apps Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Digital Biomarkers Market
Digital Health Solutions
Health Care Interoperability Solutions Market