
 Mental Health Market | 2026-2036
Mental Health Market Size, Share, and Industry Trends Forecast 2026-2036
Mental Health Market Intelligence
Evidence-based care standards is reorganizing competitive dynamics across the mental health landscape. Universal Health Services anchors inpatient psychiatric capacity across concentrated geographic clusters. Teladoc Health leverages virtual infrastructure to extend behavioral access into underserved rural markets. Lyra Health differentiates through employer-centric network curation and outcomes-based contracting.
Mental health encompasses clinical interventions, psychopharmacological treatments, digital therapeutics, and psychosocial support systems designed to diagnose, manage, and prevent psychiatric and psychological conditions. Functional parameters include symptom severity indexing, treatment response metrics, and care continuity protocols that govern patient outcomes across acute and maintenance phases. Digital tools within the delivery mode dimension capture the fastest expansion as asynchronous platforms and AI-assisted screening reduce per-session cost structures. Medications sustain the largest value pool due to chronic prescribing patterns for depression and anxiety indications, though patent cliffs and generic erosion compress margins in mature therapeutic classes.
The FDA regulates digital therapeutics as Software as a Medical Device, imposing clinical validation requirements that filter market entrants and elevate development costs for technology developers. HIPAA governs data portability and privacy architecture across teletherapy and mobile application channels, directly shaping platform design and interoperability investment. State-level telehealth parity statutes determine reimbursement equivalence between in-person and virtual encounters, creating fragmented access economics that stakeholders must monitor as federal policy alignment remains unresolved.
Market Dynamics
Telehealth parity statutes and FDA digital therapeutics pathways are restructuring how mental health services reach patients and how providers capture reimbursement, compressing traditional brick-and-mortar delivery models while elevating platform-based care coordination.
Growth Catalysts
- Employer wellness mandates:Large employers in the United States are expanding behavioral health benefits as workforce retention tools, creating guaranteed payment pools for managed care networks.
- FDA Software as a Medical Device framework:Clearer approval pathways for digital therapeutics are attracting venture investment into clinically validated mental health applications.
- AI-assisted screening platforms:Natural language processing tools embedded in primary care workflows are identifying undiagnosed depression and anxiety cases at scale.
Market Restraints
- State-level reimbursement fragmentation:Inconsistent telehealth parity laws across United States jurisdictions create administrative complexity for multi-state providers.
- Clinical workforce concentration:Psychiatrists and licensed psychologists cluster in urban corridors, leaving rural and exurban areas with severe access deficits.
- Generic psychopharmacological erosion:Patent expirations on major antidepressant classes are compressing margins for pharmaceutical developers.
Strategic Opportunities
- Integrated primary-behavioral care models:Co-located services in United States federally qualified health centers are capturing Medicaid and Medicare reimbursement streams previously lost to fragmented referrals.
- Asynchronous text-based therapy:Messaging platforms are penetrating price-sensitive segments underserved by synchronous video consultation.
- HIPAA-compliant data interoperability:Electronic health record integration is enabling closed-loop referral tracking that satisfies value-based contracting requirements.
Industry Challenges
- Licensed clinician recruitment:Burnout and compensation competition from technology platforms are constraining capacity expansion for traditional health systems.
- Multi-jurisdictional compliance architecture:Providers operating across state lines must maintain separate credentialing, malpractice coverage, and privacy protocols for each jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mental Health Market |
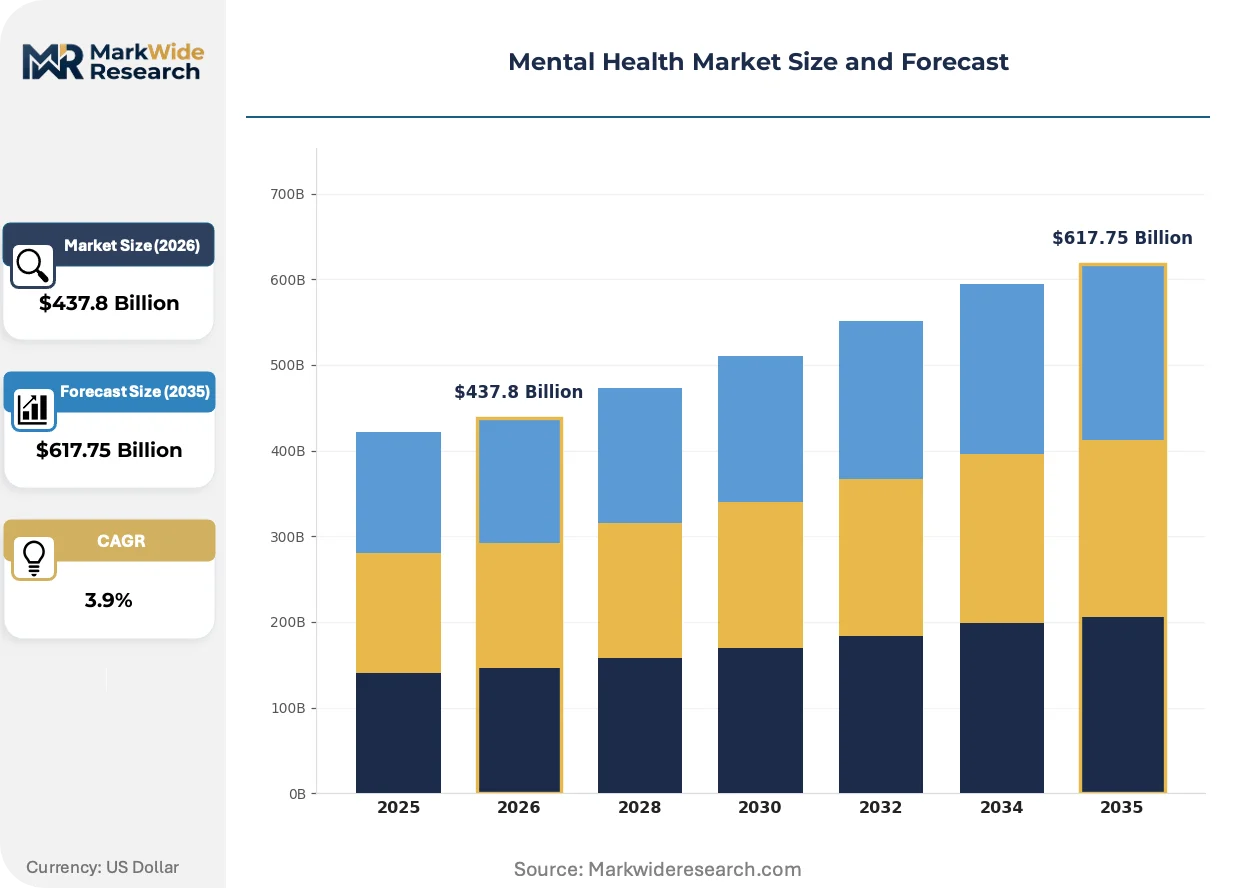
| Market Size in 2026 | $437.8 Billion |
| Market Size in 2035 | $617.75 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapies, Medications, Digital Tools, Counseling Services End User: Individuals, Healthcare Providers, Organizations, Schools Delivery Mode: In-Person, Teletherapy, Mobile Applications, Support Groups Application: Depression, Anxiety, Stress Management, Substance Abuse |
| Companies Covered | Universal Health Services, Acadia Healthcare, Teladoc Health, CVS Health, Centene Corporation, Headspace, Calm, Talkspace, Lyra Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mental Health Market Strategic Shifts & Innovations
Digital delivery infrastructure is fragmenting patient acquisition pathways while regulatory clarity on software-based interventions is unlocking new capital deployment into measurement-based care models.
AI-powered symptom monitoring is bifurcating the traditional therapeutic relationship. Passive data collection from smartphone sensors and wearable devices enables continuous mood and behavioral pattern detection. Large employers and payers are piloting these tools for early intervention in high-risk employee populations. The technology is bifurcating revenue streams between episodic reimbursement and subscription-based preventive monitoring contracts.
The FDA's evolving enforcement discretion policy for digital therapeutics is clarifying which mental health applications require full premarket review. Lower-risk wellness applications face reduced regulatory burden while prescription digital therapeutics must demonstrate randomized controlled trial outcomes. Developers in the United States are responding by stratifying product portfolios across wellness, diagnostic, and treatment categories with corresponding regulatory investment levels.
Value-based purchasing arrangements are displacing fee-for-service contracts in employer-sponsored behavioral health. Large self-insured employers are demanding outcome guarantees from network providers, shifting financial risk from payers to care delivery organizations. This restructuring is most advanced in California and Massachusetts where integrated health systems have invested in measurement infrastructure sufficient to satisfy contractual reporting requirements.
Mental Health Market Segmentation
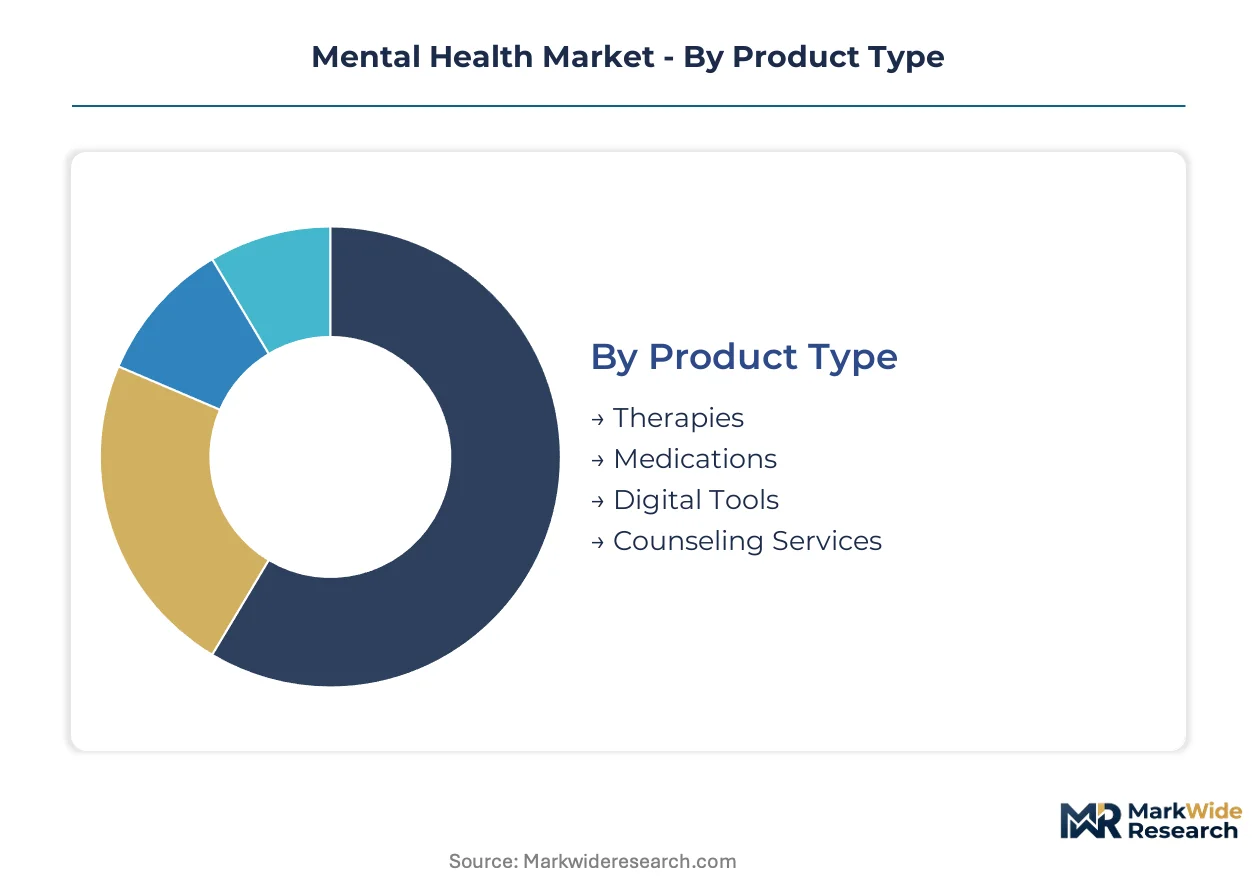
Segmentation in mental health services determines reimbursement pathways, regulatory requirements, and capital allocation strategies. Product classification dictates FDA oversight intensity, while delivery mode shapes state-level licensing compliance and payer contract structures.
Product Type:
FDA Software as a Medical Device framework creates divergent approval burdens across product categories, filtering market entrants by clinical validation capacity and development capital.
- Therapies:Evidence-based psychotherapeutic interventions including cognitive behavioral therapy and dialectical behavior therapy protocols. United States integrated health systems in California and Massachusetts concentrate demand as value-based purchasing arrangements displace fee-for-service contracts.
- Medications:Psychopharmacological treatments spanning antidepressant, anxiolytic, and antipsychotic therapeutic classes. Chronic prescribing patterns for depression and anxiety indications sustain volume, though patent cliffs and generic erosion compress margins in mature therapeutic classes.
- Digital Tools:FDA-regulated software interventions and wellness applications with corresponding regulatory investment tiers.
- Counseling Services:Licensed clinician-delivered talk therapy and crisis intervention across outpatient and community-based settings.
Medications handles the majority of throughput; Digital Tools is expanding most quickly on share.
End User:
Payment guarantee structures vary sharply across customer categories, with employer-sponsored benefits offering superior collection rates versus fragmented individual reimbursement.
- Individuals:Direct-pay consumers and insured patients navigating deductible structures and out-of-network penalties. Rural United States populations face severe access deficits as psychiatrists cluster in urban corridors, intensifying demand for teletherapy platforms.
- Healthcare Providers:Hospitals, clinics, and federally qualified health centers purchasing enterprise mental health infrastructure. United States integrated care models in federally qualified health centers capture Medicaid and Medicare reimbursement streams through co-located primary-behavioral services.
- Organizations:Employer-sponsored behavioral health programs with workforce retention mandates.
- Schools:K-12 and higher education institutions funding counseling and early intervention services.
Organizations generates the steadiest revenue per encounter; Individuals shows the widest geographic variance in realized pricing.
Delivery Mode:
State-level telehealth parity statutes fragment reimbursement economics, creating administrative complexity for providers operating across United States jurisdictions.
- In-Person:Traditional brick-and-mortar clinical encounters with full licensure and facility requirements. Urban United States corridors sustain capacity concentration, while exurban areas exhibit pronounced supply constraints relative to demand density.
- Teletherapy:Synchronous video consultation platforms extending behavioral access into underserved markets. HIPAA governs data portability and privacy architecture, directly shaping platform design and interoperability investment for multi-state providers.
- Mobile Applications:Asynchronous platforms and AI-assisted screening tools reducing per-session cost structures.
- Support Groups:Peer-led and facilitator-moderated group interventions across community and digital channels.
In-Person retains the highest per-session reimbursement; Mobile Applications is climbing the fastest on user acquisition metrics.
Application:
Diagnostic prevalence and chronicity profiles determine lifetime value calculations and therapeutic investment prioritization across pharmaceutical and digital development pipelines.
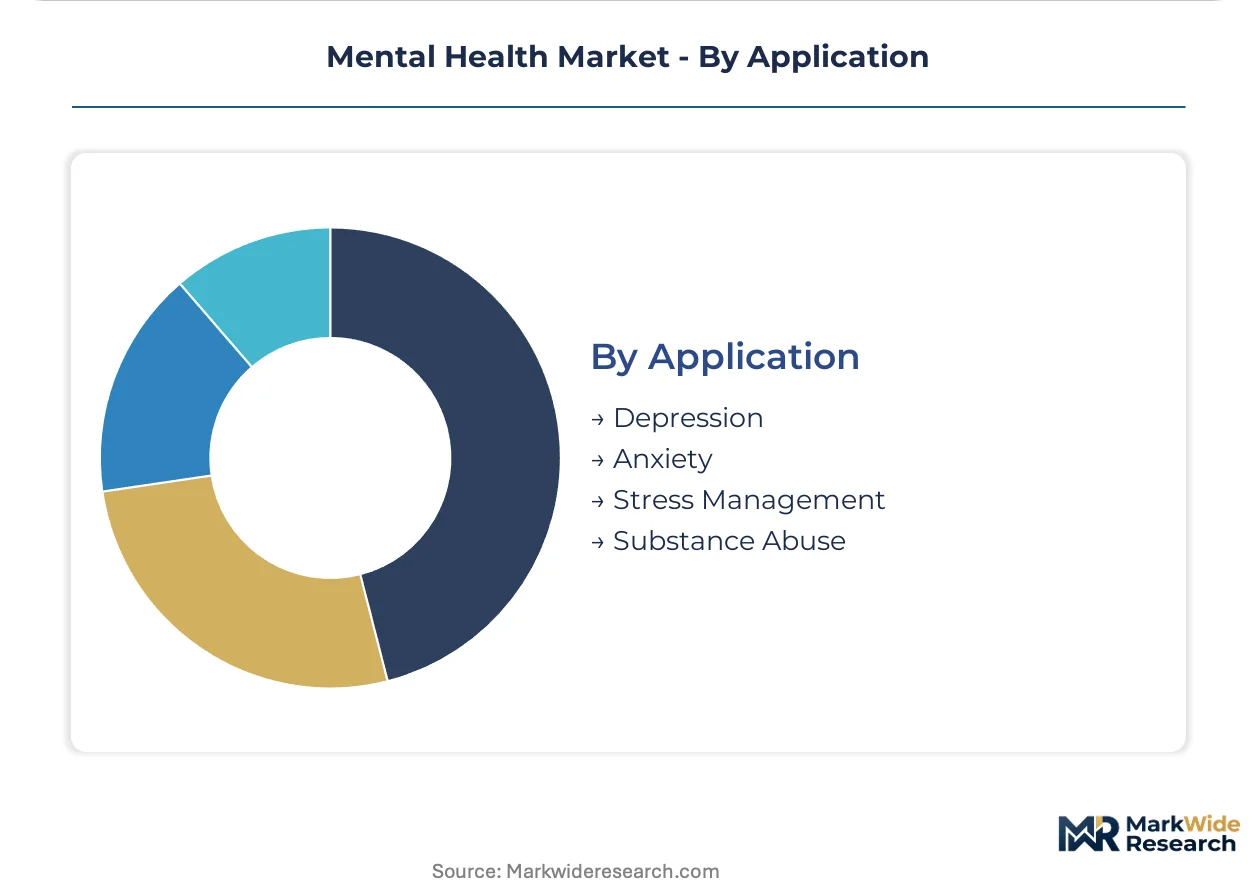
- Depression:Major depressive disorder and persistent depressive conditions with established pharmacological and psychotherapeutic protocols. United States commercial payers drive service expansion through integrated care models, with AI-assisted screening in primary care workflows identifying undiagnosed cases at scale.
- Anxiety:Generalized anxiety disorder, panic disorder, and social anxiety conditions with expanding digital therapeutic development. Large employers pilot passive data collection from smartphone sensors for early intervention in high-risk employee populations, bifurcating revenue toward subscription-based preventive monitoring.
- Stress Management:Subclinical wellness and resilience interventions targeting occupational and lifestyle factors.
- Substance Abuse:Addiction treatment and recovery support services spanning medication-assisted therapy and behavioral counseling.
Depression commands the largest absolute service volume; Anxiety is gaining share fastest on employer wellness investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The mental health services trade flows asymmetrically, with the United States importing specialized therapeutic expertise while exporting digital therapeutic platforms to European and Asian markets. Developed economies retain net importer status for clinician-delivered care, whereas software-based interventions generate cross-border revenue streams from lower-labor-cost development centers.
United States
Employer-sponsored behavioral health mandates and integrated care model investments concentrate demand in California and Massachusetts health systems. FDA's Software as a Medical Device framework and HIPAA privacy architecture shape platform development requirements for domestic and export markets. The Boston-Cambridge corridor anchors digital therapeutic venture capital deployment, with Massachusetts General Hospital and McLean Hospital clusters driving measurement-based care standardization.
Germany
Statutory health insurance reimbursement expansion for digital therapeutics and psychotherapy access reforms accelerate service adoption across ambulatory care networks. BfArM's DiGA fast-track approval pathway for digital health applications reduces time-to-market for mental health software developers. The Berlin-Brandenburg metropolitan region concentrates startup formation, with Charité university hospital partnerships validating clinical outcomes for EU market entry.
United Kingdom
NHS Talking Therapies program procurement and Improving Access to Psychological Therapies expansion sustain publicly funded service volume despite workforce constraints. MHRA's software medical device guidance and NICE technology appraisal frameworks determine reimbursement eligibility for digital interventions. Greater London hosts the predominant specialist workforce concentration, with Oxford and Cambridge university hospital trusts piloting AI-assisted screening integration.
Japan
Corporate mental health program mandates under the Stress Check Program and aging-population dementia care demand reshape service delivery priorities. PMDA's digital therapeutic approval pathways and Ministry of Health, Labour and Welfare reimbursement decisions govern market access for software-based treatments. The Tokyo-Osaka corridor sustains psychiatric specialist concentration, while regional prefectures exhibit pronounced access deficits addressed through telemedicine expansion.
Australia
Medicare-subsidized psychological services and Better Access initiative funding sustain individual therapy utilization despite session limit constraints. TGA's software as a medical device framework and state-based telehealth parity determinations fragment digital service reimbursement. Sydney and Melbourne metropolitan clusters retain clinical workforce density, with rural and remote areas dependent on telepsychiatry platforms for specialist access.
Mental Health Market Key Industry Players
Listed leaders compete with private specialists across capital access and clinical workforce retention dimensions. The market structure tiers between scale-driven hospital systems, technology-enabled virtual care platforms, and venture-backed digital therapeutic developers. Two dominant archetypes emerge: inpatient psychiatric facility operators with geographic clustering strategies, and employer-centric virtual care coordinators with outcomes-based contracting models. Consolidation through health system acquisitions and strategic partnerships with self-insured employers represent the prevailing competitive moves.
Within the facility-based tier, Universal Health Services and Acadia Healthcare exemplify geographic concentration strategies across United States metropolitan corridors. Among virtual care platforms, Teladoc Health occupies a position extending behavioral access into underserved markets through synchronous video infrastructure. Lyra Health represents the employer-centric network curation archetype, with outcomes-based contracting structures displacing traditional fee-for-service arrangements. These three entities anchor distinct competitive vectors: physical capacity, virtual reach, and purchaser integration.
| Leading Market Players |
|---|
| Universal Health Services |
| Acadia Healthcare |
| Teladoc Health |
| CVS Health |
| Centene Corporation |
| Headspace |
| Calm |
| Talkspace |
| Lyra Health |
| Others |
Cost & Logistics Intelligence
Platform scale economies in asynchronous mental health delivery compress per-session cost structures while concentrating pricing power among integrated care networks. United States employer-sponsored benefits anchor price floors through guaranteed payment pools, whereas direct-pay individual segments face wider variance as telehealth parity statutes fragment reimbursement equivalence across state jurisdictions.
Pricing Analysis
Employer-sponsored benefits anchor a three-tier pricing structure across premium, standard, and economy levels in the mental health market. Price differentiation rests on clinician credential tier and outcomes-based contracting sophistication, with California and Massachusetts integrated health systems commanding premium positioning. Pricing pressure stems from generic psychopharmacological erosion as patent expirations compress pharmaceutical margins. Individuals navigating high-deductible plans exhibit highest price sensitivity, while self-insured employers with workforce retention mandates demonstrate lowest sensitivity to per-encounter costs.
Supply Chain Analysis
Licensed clinician workforce concentration in urban United States corridors creates supply chokepoints that constrain rural and exurban service expansion. The supply chain draws from psychiatrist and psychologist training pipelines clustered in Boston-Cambridge, New York, and California metropolitan regions, with digital therapeutic development concentrated in Berlin-Brandenburg and Greater London innovation clusters. Raw material dependencies include pharmaceutical APIs from India and China, cloud infrastructure from hyperscaler data centers, and wearable sensor components from East Asian electronics manufacturers. Single-source vulnerability sits with FDA Software as a Medical Device validation capacity, where limited qualified review staff extend approval timelines. Distribution runs through employer benefits administrators, health system EHR platforms, and direct-to-consumer app marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's digital therapeutics framework and evolving telehealth parity laws constitute a regulatory inflection accelerating platform-based care displacement of traditional brick-and-mortar delivery. This disruption creates asymmetric opportunity across incumbent defense, entrant white-space capture, and investment cycle positioning.
For Market Incumbents: Fortify inpatient psychiatric capacity through geographic clustering in employer-dense United States metropolitan corridors where integrated care models capture value-based purchasing contracts. Invest in HIPAA-compliant data interoperability to satisfy closed-loop referral tracking requirements that employers increasingly mandate. Defend against virtual-first entrants by embedding measurement-based care infrastructure sufficient to guarantee outcomes.
For New Entrants and Emerging Players: Rural and exurban access deficits in the United States represent service-layer gaps where asynchronous text-based therapy platforms can establish footholds before synchronous video competitors achieve scale. Target price-sensitive individual segments underserved by high-deductible plan structures, leveraging AI-assisted screening to reduce per-acquisition costs below incumbent benchmarks. Pursue employer direct-contracting as the most penetrable go-to-market angle, bypassing health system credentialing complexity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital therapeutic developers with FDA Software as a Medical Device clearances and demonstrated randomized controlled trial outcomes. Long-term viability across the projection horizon rests on regulatory validation capacity rather than user acquisition scale alone. Acquisition target archetypes include measurement-based care infrastructure providers and clinician workforce platforms with multi-state licensing compliance. Monitor FDA enforcement discretion policy evolution as the critical inflection signal distinguishing wellness applications from prescription digital therapeutics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Regulatory clearance unlocks prescription digital therapeutic reimbursement under United States payer frameworks. |
| Employer Direct Contracting Partnership | Self-insured benefits administrators guarantee payment pools that bypass health system intermediary complexity. |
| HIPAA-Compliant EHR Integration | Closed-loop referral tracking satisfies value-based purchasing requirements from California and Massachusetts health systems. |
| Clinician Workforce Platform Expansion | Multi-state credentialing infrastructure addresses licensed provider recruitment constraints constraining traditional capacity. |
| AI-Assisted Screening Development | Natural language processing tools embedded in primary care workflows identify undiagnosed depression cases at scale. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare reimbursement databases, ClinicalTrials.gov digital therapeutic registrations, and state telehealth parity statute compilations. Primary interviews engaged behavioral health benefit directors at self-insured employers, psychiatric facility operations executives, digital therapeutic regulatory affairs leads, and telehealth platform product managers. Secondary validation drew from SEC 10-K disclosures of listed facility operators, venture capital investment databases tracking mental health technology deployment, and hospital procurement records from United States integrated health systems. Bottom-up encounter volume modeling triangulates against top-down payer expenditure estimates.
Segmentation dimensions modeled span product type, end user category, delivery mode, and application indication across the analysis window. The analytical framework derives CAGRs through regression of historical encounter volume against employer benefit expansion rates, FDA approval velocity, and telehealth parity law adoption patterns. Forecast inputs include licensed clinician pipeline graduation data from American Psychological Association and Association of American Medical Colleges sources, plus digital therapeutic venture deployment tracking from PitchBook and CB Insights databases.
Material uncertainties — state-level telehealth parity legislative reversals, FDA enforcement discretion policy shifts, and clinician workforce burnout acceleration — sit outside the modeled envelope. Forecasts reflect assumptions of continued employer wellness mandate expansion and stable Medicare reimbursement for integrated behavioral health services. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
Germany Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
South Korea Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Agoraphobia Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Postpartum Depression (PPD) Treatment Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
US Behavioral Health Care Software and Services Market