
 Europe Mobility Aids Market | 2026-2036
Europe Mobility Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobility Aids Market Intelligence
Buyer concentration among elderly homecare users is restructuring procurement patterns across national health systems. Invacare Corporation leverages extensive service networks to sustain recurring revenue from institutional contracts. Sunrise Medical anchors premium positioning through advanced seating technology for complex rehabilitation cases. Ottobock dominates the German market with orthotics-to-mobility integration that spans clinical and retail channels.
Mobility aids encompass assistive devices engineered for locomotion support, typically fabricated from aluminum alloys, carbon fiber composites, or high-grade polymers with load ratings between 100 kg and 200 kg and ergonomic adjustability for user anthropometrics. Wheelchairs and scooters absorb the largest value share as powered variants command higher unit economics and longer replacement cycles. Walkers and canes serve price-sensitive segments where lightweight folding designs and rollator configurations capture expanding elderly self-pay demand. End users fragment across Disabled Individuals, Elderly People, Rehabilitation Centers, and Healthcare Institutions, with rehabilitation centers driving specifications for bariatric and tilt-in-space configurations.
CE marking under the EU Medical Device Regulation mandates clinical evaluation and post-market surveillance for Class I through Class III mobility products, while the F-Gas Regulation constrains refrigerant choices in climate-controlled manufacturing facilities. Germany's KBA influences automotive-adjacent scooter safety standards, and France's ANSM oversees custom-molded seating classified as borderline medical devices. Stakeholders must monitor divergence between national reimbursement catalogs and harmonized technical standards as procurement centralization accelerates.
Market Dynamics
The EU Medical Device Regulation is compressing product development timelines while simultaneously elevating clinical evidence requirements, forcing manufacturers to restructure R&D budgets and post-market surveillance systems across member states.
Growth Catalysts
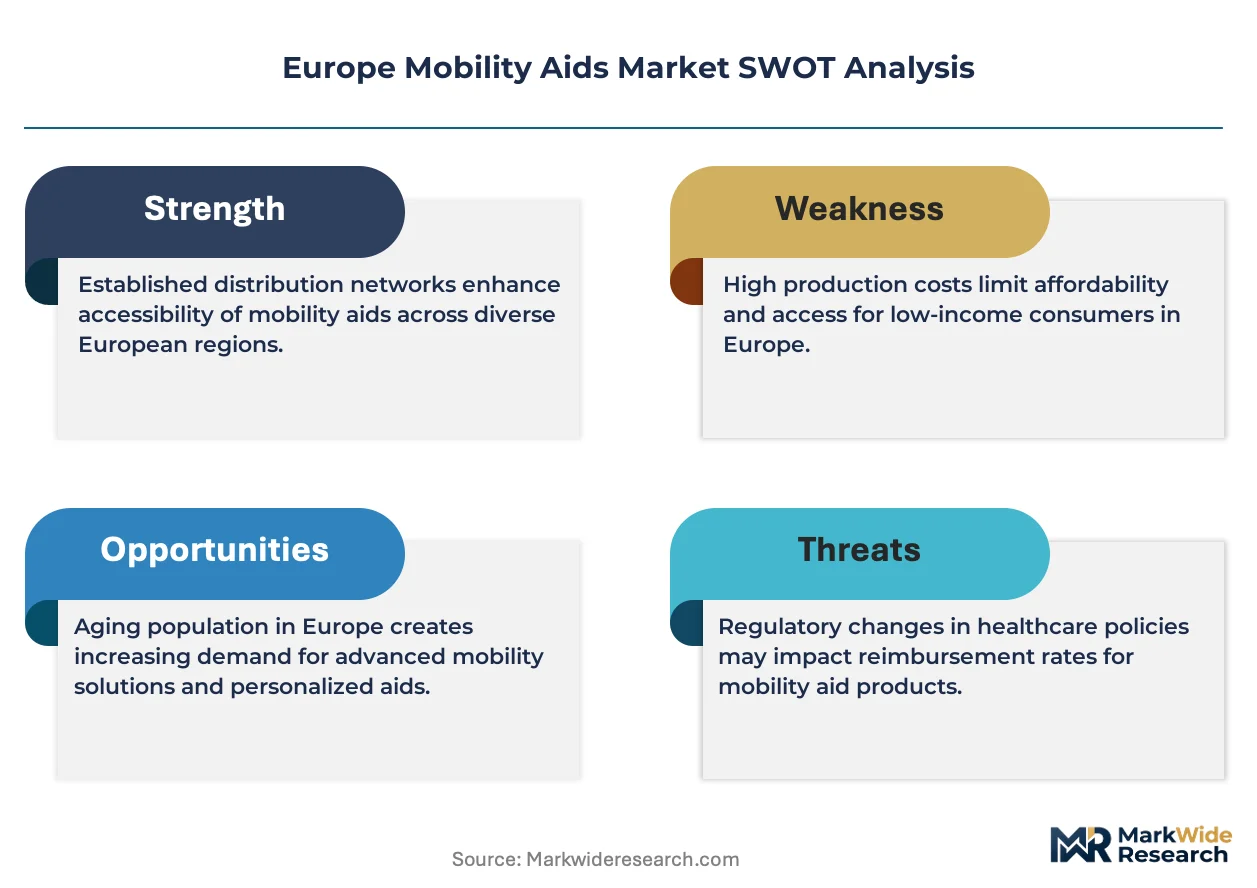
- Aging demographics:Germany's elderly population expansion drives homecare walker and rollator procurement through statutory health insurance reimbursement channels.
- MDR harmonization:CE marking convergence under the EU Medical Device Regulation reduces national technical barriers and accelerates cross-border distribution for Class IIa mobility scooters.
- Carbon fiber adoption:Lightweight composite materials enable powered wheelchair weight reduction below 10 kg, expanding airline-compatible travel segments for bariatric users.
Market Restraints
- Aluminum alloy volatility:Raw material price swings for 6061-T6 and 7075 grades compress margin buffers on standard manual wheelchair frames produced in Eastern European contract facilities.
- Battery supply concentration:Lithium-ion cell sourcing dependency on Asian suppliers creates 14-16 week lead time exposure for powered mobility OEMs serving French and Italian markets.
- Reimbursement fragmentation:Divergence between Germany's KBA automotive standards and France's ANSM borderline device classifications forces dual certification costs for cross-channel seating systems.
Strategic Opportunities
- Spanish tender centralization:Andalusia and Catalonia regional health consortia are consolidating wheelchair procurement into multi-year framework agreements favoring service-integrated suppliers.
- IoT-telemetry convergence:GPS-enabled scooters paired with remote diagnostic platforms create recurring revenue streams through predictive maintenance subscriptions for institutional lessors.
- F-Gas manufacturing incentives:Climate-controlled production facility upgrades under the EU F-Gas Regulation qualify for green transition financing in Poland and Romania assembly plants.
Industry Challenges
- Clinical evaluation capacity:Notified body bottlenecks for MDR Article 61 conformity assessments extend product launch timelines by 8-12 months for tilt-in-space wheelchair innovations.
- Legacy ERP integration:Post-market surveillance data capture systems require expensive middleware development to connect with existing German hospital procurement networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobility Aids Market |
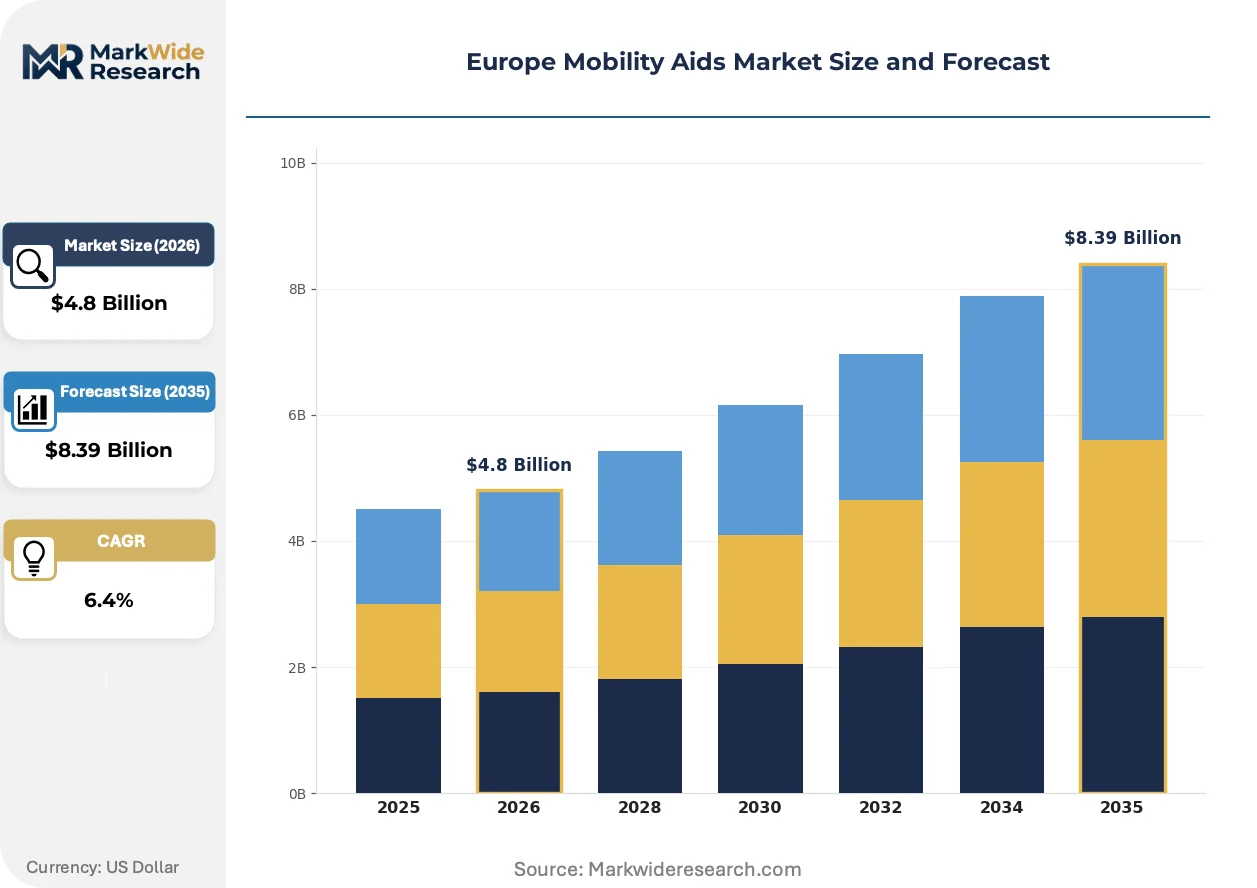
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheelchairs, Scooters, Walkers, Canes End User: Disabled Individuals, Elderly People, Rehabilitation Centers, Healthcare Institutions Distribution Channel: Online Retail, Specialized Stores, Pharmacies, Direct Sales Application: Daily Living Assistance, Sports Activities, Outdoor Mobility, Homecare Solutions |
| Companies Covered | Drive DeVilbiss Healthcare, Human Care HC AB, Invacare Corporation, Medline Industries Inc., Karma Mobility, Sunrise Medical, Ottobock, Etac, MEYRA GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobility Aids Market Strategic Shifts & Innovations
Digital connectivity and sustainable materials are converging to redefine product architecture and service delivery models across European mobility aid channels.
Modular carbon fiber frame systems are consolidating manufacturing footprints by enabling single-platform production across manual wheelchair, transport chair, and pediatric configurations. Rehabilitation centers in the Netherlands and Belgium specify these platforms for fleet standardization. The technology is consolidating supplier tiers as aluminum forging specialists lose share to composite integration houses.
The EU F-Gas Regulation is constraining refrigerant choices in climate-controlled seating mold facilities, forcing Ottobock and Sunrise Medical to retrofit polyurethane production lines in Germany. This industrial consequence elevates capital intensity for custom-contoured cushions classified as borderline devices under France's ANSM guidance.
Direct-to-consumer digital channels are displacing traditional orthopedic retailer networks for lightweight folding walker sales. Elderly buyers in Italy and Spain research rollator specifications through manufacturer websites before requesting home trials. This pattern is most visible in urban Spanish markets where pharmacy distribution margins have compressed by one-third.
Europe Mobility Aids Market Segmentation
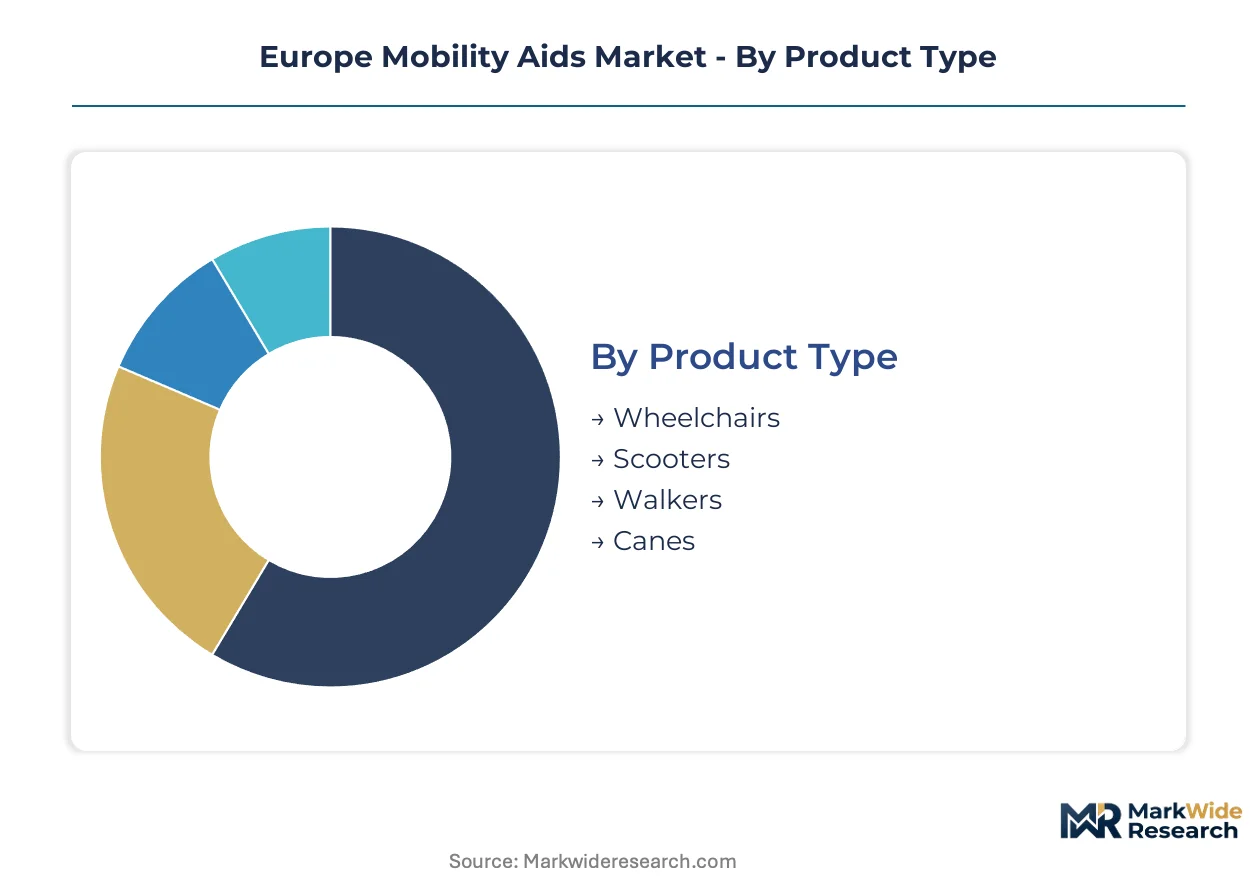
Product architecture and reimbursement pathways fragment the Europe Mobility Aids Market into distinct commercial battlegrounds. Each segmentation dimension reveals divergent margin structures, regulatory exposure, and channel control points that determine competitive outcomes.
Product Type:
Technical sophistication and unit economics separate institutional procurement from retail self-pay decisions across national health systems.
- Wheelchairs:Powered variants integrate lithium-ion battery systems with programmable drive controls for bariatric and tilt-in-space configurations. Rehabilitation centers in Germany and the Netherlands specify these for complex neurological cases, though MDR Article 61 clinical evaluation bottlenecks extend launch timelines by 8-12 months for innovative seating systems.
- Scooters:Automotive-adjacent designs with GPS-telemetry compatibility command premium positioning through statutory insurance channels. France's ANSM borderline device classification and Germany's KBA safety standards create dual certification burdens that favor established service-integrated suppliers.
- Walkers:Aluminum and carbon fiber rollator configurations serve elderly homecare demand with lightweight folding architectures.
- Canes:Basic assistive devices address price-sensitive segments through pharmacy and direct-to-consumer channels in Italy and Spain.
Volume sits with wheelchairs; growth tilts toward scooters.
End User:
Reimbursement authority and specification complexity concentrate purchasing power across four distinct stakeholder categories.
- Disabled Individuals:Users with permanent mobility impairment drive demand for custom-molded seating and modular frame systems. France's national health tender centralization and Germany's statutory insurance catalogs determine accessible price points for Class IIa medical devices.
- Elderly People:Aging demographics in Germany and Spain propel homecare walker and rollator procurement through pharmacy networks and direct manufacturer channels. Digital research behavior among Italian urban elderly is displacing traditional orthopedic retailer intermediation.
- Rehabilitation Centers:Fleet standardization requirements in Belgium and the Netherlands favor carbon fiber platform systems that span manual wheelchair, transport chair, and pediatric configurations.
- Healthcare Institutions:Hospital procurement networks demand post-market surveillance data integration through legacy ERP middleware, elevating supplier technical service capabilities.
Institutional contracts anchor current revenue; elderly self-pay segments are climbing the fastest.
Distribution Channel:
Channel margin compression and regulatory proximity reshape go-to-market economics for mobility aid manufacturers.
- Online Retail:Direct-to-consumer digital platforms capture lightweight folding walker sales as elderly buyers in Spain and Italy research specifications before requesting home trials. Pharmacy distribution margins in urban Spanish markets have compressed by one-third under this displacement pressure.
- Specialized Stores:Orthopedic retailers retain relevance for complex rehabilitation seating requiring fitting expertise and ongoing adjustment services.
- Pharmacies:Community dispensaries serve as reimbursement access points for standard walkers and canes across national health systems.
- Direct Sales:Manufacturer field organizations secure multi-year framework agreements with Andalusia and Catalonia regional health consortia.
Specialized stores hold installed base; online retail is gaining share fastest.
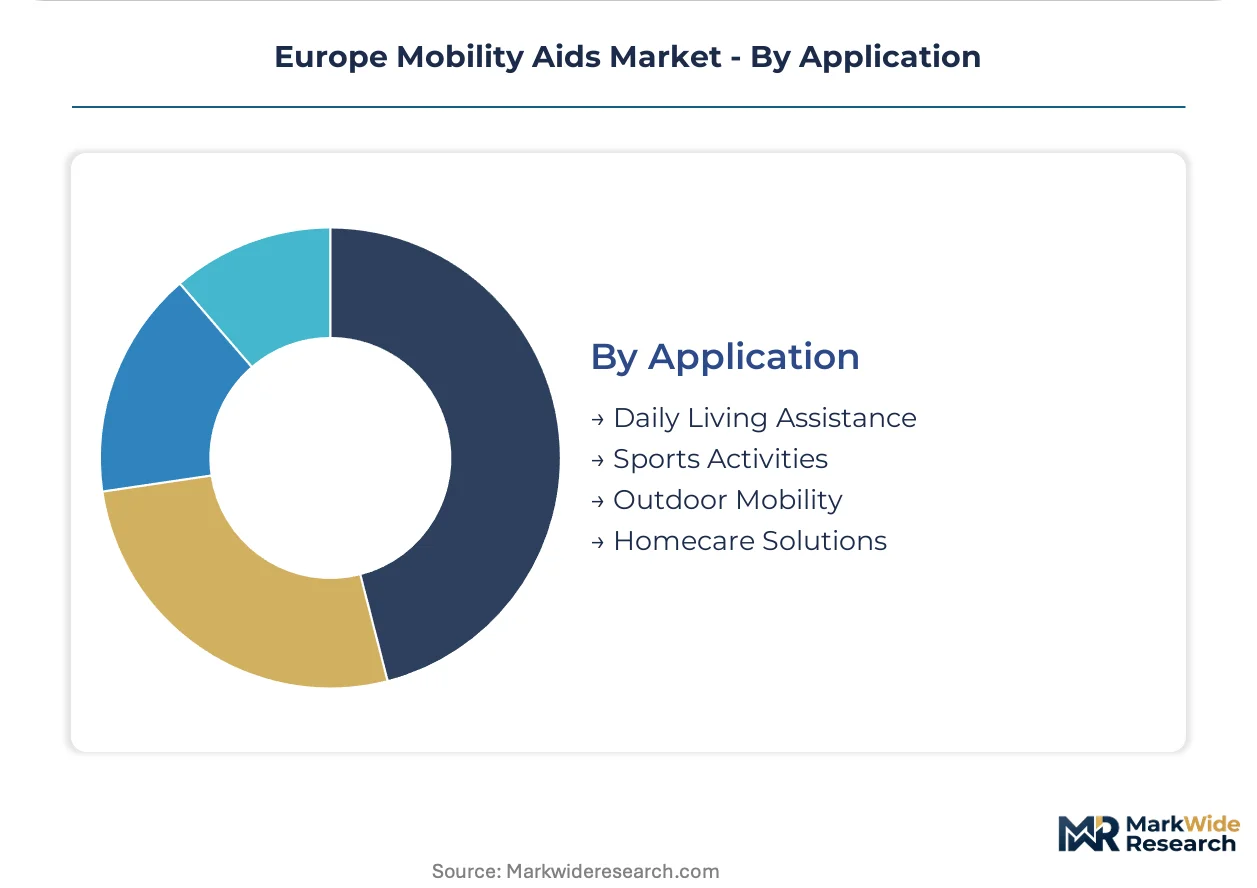
Application:
Use case intensity and environmental exposure determine product durability requirements and replacement cycle frequency.
- Daily Living Assistance:Core functional support for indoor and community navigation represents the baseline addressable market across all product categories.
- Sports Activities:Specialized racing wheelchairs and adaptive equipment serve competitive athletic segments with custom performance specifications.
- Outdoor Mobility:All-terrain scooters and reinforced frame systems address rural and uneven surface navigation requirements.
- Homecare Solutions:Adoption is rising among elderly buyers in Germany as statutory insurance reimbursement channels expand for aging-in-place support. The EU Medical Device Regulation tightens conformity requirements for these borderline domestic use products.
Daily living assistance dominates volume; homecare solutions show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates among elderly homecare users in Germany, where statutory insurance reimbursement channels are restructuring procurement patterns across national health systems. France, Italy, and Spain centralize wheelchair and walker procurement through national health tenders. The EU Medical Device Regulation tightens conformity requirements uniformly across member states.
Germany
Germany's elderly population expansion drives homecare walker and rollator procurement through statutory health insurance reimbursement channels. The KBA influences automotive-adjacent scooter safety standards, creating certification overlap with medical device frameworks. Ottobock anchors orthotics-to-mobility integration across clinical and retail channels in Duderstadt and surrounding Lower Saxony manufacturing clusters.
France
France concentrates wheelchair procurement through national health tenders administered by regional hospital consortia. The ANSM oversees custom-molded seating classified as borderline medical devices, elevating documentation burdens for seating manufacturers. Industrial activity clusters around Paris and Lyon, where service-integrated suppliers secure multi-year framework agreements with institutional buyers.
Italy
Italian elderly buyers research rollator specifications through manufacturer websites before requesting home trials, displacing traditional orthopedic retailer intermediation. CE marking under the EU Medical Device Regulation governs Class IIa mobility scooters distributed through pharmacy networks. Manufacturing and distribution concentrate in northern industrial zones around Milan and Bologna.
Spain
Andalusia and Catalonia regional health consortia consolidate wheelchair procurement into multi-year framework agreements favoring service-integrated suppliers. Pharmacy distribution margins in urban Spanish markets have compressed by one-third under direct-to-consumer digital channel pressure. Valencia and Madrid host assembly operations serving Iberian Peninsula demand.
Netherlands
Rehabilitation centers in the Netherlands specify carbon fiber platform systems for fleet standardization across manual wheelchair, transport chair, and pediatric configurations. MDR Article 61 clinical evaluation requirements extend product launch timelines for innovative seating systems. Eindhoven and Rotterdam serve as logistics hubs for Benelux distribution networks.
Europe Mobility Aids Market Key Industry Players
German producers anchor one tier; Swedish and British specialists hold differentiated positions in seating and walker segments. The vendor base spans multinational service-integrated suppliers, regional tender-focused fabricators, and orthopedic technology integrators. Three archetypes dominate: statutory insurance channel specialists, premium rehabilitation seating developers, and carbon fiber platform system suppliers. Competitive moves concentrate on M&A for service network expansion and backward integration into lithium-ion battery assembly.
Within the premium rehabilitation tier, Sunrise Medical and Ottobock occupy positions defined by advanced seating technology and orthotics-to-mobility integration respectively. Invacare Corporation exemplifies the service-integrated multinational archetype through extensive field organizations securing institutional contracts. MEYRA GmbH represents German-engineered fabrication capabilities serving statutory insurance reimbursement channels. These three anchors illustrate how geographic origin and organizational structure map to distinct competitive vectors in European procurement systems.
| Leading Market Players |
|---|
| Drive DeVilbiss Healthcare |
| Human Care HC AB |
| Invacare Corporation |
| Medline Industries Inc. |
| Karma Mobility |
| Sunrise Medical |
| Ottobock |
| Etac |
| MEYRA GmbH |
| Others |
Cost & Logistics Intelligence
Backward integration into lithium-ion battery assembly anchors supply position and pricing power for powered mobility OEMs serving German and French statutory insurance channels. This upstream control over critical energy storage components insulates margin structures from Asian supplier concentration while enabling service-integrated suppliers to bundle predictive maintenance subscriptions into multi-year framework agreements.
Pricing Analysis
Volume concentrates in standard manual wheelchairs where aluminum frame commoditization compresses margins; premium accrues to powered variants with programmable drive controls and GPS-telemetry compatibility. Pricing stratifies across premium rehabilitation seating, standard statutory insurance catalog products, and economy pharmacy-channel walkers, with CE marking tier and after-sales service bundling as primary differentiation drivers. Cost compression in standard manual wheelchair tiers is intensifying due to Eastern European contract manufacturing competition. Elderly self-pay segments for lightweight rollators exhibit highest price sensitivity; rehabilitation centers demonstrate lowest sensitivity due to specification complexity and fleet standardization requirements.
Supply Chain Analysis
CE marking and MDR Article 61 clinical evaluation requirements gate supplier qualification, extending onboarding timelines for innovative seating manufacturers. Manufacturing concentrates in Germany, Poland, and Romania, with polyurethane production facilities in Lower Saxony feeding custom-molded cushion operations. Lithium-ion cell sourcing draws from South Korean and Chinese suppliers, creating single-source vulnerability for powered mobility OEMs. Distribution runs through statutory insurance reimbursement channels, hospital procurement networks, and direct-to-consumer digital platforms displacing traditional orthopedic retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race: control over battery assembly and carbon fiber composite production determines who captures margin from electrification and lightweighting trends across European procurement systems.
For Market Incumbents: Lock in lithium-ion battery supply through captive assembly partnerships or equity stakes in cell producers to defend margin position against Asian supplier concentration. Secure multi-year framework agreements with Andalusia and Catalonia regional health consortia before tender centralization consolidates buyer power. Reinforce service network density in Germany's homecare corridor to offset direct-to-consumer digital channel displacement of pharmacy intermediaries. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany and Poland opens a window for green transition financing qualification in climate-controlled seating mold facilities, enabling capital-efficient entry against legacy retrofitting burdens. Target elderly self-pay segments in urban Italian and Spanish markets where digital research behavior has already displaced traditional retailer intermediation. Pursue white-label manufacturing partnerships with established carbon fiber platform suppliers to bypass MDR Article 61 clinical evaluation bottlenecks. For Investors and Strategic Acquirers: Exit pathways concentrate in service-integrated multinational archetypes with dense field organizations securing institutional contracts across multiple member states. Long-term viability hinges on reimbursement catalog positioning and post-market surveillance data integration capabilities that hospital procurement networks increasingly mandate. Watch for divergence between Germany's KBA automotive standards and France's ANSM borderline device classifications as an inflection signal for dual certification cost burdens favoring scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 61 clinical evaluation bottlenecks extend launch timelines for tilt-in-space innovations. |
| Hospital System Partnership | Post-market surveillance data integration through legacy ERP middleware elevates supplier technical capabilities. |
| Backward Integration | Captive lithium-ion battery assembly insulates margins from Asian supplier concentration and lead time exposure. |
| Software Companion Development | GPS-telemetry platforms create recurring revenue streams through predictive maintenance subscriptions. |
| Reimbursement Strategy | Germany's statutory insurance catalog positioning determines accessible price points for Class IIa devices. |
Research Approach
Trade databases, national health procurement registries, and EU Medical Device Regulation guidance documents formed the secondary backbone for market sizing and competitive mapping. Primary interviews with rehabilitation center procurement directors, biomedical engineers at Belgian and Dutch fleet standardization committees, GPO contracts managers in French regional hospital consortia, and field service heads at German mobility aid manufacturers validated demand patterns and pricing dynamics. Bottom-up and top-down triangulation reconciled unit shipment estimates with statutory insurance reimbursement channel value flows.
Bottom-up modeling built from product-level specifications, material input costs, and channel margin structures; top-down verification cross-checked against national health expenditure accounts and medical device trade flows. Segmentation dimensions spanned product architecture, end-user reimbursement authority, distribution channel control points, and application intensity across the analysis window. CAGRs derived from demographic elasticity models tied to elderly population projections and statutory insurance catalog expansion trajectories, with carbon fiber adoption curves and IoT-telemetry penetration as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery chemistry or hydrogen fuel cell powertrains would alter the outlook for powered mobility scooter specifications and weight-class certifications. Forecasts reflect assumptions about MDR notified body capacity expansion and F-Gas Regulation enforcement consistency across member states. A model refresh is warranted upon material change in Germany's statutory insurance reimbursement catalog structure or France's ANSM borderline device classification guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Brachytherapy Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
Vaginal Specula Market
Medical Devices
3D-Printed Prosthetic Implants Market
Medical Devices
Self-Injections Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
Global Intraosseous Devices Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Digital Magnifiers Market
Medical Devices
Absorbable Nasal Implant Market