
 Bariatric Patient Room Market | 2026-2036
Bariatric Patient Room Market Size, Share, and Industry Trends Forecast 2026-2036
Bariatric Patient Room Market Outlook
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape into qualified manufacturers and marginal suppliers. Stryker leverages its integrated hospital equipment portfolio to dominate North American contract channels. Hill-Rom sustains technology leadership through pressure-relief surface innovations that reduce caregiver injury rates. Joerns Healthcare specializes in rental and service-based models that lower capital barriers for smaller facilities.
A bariatric patient room comprises reinforced beds, chairs, tables, and mobility aids engineered with higher load capacities, wider dimensions, and enhanced stability parameters for patients exceeding standard weight thresholds. Bariatric beds incorporate steel-reinforced frames rated for significantly higher distributed loads than conventional hospital beds, with motorized articulation systems that reduce manual handling risks for clinical staff. Bariatric chairs and shower commode chairs represent the fastest-expanding product categories as facilities prioritize safe patient handling across the full care continuum. The end-user base tilts toward hospitals and long-term care facilities, where regulatory compliance and staff injury liability create durable replacement cycles.
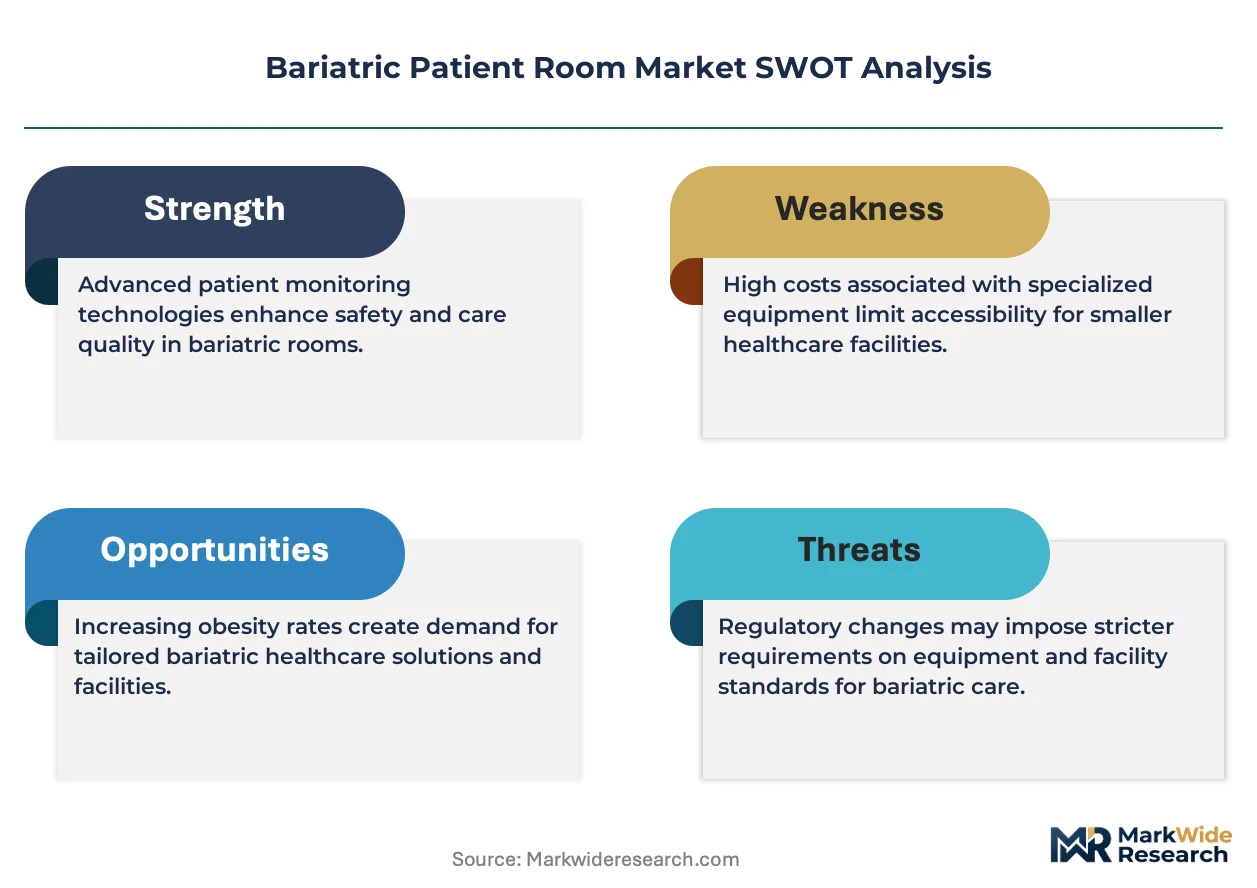
FDA 510(k) clearance requirements govern bariatric bed introductions in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for European market access. OSHA workplace safety guidelines and state-level safe patient handling laws in California, New York, and Illinois directly shape procurement specifications for bariatric equipment. Stakeholders must monitor evolving reimbursement policies for bariatric surgery and related inpatient stays, as these determine capacity expansion budgets and equipment refresh timelines across health systems.
Market Dynamics
Hospital systems are consolidating purchasing power through group purchasing organizations, forcing equipment vendors to absorb certification costs while compressing margins on bariatric bed contracts. This concentration is redrawing competitive boundaries between integrated manufacturers and specialized rental providers.
Growth Catalysts
- OSHA Safe Patient Handling Standards:US workplace safety mandates are compelling acute care facilities to replace manual lift protocols with motorized bariatric beds, creating durable replacement demand across California, New York, and Illinois health systems.
- Steel-reinforced frame engineering:Advanced metallurgy enabling 1,000-pound distributed load ratings is expanding addressable patient populations and reducing liability exposure for caregiver injury claims.
- Long-term care facility expansion:Skilled nursing operators are adding dedicated bariatric wings to capture higher-reimbursement patient categories, driving chair and commode chair procurement cycles.
Market Restraints
- Specialized steel alloy costs:Cold-rolled steel price volatility and supply chain concentration in Chinese and Indian foundries compress manufacturer margins on frame components.
- FDA 510(k) clearance timelines:Pre-market notification requirements for motorized articulation systems extend product launch windows by 12-18 months, delaying revenue recognition for new bed platforms.
- Fixed-height conventional beds:Non-motorized alternatives in standard patient rooms limit upgrade urgency for budget-constrained rural hospitals.
Strategic Opportunities
- Home care bariatric equipment:Discharge planning protocols are pushing durable medical equipment into residential settings, opening rental and service revenue streams outside institutional procurement.
- EU Medical Device Regulation clinical evidence pathways:Stricter MDR requirements for Class IIa devices create first-mover advantages for manufacturers with established clinical data packages.
- Pressure-relief surface integration:Convergence of dynamic air-cell technology with bariatric bed frames enables premium pricing for integrated systems that reduce pressure ulcer incidence.
Industry Challenges
- ISO 13485 quality management certification:Smaller manufacturers face 18-24 month implementation timelines and auditor scarcity, creating competitive exclusion from hospital contract eligibility.
- Legacy nurse call system integration:Bariatric beds must interface with proprietary hospital communication infrastructure, requiring custom engineering for each health system deployment.
- Biomedical technician specialization:Motorized articulation systems demand training programs that most facilities have not institutionalized, slowing maintenance response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bariatric Patient Room Market |
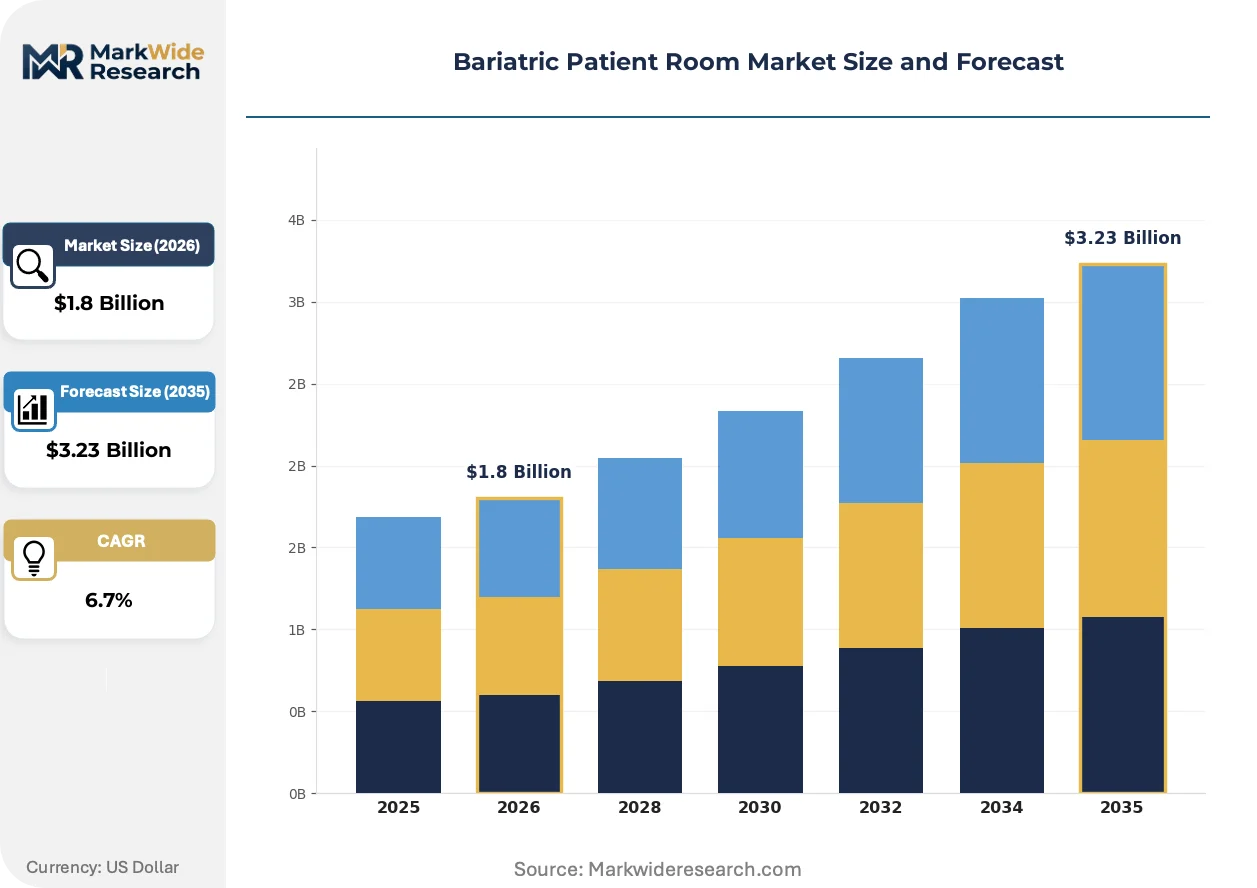
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bariatric Beds, Bariatric Chairs, Overbed Tables, Shower Commode Chairs End User: Hospitals, Long-Term Care Facilities, Rehabilitation Centers, Home Care Material: Steel, Aluminum, Plastic, Fabric Installation: Mobile, Fixed, Modular, Modular-Custom |
| Companies Covered | Stryker, Hill-Rom, Invacare Corporation, Arjo, Joerns Healthcare, Medline Industries, Nemschoff, Brayton, LINET Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bariatric Patient Room Market Strategic Shifts
Equipment manufacturers are embedding sensor networks and predictive maintenance capabilities into bariatric platforms, transforming capital goods into connected care infrastructure. This shift is redefining value capture from hardware sales toward recurring service revenue.
Capacitive weight sensing and position monitoring technology is bifurcating the competitive landscape between integrated smart-bed platforms and basic motorized frames. Academic medical centers and large integrated delivery networks are adopting sensor-equipped beds at accelerated rates to support fall prevention protocols and remote patient monitoring initiatives. The technology is bifurcating vendor strategies: established players are acquiring digital health capabilities while specialists retreat to rental and service models.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical evidence obligations for bariatric bed manufacturers seeking European market access. Device history record maintenance and periodic safety update reporting now consume substantial regulatory affairs resources. European hospital procurement is responding by consolidating supplier relationships with manufacturers possessing established notified body certifications.
Acute care facilities are unbundling equipment acquisition from preventive maintenance contracts, treating bariatric beds as utility-like infrastructure rather than capital assets. Third-party service providers are capturing maintenance revenue that manufacturers previously retained through bundled pricing. This pattern is most pronounced in United States health systems where operating lease structures dominate capital planning.
Bariatric Patient Room Market Segmentation
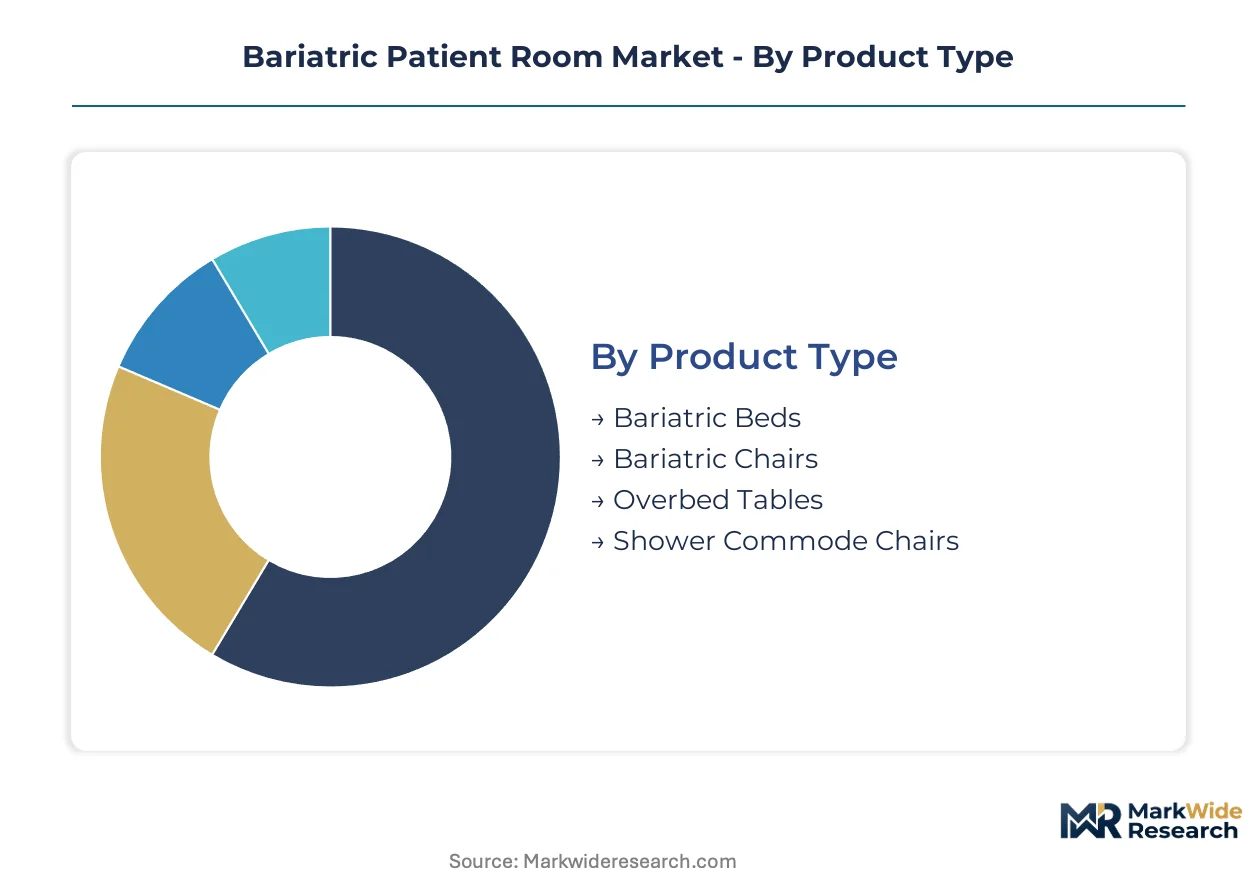
Equipment procurement channels diverge sharply across patient care settings, with acute care hospitals favoring capital purchases through group purchasing organizations while long-term care and home care segments gravitate toward rental and lease structures. Understanding these channel dynamics is essential for manufacturers configuring pricing, service, and distribution strategies.
Product Type:
Channel concentration varies by product complexity, with motorized beds flowing through integrated distributor networks and chairs/commodes increasingly sourced through durable medical equipment specialists.
- Bariatric Beds:Steel-reinforced frames with motorized articulation systems rated for distributed loads exceeding 1,000 pounds. Demand concentrates in United States hospital systems where OSHA safe patient handling mandates in California, New York, and Illinois are compelling replacement of manual lift protocols.
- Bariatric Chairs:Reinforced seating platforms with wider seat depths and enhanced stability bases for safe patient transfer. Long-term care facilities in the United States are adding dedicated bariatric wings to capture higher-reimbursement patient categories, driving procurement cycles for seating and mobility equipment.
- Overbed Tables:Height-adjustable surfaces with extended reach mechanisms and reinforced column structures.
- Shower Commode Chairs:Waterproof seating with integrated commode functions and corrosion-resistant frames for hygiene protocols.
Bariatric beds dominate installed base. Bariatric chairs and shower commode chairs are where expansion concentrates.
End User:
Cost tier stratification separates capital-rich acute care systems from budget-constrained post-acute operators and residential settings.
- Hospitals:Integrated delivery networks with consolidated purchasing power through group purchasing organizations. These systems prioritize FDA 510(k) cleared platforms with nurse call integration and predictive maintenance capabilities.
- Long-Term Care Facilities:Skilled nursing operators expanding dedicated bariatric wings. Reimbursement rate differentials for bariatric patients are driving capacity investments and equipment refresh timelines.
- Rehabilitation Centers:Therapy-focused settings requiring mobility aids that support active patient engagement during recovery protocols.
- Home Care:Discharge planning protocols are pushing durable medical equipment into residential settings, opening rental revenue streams and preventive maintenance contracts outside institutional procurement channels.
Hospitals command the premium tier for integrated smart-bed platforms. Home care is expanding most quickly as payors push cost-effective discharge alternatives.
Material:
Application requirements dictate material selection, with load-bearing structures demanding metallurgical performance and surface components prioritizing infection control and patient comfort.
- Steel:Cold-rolled and alloy-reinforced grades for frame structures requiring maximum distributed load ratings. Supply chain concentration in Chinese and Indian foundries creates price volatility exposure for manufacturers.
- Aluminum:Lightweight alloys for mobile equipment and components where caregiver maneuverability is prioritized over absolute load capacity.
- Plastic:High-density polymers for non-structural components, armrests, and hygiene surfaces requiring frequent cleaning protocols.
- Fabric:Medical-grade upholstery materials with pressure-relief properties and fluid-resistant coatings for seating and mattress surfaces.
Steel structures anchor the heavy-duty segment. Aluminum is gaining share fastest in mobile and transport equipment categories.
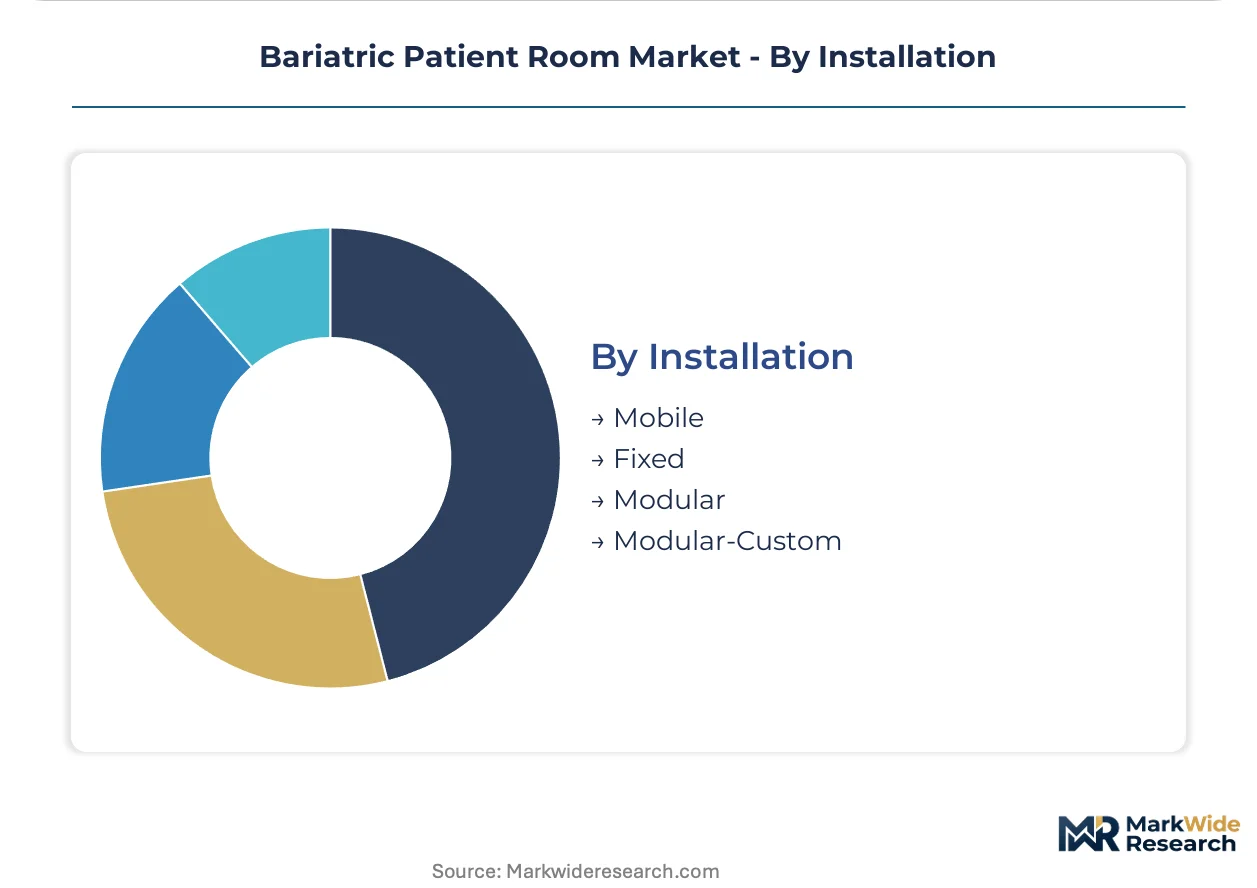
Installation:
Volume concentration tilts toward standardized configurations, with custom and modular systems capturing margin in specialized clinical environments.
- Mobile:Castor-mounted equipment for flexible room configuration and emergency transport protocols. These units dominate rental fleet inventories and facilities with variable census patterns.
- Fixed:Permanently anchored installations for high-acuity settings where equipment stability is paramount during critical care interventions.
- Modular:Standardized component systems enabling rapid deployment and simplified maintenance across multi-facility health systems.
- Modular-Custom:Configured platforms for specialized bariatric units with unique architectural constraints or integrated technology requirements.
Mobile installations dominate rental and service-based revenue models. Modular systems are where standardization benefits and procurement efficiency gains are concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States concentrate the highest absolute spending on bariatric room infrastructure, with integrated delivery networks consolidating specifications through group purchasing organizations.
United States
OSHA safe patient handling mandates in California, New York, and Illinois are compelling acute care facilities to replace manual lift protocols with motorized bariatric beds. The FDA's 510(k) clearance requirements govern all motorized bed introductions, extending product launch windows substantially. Cleveland Clinic and Mayo Clinic anchor demand for integrated smart-bed platforms with predictive maintenance capabilities.
Germany
The EU Medical Device Regulation imposes stricter clinical evidence standards for Class IIa bariatric beds seeking European market access. German hospital procurement is consolidating supplier relationships with manufacturers possessing established notified body certifications. The Baden-Württemberg medical technology cluster around Tübingen and Stuttgart hosts engineering centers developing pressure-relief surface innovations.
United Kingdom
NHS England's specialized commissioning frameworks are expanding dedicated bariatric units within acute trusts to address rising severe obesity prevalence. The Care Quality Commission's inspection regimes enforce equipment safety standards across hospital and long-term care settings. The Greater Manchester health system is standardizing bariatric room specifications across its integrated care partnership.
Japan
Japan's aging demographic and rising metabolic syndrome rates are expanding the addressable patient population for reinforced hospital equipment. The Pharmaceuticals and Medical Devices Agency maintains rigorous pre-market approval processes for motorized medical beds. Tokyo's university hospital network is piloting sensor-integrated bariatric platforms for fall prevention protocols.
Canada
Provincial health authorities in Ontario and British Columbia are adding bariatric capacity to capture higher-acuity patient transfers from rural facilities. Health Canada's medical device licensing requirements parallel FDA frameworks for motorized bed platforms. The Toronto academic hospital cluster is consolidating procurement specifications through shared services organizations.
Bariatric Patient Room Market Competitive Environment
Player mix skews toward diversified medical equipment conglomerates with integrated hospital portfolios alongside specialized rental and service providers. Market structure tilts consolidated at the premium motorized bed tier, where regulatory certification barriers and nurse call integration requirements favor established manufacturers. Two strategic archetypes dominate: integrated equipment conglomerates leveraging full hospital room portfolios, and specialized providers capturing rental and maintenance revenue outside capital procurement cycles. Competitive moves concentrate on predictive maintenance service contracts and pressure-relief surface technology licensing.
Within the integrated conglomerate tier, Stryker and Hill-Rom exemplify archetypes combining motorized bed platforms with full room integration capabilities. Stryker represents the diversified medical technology conglomerate with hospital equipment portfolios spanning surgical and patient care domains. Hill-Rom occupies a position emphasizing technology leadership through surface engineering and caregiver safety protocols. Joerns Healthcare anchors the specialized rental and service provider archetype, capturing recurring revenue through operating lease structures that lower capital barriers for smaller facilities.
| Leading Market Players |
|---|
| Stryker |
| Hill-Rom |
| Invacare Corporation |
| Arjo |
| Joerns Healthcare |
| Medline Industries |
| Nemschoff |
| Brayton |
| LINET Group |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification gates both supplier qualification and price differentiation in bariatric equipment, bifurcating the competitive landscape into certified manufacturers commanding premium contract terms and uncertified suppliers relegated to spot-market chair and commode sales. This regulatory threshold simultaneously concentrates supply among qualified producers while enabling tiered pricing based on quality management maturity.
Pricing Analysis
Cost-plus contracts with steel indexation dominate bariatric bed procurement between hospital systems and integrated manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k) cleared smart-bed platforms with predictive maintenance from basic motorized frames and non-certified imports. Pricing pressure stems from group purchasing organization consolidation forcing vendors to absorb ISO certification and nurse call integration costs. Rural hospitals and long-term care facilities exhibit highest price sensitivity, while academic medical centers prioritize clinical evidence and connectivity over unit cost.
Supply Chain Analysis
Cold-rolled steel supply from Chinese and Indian foundries creates a chokepoint that underwrites frame cost volatility across the industry. Bariatric bed manufacturing draws from specialized steel alloys, motorized articulation systems sourced from German and Japanese precision engineering clusters, and medical-grade upholstery from domestic textile converters. Single-source vulnerability concentrates in Asian metallurgical supply for load-bearing components. Distribution runs through integrated hospital equipment distributors for capital sales and specialized durable medical equipment providers for rental fleet deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified biomedical engineering talent capable of integrating legacy nurse call protocols with motorized articulation systems represents the scarcest capability in this market, constraining both manufacturer expansion and health system technology refresh timelines.
For Market Incumbents: Compound technology leadership in pressure-relief surface engineering by acquiring digital health capabilities for sensor-integrated platforms, while extending predictive maintenance service contracts to capture recurring revenue streams that third-party providers currently absorb. Defend against specialized rental providers by embedding ISO 13485 certification costs into bundled lease structures that lower capital barriers for mid-tier hospital systems. For New Entrants and Emerging Players: Anchor in home care bariatric equipment rental as the most penetrable segment, where discharge planning protocols and payor cost-containment priorities are displacing institutional procurement with residential service models. Target skilled nursing operators in United States states expanding dedicated bariatric wings under higher-reimbursement patient categories. Pursue go-to-market partnerships with durable medical equipment specialists possessing established Medicare billing infrastructure. For Investors and Strategic Acquirers: EU Medical Device Regulation post-market surveillance requirements reshape the acquisition landscape by elevating regulatory affairs capabilities to primary diligence criteria. Long-term viability over the next decade hinges on manufacturers possessing established notified body relationships and clinical evidence packages for Class IIa device pathways. Acquisition target archetype: mid-cap specialists with ISO 13485 certification and European market access. Monitor FDA 510(k) clearance timeline extensions as a signal for distressed asset opportunities among capital-constrained innovators.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates market access for motorized articulation platforms in California, New York, and Illinois health systems. |
| CE Marking Under EU MDR | Unlocks procurement consolidation with German hospital systems demanding notified body certification. |
| Hospital System Partnership | Secures multi-year GPO contracts with integrated delivery networks standardizing bariatric room specifications. |
| Software Companion Development | Enables predictive maintenance revenue streams through sensor-integrated bed platforms with remote monitoring. |
| Reimbursement Strategy | Aligns equipment financing with Medicare bariatric surgery coverage expansion and inpatient stay policies. |
Study Parameters
A spread of perspectives from hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and durable medical equipment rental operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, hospital procurement records, CMS Medicare reimbursement schedules, and OSHA safe patient handling enforcement data. Bottom-up equipment unit economics triangulated against top-down health system capital expenditure patterns across the analysis window.
Segmentation dimensions modeled include product type complexity, end-user capital intensity, material metallurgical grade, and installation mobility requirements. CAGRs were derived from equipment replacement cycle analysis, reimbursement policy trajectory, and regulatory mandate implementation timelines. Forecast inputs incorporated bariatric surgery volume projections, skilled nursing facility capacity expansion plans, and steel price volatility indices.
Decision-makers should treat outputs as directional under assumptions of steady OSHA enforcement continuity and stable Medicare reimbursement for bariatric procedures; material deviation in either policy domain would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR transition timelines and group purchasing organization consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
North America Bariatric Surgery Devices Market