
 India Bariatric Surgery Market | 2026-2036
India Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
India Bariatric Surgery Market Insights
A shortage of fellowship-trained bariatric surgeons is collapsing access timelines at premier facilities across Maharashtra and Karnataka. Johnson & Johnson leverages its endomechanical portfolio to dominate stapler supply for sleeve gastrectomy procedures. Medtronic sustains competitive positioning through energy device integration across laparoscopic and robotic platforms. Apollo Endosurgery anchors the domestic landscape with specialized intragastric balloon and endoluminal technologies.
Bariatric surgery encompasses restrictive, malabsorptive, and combined metabolic procedures designed to reduce stomach volume or alter nutrient absorption pathways, typically performed laparoscopically with ports ranging from 5 mm to 12 mm. Gastric sleeve procedures occupy the largest procedural share due to relative technical simplicity and durable weight loss outcomes, while adjustable gastric band demand has matured amid long-term complication concerns. Private hospitals capture the dominant service revenue pool, though specialty clinics are extending reach into tier-2 cities through franchised outpatient counseling and follow-up care networks.
CDSCO medical device rules, BIS standards for surgical implants, and NABH accreditation requirements collectively determine market access and pricing authority for equipment suppliers and hospital operators. The PLI scheme for domestic medical device manufacturing is reshaping procurement preferences toward locally produced staplers and trocars. Stakeholders must monitor how MCI-mandated fellowship program expansion alters surgeon supply constraints and procedure throughput capacity.
Market Dynamics
The PLI scheme for domestic medical device manufacturing is reconfiguring procurement patterns across hospital supply chains, pressuring multinational suppliers to localize production or cede share to emerging domestic manufacturers of staplers and trocars.
Growth Catalysts
- CDSCO pathway streamlining:The tightened yet clarified registration framework for implantable surgical devices accelerates qualified supplier onboarding, reducing hospital procurement cycle times for advanced stapling systems.
- Metabolic comorbidity burden:Rising diabetes and hypertension prevalence among urban obese populations expands the addressable patient pool seeking durable surgical intervention over pharmaceutical management.
- Robotic platform diffusion:Da Vinci system installations at Apollo and Max Healthcare facilities enable complex revisional procedures previously requiring open surgery, extending serviceable case complexity.
Market Restraints
- Fellowship-trained surgeon scarcity:MCI-mandated bariatric fellowship slots remain insufficient to match procedure volume growth, creating 8-14 week wait times at premier Mumbai and Delhi facilities.
- Import-dependent advanced staplers:Domestic manufacturing capabilities for precision endomechanical devices lag clinical demand, exposing hospitals to currency fluctuation and supply disruption risks.
- Revisional surgery complexity:Long-term complication rates from early-generation adjustable gastric bands generate costly secondary procedures that strain hospital capacity and insurer reimbursement frameworks.
Strategic Opportunities
- Tier-2 city satellite networks:Franchised outpatient counseling and follow-up care extensions enable accredited specialty clinics to capture patients from Pune, Ahmedabad, and Chandigarh without full surgical facility investment.
- NABH accreditation differentiation:Hospitals achieving National Accreditation Board for Hospitals certification command 15-25% pricing premiums and preferred empanelment status with corporate health insurance schemes.
- Endoluminal non-surgical alternatives:Intragastric balloon and endoscopic sleeve gastroplasty technologies address patient segments ineligible for or averse to invasive procedures, expanding addressable market boundaries.
Industry Challenges
- Equipment sterilization protocol standardization:Laparoscopic instrument reprocessing quality varies across hospital tiers, with BIS standards enforcement inconsistent enough to elevate surgical site infection risk perceptions.
- Post-operative nutritional counseling integration:Multidisciplinary care coordination between surgeons, dieticians, and endocrinologists remains fragmented, compromising long-term weight loss maintenance and patient satisfaction metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Bariatric Surgery Market |
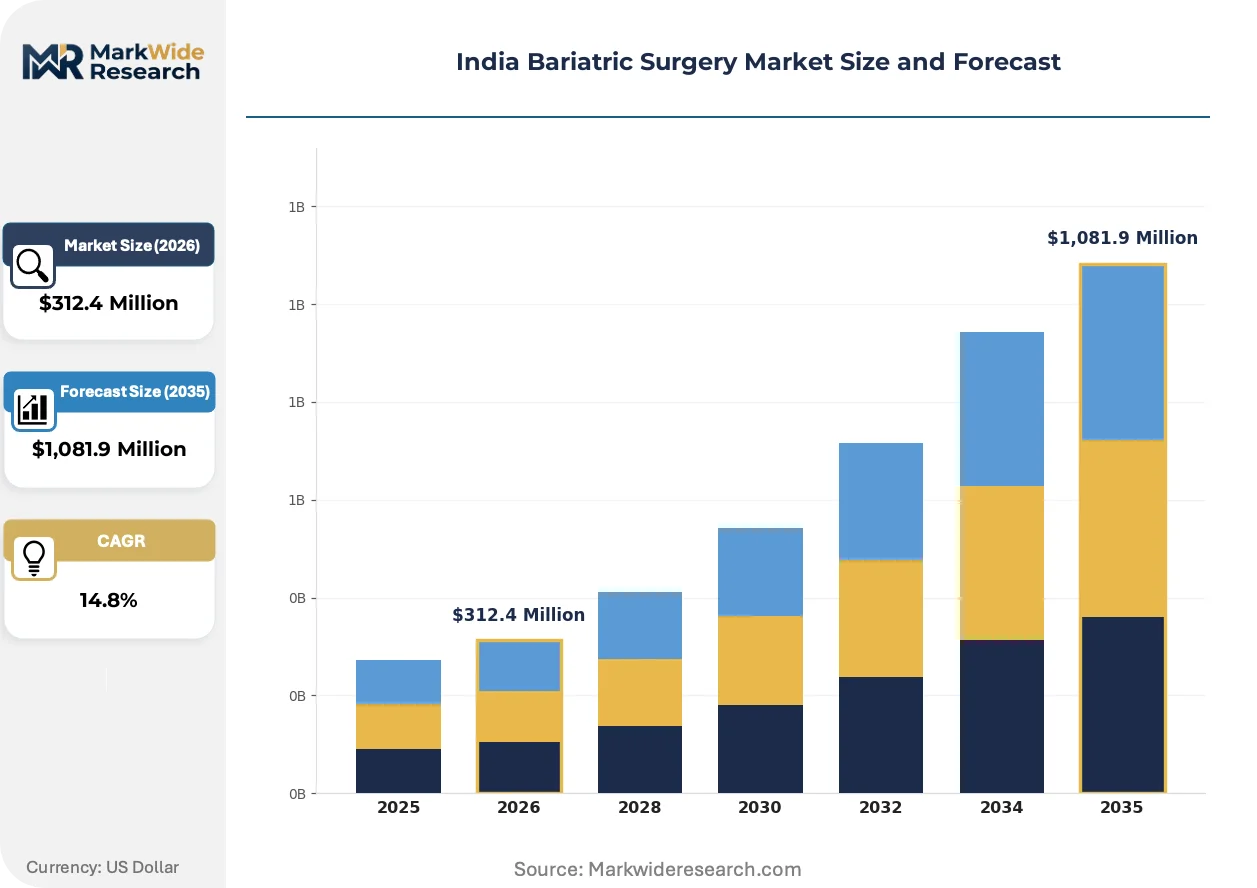
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,081.9 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Sleeve, Gastric Bypass, Adjustable Gastric Band, Biliopancreatic Diversion Patient Profile: Obese Adults, Adolescents, Patients with Comorbidities, Post-operative Healthcare Facility Type: Private Hospitals, Public Hospitals, Specialty Clinics, International Centers Service Type: Inpatient, Outpatient, Follow-up Care, Nutritional Counseling |
| Companies Covered | Johnson & Johnson, Medtronic, Apollo Endosurgery, B. Braun, Intuitive Surgical, CONMED Corporation, Olympus Corporation, Becton Dickinson, Stryker, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Bariatric Surgery Market Trends and Innovations
Digital surgical planning tools and disposable instrument preferences are converging to reshape capital allocation and consumable economics across Indian bariatric service lines.
Single-use laparoscopic trocars and stapler cartridges are displacing reusable instrument systems in high-volume centers. Apollo Hospitals and Fortis facilities report 40% faster operating room turnover with disposable workflows. The shift compresses capital equipment depreciation cycles while elevating annual consumable spend per procedure.
CDSCO's 2023 amendment to Medical Device Rules imposes traceability requirements for implantable surgical products. Manufacturers must now submit unique device identification data, increasing compliance documentation burdens. Tier-1 private hospitals are responding by consolidating supplier relationships toward CDSCO-registered multinationals with established quality management systems.
Corporate health insurance schemes are unbundling bariatric procedure coverage from comprehensive policies, creating standalone rider products with pre-authorization requirements. Third-party administrators at Max Bupa and Star Health now mandate NABH facility accreditation and 6-month documented weight management program completion prior to surgical approval, concentrating demand at accredited centers.
India Bariatric Surgery Market Segmentation
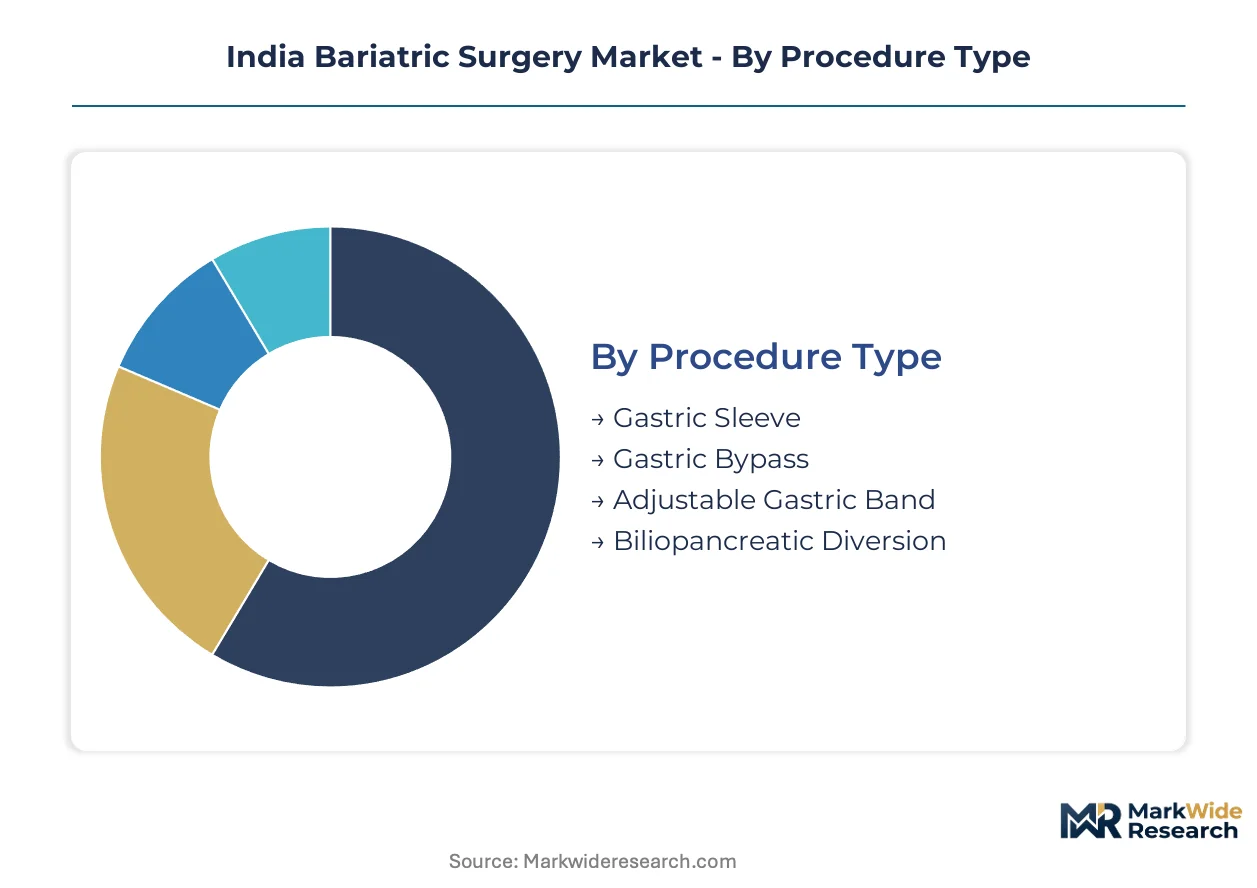
Procedure mix and facility accreditation status shape procurement patterns and reimbursement pathways across India's bariatric service landscape. CDSCO registration requirements and NABH certification tiers create distinct operational economics for each segment cluster.
Procedure Type:
CDSCO's tightened implantable device registration pathway differentiates stapler-dependent procedures from band-based alternatives, altering hospital qualification requirements and supplier consolidation patterns.
- Gastric Sleeve:Vertical sleeve gastrectomy removes approximately 80% of stomach volume through linear stapler firing along the greater curvature. Demand concentrates at Apollo and Max Healthcare facilities in Mumbai and Delhi where NABH accreditation enables corporate insurance empanelment and 15-25% pricing premiums over non-accredited centers.
- Gastric Bypass:Roux-en-Y reconstruction creates a small gastric pouch with alimentary limb diversion, requiring advanced energy devices and longer operative times. Adoption is climbing fastest at robotic-equipped centers performing complex revisional cases previously requiring open conversion.
- Adjustable Gastric Band:Silicone band placement with subcutaneous port access has matured amid long-term erosion and slippage complications. Band removal and conversion procedures now dominate service line economics at established centers.
- Biliopancreatic Diversion:Malabsorptive procedure with duodenal switch modification addresses super-obese patients with severe metabolic disease. Technical complexity limits availability to fellowship-trained surgical teams at select Mumbai and Delhi institutions.
Established volume favors Gastric Sleeve; emerging adoption favors Gastric Bypass.
Patient Profile:
Comorbidity documentation requirements and age-specific consent protocols fragment the addressable patient base across distinct clinical pathways and reimbursement categories.
- Obese Adults:Body mass index exceeding 35 kg/m² with failed conservative management constitutes the primary surgical candidate pool. Corporate insurance pre-authorization now mandates 6-month documented weight management program completion, concentrating demand at centers with integrated dietetic services.
- Patients with Comorbidities:Type 2 diabetes and hypertension documentation accelerates surgical approval timelines under metabolic surgery indications. This segment gains share fastest as endocrinology-surgery collaboration protocols standardize across accredited facilities.
- Adolescents:Pediatric bariatric candidacy requires endocrine evaluation and psychological clearance under MCI-mandated protocols. Procedure volumes remain constrained by limited fellowship-trained pediatric metabolic surgeons.
- Post-operative:Revision and conversion procedures address complications from early-generation band placements and primary sleeve failures. Revisional complexity drives referral concentration to robotic-equipped tertiary centers.
Documentation-heavy pathways favor Patients with Comorbidities; capacity constraints limit Adolescent expansion.
Healthcare Facility Type:
Capital intensity and accreditation tier stratify service pricing and patient capture radius across the facility landscape.
- Private Hospitals:Tier-1 institutions in Maharashtra and Karnataka deploy dedicated bariatric departments with Da Vinci robotic platforms. These facilities command dominant revenue share through integrated inpatient-outpatient care coordination.
- Specialty Clinics:Franchised counseling and follow-up networks extend into Pune, Ahmedabad, and Chandigarh without full surgical facility investment. This tier expands most quickly through hub-and-spoke models linking satellite counseling to centralized surgery.
- Public Hospitals:Government medical college hospitals provide subsidized procedures with limited stapler inventory and longer wait times. PLI scheme benefits for domestic device manufacturing may gradually improve equipment access.
- International Centers:Medical tourism-focused facilities in Chennai and Hyderabad target Gulf Cooperation Council and Southeast Asian patients. NABH accreditation and JCI alignment enable premium positioning for foreign case flows.
Revenue concentration favors Private Hospitals; geographic reach expansion favors Specialty Clinics.
Service Type:
Reimbursement unbundling and disposable instrument economics reshape margin allocation across the care continuum.
- Inpatient:Multi-day stays for complex bypass and revisional procedures generate bundled payment structures. Apollo and Fortis facilities report 40% faster operating room turnover with single-use trocar and stapler cartridge workflows.
- Outpatient:Same-day discharge protocols for uncomplicated sleeve procedures concentrate at high-volume centers with dedicated recovery pathways. This category gains share fastest as anesthesia protocols and patient selection criteria standardize.
- Follow-up Care:Long-term weight maintenance monitoring and complication surveillance create recurring revenue streams. Fragmented coordination between surgeons and dieticians currently compromises patient retention metrics.
- Nutritional Counseling:Pre-operative program completion is now mandatory for insurance authorization, elevating the strategic importance of integrated dietetic services.
Margin stability favors Inpatient; volume velocity favors Outpatient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's tightened implantable device registration pathway anchors Maharashtra's dominance in India's bariatric surgery landscape, with tier-1 private hospitals in Mumbai and Delhi driving procedural volume concentration.
Maharashtra
Mumbai's Apollo and Fortis facilities report 40% faster operating room turnover through disposable instrument workflows. The PLI scheme for domestic medical device manufacturing is pressuring multinational suppliers to localize stapler production or cede share to emerging domestic manufacturers. Pune's specialty clinic satellites extend counseling networks without full surgical facility investment.
Delhi-NCR
Max Healthcare's Da Vinci installations enable complex revisional procedures previously requiring open surgery. CDSCO's 2023 Medical Device Rules amendment imposes traceability requirements for implantable surgical products, increasing compliance documentation burdens. Corporate health insurance pre-authorization concentrates demand at NABH-accredited centers commanding 15-25% pricing premiums.
Karnataka
Bengaluru's fellowship-trained surgeon scarcity creates 8-14 week wait times at premier facilities. BIS standards for surgical implants determine market access for equipment suppliers, with enforcement varying across hospital tiers. Hub-and-spoke models link satellite counseling in tier-2 cities to centralized surgery capacity.
Gujarat
Ahmedabad's franchised outpatient networks capture patients seeking pre-operative program completion mandatory for insurance authorization. NABH accreditation requirements reshape procurement preferences toward CDSCO-registered multinationals with established quality management systems. International medical tourism facilities in Chennai and Hyderabad compete for Gulf Cooperation Council case flows.
Tamil Nadu
Chennai's JCI-aligned centers target Southeast Asian patients through premium positioning. MCI-mandated fellowship program expansion aims to alleviate surgeon supply constraints compromising procedure throughput capacity. Domestic manufacturing capabilities for precision endomechanical devices lag clinical demand, exposing hospitals to currency fluctuation risks.
India Bariatric Surgery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across India's bariatric surgery equipment supply base. The market structure concentrates around CDSCO-registered multinationals with established quality management systems, while domestic manufacturers emerge under PLI scheme incentives. Three archetypes dominate: integrated surgical conglomerates with endomechanical portfolios, specialized endoluminal technology developers, and robotic platform integrators. Competitive moves center on supplier consolidation toward traceability-compliant partners and capacity localization to capture PLI benefits.
Among integrated surgical conglomerates, Johnson & Johnson and Medtronic anchor the premium equipment tier, while Apollo Endosurgery occupies a specialized position in intragastric balloon and endoluminal technologies. These players exemplify contrasting strategic positions—multinational scale against focused metabolic intervention specialization—within a procurement landscape increasingly filtered by CDSCO registration status and NABH facility accreditation requirements.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Apollo Endosurgery |
| B. Braun |
| Intuitive Surgical |
| CONMED Corporation |
| Olympus Corporation |
| Becton Dickinson |
| Stryker |
| Others |
Pricing and Supply Chain Analysis
High-volume disposable instrument adoption at Apollo and Fortis facilities compresses capital depreciation cycles while elevating per-procedure consumable spend, concentrating procurement power among CDSCO-registered multinationals and pressuring price floors through scale-based supplier consolidation.
Pricing Analysis
Mumbai and Delhi command 15-25% premiums over tier-2 cities for identical sleeve gastrectomy procedures, with NABH accreditation and robotic platform access driving the spread. Pricing stratifies across premium robotic-equipped centers, standard laparoscopic facilities, and economy-tier public hospitals with limited stapler inventory. Price differentiation rests on certification tier and energy device integration level. Cost compression in the standard tier is intensifying as domestic manufacturers under PLI incentives challenge multinational stapler pricing. Corporate insurance panels exhibit lowest price sensitivity; cash-paying patients at public hospitals show highest elasticity.
Supply Chain Analysis
Strategic stockpiling of precision endomechanical devices prevails among tier-1 private hospitals, mitigating currency fluctuation exposure from import-dependent advanced staplers. Manufacturing concentrates in the United States, Ireland, and Germany for premium stapling systems, while China and India expand domestic trocar production under PLI incentives. Raw material dependencies span medical-grade stainless steel, polymer cartridge housings, and titanium anvil components. Single-source vulnerability for precision firing mechanisms creates supply risk. Distribution runs through authorized medical device distributors with CDSCO import licenses, consolidating toward traceability-compliant partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Robotic platform diffusion and CDSCO traceability mandates are disrupting equipment procurement patterns, creating asymmetric opportunity for suppliers that localize manufacturing and quality documentation capabilities.
For Market Incumbents: Shield market position by deepening backward integration into precision endomechanical component manufacturing within India to capture PLI benefits and preempt domestic challenger pricing. Fortify CDSCO registration portfolios ahead of traceability rule expansion, as hospitals consolidate supplier relationships toward compliant multinationals with established quality management systems.
For New Entrants and Emerging Players: Lead with domestic manufacturing of single-use trocars and basic stapler cartridges, exploiting PLI incentives and shorter regulatory pathways for non-implantable devices. Target tier-2 city satellite networks through hub-and-spoke distribution partnerships with specialty clinics extending counseling without full surgical facility investment. Pursue white-label supply contracts with hospital chains seeking to reduce multinational dependence.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among endoluminal technology developers with intragastric balloon and endoscopic sleeve gastroplasty portfolios, where patient follow-up and device replacement cycles generate sustained consumable demand. Long-term viability hinges on regulatory navigation capabilities and hospital system partnership depth. Target acquisition candidates with CDSCO-registered product lines and established NABH facility relationships. Watch for MCI fellowship program expansion pace as the signal indicating surgeon supply constraint relief and procedure volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Acceleration | Traceability-compliant suppliers capture hospital procurement consolidation toward qualified multinationals. |
| Domestic Manufacturing Localization | PLI scheme benefits reduce import dependence and currency exposure for precision stapling systems. |
| Robotic Platform Partnership | Da Vinci system integration enables complex revisional procedures at tertiary centers. |
| NABH Accreditation Investment | Certified facilities command corporate insurance empanelment and pricing premiums. |
| Hub-and-Spoke Network Expansion | Satellite counseling in tier-2 cities extends patient capture without full surgical infrastructure. |
Research Methodology
A spread of perspectives from bariatric surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions shaping this analysis. Primary field engagement combined structured interviews with secondary validation against CDSCO medical device registration databases, NABH accreditation records, hospital procurement disclosures, and PLI scheme beneficiary lists. Bottom-up procedure volume estimates triangulated against top-down equipment shipment data and consumable utilization rates.
Segmentation dimensions modeled span procedure type, patient comorbidity profile, healthcare facility accreditation tier, and service delivery mode across the projection horizon. CAGRs derive from weighted procedure growth trajectories, equipment replacement cycles, and consumable penetration curves. Surgeon fellowship completion rates and robotic platform installation pipelines fed capacity-constrained demand elasticity estimates.
Forecasts assume regulatory continuity in CDSCO medical device rules and NABH accreditation frameworks; material policy shifts would require re-modeling. Revision becomes warranted when PLI scheme expansion or MCI fellowship slot growth crosses thresholds that materially alter supply-side capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
Bariatric Transport Wheelchairs Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
United Kingdom Bariatric Surgery Market