
 Brazil Bariatric Surgery Market | 2026-2036
Brazil Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Bariatric Surgery Market Outlook
ANVISA's streamlined registration for Class III surgical devices is realigning the cost-of-entry calculus for device manufacturers seeking commercial traction. Medtronic leverages its broad laparoscopic portfolio to sustain institutional contracts across Brazil's largest hospital networks. Johnson & Johnson (Ethicon Inc) anchors its position through deep specialization in stapling and energy platforms tailored to bariatric workflows. Intuitive Surgical Inc competes by extending robotic-assisted surgical system placements into high-volume private surgical centers.
Brazil bariatric surgery encompasses metabolic and weight-loss interventions performed via open, laparoscopic, or robotic-assisted approaches, typically involving gastric restriction, malabsorption, or combined physiological mechanisms to achieve sustained reduction in body mass index. The primary purpose is treating morbid obesity and related comorbidities including type 2 diabetes, hypertension, and obstructive sleep apnea. Sleeve gastrectomy dominates procedure type volumes due to its technical simplicity and favorable complication profile relative to gastric bypass. Private hospitals and specialized clinics capture the dominant margin pool within hospital type segmentation, while public hospitals handle the largest absolute patient volumes under Brazil's unified health system.
ANVISA governs medical device registration and post-market surveillance, enforcing Good Manufacturing Practice standards that shape product quality benchmarks and market access timelines. The Brazilian Ministry of Health's incorporation guidelines for surgical technologies determine reimbursement eligibility and public procurement priorities for bariatric procedures. Stakeholders must monitor how ANVISA's pending alignment with International Medical Device Regulators Forum standards reshapes conformity assessment requirements for imported devices.
Market Dynamics
ANVISA's compression of Class III device registration timelines is redistributing competitive advantage toward manufacturers with established Brazilian regulatory infrastructure, accelerating market entry velocity for laparoscopic and robotic surgical platforms.
Growth Catalysts
- Southeast Region Insurance Penetration:Private health coverage density in São Paulo and Rio de Janeiro states concentrates surgical demand where reimbursement infrastructure supports elective metabolic procedures.
- ANVISA Streamlined Pathways:The regulator's updated medical device registration framework reduces approval duration for imported laparoscopic instruments, lowering time-to-revenue for international manufacturers.
- Sleeve Gastrectomy Standardization:Technical simplicity relative to gastric bypass procedures expands the addressable surgeon pool, enabling volume growth in mid-tier private hospital networks.
Market Restraints
- Specialist Surgeon Concentration:Bariatric fellowship-trained physicians cluster disproportionately in São Paulo and Rio de Janeiro, constraining service expansion into Brazil's North and Northeast regions.
- Public Sector Reimbursement Caps:Brazil's unified health system reimbursement rates for metabolic surgery under SUS protocols limit procedure economics in publicly administered facilities.
- Imported Device Cost Structure:Laparoscopic staplers and energy platforms sourced from North American and European suppliers carry foreign exchange exposure that amplifies procurement volatility.
Strategic Opportunities
- Northeast Region Undersupply:Pernambuco and Bahia states exhibit obesity prevalence comparable to the Southeast with minimal bariatric surgical infrastructure, creating greenfield expansion potential.
- Robotic-Assisted Platform Adoption:High-volume private surgical centers in Curitiba and Belo Horizonte represent untapped placement opportunities for next-generation surgical systems.
- Telemedicine Pre-Operative Pathways:Remote patient screening and nutritional counseling protocols reduce geographic barriers to specialist access in Brazil's interior municipalities.
Industry Challenges
- Multidisciplinary Team Scarcity:Certified bariatric nutritionists and mental health specialists required for comprehensive metabolic programs remain concentrated in major metropolitan corridors.
- Post-Market Surveillance Compliance:ANVISA's adverse event reporting obligations for Class III surgical devices impose documentation burdens that strain smaller clinic administrative capacity.
- Equipment Standardization Across Networks:Heterogeneous laparoscopic instrument specifications between hospital systems complicate surgeon mobility and training program design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Bariatric Surgery Market |
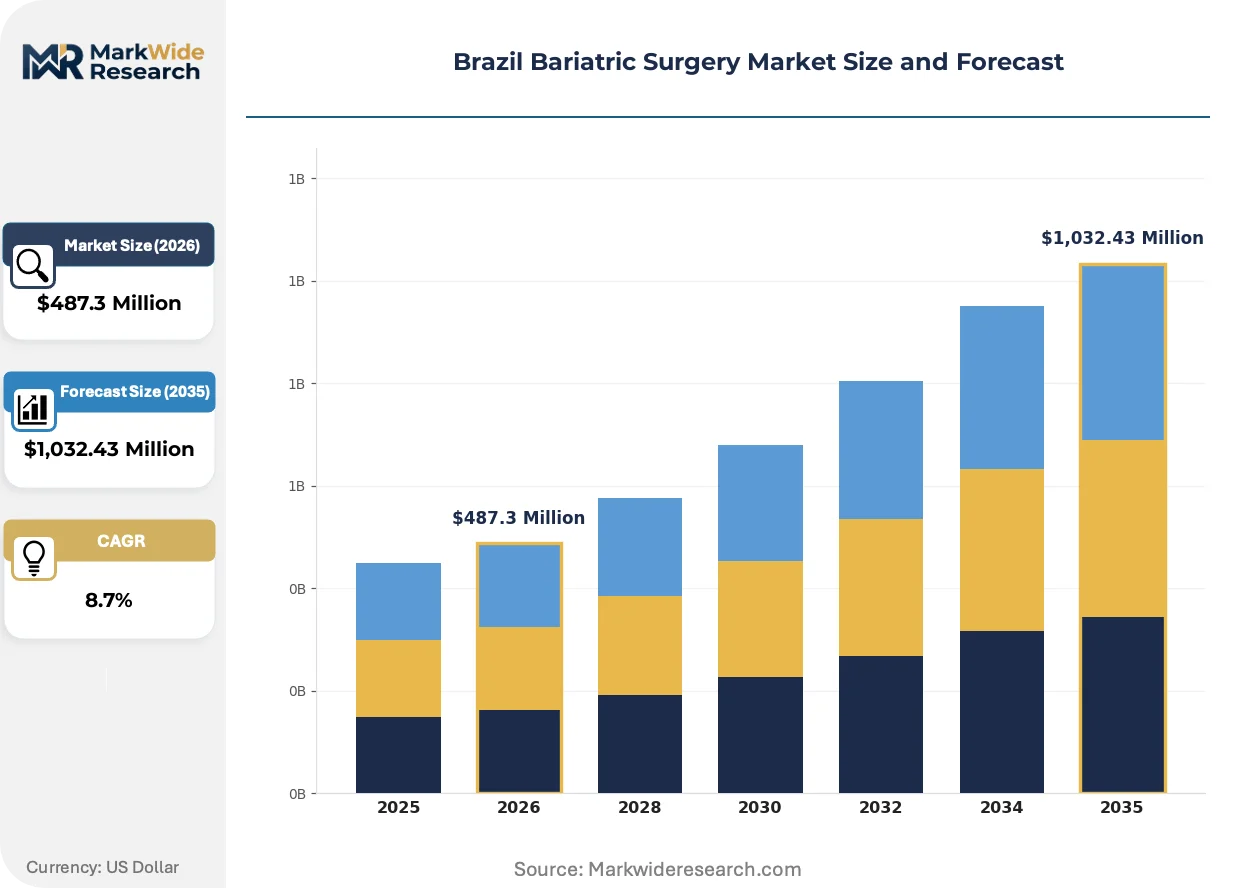
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion Patient Demographics: Adults, Adolescents, Seniors, Obese Patients Hospital Type: Public Hospitals, Private Hospitals, Specialized Clinics, Surgical Centers Geographical Distribution: Urban Areas, Rural Areas, Coastal Regions, Inland |
| Companies Covered | B. Braun Melsungen AG, TransEnterix, Medtronic, EziSurg, USGI Medical, Johnson & Johnson (Ethicon Inc), Spatz FGIA Inc, Intuitive Surgical Inc, Apollo Endosurgery Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Bariatric Surgery Market Strategic Shifts
Robotic surgical platforms and single-incision techniques are reconfiguring the technical boundary between high-volume centers and community hospitals, compressing the traditional hierarchy of metabolic surgical capability.
Single-port laparoscopic systems are modularizing access to reduced-scar bariatric procedures. Private hospital networks in São Paulo deploy these platforms to differentiate service offerings within saturated metropolitan markets. The technology is modularizing competitive positioning by enabling mid-tier facilities to match outcomes previously associated with academic medical centers.
ANVISA's pending alignment with International Medical Device Regulators Forum standards is recalibrating conformity assessment requirements for imported surgical staplers. Brazilian distributors must now prepare technical documentation packages that satisfy both national and emerging international benchmarks. High-volume importers are responding by consolidating supplier relationships to reduce compliance fragmentation across product portfolios.
Patient selection protocols are shifting toward metabolic syndrome severity rather than body mass index thresholds alone. Endocrinology referral networks in Rio de Janeiro and Porto Alegre are displacing traditional primary-care gatekeeping for surgical candidacy determination. This behavioral pivot is most visible in privately insured populations where diabetes remission outcomes drive procedure preference over weight reduction metrics.
Brazil Bariatric Surgery Market Segmentation
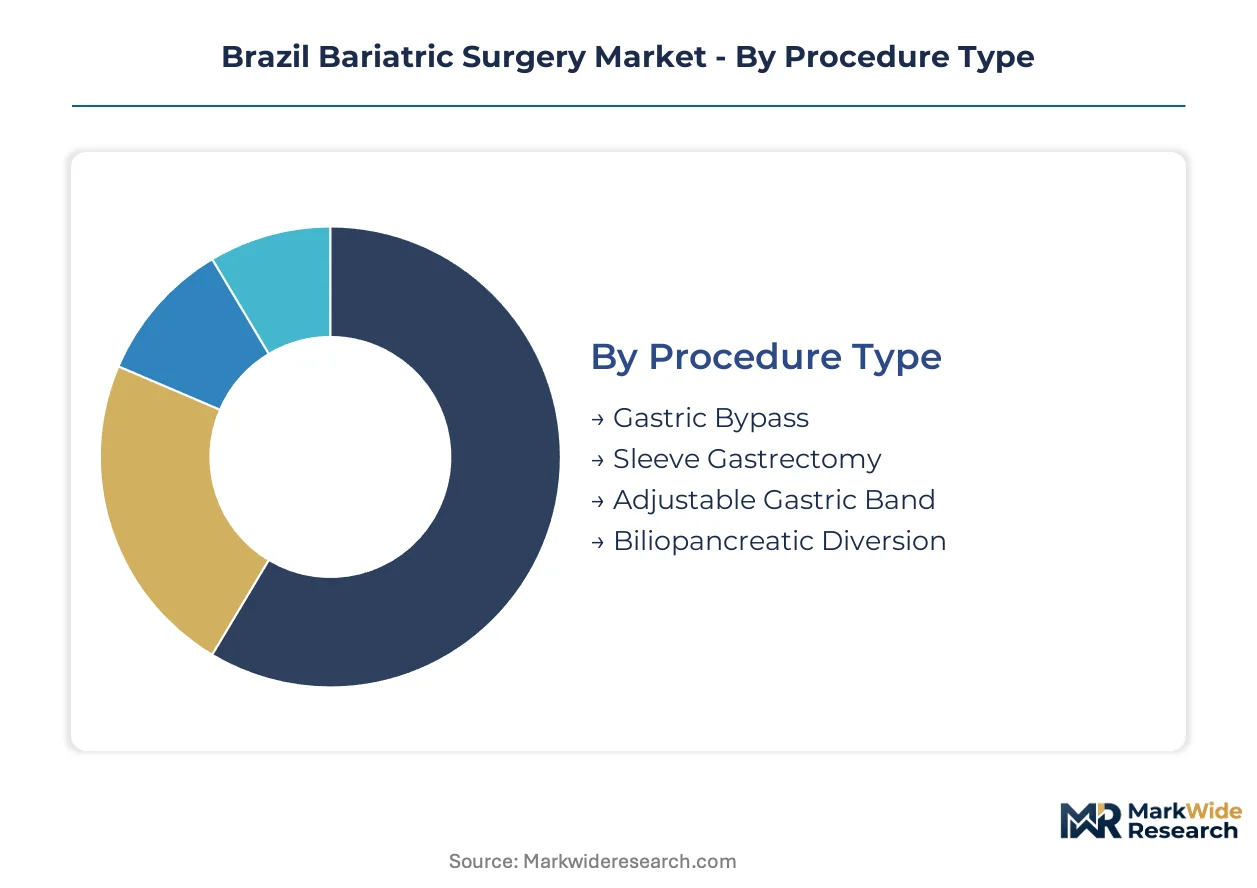
Bariatric procedure economics diverge sharply across technical complexity and reimbursement pathways. Patient risk stratification and facility certification tiers further fragment addressable demand within Brazil's federated healthcare system.
Procedure Type:
Standardization pressure from ANVISA and payer consolidation is compressing the customization spectrum toward technically reproducible interventions with established safety profiles.
- Sleeve Gastrectomy:Partial gastric resection creates a tubular stomach pouch via laparoscopic stapling platforms. São Paulo private hospital networks concentrate demand here due to reduced operative time and lower leak rates relative to malabsorptive alternatives. Payer preference for same-day discharge eligibility accelerates adoption.
- Gastric Bypass:Roux-en-Y reconstruction combines restrictive and malabsorptive mechanisms through gastrojejunal anastomosis. Rio de Janeiro academic medical centers anchor volume for diabetic patients seeking metabolic remission outcomes. Technical complexity limits deployment to fellowship-trained surgical teams.
- Adjustable Gastric Band:Silicone band placement with subcutaneous port access for saline adjustment. Declining utilization in Brazil follows international reoperation rate concerns.
- Biliopancreatic Diversion:Extended malabsorptive reconstruction with duodenal switch modification. Restricted to super-obese cohorts in tertiary referral centers.
Most installed capacity flows through Sleeve Gastrectomy. Expansion is steepest in Gastric Bypass among metabolic surgery programs.
Patient Demographics:
Cost tier stratification separates publicly funded universal access from private insurance pre-authorization requirements across age and comorbidity bands.
- Adults:Dominant volume cohort aged 18-65 with private plan coverage or SUS eligibility. Southeast region obesity prevalence drives regional concentration.
- Obese Patients:BMI-defined surgical candidacy with comorbidity documentation requirements. Endocrinology referral networks in Belo Horizonte and Curitiba shape pre-operative pathways.
- Adolescents:Strict metabolic indication thresholds under Brazilian pediatric surgery society guidelines. Limited to specialized academic programs.
- Seniors:Age-adjusted risk scoring prioritizes cardiovascular optimization. Geriatric anesthesia capabilities constrain site-of-service options.
Procedure volume concentrates in Adults. Adolescents are gaining share fastest among emerging metabolic surgery programs.
Hospital Type:
Margin structure separates capital-intensive robotic platforms in private networks from high-volume, standardized laparoscopic workflows in public facilities.
- Private Hospitals:Multi-specialty networks with dedicated bariatric service lines and comprehensive metabolic programs. São Paulo and Rio de Janeiro states capture dominant revenue pools.
- Public Hospitals:SUS-administered facilities handling largest absolute patient volumes with reimbursement-constrained economics. Waiting list management drives triage protocols.
- Specialized Clinics:Ambulatory-focused models with streamlined pre-operative pathways. Rapid patient turnover compensates for lower per-case reimbursement.
- Surgical Centers:Standalone facilities with focused laparoscopic infrastructure. ANVISA certification requirements limit geographic distribution.
Revenue generation concentrates in Private Hospitals. Patient volume expansion is steepest in Specialized Clinics.
Geographical Distribution:
Supply concentration in coastal metropolitan corridors creates access gradients that telemedicine screening protocols are beginning to compress.
- Urban Areas:São Paulo, Rio de Janeiro, Belo Horizonte, and Curitiba metropolitan zones concentrate fellowship-trained surgeons and robotic platforms. Insurance density supports elective procedure economics.
- Coastal Regions:Secondary cities with tourism-linked private health infrastructure. Seasonal demand patterns from medical travel segments.
- Inland:Interior municipalities dependent on mobile surgical teams and telemedicine pre-operative pathways. ANVISA logistics for device replenishment complicate inventory management.
- Rural Areas:Minimal procedural infrastructure with referral-dependent access to urban centers. SUS transportation subsidies partially offset geographic barriers.
Installed surgical capacity concentrates in Urban Areas. Telemedicine-enabled expansion is steepest in Inland municipalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained bariatric surgeons cluster disproportionately in Brazil's Southeast, creating surgical capacity gradients that telemedicine protocols and mobile surgical teams now attempt to flatten.
São Paulo
Private health insurance density and metabolic surgery program maturation concentrate demand in São Paulo state's hospital networks. ANVISA's streamlined Class III device registrations accelerate laparoscopic platform procurement for multi-specialty facilities. São Paulo metropolitan hospitals anchor robotic-assisted surgical system placements and sleeve gastrectomy standardization.
Rio de Janeiro
Academic medical centers in Rio de Janeiro specialize in gastric bypass procedures for diabetic patients seeking metabolic remission outcomes. The Brazilian Ministry of Health's incorporation guidelines shape public procurement priorities for SUS-administered facilities. Tijuca and Barra da Tijuca surgical corridors concentrate fellowship-trained teams and comprehensive metabolic programs.
Minas Gerais
Belo Horizonte's private hospital networks represent untapped placement opportunities for next-generation robotic platforms. State-level reimbursement negotiations under Brazil's federated health system determine elective procedure economics. Contagem and Nova Lima municipalities exhibit expanding bariatric service line development.
Rio Grande do Sul
Porto Alegre endocrinology referral networks displace traditional primary-care gatekeeping for surgical candidacy determination. ANVISA's Good Manufacturing Practice standards shape product quality benchmarks for imported stapling devices. Caxias do Sul and Pelotas secondary cities develop ambulatory-focused metabolic surgery models.
Bahia
Pernambuco and Bahia states exhibit obesity prevalence comparable to the Southeast with minimal bariatric surgical infrastructure, creating greenfield expansion potential. SUS transportation subsidies partially offset geographic barriers for rural patient referral. Salvador metropolitan hospitals pilot telemedicine pre-operative pathways to reduce specialist access constraints.
Brazil Bariatric Surgery Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Brazil's bariatric surgery market, producing a tiered structure where scale-driven device manufacturers anchor institutional contracts while niche innovators occupy procedural sub-segments. Market concentration reflects regulatory entry barriers rather than pure commercial scale, with ANVISA certification requirements filtering participant quality. Three archetypes dominate: diversified medical technology conglomerates with broad laparoscopic portfolios, robotic surgical system specialists, and focused metabolic device innovators. Competitive dynamics center on strategic partnerships with private hospital networks and geographic expansion into underserved Northeast corridors.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson (Ethicon Inc) exemplify scale-driven archetypes with established Brazilian regulatory infrastructure and institutional contract depth. Intuitive Surgical Inc occupies a distinct position within robotic-assisted surgical platforms, representing the capital-intensive automation tier. These three anchors illustrate how manufacturer competitive positioning diverges across technical specialization vectors rather than converging on undifferentiated scale.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| TransEnterix |
| Medtronic |
| EziSurg |
| USGI Medical |
| Johnson & Johnson (Ethicon Inc) |
| Spatz FGIA Inc |
| Intuitive Surgical Inc |
| Apollo Endosurgery Inc |
| Others |
Value Chain & Pricing Dynamics
Device certification tiers under ANVISA's Class III framework bifurcate Brazil's bariatric surgery market into premium imported platforms and domestically registered alternatives, with this divergence manifesting in both procurement costs and distributor inventory strategies across São Paulo and Rio de Janeiro hospital networks.
Pricing Analysis
Bundled service contracts dominate private hospital procurement while unbundled instrument pricing prevails in public SUS facilities. Three-tier pricing structure across premium robotic systems, standard laparoscopic platforms, and economy reusable instruments separates academic medical centers from mid-tier networks from municipal hospitals. Pricing pressure stems from foreign exchange volatility affecting North American and European device imports. Public sector buyers exhibit highest price sensitivity due to reimbursement caps, while premium private networks prioritize outcome metrics over unit cost.
Supply Chain Analysis
ANVISA Good Manufacturing Practice certification gates entry for stapling devices and energy platforms sourced from the United States, Germany, and Switzerland. Titanium alloy staples, polymer trocars, and electrosurgical generators constitute critical input dependencies. Single-source vulnerability concentrates in robotic system console manufacturing. Distribution runs through authorized Brazilian distributors with regional warehousing in São Paulo state.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's bariatric surgery market compounds steadily as obesity prevalence and private insurance penetration create durable procedure demand across the Southeast region.
For Market Incumbents: Anchor institutional contracts through exclusive stapling platform agreements with São Paulo hospital networks facing emerging robotic-assisted competition. Deepen backward integration into local device servicing capabilities to offset foreign exchange exposure on imported components. Prioritize ANVISA certification maintenance as regulatory alignment with International Medical Device Regulators Forum standards intensifies documentation requirements. For New Entrants and Emerging Players: Specialized clinics in Pernambuco and Bahia states represent the most penetrable channel partner type for laparoscopic platform distribution. Telemedicine-enabled pre-operative pathways offer a direct go-to-market angle to bypass specialist surgeon scarcity in Brazil's Northeast corridor. Target mid-tier private hospital networks in Belo Horizonte seeking robotic system alternatives. For Investors and Strategic Acquirers: Consolidation pressure builds where ANVISA regulatory infrastructure creates moats around established Brazilian distributors. The market supports long-term viability framing centered on metabolic syndrome severity shifting patient selection protocols. Acquisition target archetypes include focused metabolic device innovators with ANVISA registration depth. Watch for ANVISA alignment with International Medical Device Regulators Forum standards as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Class III Registration Pathway | Accelerates market entry velocity for laparoscopic stapling platforms in São Paulo networks. |
| Hospital System Partnership | Secures multi-year exclusive supply agreements with Rio de Janeiro academic centers. |
| Robotic Platform Placement | Establishes recurring revenue streams through instrument and service contracts. |
| Telemedicine Companion Development | Expands addressable patient base beyond specialist surgeon geographic concentration. |
| Reimbursement Strategy | Aligns procedure coding with Brazilian Ministry of Health incorporation guidelines. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged bariatric surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers across São Paulo, Rio de Janeiro, and Belo Horizonte. Secondary validation drew from ANVISA registration databases, Brazilian Ministry of Health incorporation guidelines, hospital procurement records, and private health insurance claims data. Bottom-up procedure volume estimates triangulated against top-down market size calculations.
Comparable-period anchoring linked projection assumptions to historical reference intervals across the analysis window. Segmentation modeling spanned procedure type, hospital tier, patient risk stratification, and geographic insurance density. CAGRs derived from regression analysis of installed surgical capacity against obesity prevalence trajectories. Forecast inputs incorporated ANVISA registration timeline compression and sleeve gastrectomy standardization curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA regulatory alignment timing and foreign exchange trajectory. Model outputs reflect documented assumptions regarding specialist surgeon training pipeline expansion. A model refresh is warranted upon material change in Brazilian Ministry of Health reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Bariatric Transport Wheelchairs Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Mexico Bariatric Surgery Market