
 Cardiac Poc Testing Devices Market | 2026-2036
Cardiac Poc Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Poc Testing Devices Market Analysis
Buyer concentration among urgent care centers and hospital-at-home networks is realigning procurement patterns across the cardiac PoC testing landscape. Abbott Laboratories leverages its integrated diagnostics portfolio to sustain channel relationships with large health systems. Siemens Healthineers AG anchors its position through manufacturing scale in immunoassay-based cardiac biomarker platforms. F. Hoffmann-La Roche AG differentiates via R&D intensity in high-sensitivity troponin assays.
Cardiac point-of-care testing devices are portable or handheld diagnostic instruments that measure cardiac biomarkers, electrical activity, or coagulation parameters at or near the patient site, typically delivering results within 15 minutes using cartridge-based microfluidic or optical detection systems. These devices serve emergency triage, acute coronary syndrome rule-out, and anticoagulation monitoring where rapid clinical decision-making determines patient outcomes. Biomarker analyzers lead the product type landscape due to troponin testing volume in emergency departments, while microfluidics technology occupies the fastest-expanding segment as manufacturers miniaturize multiplex assay architectures. Immunoassay platforms dominate current installed bases, though nucleic acid amplification approaches are gaining traction in specialized cardiac risk stratification protocols.
FDA CLIA waiver requirements shape product design standards and limit market access to manufacturers capable of demonstrating operator-independent accuracy. The EPA and OSHA frameworks govern manufacturing site compliance for reagent production and device assembly facilities in the United States. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled ECG interpretation and state-level scope-of-practice regulations affecting non-physician operators in retail clinic settings.
Market Dynamics
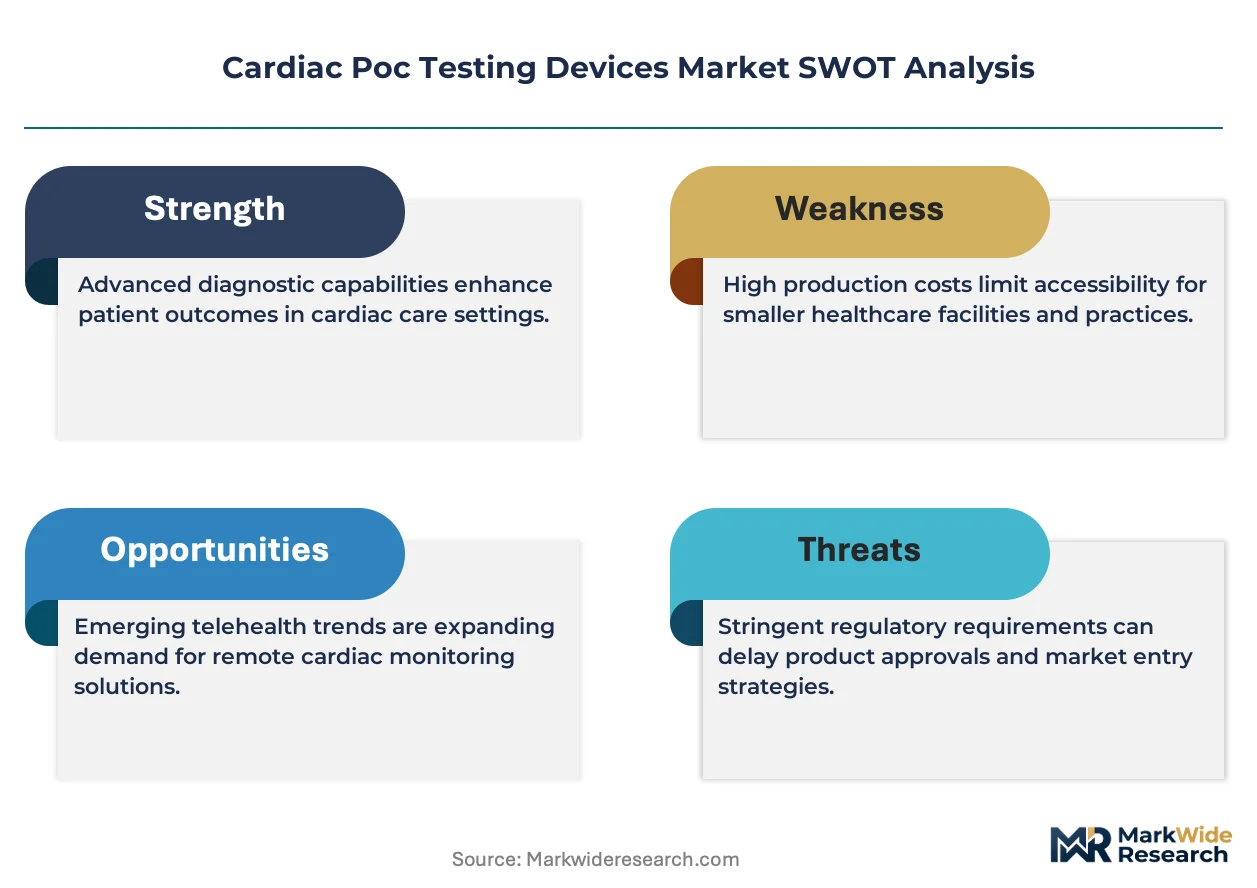
CLIA-waiver compression is restructuring competitive access in cardiac point-of-care diagnostics, as FDA clearance timelines now determine which manufacturers can serve urgent care and retail clinic channels.
Growth Catalysts
- Hospital-at-home program expansion:CMS reimbursement codes for acute care at home are pulling troponin and ECG testing into residential settings across the United States.
- CLIA-waived device pathways:FDA streamlined clearance for operator-independent platforms is accelerating deployment in non-laboratory environments.
- Microfluidic cartridge miniaturization:Multiplex assay architectures are enabling 15-minute turnaround times for biomarker panels in emergency triage workflows.
Market Restraints
- Reagent supply concentration:Specialized antibody production for high-sensitivity troponin assays clusters among limited biologics suppliers in North America and Western Europe.
- Capital intensity of manufacturing scale-up:Automated cartridge assembly lines require substantial upfront investment before achieving cost-competitive unit economics.
- Substitution from laboratory-based testing:Central lab high-throughput analyzers retain cost advantages for non-urgent cardiac risk stratification in integrated health networks.
Strategic Opportunities
- Rural and frontier health systems:Underserved regions in the United States lack proximate laboratory infrastructure, creating demand for decentralized cardiac biomarker platforms.
- Artificial intelligence-enabled ECG interpretation:Machine learning algorithms paired with handheld devices are opening new diagnostic categories beyond traditional arrhythmia detection.
- Retail clinic channel penetration:Pharmacy chains and urgent care franchises are expanding point-of-care cardiac testing as a patient acquisition and retention tool.
Industry Challenges
- Operator training standardization:Non-laboratory personnel in retail and home settings require validated competency protocols to maintain diagnostic accuracy.
- Legacy health record integration:Point-of-care devices must interface with diverse electronic medical record systems across fragmented hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Poc Testing Devices Market |
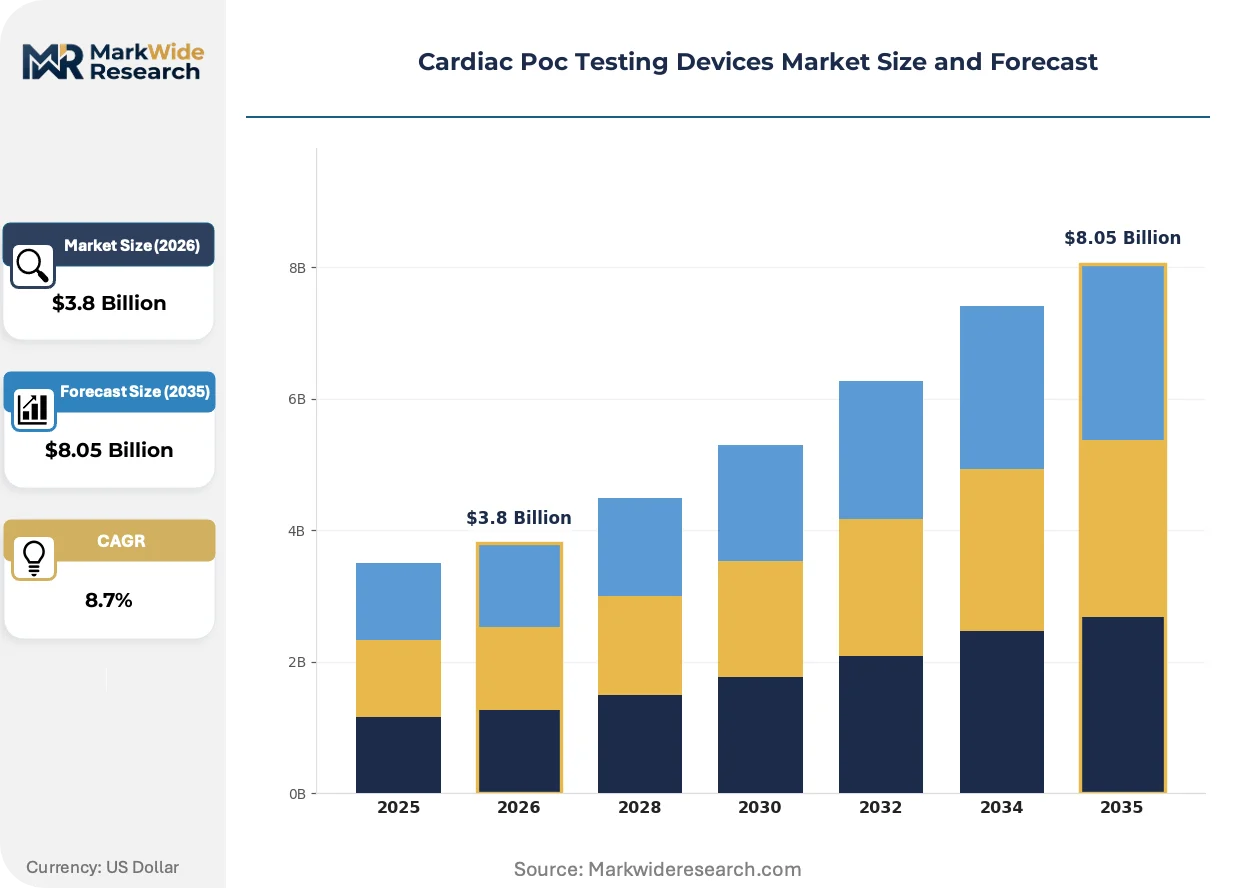
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrocardiogram, Biomarker Analyzers, Coagulation Testing, Glucose Meters Technology: Microfluidics, Optical, Immunoassay, Nucleic Acid Amplification End User: Hospitals, Home Care, Diagnostic Laboratories, Urgent Care Centers Application: Cardiac Monitoring, Emergency Response, Risk Assessment, Patient Management |
| Companies Covered | Abbott Laboratories, Siemens Healthineers AG, F. Hoffmann-La Roche AG, Danaher Corporation, Bio-Rad Laboratories Inc., ACON Laboratories Inc., LifeSign LLC, Nova Biomedical Corporation, Nano-Ditech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Poc Testing Devices Market Emerging Trajectories
Device architecture is converging on cartridge-based microfluidics while regulatory frameworks and procurement models simultaneously reshape how cardiac diagnostics reach clinical endpoints.
Microfluidic multiplexing is overtaking single-analyte immunoassay platforms in new product development cycles. Emergency departments and urgent care centers are adopting these architectures for simultaneous troponin, BNP, and D-dimer quantification. The technology is overtaking discrete testing workflows by compressing time-to-diagnosis and reducing instrument footprint in space-constrained clinical environments.
FDA guidance on artificial intelligence-enabled ECG interpretation is creating compliance benchmarks for algorithm-based diagnostic claims. Manufacturers must submit clinical validation data demonstrating non-inferiority to physician interpretation in specific arrhythmia categories. Cardiac monitoring device segments targeting ambulatory and home settings are most affected, with firms restructuring regulatory submissions to address software-as-medical-device classifications.
Consolidated procurement by large health systems is displacing fragmented purchasing across individual emergency departments. Integrated delivery networks in the United States are negotiating enterprise-wide contracts for point-of-care cardiac platforms, bundling devices, consumables, and service agreements. This concentration is most visible in the Southeast and Midwest regions where hospital system mergers have created super-regional purchasing entities with substantial negotiating leverage over device manufacturers.
Cardiac Poc Testing Devices Market Segmentation
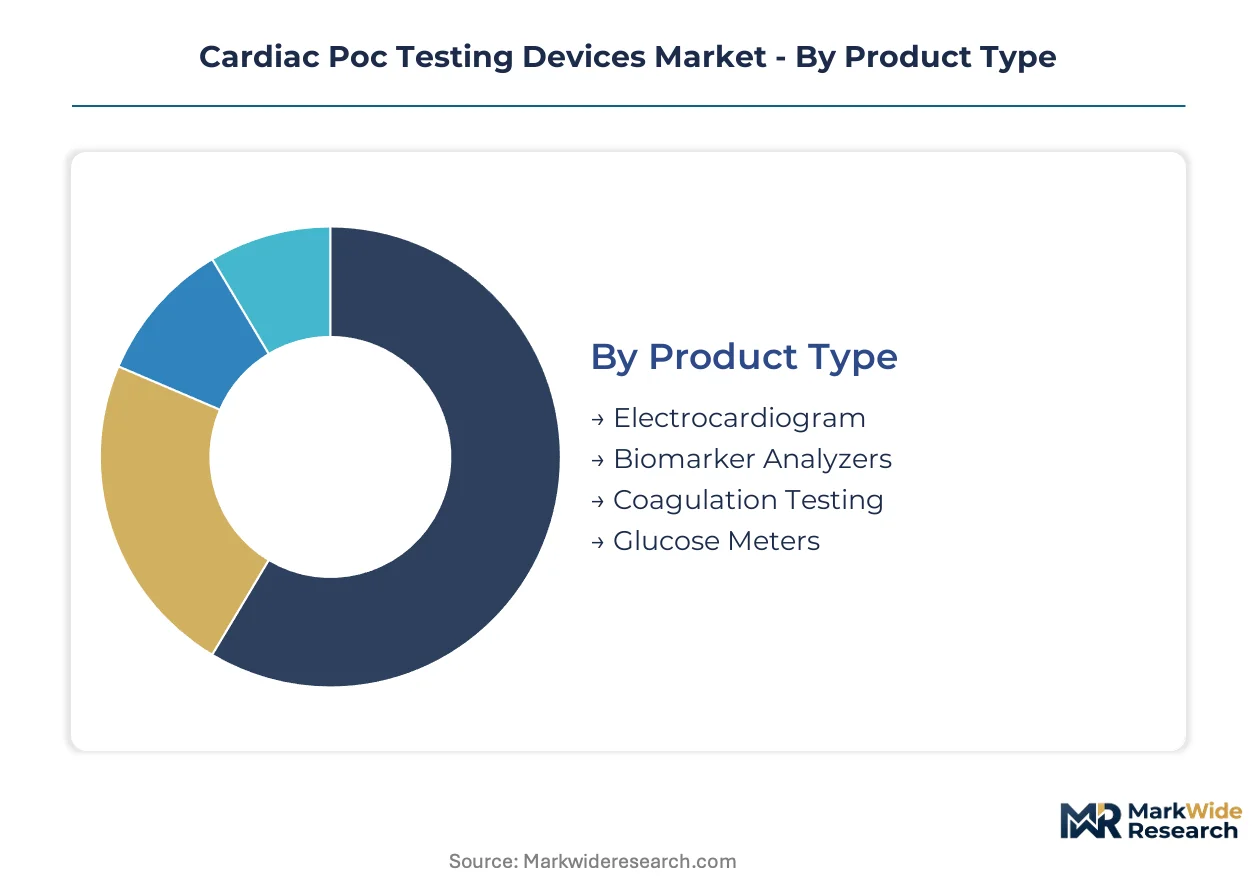
Cardiac point-of-care testing devices fragment across four critical dimensions that determine procurement patterns and technology adoption curves. Product type and technology choices dictate manufacturing scale requirements, while end-user concentration shapes channel economics and application focus determines reimbursement pathways.
Product Type:
Supply concentration in cartridge manufacturing favors platforms with standardized consumable architectures over discrete instrument categories.
- Biomarker Analyzers:Cartridge-based systems quantifying troponin, BNP, and D-dimer through immunoassay chemistry dominate emergency department throughput in the United States. Hospital-at-home networks in Texas and Florida are pulling these platforms into residential settings as CMS reimbursement codes mature for acute care at home.
- Electrocardiogram:Handheld devices with single-lead to 12-lead configurations deliver rhythm analysis at the point of symptom onset. Urgent care franchises across the Southeast are deploying these for chest pain triage where laboratory turnaround exceeds clinical tolerance.
- Coagulation Testing:PT/INR monitoring devices serve anticoagulation clinics and home-based warfarin management with capillary blood sampling.
- Glucose Meters:Cardiac-specific glucose monitoring addresses metabolic-cardiovascular comorbidity management in integrated care protocols.
Today's leader: Biomarker Analyzers. Tomorrow's challenger: Electrocardiogram.
Technology:
Manufacturing cost tiers separate mature immunoassay infrastructure from emerging microfluidic architectures requiring precision molding investments.
- Microfluidics:Multiplex assay integration on polymer cartridges enables 15-minute panel results from microliter sample volumes. FDA CLIA-waiver pathways are accelerating deployment in retail clinic channels where operator training is minimal.
- Immunoassay:Established chemiluminescence and fluorescence platforms anchor installed bases in hospital emergency departments with proven regulatory track records and lower per-test costs at volume.
- Optical:Reflectance and absorbance detection methods serve coagulation and select biomarker applications with simplified hardware requirements.
- Nucleic Acid Amplification:PCR-based cardiac risk stratification for genetic markers remains confined to specialized reference applications pending cost reduction.
Microfluidics is gaining share fastest. Immunoassay retains volume dominance.
End User:
Customer type determines pricing tolerance and service bundling requirements across acute, ambulatory, and residential care settings.
- Hospitals:Emergency departments and cardiac catheterization laboratories drive biomarker testing volume with integrated electronic medical record connectivity requirements. Large health systems in the Midwest are consolidating procurement through enterprise-wide device contracts.
- Urgent Care Centers:Retail-accessible locations prioritize CLIA-waived platforms with minimal maintenance and rapid staff onboarding. This segment is expanding most quickly as pharmacy chains add cardiac testing to patient acquisition strategies.
- Home Care:Hospital-at-home programs and decentralized emergency response networks require portable devices with telemedicine integration.
- Diagnostic Laboratories:Centralized reference sites maintain cost advantages for non-urgent cardiac risk stratification in integrated networks.
Urgent Care Centers represent the steepest expansion trajectory. Hospitals retain revenue concentration.
Application:
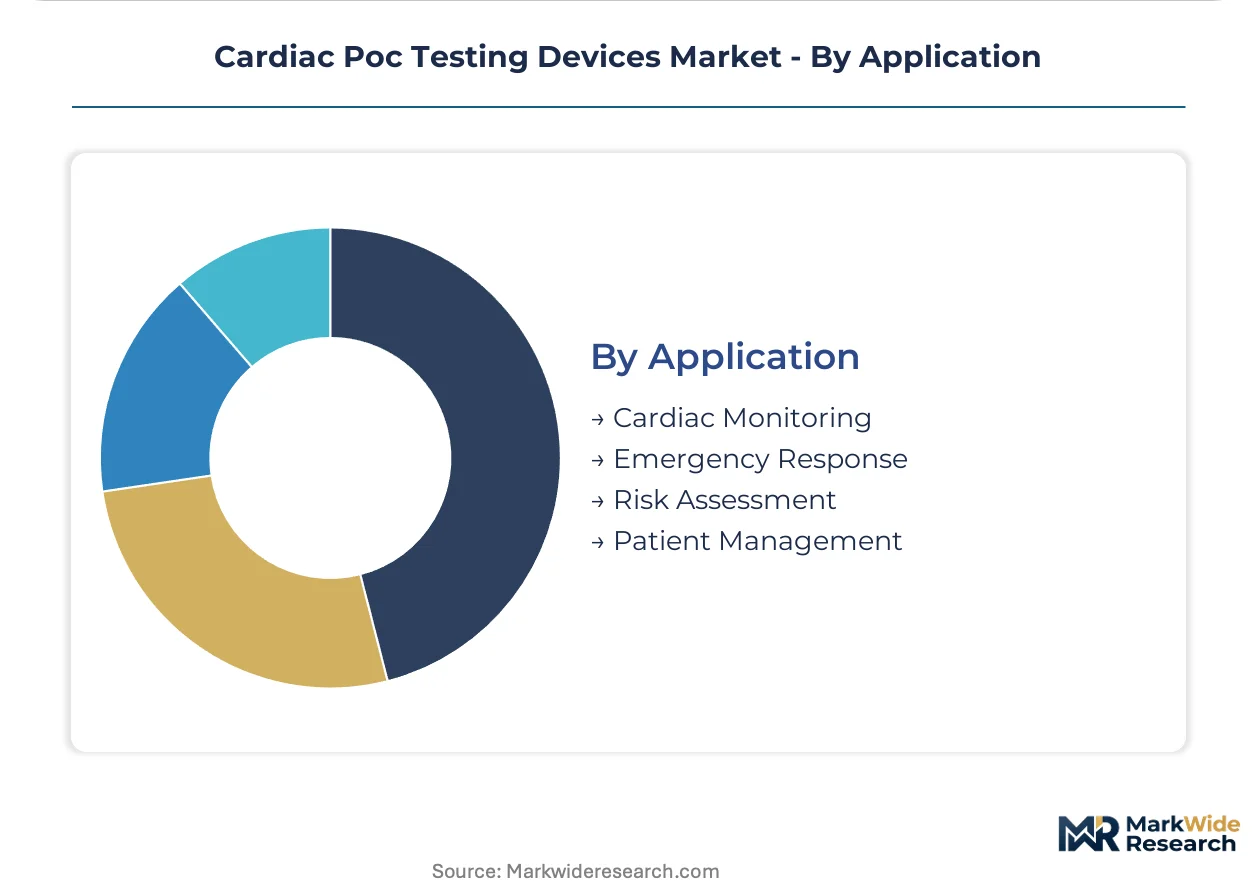
Clinical use case determines sensitivity specifications, turnaround requirements, and reimbursement coding complexity.
- Emergency Response:Pre-hospital and triage settings demand definitive rule-in/rule-out capability for acute coronary syndrome with 15-minute turnaround. Ambulance services in California and New York are piloting troponin testing in transport vehicles.
- Cardiac Monitoring:Continuous or intermittent rhythm assessment supports post-acute surveillance and chronic disease management in home settings.
- Risk Assessment:Stratification protocols for perioperative evaluation and preventive cardiology utilize biomarker panels with lower urgency requirements.
- Patient Management:Therapeutic monitoring of anticoagulation and heart failure medications requires longitudinal testing with result trending.
Emergency Response commands premium pricing. Patient Management offers recurring revenue stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital-at-home networks deploy troponin testing platforms faster than German outpatient clinics adopt comparable systems, reflecting divergent reimbursement architectures and regulatory flexibility across Atlantic markets.
United States
CMS acute care at home codes pull biomarker analyzers into residential settings across Texas and Florida. FDA CLIA-waiver pathways compress clearance timelines for operator-independent platforms. The Southeast hospital system consolidation creates super-regional purchasing entities with substantial negotiating leverage.
Germany
Outpatient cardiac rehabilitation centers drive demand for portable ECG devices in Bavaria and North Rhine-Westphalia. EMA MDR compliance requirements extend validation timelines for microfluidic cartridge systems. The Berlin-Brandenburg corridor hosts specialized antibody suppliers serving troponin assay manufacturers.
China
Tier-two city emergency departments expand point-of-care cardiac testing faster than tier-one saturation suggests. NMPA streamlined review channels for innovative diagnostics accelerate domestic manufacturer market entry. The Yangtze River Delta concentrates precision molding capacity for microfluidic cartridge production.
Japan
Metropolitan ambulance services pilot pre-hospital troponin testing in Kanto and Kansai regions. PMDA guidance on software-as-medical-device classifications shapes AI-enabled ECG submission requirements. Nagoya-based industrial clusters supply optical detection components to regional device assemblers.
United Kingdom
NHS long-term plan decentralization pushes cardiac biomarker testing into community diagnostic hubs across London and the Midlands. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR harmonization timelines. The Oxford-Cambridge corridor attracts venture funding for microfluidic diagnostics startups.
Cardiac Poc Testing Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the cardiac point-of-care testing landscape. The vendor base organizes into three tiers: integrated diagnostics portfolios, immunoassay platform anchors, and microfluidic technology specialists. Consolidated procurement by United States health systems favors enterprise-scale suppliers with service bundling capabilities. Dominant competitive moves include strategic partnerships for cartridge manufacturing scale and technology licensing for AI-enabled ECG algorithms.
Within the integrated diagnostics tier, Abbott Laboratories and Siemens Healthineers AG exemplify conglomerate structures with channel depth across hospital systems and urgent care networks. F. Hoffmann-La Roche AG occupies a position among high-sensitivity assay specialists. These three entities represent contrasting strategic postures: portfolio breadth, manufacturing scale, and R&D intensity respectively.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers AG |
| F. Hoffmann-La Roche AG |
| Danaher Corporation |
| Bio-Rad Laboratories Inc. |
| ACON Laboratories Inc. |
| LifeSign LLC |
| Nova Biomedical Corporation |
| Nano-Ditech Corporation |
| Others |
Supply Flow & Price Mechanics
Specialized antibody production costs for high-sensitivity troponin assays flow from North American and Western European biologics suppliers through CLIA-waived cartridge manufacturers into tiered hospital procurement contracts, with cartridge molding precision determining price stratification across emergency department and retail clinic channels.
Pricing Analysis
Capacity additions in China's Yangtze River Delta precision molding clusters are reshaping price floors for microfluidic cartridge substrates. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared high-sensitivity platforms from CLIA-waived retail devices and unregulated emerging-market alternatives. Pricing pressure stems from consolidated procurement by United States super-regional health systems negotiating enterprise-wide device and consumable bundles. Urgent care franchises exhibit highest price sensitivity due to thin per-test margins, while hospital catheterization laboratories tolerate premium tiers for integrated EMR connectivity.
Supply Chain Analysis
Direct-to-hospital contracts handle hyperscale demand from integrated delivery networks, while distributor-mediated channels serve fragmented urgent care and retail clinic segments. Geographic supply concentration centers on China for microfluidic cartridge molding, Germany for optical detection components, and the United States for specialized antibody production. Raw material dependencies include precision-molded polymers, monoclonal antibody reagents, and optical sensor arrays. Single-source vulnerability in high-sensitivity troponin antibody supply creates exposure to biologics manufacturing disruptions. Distribution runs through regional medical device distributors with service bundling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cardiac point-of-care testing rests on cartridge manufacturing scale-down and the premium-tier shift toward AI-enabled ECG platforms with software-as-medical-device recurring revenue models.
For Market Incumbents: Hedge against microfluidic technology disruption by securing captive antibody supply agreements with North American biologics manufacturers. Reinforce hospital system relationships through enterprise-wide EMR integration investments that raise switching costs. Defend against urgent care channel price erosion by bundling device placement with exclusive consumable contracts. For New Entrants and Emerging Players: The price-point gap between premium AI-enabled ECG systems and economy single-lead devices opens white-space at the mid-tier for retail clinic channels. Target pharmacy chain urgent care expansions in the United States Southeast and Midwest where laboratory infrastructure is sparse. Pursue CLIA-waiver-first regulatory strategy to compress time-to-revenue versus full FDA clearance pathways. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital-at-home reimbursement codes mature and procurement concentrates among super-regional health systems. Long-term viability favors platforms with software recurring revenue and cartridge consumable lock-in over hardware-only business models. Target acquisition archetype: microfluidic technology specialists with FDA-cleared multiplex panels and underpenetrated retail clinic channel presence. Watch CMS expansion of acute care at home codes as inflection signal for residential biomarker testing demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA CLIA-Waiver Pathway | Accelerates deployment in retail clinics with minimal operator training requirements. |
| Hospital System Partnership | Secures enterprise-wide procurement contracts with integrated EMR connectivity bundles. |
| Software Companion Development | Enables AI-enabled ECG algorithm subscriptions beyond hardware revenue capture. |
| Backward Integration into Antibody Supply | Reduces exposure to concentrated North American biologics supplier bottlenecks. |
| Reimbursement Strategy | Aligns product positioning with CMS acute care at home coding expansions. |
Methodological Framework
Bottom-up urgent care center and hospital-at-home deployment modeling reconciled against top-down cartridge manufacturing capacity tracking forms the analytical core. Primary interviews with emergency department directors, biomedical engineers, GPO contracts managers, and CLIA-waiver regulatory consultants combined with secondary validation against FDA 510(k) filings, CMS reimbursement code databases, and hospital procurement records. Triangulation across stakeholder inputs and published regulatory submissions ensures segment-level accuracy.
Historical trendline analysis of installed base growth and consumable throughput per device informs projection modeling across the analysis window. Segmentation dimensions include product type, technology platform, end-user setting, and application urgency tier. CAGRs derive from curve-fitting against biomarker testing volume expansion and microfluidic technology substitution rates. Forecast inputs incorporate CMS reimbursement policy trajectories and FDA guidance evolution on software-as-medical-device classifications.
Caveats apply where FDA guidance revisions on AI-enabled diagnostics or state-level scope-of-practice regulations could materially shift the outlook. Forecasts reflect base-case assumptions regarding CLIA-waiver pathway stability and hospital-at-home program expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Medical Thermometers Market
Medical Devices
Clot Management Devices Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Mediastinoscope Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Digital Pregnancy Test Kits Market
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Netherlands Respiratory Devices Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Minimally Invasive Deformity Correction System Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Implantable Pacemaker Market
Medical Devices
Endodontic Files Market
Medical Devices
Steroid Releasing Implant Market