
 Walking Aids Market | 2026-2036
Walking Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Walking Aids Market Intelligence
German orthopedic manufacturers is broadening production capacity for lightweight aluminum rollators to serve European homecare channels. Medline Industries leverages extensive distribution networks across North American hospital pharmacies. GF Health Products anchors its position through durable steel-frame walker lines aimed at institutional buyers. Invacare Corporation specializes in adjustable-height mobility solutions that comply with varying international standards.
Walking aids encompass assistive mobility devices engineered with aluminum tubing, polymer grips, and rubber-tip bases to redistribute body weight and stabilize gait patterns for users with impaired balance or lower-extremity weakness. Rollators incorporate hand-operated braking systems and padded seats, distinguishing them from basic canes or axillary crutches in both functionality and price positioning. Aluminum dominates material selection due to its strength-to-weight ratio, though carbon-fiber variants are gaining traction among premium segments. End-user demand from seniors and rehabilitation patients concentrates in retail and medical supply store channels, where physical fitting and insurance verification remain critical to purchase completion.
FDA 510(k) premarket notification requirements govern walking aid safety classifications in the United States, while the EU Medical Device Regulation mandates CE marking and post-market surveillance across European Economic Area states. ISO 11199 technical specifications for walking manipulability and static load testing shape baseline product engineering decisions for manufacturers targeting multiple jurisdictions. Stakeholders must monitor evolving reimbursement coding from Medicare and national health services, as coverage determinations directly influence patient out-of-pocket exposure and channel preference shifts.
Market Dynamics
Reimbursement coding revisions from Medicare and national health services are compressing patient out-of-pocket exposure and redirecting procurement volumes toward retail and medical supply channels. This structural force is reconfiguring how manufacturers position rollators and wheeled walkers across institutional and homecare segments.
Growth Catalysts
- ISO 11199 stability testing:Standardized static load protocols are accelerating product engineering convergence across aluminum and carbon-fiber frame variants, reducing regional compliance fragmentation for manufacturers targeting multiple jurisdictions.
- Home healthcare providers:Post-surgical recovery protocols are concentrating procurement of wheeled walkers and rollators into dedicated durable medical equipment channels, creating dedicated demand pipelines.
- Japan's aging demographic:Metropolitan Tokyo and Osaka prefectures are exhibiting concentrated demand for adjustable-height mobility solutions as municipal reimbursement frameworks expand access thresholds.
Market Restraints
- Aluminum input volatility:Primary aluminum price swings from Chinese smelter output adjustments are compressing margin predictability for lightweight rollator producers dependent on extruded tubing supply.
- FDA 510(k) pathway friction:Premarket notification timelines for novel braking systems and folding mechanisms are extending commercialization cycles for innovative rollator designs.
- Basic cane substitution:Low-cost axillary crutches and single-point canes retain price advantage in cash-pay segments, limiting premium rollator penetration among uninsured populations.
Strategic Opportunities
- German homecare channel expansion:Orthopedic manufacturers are broadening production capacity for lightweight aluminum rollators to capture European retail pharmacy networks serving aging rural populations.
- Carbon-fiber premium tier:Material convergence with aerospace composite supply chains is enabling sub-five-kilogram rollator variants for affluent senior segments prioritizing transportability.
- EU Medical Device Regulation tailwind:CE marking harmonization across European Economic Area states is reducing duplicate testing burdens for manufacturers with existing ISO 11199 certification.
Industry Challenges
- Biomechanical fitting expertise:Retail pharmacy staff lack specialized training in gait assessment and height-adjustment protocols, elevating return rates for improperly configured rollators.
- Cross-border reimbursement verification:Insurance pre-authorization systems vary across United States state Medicaid programs, complicating inventory planning for multi-state distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walking Aids Market |
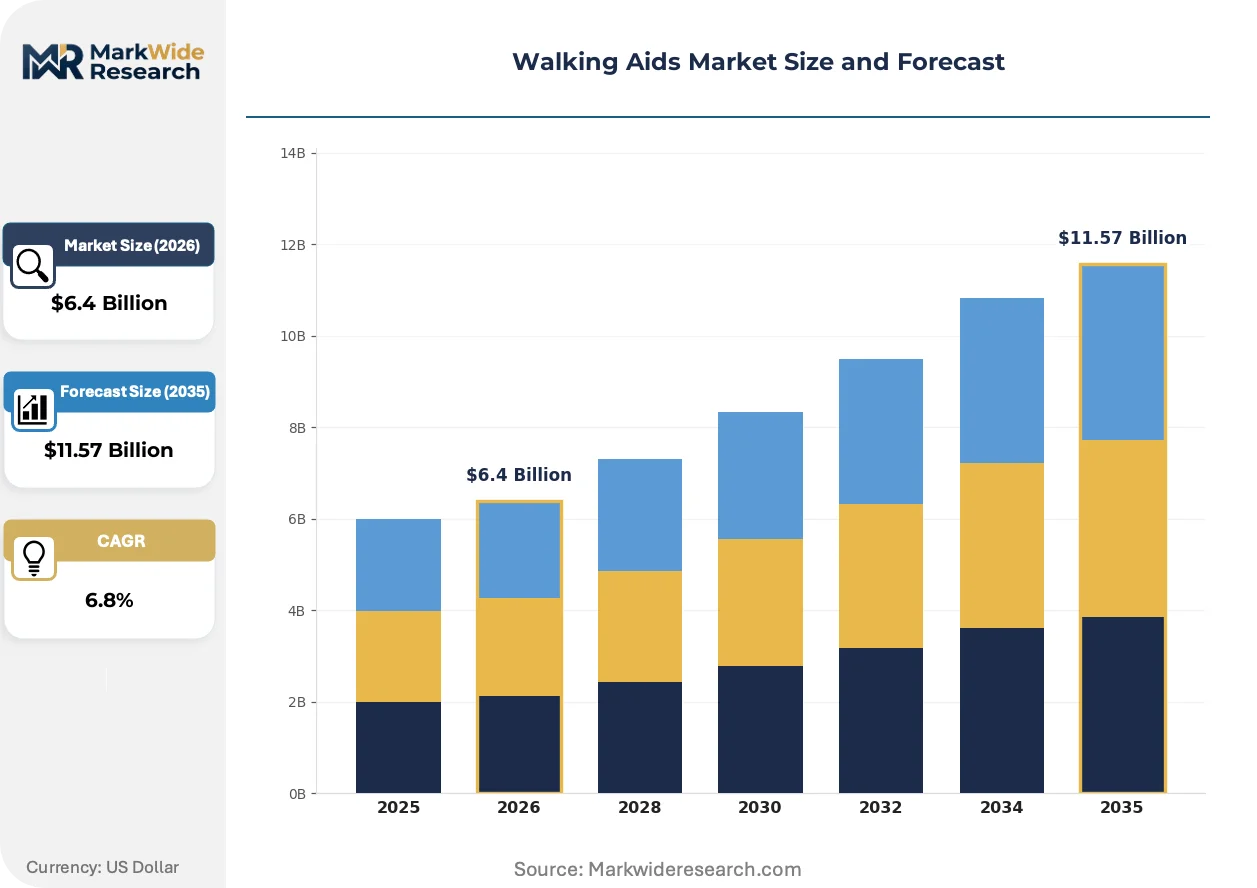
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canes, Crutches, Walkers, Rollators End User: Seniors, Physically Disabled, Rehabilitation Patients, General Public Material: Aluminum, Steel, Plastic, Wood Distribution Channel: Online, Retail, Medical Supply Stores, Hospital Pharmacies |
| Companies Covered | Medline Industries, GF Health Products, Invacare Corporation, Etac AB, TOPRO Mobility, Drive DeVilbiss Healthcare, Otto Bock HealthCare, Mabis Healthcare, Sunrise Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walking Aids Market Strategic Shifts & Innovations
Sensor-embedded braking systems and polymer composite frames are displacing mechanical-only designs across premium rollator segments. These innovations are compressing the functional gap between basic walkers and powered mobility devices while elevating safety benchmarks.
Electromagnetic braking modules with pressure-sensitive activation are automating descent control on inclined surfaces. Rehabilitation hospitals in the United States are piloting these systems for post-stroke patients with impaired grip strength. The technology is compressing liability exposure for institutional buyers while extending safe independent mobility for users with upper-extremity weakness.
EU Medical Device Regulation post-market surveillance mandates are tightening adverse event reporting requirements for walking aid distributors. Manufacturers must now maintain traceability records across polymer grip and rubber-tip component suppliers. European Economic Area states are responding with consolidated quality management system investments to preempt regulatory enforcement actions.
Direct-to-consumer digital channels are fragmenting traditional durable medical equipment procurement patterns. Medicare Advantage plans in Florida and Arizona are experimenting with online fitting tools and home delivery for standard rollator configurations. This shift is most visible in sunbelt retirement communities where mobility-limited seniors prioritize convenience over in-person pharmacy consultation.
Walking Aids Market Segmentation
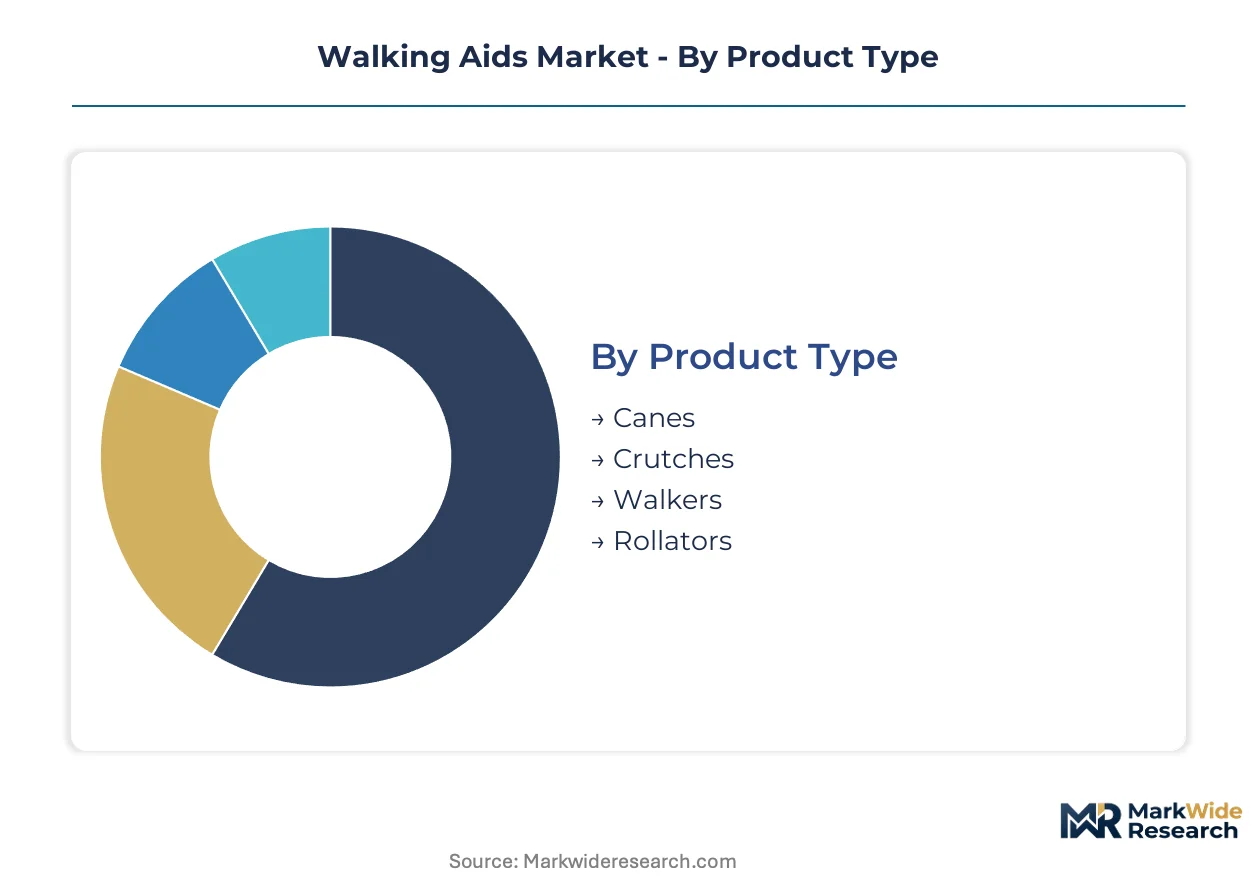
Walking aids manufacturers engineer product portfolios around distinct biomechanical needs, reimbursement pathways, and channel economics. Segmentation discipline separates volume-driven institutional procurement from premium retail positioning where transportability and aesthetic design command price premiums.
Product Type:
Volume concentrates in basic walkers and canes, while premium positioning accrues to rollators with integrated seating and braking systems.
- Rollators:Four-wheeled frames with hand-operated brakes and padded seats redistribute body weight for users with moderate balance impairment. Demand clusters in German and Japanese homecare channels where municipal reimbursement covers wheeled mobility devices for post-surgical recovery.
- Walkers:Rigid or folding frames without wheels provide maximum stability for users with severe lower-extremity weakness or post-stroke rehabilitation protocols. Institutional procurement in United States skilled nursing facilities drives volume, though aluminum frame variants are penetrating European retail pharmacies.
- Canes:Single-point or quad-base designs serve mild balance impairment with minimal cost burden.
- Crutches:Axillary and forearm variants address temporary mobility needs following orthopedic procedures.
Mature deployment sits with walkers. Newer deployment is concentrated in rollators.
End User:
Application context determines specification requirements, with institutional buyers prioritizing durability and home users emphasizing portability and storage convenience.
- Seniors:Aging populations with chronic conditions such as osteoarthritis and Parkinson's disease require adjustable-height solutions that accommodate progressive functional decline. Metropolitan Tokyo and Osaka prefectures exhibit concentrated demand as Japanese municipal frameworks expand access thresholds for durable medical equipment.
- Rehabilitation Patients:Post-surgical and post-stroke users need graduated mobility support through recovery phases. United States hospital discharge planners coordinate procurement through durable medical equipment suppliers, creating dedicated demand pipelines for wheeled walkers with weight-bearing modifications.
- Physically Disabled:Long-term users with congenital or traumatic conditions drive customization requirements for seat height and handle positioning.
- General Public:Temporary injury recovery and preventive mobility support generates cash-pay demand through retail channels.
Rehabilitation patients generate the steepest expansion trajectory as surgical volumes rise and length-of-stay compression accelerates home-based recovery protocols.
Material:
Cost tier and performance specifications diverge sharply between institutional-grade durability and consumer-grade transportability.
- Aluminum:Extruded tubing delivers optimal strength-to-weight ratios for rollator frames under five kilograms. German orthopedic manufacturers are broadening production capacity to serve European retail pharmacy networks with lightweight variants.
- Steel:Heavy-gauge tubing anchors institutional walker lines where durability outweighs portability concerns. GF Health Products targets this specification tier for skilled nursing facility procurement in the United States.
- Plastic:Polymer components form grips, seats, and structural elements in economy-tier products.
- Wood:Traditional canes serve aesthetic preferences in cash-pay segments with limited clinical functionality.
Steel dominates institutional procurement. Aluminum is gaining share fastest in homecare channels where transportability determines purchase completion.
Distribution Channel:
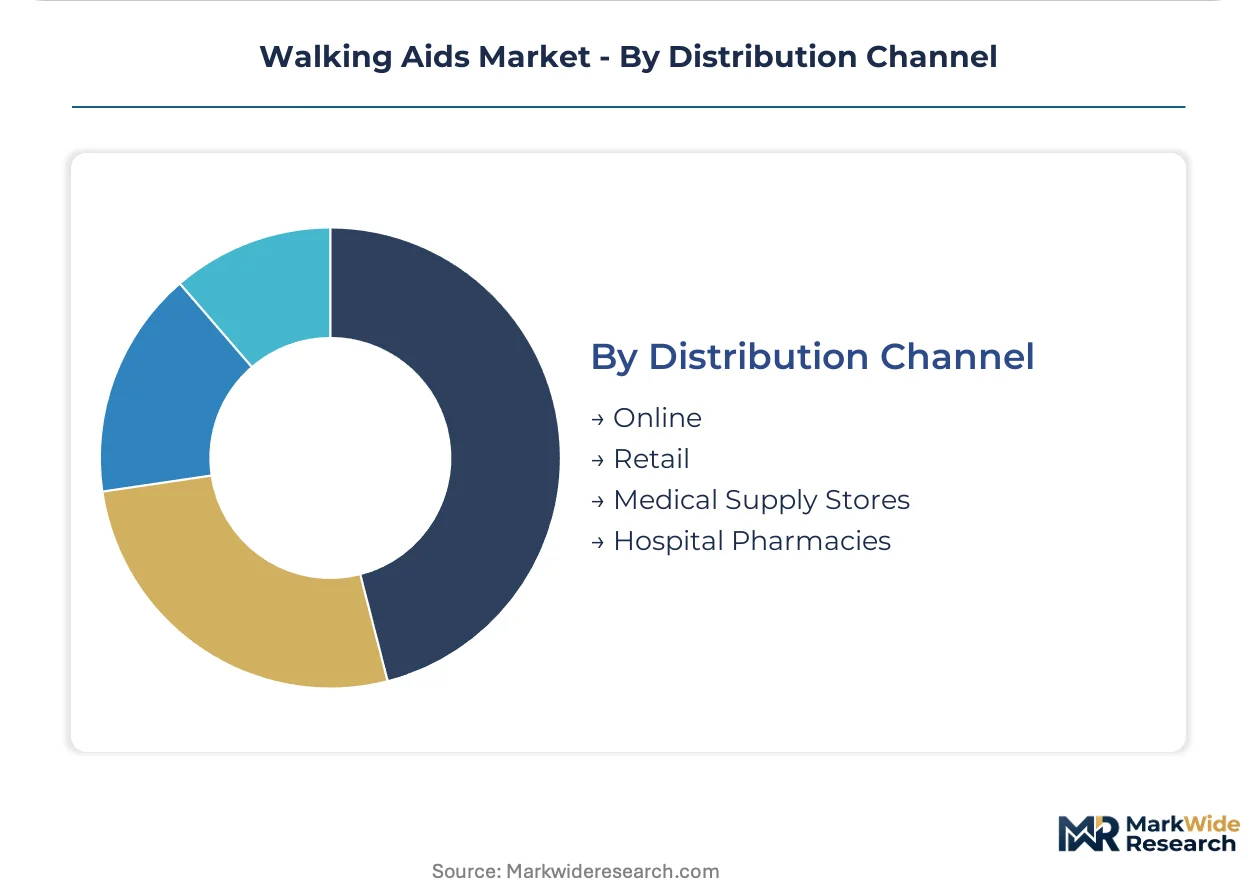
Channel selection intersects with reimbursement verification requirements and the need for physical fitting assistance.
- Medical Supply Stores:Specialized durable medical equipment dealers provide gait assessment, height adjustment, and insurance pre-authorization. Medicare and Medicaid reimbursement verification remains critical to purchase completion in United States markets.
- Hospital Pharmacies:Integrated discharge planning coordinates immediate post-surgical procurement. Medline Industries leverages extensive distribution networks across North American hospital pharmacies to capture institutional volumes.
- Retail:Pharmacy chains and big-box stores serve cash-pay seniors with standard configurations.
- Online:Direct-to-consumer digital channels are fragmenting traditional procurement patterns, with Medicare Advantage plans in Florida and Arizona piloting home delivery for standard rollator configurations.
Medical supply stores anchor reimbursement-dependent transactions. Online deployment is expanding most quickly in sunbelt retirement communities where convenience outweighs in-person consultation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum extrusion clusters in Germany's North Rhine-Westphalia and Japan's Kanto corridor supply lightweight tubing that anchors rollator manufacturing for aging populations across three continents.
United States
Medicare Advantage expansion in Florida and Arizona is accelerating home-delivery procurement for standard rollator configurations. FDA 510(k) premarket notification requirements govern braking system safety classifications. Hospital discharge planners in metropolitan Phoenix and Miami coordinate wheeled walker procurement through durable medical equipment suppliers.
Germany
Municipal reimbursement frameworks in Bavaria and Baden-Württemberg are broadening access thresholds for wheeled mobility devices. EU Medical Device Regulation mandates CE marking and post-market surveillance across European Economic Area states. Orthopedic manufacturers in North Rhine-Westphalia are expanding lightweight aluminum rollator production capacity for European retail pharmacy networks.
Japan
Metropolitan Tokyo and Osaka prefectures exhibit concentrated demand for adjustable-height mobility solutions as municipal frameworks expand durable medical equipment access. PMDA and METI oversight aligns with JIS standards for walking aid stability. Nagoya-based fabricators supply polymer grip components to domestic rollator assemblers serving Kansai-region homecare channels.
United Kingdom
NHS reimbursement coding revisions are compressing patient out-of-pocket exposure for post-surgical recovery equipment. MHRA compliance with EU MDR transitional provisions maintains CE marking recognition for walking aid imports. London and Southeast England medical supply stores anchor gait assessment and insurance verification services for rollator dispensing.
China
NMPA regulatory pathways for Class I medical devices are standardizing production quality system requirements for export-oriented manufacturers. GB standards for assistive products shape baseline engineering for aluminum frame variants. Yangtze River Delta fabricators supply extruded tubing to German and Japanese OEMs under ISO 11199 certification protocols.
Walking Aids Market Key Industry Players
Global majors compete with regional champions across distribution network depth and reimbursement verification capabilities. The vendor base organizes around three tiers: diversified healthcare conglomerates with hospital pharmacy access, specialized orthopedic manufacturers with homecare channel expertise, and regional fabricators serving municipal procurement contracts. Two dominant competitive moves are reshaping positioning: backward integration into aluminum extrusion capacity to offset raw material volatility, and strategic partnerships with Medicare Advantage plans to secure direct-to-consumer delivery routes.
Among diversified healthcare suppliers, Medline Industries and Drive DeVilbiss Healthcare exemplify the scale-driven archetype with extensive North American distribution infrastructure. GF Health Products occupies a position within the institutional-durability tier, while Invacare Corporation represents adjustable-height specialization for international standard compliance. Etac AB and TOPRO Mobility anchor Scandinavian-engineered positioning in premium European homecare segments.
| Leading Market Players |
|---|
| Medline Industries |
| GF Health Products |
| Invacare Corporation |
| Etac AB |
| TOPRO Mobility |
| Drive DeVilbiss Healthcare |
| Otto Bock HealthCare |
| Mabis Healthcare |
| Sunrise Medical |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between ISO 11199-compliant premium rollators and uncertified economy canes manifests in divergent margin structures and sourcing footprints. Premium tiers command bundled service warranties and gait-fitting support through medical supply channels, while commodity segments compete on spot aluminum pricing through retail big-box procurement.
Pricing Analysis
Service-bundling separates premium rollator configurations from stripped-down economy walkers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 11199 certification status, aluminum grade specifications, and after-sales fitting support. Cost compression in economy steel-frame walkers is intensifying because Chinese smelter output adjustments transmit directly to extruded tubing costs. Institutional buyers in United States skilled nursing facilities exhibit lowest price sensitivity due to Medicare reimbursement coverage, while uninsured cash-pay seniors in retail channels face highest out-of-pocket exposure.
Supply Chain Analysis
Workforce availability constraints in Yangtze River Delta extrusion facilities and North Rhine-Westphalia aluminum clusters are elevating lead time variability for lightweight rollator tubing. Supply concentrates in China for primary aluminum inputs, Germany for precision extrusion and component assembly, and Japan for polymer grip fabrication. Raw material dependencies encompass primary aluminum billets, rubber-tip compounds, and polymer composite resins. Single-source vulnerability sits with Chinese smelter concentration for primary aluminum. Distribution runs through durable medical equipment dealers for reimbursement-verified transactions, with direct-to-consumer channels fragmenting traditional pharmacy procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-embedded braking systems are displacing mechanical-only designs across premium rollator segments, compressing the functional gap between basic walkers and powered mobility devices.
For Market Incumbents: Acquire carbon-fiber composite manufacturing capacity to secure aerospace supply chain access for sub-five-kilogram rollator variants. Threat from electromagnetic braking module suppliers necessitates backward integration into sensor-embedded system design. Certification investment in EU MDR and FDA 510(k) parallel pathways anchors institutional procurement relationships against emerging Asian competitors. For New Entrants and Emerging Players: The premium-economy price-point gap in adjustable-height rollators opens white-space targeting in Japanese municipal reimbursement channels. Most penetrable segment sits with rehabilitation patients requiring graduated mobility support through post-surgical recovery phases. Go-to-market angle leverages direct-to-consumer digital fitting tools paired with Medicare Advantage home delivery partnerships in Florida and Arizona retirement communities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified healthcare conglomerates seeking hospital pharmacy distribution depth. Long-term viability frames around five-to-ten year demographic tailwinds in aging populations across United States, Germany, and Japan. Acquisition target archetype: specialized orthopedic manufacturers with ISO 11199 certification and established European retail pharmacy networks. Signal to watch: Medicare Advantage plan expansion rates in sunbelt states as inflection indicator for direct-to-consumer channel viability.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11199 Certification Investment | CE marking harmonization reduces duplicate testing burdens across European Economic Area states. |
| Backward Integration into Aluminum Extrusion | Captive supply of lightweight tubing offsets Chinese smelter output volatility for rollator frames. |
| Sensor-Embedded Braking Development | Electromagnetic modules automate descent control for post-stroke patients with impaired grip strength. |
| Medicare Advantage Partnership | Direct-to-consumer delivery routes secure preferred provider status in Florida and Arizona markets. |
| Carbon-Fiber Composite Sourcing | Aerospace supply chain access enables sub-five-kilogram premium rollator variants for affluent seniors. |
Research Approach
Multi-period observation of Medicare reimbursement coding revisions, aluminum price indices, and FDA 510(k) clearance timelines anchored the trend analysis, supplemented by interviews with hospital discharge planners, durable medical equipment procurement managers, biomedical engineers, and retail pharmacy category buyers. Secondary validation drew from FDA premarket notification databases, CMS Medicare claims data, EU MDR CE marking registries, and ISO 11199 certification records. Bottom-up patient population modeling and top-down healthcare expenditure triangulation converged on segment-level demand estimates.
Segment-weighting across product type, material specification, end-user application, and distribution channel shaped the analytical framework. CAGRs were derived from fitted growth curves against demographic projections and reimbursement policy trajectories across the analysis window. Industry-specific forecast inputs encompassed surgical volume trends, length-of-stay compression rates, and municipal durable medical equipment access threshold expansions.
Inputs from Medicare claims databases, EU MDR registries, and aluminum futures markets were available through the study window; gaps in real-time Medicaid state-level reimbursement verification systems introduce uncertainty bands around channel mix projections. Forecasts reflect documented assumptions regarding demographic aging trajectories and regulatory stability. Material deviation in Medicare Advantage expansion rates, Chinese smelter output policy, or FDA 510(k) timeline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Brachytherapy Catheters Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Global Medical Composite Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
Hearing Loop Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Orthodontic Retainers Market
Medical Devices
US Nebulizer Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market