
 Australia Bariatric Surgery Market | 2026-2036
Australia Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Bariatric Surgery Market Outlook
Australian hospital capacity for metabolic procedures is hardening as public funding commitments expand. Johnson & Johnson leverages its broad surgical portfolio across multiple procedure categories. Medtronic PLC anchors its position through sustained investment in laparoscopic platforms. Intuitive Surgical Inc. differentiates via robotic surgery installations in tertiary centers.
Bariatric surgery encompasses surgical interventions to reduce stomach volume or alter digestive physiology, typically employing stapling devices, adjustable bands, or intestinal rerouting to achieve sustained weight reduction in patients with clinically severe obesity. Sleeve gastrectomy dominates procedural volumes due to favorable risk profiles and reversibility constraints, while robotic surgery segments capture premium positioning despite higher capital requirements. Ambulatory surgical centers represent the fastest-growing end-user channel as payor pressure shifts lower-complexity cases away from inpatient settings.
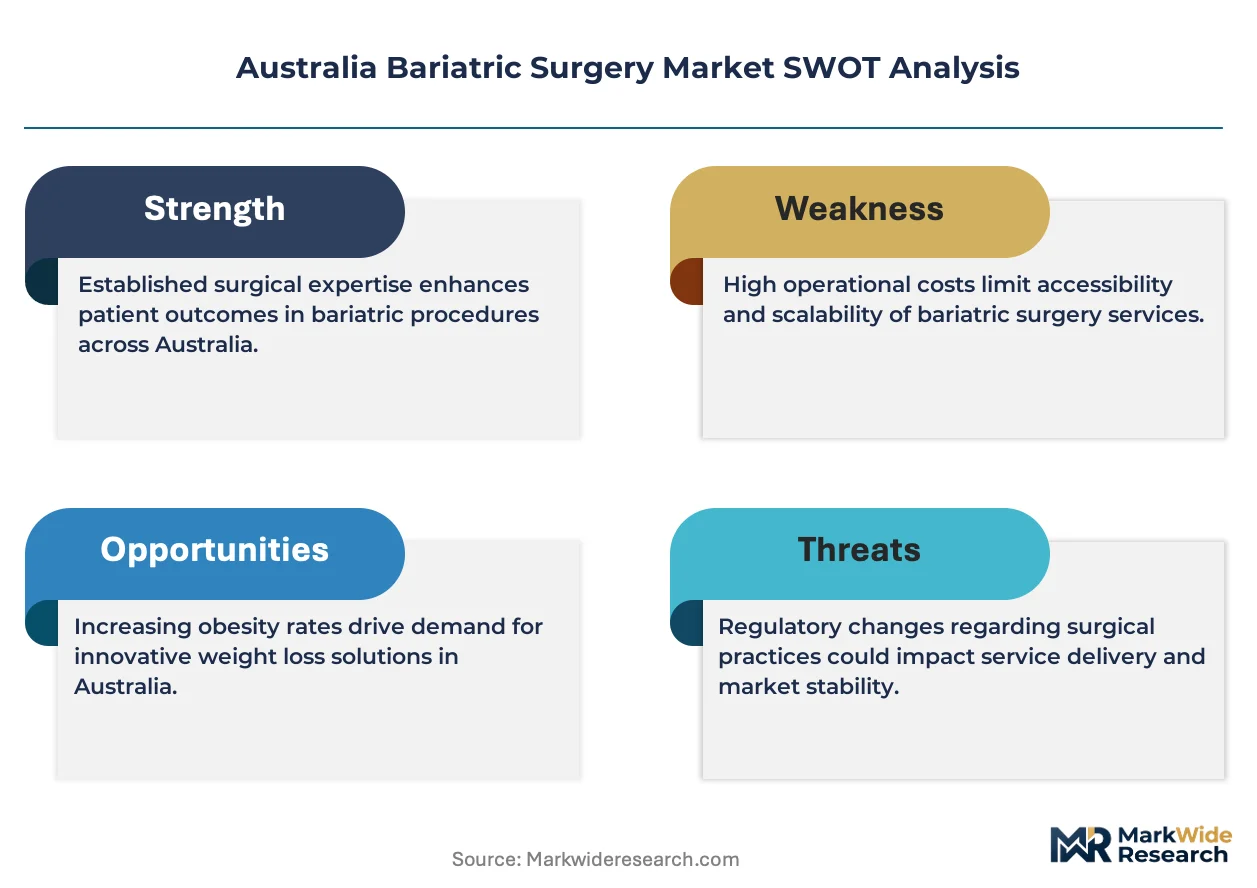
TGA medical device regulations govern implantable staplers and energy platforms, while Medicare Benefit Schedule determinations directly influence surgeon reimbursement and patient access thresholds across states. Private health fund coverage policies create parallel demand dynamics distinct from public waitlist flows. Stakeholders must monitor evolving MBS item number reviews and state-level hospital funding allocations to anticipate volume shifts between public and private treatment pathways.
Market Dynamics
Medicare Benefit Schedule reviews are compressing reimbursement timelines while public hospital networks in Victoria and New South Wales expand metabolic surgery capacity, creating divergent access pathways between insured and uninsured patient populations.
Growth Catalysts
- Public Hospital Expansion:Victorian and New South Wales health authorities are funding dedicated bariatric surgery units within tertiary centers, reducing waitlist durations for uninsured patients.
- TGA Streamlined Pathways:Australia's medical device regulator has accelerated pre-market assessment timelines for stapling platforms and energy devices, compressing product launch cycles.
- Sleeve Gastrectomy Preference:Surgeons increasingly favor this procedure over gastric bypass due to reduced complication rates and shorter operative times, driving volume concentration in this technique.
Market Restraints
- Robotic Capital Requirements:Da Vinci system installation costs exceed AUD 3 million per unit, restricting robotic-assisted procedures to metropolitan tertiary centers with philanthropic or state-funded capital programs.
- Private Health Fund Coverage Gaps:Tiered insurance products exclude obesity-related procedures from basic coverage tiers, forcing patients into higher premium brackets or public waitlists.
- Anesthesiology Workforce Constraints:Critical care specialist shortages in regional Queensland and Western Australia limit procedural expansion outside Sydney, Melbourne, and Brisbane surgical hubs.
Strategic Opportunities
- Western Australia Penetration:Perth metropolitan surgical capacity remains underdeveloped relative to eastern seaboard cities, presenting first-mover positioning for ambulatory center networks.
- MBS Item Number Expansion:Federal Health Department reviews of obesity-related procedure listings may extend reimbursement to revision surgeries and adolescent metabolic interventions.
- Telehealth Preoperative Assessment:Remote patient evaluation protocols are reducing geographic barriers to specialist consultation, enabling regional patient funneling into metropolitan surgical queues.
Industry Challenges
- Specialized Nursing Recruitment:Bariatric ward nursing requires additional certification in postoperative metabolic monitoring, creating workforce pipeline constraints as unit volumes expand.
- Multidisciplinary Program Integration:Successful outcomes require coordinated dietetic, psychological, and endocrinological support, complicating service line economics for standalone surgical practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Bariatric Surgery Market |
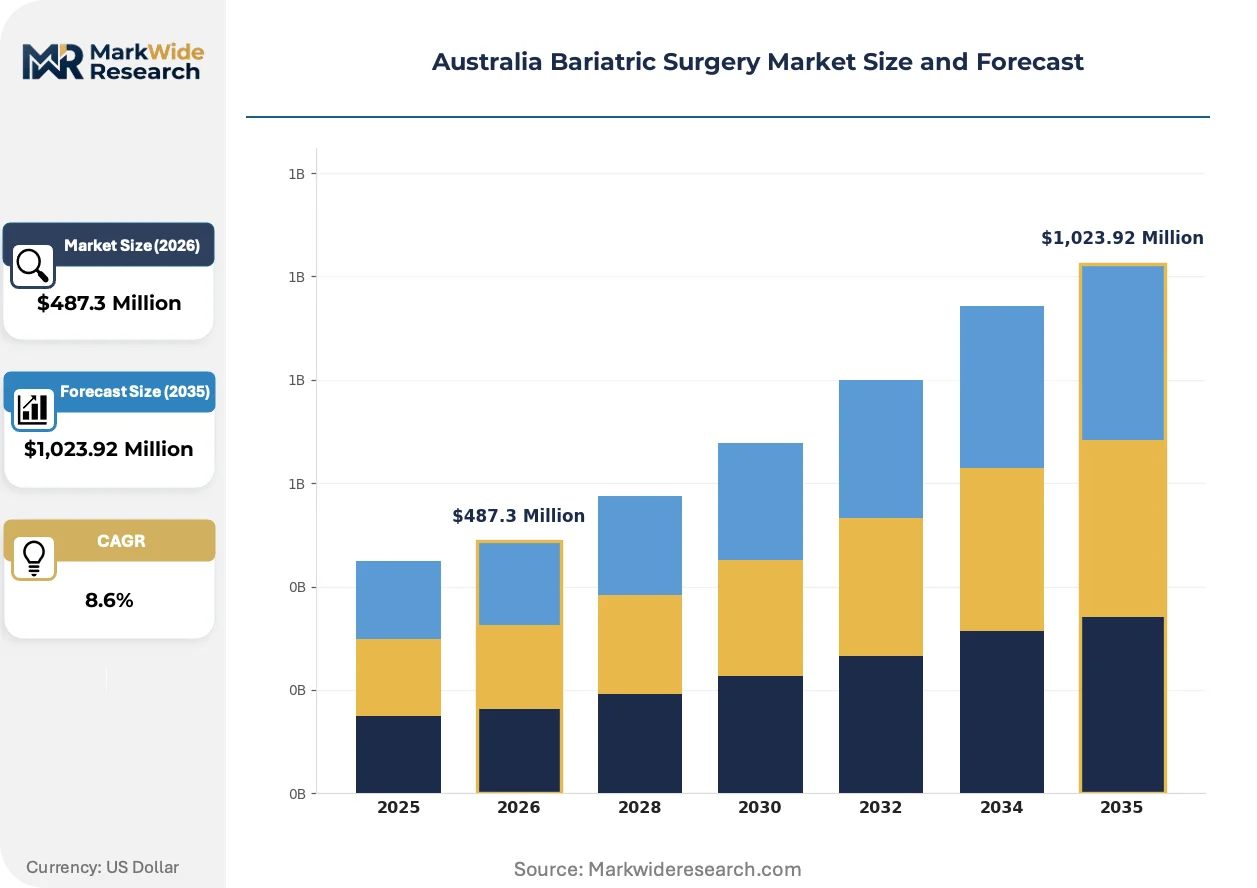
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Weight Loss Centers Technology: Laparoscopic, Robotic Surgery, Endoscopic, Open Surgery Patient Demographics: Obese Adults, Adolescents, Older Adults, Patients with Comorbidities |
| Companies Covered | Apollo Endosurgery Inc., B. Braun SE, Conmed Corporation, Intuitive Surgical Inc., Johnson & Johnson, Medtronic PLC, Olympus Corporation, The Cooper Companies, Inc., ReShape Lifesciences, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Bariatric Surgery Market Strategic Shifts
Digital surgical planning platforms and reimbursement pathway digitization are compressing patient journey timelines while reshaping how providers coordinate preoperative and postoperative care across Australia's fragmented public-private system.
Robotic-assisted sleeve gastrectomy is automating suturing precision and anatomical measurement during gastric resection, reducing operative variability. Private hospitals in Sydney and Melbourne are prioritizing capital allocation toward these installations. The technology is automating previously manual steps in staple line reinforcement, compressing training curves for newly credentialed surgeons.
TGA post-market surveillance requirements for implantable staplers have intensified adverse event reporting obligations, extending manufacturer compliance timelines. Device sponsors must now submit real-world performance data for five-year license renewals. Stapling platform suppliers are responding by embedding traceability chips and automated usage logging into instrument handles.
Patient self-referral through digital health platforms is displacing traditional general practitioner gatekeeping for initial bariatric surgery consultation. Telehealth-enabled direct-to-specialist booking engines are capturing younger, commercially insured demographics. This behavioral shift is most pronounced in Melbourne's inner suburbs where private practice marketing expenditure has pivoted toward social media patient education campaigns.
Australia Bariatric Surgery Market Segmentation
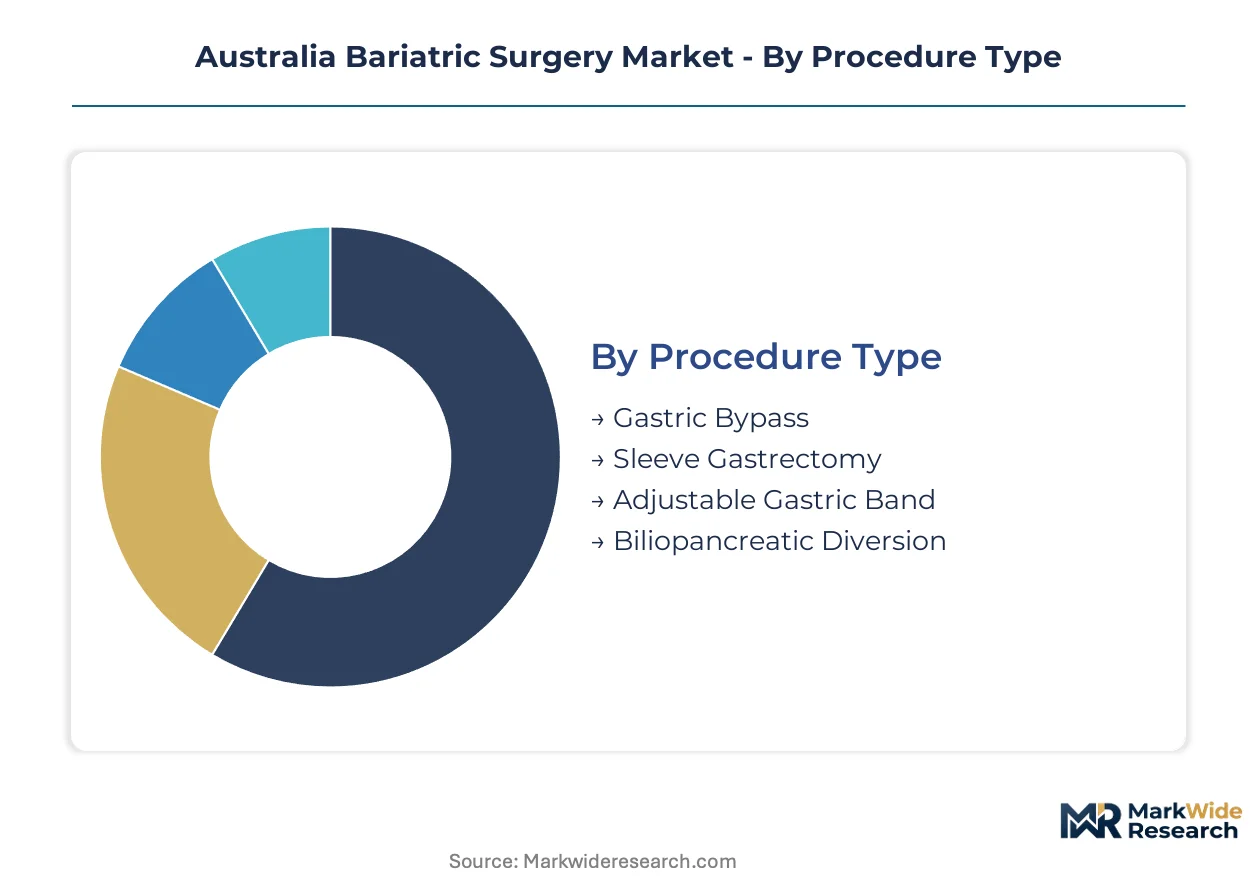
Procedure selection, technology platform, and care setting collectively determine reimbursement pathways and capital allocation priorities across Australian bariatric surgery networks. Understanding how these dimensions intersect reveals where volume concentrates and where emerging channels are capturing patient flow.
Procedure Type:
Upgrade cycles from adjustable bands to metabolic interventions are compressing as sleeve gastrectomy demonstrates superior long-term outcomes and reduced revision rates.
- Sleeve Gastrectomy:This vertical gastric resection removes approximately 80 percent of stomach volume while preserving pyloric function. Victorian and New South Wales public hospitals are prioritizing dedicated sleeve programs within their metabolic surgery unit expansions, driven by Medicare Benefit Schedule reimbursement stability and shorter operative times relative to bypass alternatives.
- Gastric Bypass:Roux-en-Y reconstruction alters both restriction and malabsorption pathways through gastrojejunal anastomosis. Tertiary centers in Sydney and Melbourne maintain bypass capacity for super-obese patients and revision cases, though volume share is contracting as sleeve techniques advance.
- Adjustable Gastric Band:Silicone band placement with subcutaneous port access dominates historical procedural volumes but now concentrates in revision and removal workflows. Band-related complications are accelerating conversion demand toward definitive metabolic procedures.
- Biliopancreatic Diversion:The most aggressive malabsorptive intervention, typically reserved for BMI thresholds exceeding 50 or failed prior procedures. Niche application in Australian practice reflects anesthesiology complexity and specialized nutritional support requirements.
Sleeve gastrectomy sits at the top of the volume ranking, with biliopancreatic diversion climbing the fastest among revision pathways as super-obese patient identification improves.
End User:
Capital intensity and staffing models fragment patient flow across institutional types, with reimbursement differentials determining where commercially insured versus public patients receive treatment.
- Hospitals:Tertiary public facilities anchor complex metabolic surgery through state-funded unit expansions, while private hospitals compete on robotic platform availability and hotel-style amenities.
- Ambulatory Surgical Centers:Lower-complexity sleeve procedures are migrating to standalone surgical facilities as anesthesiology protocols advance and private health funds pressure site-of-service economics. Perth metropolitan capacity remains underdeveloped relative to eastern seaboard penetration.
- Specialty Clinics:Private bariatric practices in Melbourne's inner suburbs are deploying direct-to-patient digital marketing to capture commercially insured demographics bypassing traditional GP referral channels.
- Weight Loss Centers:Integrated multidisciplinary programs combining surgical, dietetic, and psychological services command premium positioning but face workforce pipeline constraints for specialized nursing certification.
Hospitals retain dominant volume share, though ambulatory surgical centers are gaining share fastest as payor pressure intensifies site-of-service differentiation.
Technology:
Platform selection determines capital expenditure profiles, training curve duration, and TGA device license renewal obligations across Australian surgical networks.
- Laparoscopic:Standard-of-care access surgery through multiport or single-incision approaches dominates procedural economics. Medtronic PLC sustains platform investment through energy device and stapling portfolio integration.
- Robotic Surgery:Da Vinci system installations exceeding AUD 3 million per unit restrict penetration to metropolitan tertiary centers with philanthropic or state-funded capital access. Automated suturing precision during staple line reinforcement compresses variability for newly credentialed surgeons.
- Endoscopic:Transoral procedures including gastric balloon placement and endoscopic sleeve gastroplasty serve non-surgical candidates and bridge therapy roles. TGA pre-market assessment timelines for endoluminal platforms have compressed through streamlined pathways.
- Open Surgery:Conversion reserve for catastrophic intraoperative complications or reoperative abdominal scenarios. Minimal elective volume reflects laparoscopic technique maturation.
Laparoscopic platforms anchor current procedural volume, with robotic surgery expanding most quickly among capital-equipped private hospital networks.
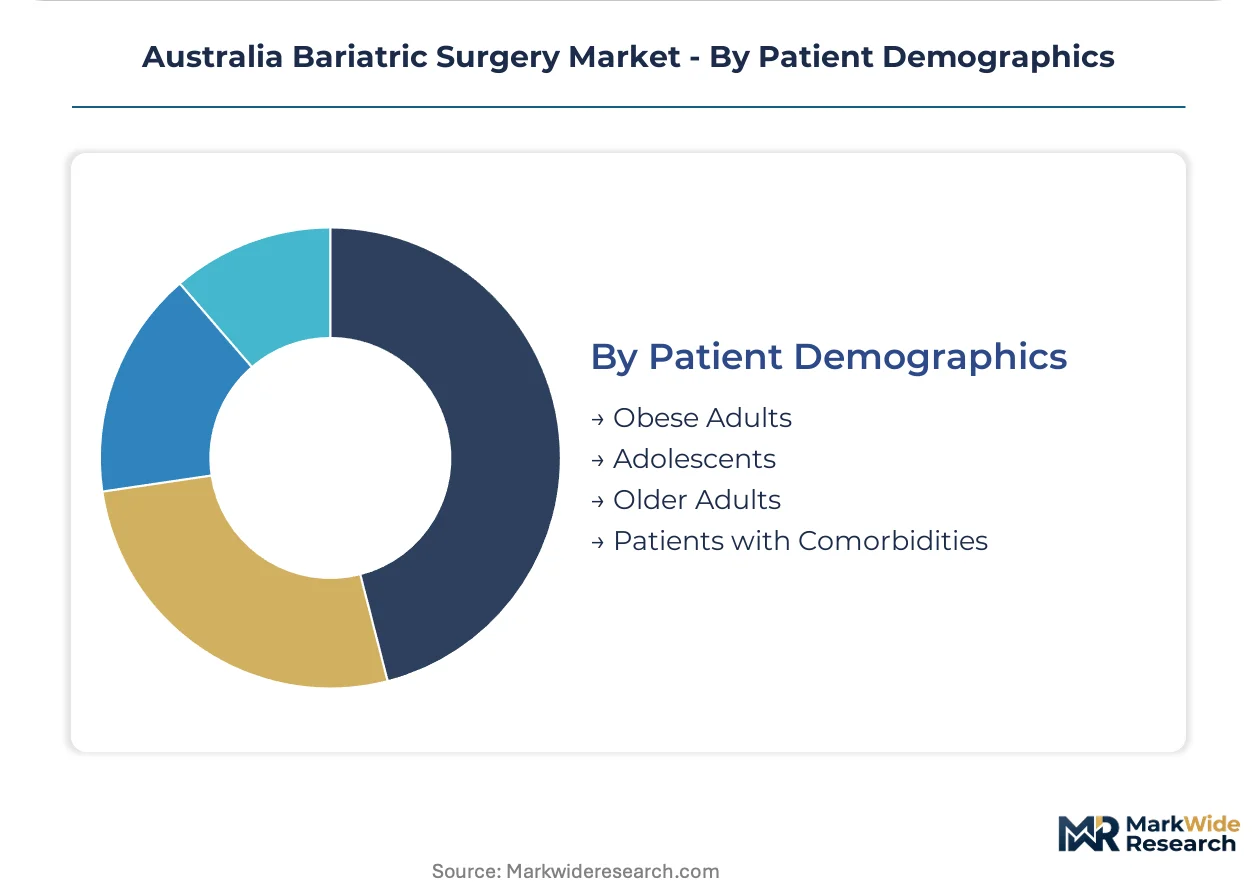
Patient Demographics:
Risk stratification and comorbidity burden determine procedure selection, anesthesiology resource allocation, and multidisciplinary program intensity across Australian treatment pathways.
- Obese Adults:Core demographic for sleeve gastrectomy and gastric bypass, with metabolic syndrome resolution driving procedure demand among working-age populations. Telehealth preoperative assessment protocols are reducing geographic barriers to specialist consultation for regional patient funneling.
- Patients with Comorbidities:Type 2 diabetes, hypertension, and obstructive sleep apnea severity influence procedure selection toward metabolic bypass options. Public hospital networks prioritize this segment through dedicated multidisciplinary intake pathways.
- Adolescents:Pediatric metabolic surgery remains constrained by limited Australian data and ethical review requirements, though international evidence is informing emerging tertiary center programs.
- Older Adults:Frailty assessment and cardiovascular risk stratification complicate candidacy determination, with procedural concentration in high-volume metropolitan centers possessing intensive care backup.
Obese adults represent the largest addressable population, while patients with comorbidities are deepening fastest as metabolic surgery gains recognition for disease modification beyond weight reduction alone.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in Australian healthcare given TGA's harmonized standards, yet state-level funding disparities create procedural access gaps that concentrate surgical migration toward better-resourced jurisdictions.
New South Wales
Sydney metropolitan surgical hubs anchor the nation's largest bariatric procedure volumes through tertiary public hospital networks. The state health department's metabolic surgery unit expansions reduce uninsured patient waitlists. Royal Prince Alfred Hospital and Westmead Hospital clusters drive laparoscopic platform adoption rates.
Victoria
Melbourne's inner suburbs concentrate private practice marketing expenditure toward direct-to-patient digital channels. Victorian public hospital funding commitments for dedicated bariatric units outpace other states. The Alfred Hospital and Monash Medical Centre anchor robotic surgery installations through state-philanthropic capital partnerships.
Queensland
Brisbane surgical hubs face anesthesiology workforce constraints that limit expansion beyond metropolitan boundaries. Queensland Health's metabolic surgery programs prioritize patients with diabetes comorbidities through multidisciplinary intake pathways. Royal Brisbane and Women's Hospital maintains bypass capacity for super-obese referrals.
Western Australia
Perth metropolitan surgical capacity remains underdeveloped relative to eastern seaboard cities, presenting first-mover positioning for ambulatory center networks. WA Health's bariatric service funding lags Victoria and New South Wales allocations. Sir Charles Gairdner Hospital anchors limited public metabolic surgery capacity.
South Australia
Adelaide's surgical volumes concentrate in hybrid public-private models given smaller absolute patient populations. SA Health maintains metabolic surgery programs at Flinders Medical Centre and Royal Adelaide Hospital. Regional patient funneling into metropolitan queues relies on telehealth preoperative assessment protocols.
Australia Bariatric Surgery Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue endoscopic and robotic-assisted platforms as differentiation vectors. Market structure consolidates around diversified surgical conglomerates with broad stapling and energy device portfolios. Three archetypes dominate: integrated surgical technology conglomerates, specialized bariatric device manufacturers, and robotic platform specialists. Competitive moves center on TGA pre-market pathway navigation and state hospital procurement contract capture.
Among diversified surgical technology conglomerates, Johnson & Johnson and Medtronic PLC occupy positions spanning multiple procedure categories and device classes. Intuitive Surgical Inc. anchors the robotic-assisted surgery tier through metropolitan tertiary center installations. These three entities exemplify distinct strategic postures: broad portfolio coverage, platform integration focus, and capital-intensive automation specialization respectively.
| Leading Market Players |
|---|
| Apollo Endosurgery Inc. |
| B. Braun SE |
| Conmed Corporation |
| Intuitive Surgical Inc. |
| Johnson & Johnson |
| Medtronic PLC |
| Olympus Corporation |
| The Cooper Companies, Inc. |
| ReShape Lifesciences, Inc. |
| Others |
Value Chain & Pricing Dynamics
Robotic-assisted surgical platform adoption simultaneously reshapes cost economics and supply concentration across Australian bariatric networks, compressing per-procedure margins at capital-equipped centers while concentrating procurement power among tertiary hospitals with philanthropic or state-funded installation programs. TGA medical device licensing requirements and Medicare Benefit Schedule reimbursement stability create divergent pricing power between metropolitan surgical hubs and regional facilities lacking robotic capacity.
Pricing Analysis
Distributor margins on implantable staplers and energy devices compress as hospital procurement committees consolidate vendor contracts through state-level tender frameworks. Pricing stratifies across premium robotic-assisted, standard laparoscopic, and economy band-conversion tiers, with brand premium and volume scale as primary differentiation drivers. Cost compression in laparoscopic device bundles intensifies as Medtronic PLC and Johnson & Johnson compete for exclusive supply agreements. Public hospital networks exhibit highest price sensitivity due to fixed state funding allocations, while private metropolitan centers prioritize technology premium over unit cost.
Supply Chain Analysis
TGA device license renewal obligations and ISO 13485 quality system certification gate supplier participation, filtering subscale manufacturers from implantable stapler and energy platform markets. Device manufacturing concentrates in the United States, Ireland, and Switzerland, with sterilization packaging and surgical instrument finishing drawing from Mexican and Malaysian contract facilities. Single-source vulnerability runs through specialized tungsten carbide staple formation components and robotic instrument sterilization trays. Distribution runs through Johnson & Johnson's Ethicon surgical supply network and Medtronic's direct hospital service models, with regional Queensland and Western Australia facing extended logistics lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in robotic platform utilization efficiency and ambulatory center site-of-service economics, with telehealth-enabled patient funneling reducing customer acquisition cost intensity for private practice networks.
For Market Incumbents: Hedge against ambulatory surgical center channel displacement by securing exclusive stapling and energy device contracts with expanding standalone facility networks in Perth and Adelaide. Prioritize TGA post-market surveillance compliance investment to maintain five-year license renewal velocity amid intensified adverse event reporting obligations. Vertical integration into remote patient monitoring software creates defensive positioning against telehealth-native entrants capturing preoperative assessment workflows. For New Entrants and Emerging Players: Private health fund preferred provider networks offer the most penetrable channel architecture, particularly for digitally-enabled patient acquisition platforms targeting Melbourne's inner suburbs. Western Australia's underdeveloped ambulatory center infrastructure presents geographic whitespace for sleeve gastrectomy-focused standalone facilities. Direct-to-specialist booking engines bypassing traditional GP referral gatekeeping capture younger, commercially insured demographics with lower price elasticity. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale robotic surgery service providers with underutilized Da Vinci system capacity and established hospital concession agreements. Long-term viability hinges on Medicare Benefit Schedule item number expansion for revision surgeries and adolescent metabolic interventions. Watch MBS review committee obesity-related procedure listing decisions as the primary inflection signal for volume acceleration in public hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| MBS Item Number Expansion | Federal Health Department reimbursement listing revisions would unlock public hospital volume for revision surgeries. |
| Robotic Platform Installation | Metropolitan tertiary center Da Vinci system deployments compress training curves for newly credentialed surgeons. |
| Telehealth Preoperative Assessment | Remote patient evaluation protocols reduce geographic barriers funneling regional patients into surgical queues. |
| Ambulatory Center Network Buildout | Perth metropolitan capacity expansion captures site-of-service economics as private health funds pressure inpatient alternatives. |
| TGA Streamlined Pathway Navigation | Accelerated pre-market assessment timelines compress product launch cycles for stapling platforms and energy devices. |
Study Parameters
Coverage spans New South Wales, Victoria, Queensland, Western Australia, and South Australia, with primary inputs from each state's public health department metabolic surgery program directors. The analysis combines structured interviews with bariatric surgeons, hospital procurement committee members, biomedical engineers, and private health fund policy managers with secondary validation through TGA medical device register entries, Medicare Benefit Schedule determinations, and state hospital funding allocation disclosures. Bottom-up procedural volume estimates triangulate against top-down device shipment data and hospital capacity expansion announcements.
Rate-of-change decomposition across procedure type, technology platform, end-user setting, and patient demographic risk stratification anchors the analytical framework over the projection horizon. CAGRs derive from segmented volume modeling incorporating MBS reimbursement trajectory assumptions, state hospital capital commitment schedules, and private health fund coverage tier evolution. Forecast inputs include anesthesiology workforce pipeline projections, robotic system installation timelines, and TGA regulatory pathway velocity indicators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Federal Health Department MBS review timing and state-level metabolic surgery funding allocation volatility. Deviation in private health fund obesity-related procedure exclusion policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
United Kingdom Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Bariatric Transport Wheelchairs Market