
 Global Bariatric Surgical Devices Market | 2026-2036
Global Bariatric Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bariatric Surgical Devices Market Foresight
Premium robotic-assisted specifications is bifurcating the competitive landscape into high-precision and conventional manual tiers. Intuitive Surgical leverages its da Vinci platform to dominate minimally invasive bariatric procedures. Medtronic anchors its position through broad laparoscopic instrument portfolios and sustained R&D spending on stapling technologies. Johnson & Johnson differentiates via Ethicon's energy devices and suture systems that occupy critical steps in Roux-en-Y and sleeve gastrectomy workflows.
Bariatric surgical devices encompass instruments, implants, and energy systems designed to alter gastrointestinal anatomy for weight reduction, typically constructed from biocompatible polymers, stainless steel, or titanium alloys with tensile strengths exceeding 800 MPa for staple line integrity. Gastric sleeve tools command the largest revenue share due to procedure volume dominance, while adjustable devices represent the fastest-expanding category as revisional surgery rates climb. Ambulatory surgery centers are capturing volume from traditional hospital settings as same-day discharge protocols for laparoscopic procedures gain clinical acceptance across North America and Western Europe.
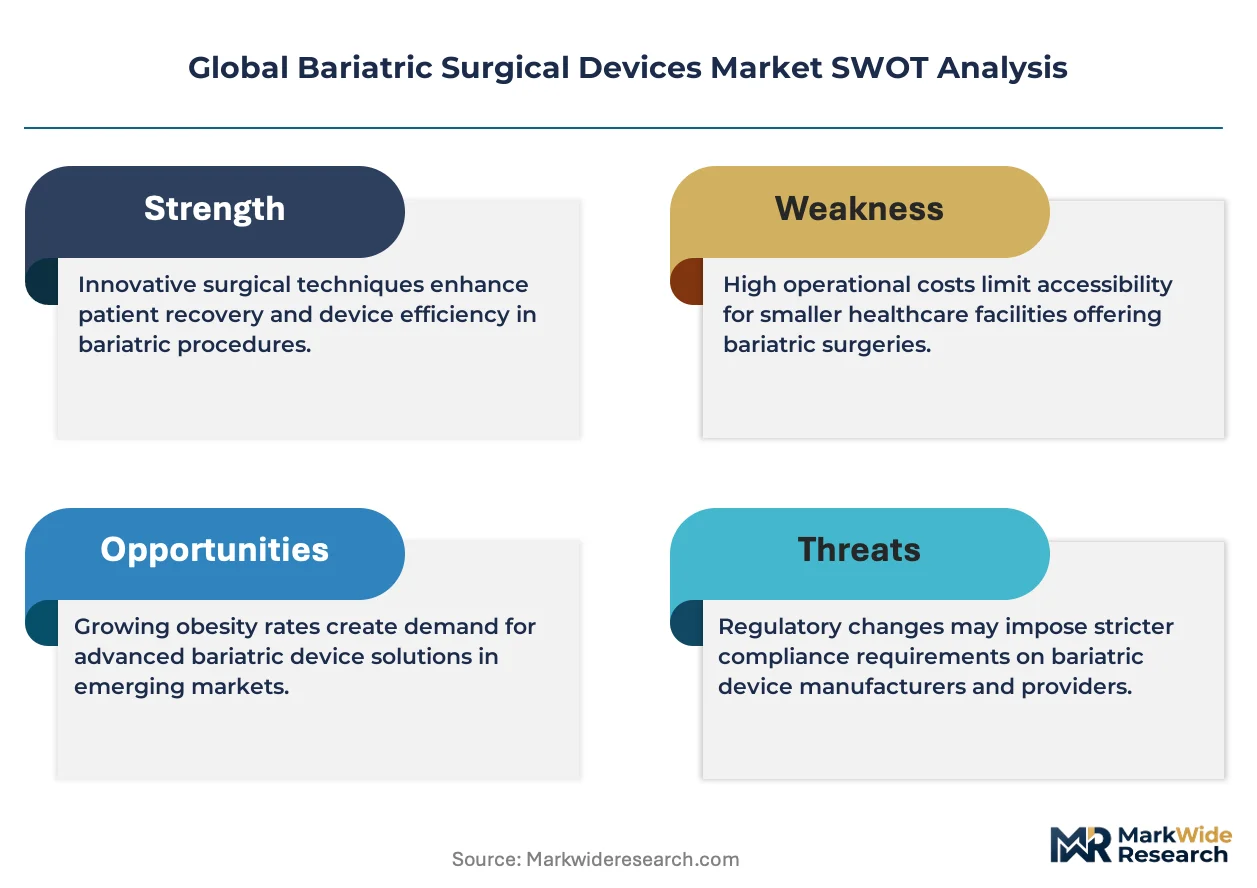
FDA 510(k) clearance requirements and EU MDR conformity assessments impose substantial clinical validation burdens that filter out undercapitalized entrants. The EPA regulates sterilization byproduct emissions from device reprocessing facilities, adding operational compliance layers for hospitals and third-party reprocessors. Stakeholders must monitor evolving NICE and CMS reimbursement decisions for metabolic surgery indications beyond body mass index thresholds, as expanded coverage criteria would directly shift procedure volumes and device procurement cycles.
Market Dynamics
Robotic-assisted surgical platforms are fragmenting the bariatric device landscape into precision-tier and manual-tier supply chains, with hospital procurement committees now evaluating total cost of ownership against clinical outcome metrics rather than per-procedure instrument costs alone.
Growth Catalysts
- Metabolic surgery reimbursement expansion:CMS coverage criteria for type 2 diabetes remission indications in the United States are widening patient eligibility pools beyond traditional body mass index thresholds.
- Laparoscopic stapler material advances:Titanium-nitride coated cartridges with enhanced tissue compression profiles are reducing staple line leak rates in sleeve gastrectomy procedures.
- Ambulatory facility accreditation growth:Medicare-certified ambulatory surgery centers in Germany and Japan are adding bariatric suites to capture same-day discharge volumes.
Market Restraints
- EU MDR clinical evidence burdens:Extended conformity assessment timelines for class IIb implantable devices are delaying market access for novel adjustable gastric band designs.
- Specialized surgeon supply constraints:Fellowship-trained bariatric surgeons concentrate in urban academic medical centers, limiting procedure access in secondary metropolitan markets.
- Reprocessing compliance costs:EPA emissions controls on ethylene oxide sterilization facilities are raising operational expenditures for hospitals and third-party reprocessors handling laparoscopic instrument fleets.
Strategic Opportunities
- Revisional surgery instrument demand:Adjustable gastric band-to-sleeve conversion procedures in Australia are creating specialized retractor and stapler requirements distinct from primary bariatric cases.
- Single-use energy device adoption:Battery-powered ultrasonic shears are penetrating ambulatory settings where reprocessing infrastructure investments prove uneconomical.
- Japan PMDA fast-track pathways:Breakthrough designation for robotic suturing systems is compressing premarket review timelines for novel anastomosis technologies.
Industry Challenges
- OR integration complexity:Robotic platform installation requires structural modifications to existing laparoscopic suites, extending capital deployment cycles.
- Surgeon retraining mandates:Proctoring requirements for robotic certification are bottlenecking adoption in community hospital settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bariatric Surgical Devices Market |
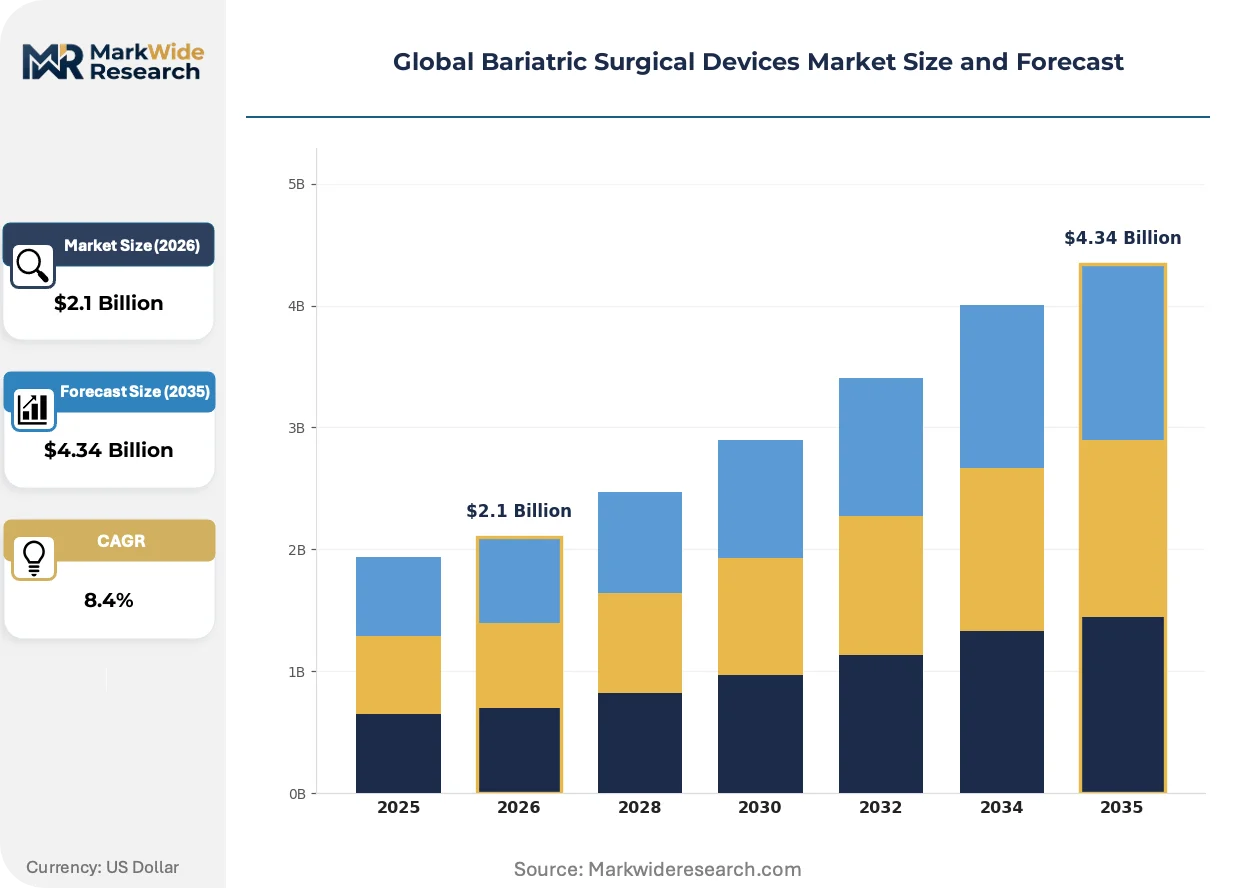
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gastric Bands, Gastric Balloons, Roux-en-Y Devices, Gastric Sleeve Tools, Adjustable Devices Therapy Area: Morbid Obesity, Type 2 Diabetes, Metabolic Syndrome, Weight Management, Hypertension End User: Specialty Clinics, Outpatient Facilities, Medical Centers, Ambulatory Surgery Centers, Bariatric Practices Distribution Channel: Direct Sales, Medical Distributors, Online Medical Marketplaces, Hospital Procurement, Third-Party Suppliers |
| Companies Covered | Intuitive Surgical, Conmed Corporation, Medtronic, Spatz FGIA, Stryker Corporation, Johnson & Johnson, Olympus Corporation, ReShape Lifesciences, Boston Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bariatric Surgical Devices Market Shifts & Advancements
Digital surgical planning and intraoperative navigation are redefining precision benchmarks in metabolic procedures, with software-enabled device ecosystems now competing on prediction accuracy rather than mechanical specifications alone.
Artificial intelligence-powered preoperative risk stratification is decomposing traditional patient selection workflows. Academic medical centers in the United States are deploying machine learning models to predict complication probability profiles. This capability is compressing variability in surgical outcomes and redistributing high-complexity cases toward quaternary referral networks.
EU MDR post-market surveillance requirements are mandating extended follow-up registries for implantable bariatric devices. Manufacturers must now submit periodic safety update reports spanning five-year intervals. Adjustable gastric band producers face disproportionate documentation burdens as long-term explantation data accumulates across European notified body jurisdictions.
Hospital purchasing consortia are consolidating device procurement under centralized contracting vehicles. Integrated delivery networks in the United States are unbundling service contracts from capital equipment leases. This restructuring favors suppliers with transparent lifecycle cost models and penalizes vendors reliant on disposable recurring revenue streams.
Global Bariatric Surgical Devices Market Segmentation
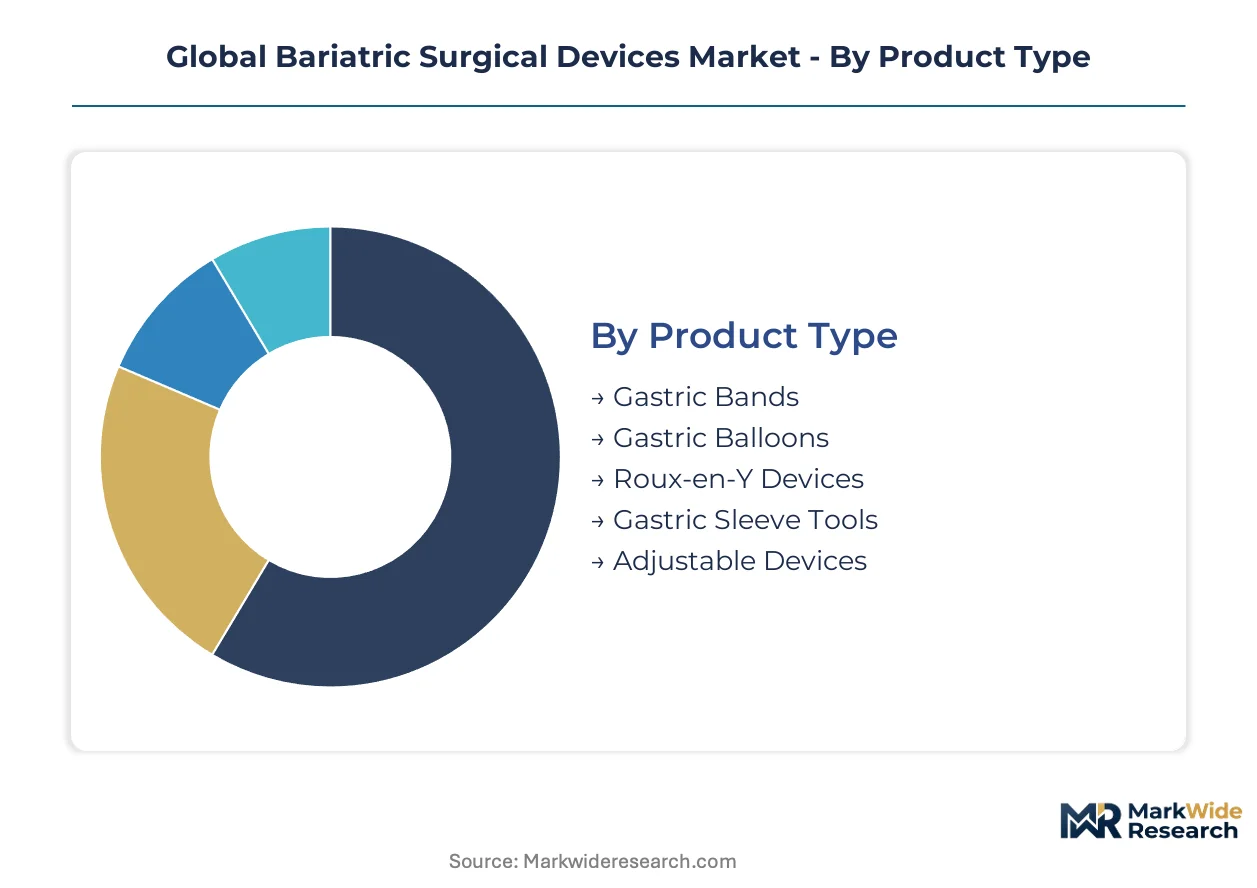
Device selection in bariatric surgery hinges on anatomical target, metabolic indication, and facility infrastructure. Procurement committees evaluate total cost of ownership across stapler cartridges, energy platforms, and implantable systems rather than isolated instrument pricing.
Product Type:
Margin pools concentrate in reusable energy platforms and precision stapling systems where hospital capital budgets allocate disproportionately to robotic-compatible specifications.
- Gastric Sleeve Tools:Titanium-nitride coated stapler cartridges deliver tissue compression profiles exceeding 800 MPa tensile strength for staple line integrity. Demand clusters in United States academic medical centers where same-day discharge protocols for sleeve gastrectomy dominate procedure economics.
- Adjustable Devices:Silicone elastomer bands with subcutaneous port systems enable postoperative restriction modulation. Revisional surgery rates in Australia and Germany are expanding explant-to-conversion workflows that require specialized retrieval instrumentation.
- Gastric Bands:Laparoscopic implantable restriction systems with saline-filled chambers.
- Gastric Balloons:Transient intragastric space-occupying devices for pre-surgical weight loss.
- Roux-en-Y Devices:Anastomosis staplers and linear cutters for gastric bypass reconstruction.
Gastric sleeve tools hold installed capacity. Adjustable devices are rotating up the share rankings.
Therapy Area:
Reimbursement coding density varies sharply across metabolic indications, with diabetes remission claims commanding premium device specifications in United States and Japanese markets.
- Type 2 Diabetes:Metabolic surgery indications beyond body mass index thresholds now qualify for CMS coverage in the United States. PMDA fast-track designations in Japan are compressing premarket review timelines for glucose-lowering surgical technologies.
- Morbid Obesity:Traditional body mass index-based eligibility criteria anchor procedure volumes in European Union markets where MDR conformity assessments filter device entrants.
- Metabolic Syndrome:Clustered cardiovascular risk factors driving multi-morbidity surgical candidacy.
- Weight Management:Lifestyle-intervention adjunctive procedures in ambulatory settings.
- Hypertension:Blood pressure remission as secondary surgical outcome measure.
Morbid obesity holds installed capacity. Type 2 diabetes is rotating up the share rankings.
End User:
Capital deployment cycles diverge between integrated delivery networks and independent ambulatory facilities, with procurement authority centralizing under hospital consortium contracting vehicles.
- Ambulatory Surgery Centers:Medicare-certified facilities in Germany and Japan are adding dedicated bariatric suites for same-day discharge protocols. Battery-powered ultrasonic shears penetrate these settings where reprocessing infrastructure investments prove uneconomical.
- Medical Centers:Quaternary referral networks in the United States concentrate fellowship-trained bariatric surgeons and robotic platform installations requiring structural OR modifications.
- Specialty Clinics:Focused metabolic surgery practices with high procedural throughput.
- Outpatient Facilities:Same-day discharge-capable sites with limited overnight observation capacity.
- Bariatric Practices:Physician-owned surgical groups with hybrid hospital affiliations.
Medical centers hold installed capacity. Ambulatory surgery centers are rotating up the share rankings.
Distribution Channel:
Channel economics shift as integrated delivery networks unbundle service contracts from capital equipment leases, favoring suppliers with transparent lifecycle cost models.
- Hospital Procurement:Centralized contracting through United States purchasing consortia is consolidating vendor selection under multi-year framework agreements. EPA emissions controls on ethylene oxide sterilization are raising operational expenditures that procurement committees offset through disposable volume commitments.
- Direct Sales:Manufacturer field representatives negotiate robotic platform installations with extended proctoring and certification service attachments.
- Medical Distributors:Regional inventory-holding intermediaries with instrument repair capabilities.
- Online Medical Marketplaces:Digital procurement portals for standardized consumables and accessories.
- Third-Party Suppliers:Independent reprocessors facing EPA compliance cost pressures.
Hospital procurement holds installed capacity. Direct sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in bariatric surgical devices tilt toward net imports in emerging markets while the United States and Germany maintain manufacturing surpluses in precision stapling systems. Currency fluctuations and MDR transition costs are reshaping procurement patterns across European hospital networks.
United States
CMS reimbursement expansion for type 2 diabetes remission procedures is widening patient eligibility pools beyond traditional BMI thresholds. FDA 510(k) clearance pathways impose substantial clinical validation burdens that filter out undercapitalized device entrants. Fellowship-trained bariatric surgeons concentrate in urban academic medical centers across the Northeast Corridor and California, limiting procedure access in secondary metropolitan markets.
Germany
Medicare-certified ambulatory surgery centers are adding dedicated bariatric suites to capture same-day discharge volumes for laparoscopic sleeve procedures. EU MDR conformity assessment timelines for class IIb implantable devices are delaying market access for novel adjustable gastric band designs. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host precision instrument manufacturers supplying stapler cartridge production lines.
Japan
PMDA fast-track designations for robotic suturing systems are compressing premarket review timelines for novel anastomosis technologies. METI industrial policy supports domestic production of minimally invasive surgical platforms through targeted R&D subsidies. The Kanto region surrounding Tokyo anchors quaternary referral networks where robotic platform installations require structural OR modifications.
Australia
Revisional surgery rates are expanding explant-to-conversion workflows that require specialized retrieval instrumentation distinct from primary bariatric cases. TGA regulatory frameworks align with international standards while maintaining supplementary clinical evidence requirements for implantable restriction devices. Sydney and Melbourne metropolitan areas concentrate accredited bariatric practices with hybrid hospital affiliations.
India
CDSCO medical device regulations are harmonizing with international standards while maintaining domestic manufacturing incentives through PLI scheme allocations. Cost-sensitive procurement patterns in private hospital chains favor reusable energy platforms over disposable alternatives. Industrial corridors in Maharashtra and Gujarat host contract manufacturers producing laparoscopic instrument components for export markets.
Global Bariatric Surgical Devices Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that leverage broad surgical instrument portfolios across metabolic, oncologic, and general surgery applications. The vendor base separates into precision-tier robotic platform suppliers and conventional manual instrument specialists. Two strategic archetypes dominate: integrated surgical ecosystem providers bundling capital equipment with disposable recurring revenue streams, and focused component suppliers concentrating on single-procedure instrument categories. Competitive moves center on OR integration partnerships with hospital networks and proctoring service attachments that lock in surgeon certification pathways.
Among diversified conglomerates, Intuitive Surgical, Medtronic, and Johnson & Johnson occupy positions spanning the precision-tier and manual-tier segments. Intuitive Surgical exemplifies the integrated ecosystem archetype through its da Vinci platform dominance in minimally invasive procedures. Medtronic anchors scale-driven supply relationships through sustained R&D positioning in stapling technologies. Johnson & Johnson represents the diversified portfolio approach via Ethicon-branded energy devices and suture systems occupying critical procedural steps.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Conmed Corporation |
| Medtronic |
| Spatz FGIA |
| Stryker Corporation |
| Johnson & Johnson |
| Olympus Corporation |
| ReShape Lifesciences |
| Boston Scientific |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for titanium-nitride coated stapler cartridges concentrate procurement leverage among United States and German hospital purchasing consortia, compressing margin pools for component suppliers while amplifying pricing power for integrated device manufacturers with captive forging capacity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across FDA 510(k) cleared premium specifications, standard MDR-compliant tiers, and economy-grade manual instruments. Price differentiation hinges on robotic platform compatibility and after-sales proctoring service bundling. Cost compression in standard laparoscopic tiers intensifies because ambulatory surgery centers prioritize disposable volume commitments over capital equipment leases. Community hospital procurement committees exhibit highest price sensitivity; quaternary academic medical centers demonstrate lowest sensitivity due to outcome-based reimbursement alignment.
Supply Chain Analysis
Port congestion on trans-Pacific lanes from Shanghai to Long Beach elevates inbound logistics costs for stainless steel instrument blanks sourced from Chinese contract forgers. Manufacturing gravity centers on Germany, Japan, and the United States for precision stapling systems, with titanium alloy feedstock drawing from Japanese and Russian smelters. Single-source vulnerability concentrates in specialized polymer extrusion for adjustable gastric band silicone elastomers. Distribution runs through hospital procurement consortia and manufacturer direct sales forces with attached certification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States and European hospital alliance formation, fragmenting vendor access and forcing transparent lifecycle cost disclosure.
For Market Incumbents: Compound platform stickiness through robotic certification pathway lock-in and backward integration into titanium alloy forging capacity. Defend against emerging single-use energy device entrants by embedding disposable recurring revenue into capital equipment lease structures. Prioritize EPA compliance service bundling to offset sterilization cost pressures on hospital reprocessing operations. For New Entrants and Emerging Players: Differentiate on revisional surgery instrumentation specialization, targeting explant-to-conversion workflows in Australia and Germany where retrieval tool requirements diverge from primary cases. Penetrate Medicare-certified ambulatory surgery centers in Japan with battery-powered ultrasonic shears where reprocessing infrastructure investments prove uneconomical. Pursue PMDA fast-track designation for anastomosis technologies to compress premarket review timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates divesting non-core metabolic surgery portfolios amid OR integration complexity and surgeon retraining mandate pressures. Long-term viability favors integrated ecosystem providers with transparent service contract unbundling capabilities. Monitor CMS reimbursement decisions for type 2 diabetes remission indications as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Locks in multi-year disposable volume commitments through GPO contracting vehicles. |
| FDA Submission Pathway | 510(k) clearance for titanium-nitride coated cartridges accelerates academic medical center adoption. |
| CE Marking Pathway | MDR conformity assessment compliance enables European ambulatory surgery center penetration. |
| Software Companion Development | AI-powered preoperative risk stratification differentiates robotic platform ecosystems. |
| Reimbursement Strategy | CMS coverage expansion for diabetes remission indications widens addressable patient pools. |
Research Methodology
A spread of perspectives from bariatric surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions through structured primary interviews. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up procedure volume estimates and top-down device revenue aggregates were triangulated to anchor market sizing.
Segmentation dimensions modeled span product type, therapy area, end user facility tier, and distribution channel across the projection horizon. CAGRs were derived from procedure volume trajectories and per-procedure device intensity assumptions. Forecast inputs incorporated PMDA fast-track designation timelines, MDR transition cost impacts, and ambulatory surgery center accreditation expansion rates.
Decision-makers should treat outputs as directional under assumptions of stable CMS reimbursement frameworks and EPA emissions compliance cost trajectories; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
South Africa Bariatric Surgery Market