
 Spain Bariatric Surgery Market | 2026-2036
Spain Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Bariatric Surgery Market Analytics
Spain is rewriting the Mediterranean bariatric landscape through sustained investment in robotic surgical infrastructure across its autonomous communities. Medtronic leverages its integrated surgical ecosystem to dominate supply relationships with major public hospital consortia in Catalonia and Andalusia. Johnson & Johnson sustains competitive positioning through its broad portfolio spanning stapling, energy devices, and suture platforms for complex metabolic procedures. Intuitive Surgical anchors the premium segment with da Vinci system placements in tertiary referral centers performing high-volume sleeve gastrectomy and gastric bypass operations.
Bariatric surgery encompasses a range of metabolic and gastrointestinal procedures designed to induce weight loss through restriction, malabsorption, or combined physiological mechanisms, typically requiring specialized stapling devices, energy platforms, and laparoscopic instrumentation with precision tolerances measured in millimeters. Sleeve gastrectomy now leads procedure volume in Spanish public hospitals due to shorter operative times and reduced nutritional complication profiles compared to Roux-en-Y gastric bypass. Robotic-assisted technology represents the fastest-expanding modality as regional health services negotiate bundled service contracts for advanced platforms. Hospitals capture the dominant end-user share, though ambulatory surgical centers are gaining selective cases as enhanced recovery protocols shorten length-of-stay requirements.
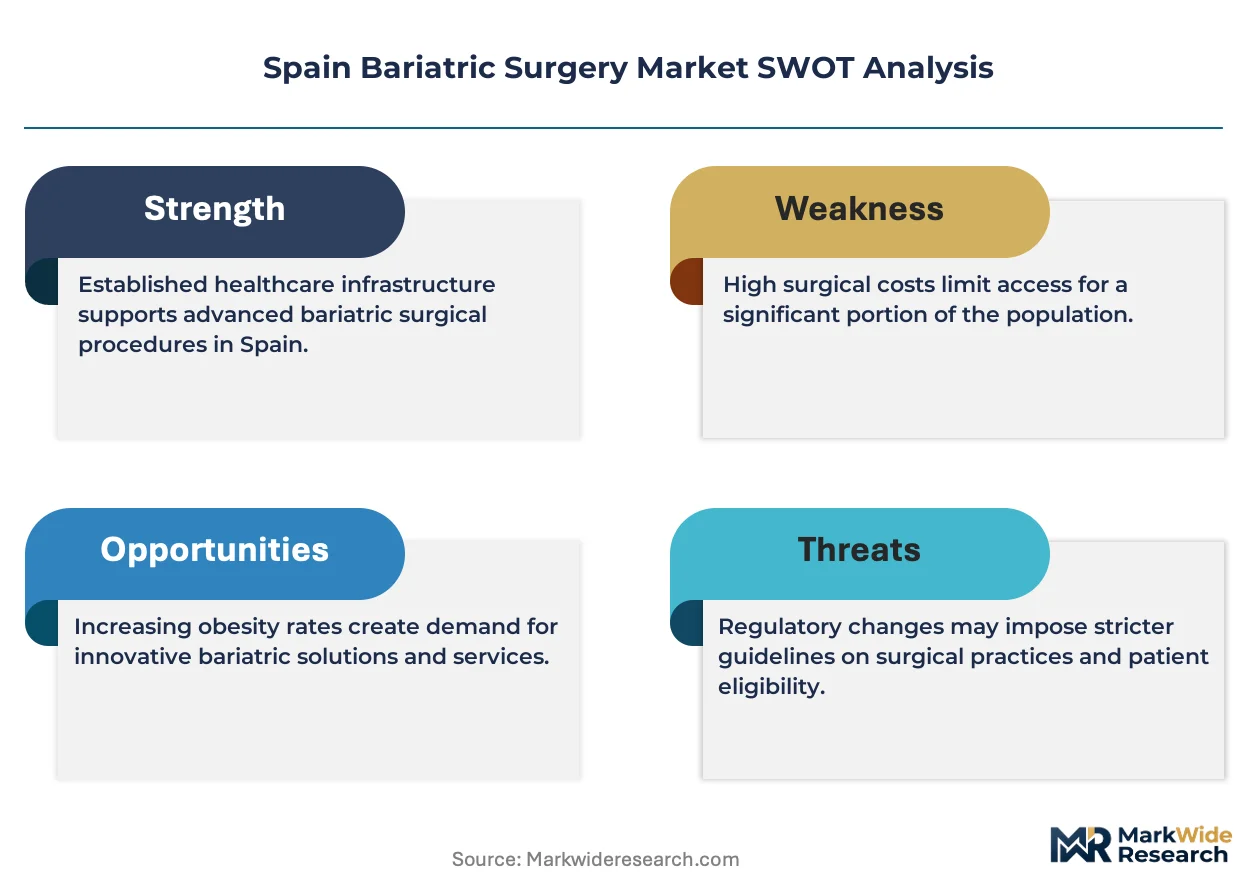
Spain's Ministry of Health, the Spanish Agency for Medicines and Health Products (AEMPS), and regional health authorities across autonomous communities enforce medical device registration, surgical facility accreditation, and reimbursement eligibility criteria that directly determine market access for implantable and capital equipment. The AEMPS maintains CE marking alignment under EU Medical Device Regulation transition timelines while imposing additional national vigilance reporting obligations for serious adverse events in metabolic surgery. Stakeholders must monitor how regional health spending autonomy interacts with centralized procurement frameworks as robotic platform adoption accelerates beyond current budget allocation models.
Market Dynamics
Spain's bariatric surgery market is restructuring around regional health authority procurement consolidation and the shift toward bundled robotic platform contracts that replace traditional device-by-device purchasing.
Growth Catalysts
- Public Hospital Network Expansion:Regional health services in Catalonia and Andalusia are scaling metabolic surgery programs to address diabetes prevalence, creating sustained demand for specialized stapling and energy platforms.
- EU Medical Device Regulation Alignment:AEMPS harmonization with MDR transition timelines is streamlining market access pathways for CE-marked surgical devices, reducing registration friction for qualified manufacturers.
- Robotic-Assisted Modality Adoption:Autonomous communities are negotiating system-wide service agreements for advanced surgical platforms, accelerating capital equipment refresh cycles beyond historical replacement rates.
Market Restraints
- Capital Equipment Concentration:Robotic platform supply concentrates among a limited vendor base, creating procurement bottlenecks as multiple regional health services compete for simultaneous system deployments.
- Reimbursement Protocol Rigidity:National Health System bariatric surgery eligibility criteria impose strict patient selection thresholds that cap addressable procedure volumes regardless of underlying disease burden.
- Specialized Workforce Scarcity:Certified metabolic surgeons and robotic console operators remain concentrated in Madrid and Barcelona, constraining program expansion into secondary cities.
Strategic Opportunities
- Ambulatory Surgical Center Penetration:Enhanced recovery protocols are enabling selective sleeve gastrectomy cases to migrate from tertiary hospitals to licensed day-surgery facilities in Valencia and Seville.
- Integrated Service Contracting:Regional consortia are piloting per-procedure leasing models that bundle capital equipment, disposables, and maintenance, creating recurring revenue structures for platform vendors.
- Cross-Autonomous Community Procurement:Centralized purchasing frameworks under the Interterritorial Council are enabling volume aggregation across Spain's seventeen regions, favoring suppliers with national service capabilities.
Industry Challenges
- CE Marking Transition Complexity:Manufacturers face compressed timelines to migrate technical documentation to MDR requirements while maintaining AEMPS vigilance reporting compliance for adverse event tracking.
- Robotic Console Utilization Optimization:Hospitals struggle to achieve target case volumes per system given procedure scheduling constraints and surgeon availability, pressuring return-on-investment calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Bariatric Surgery Market |
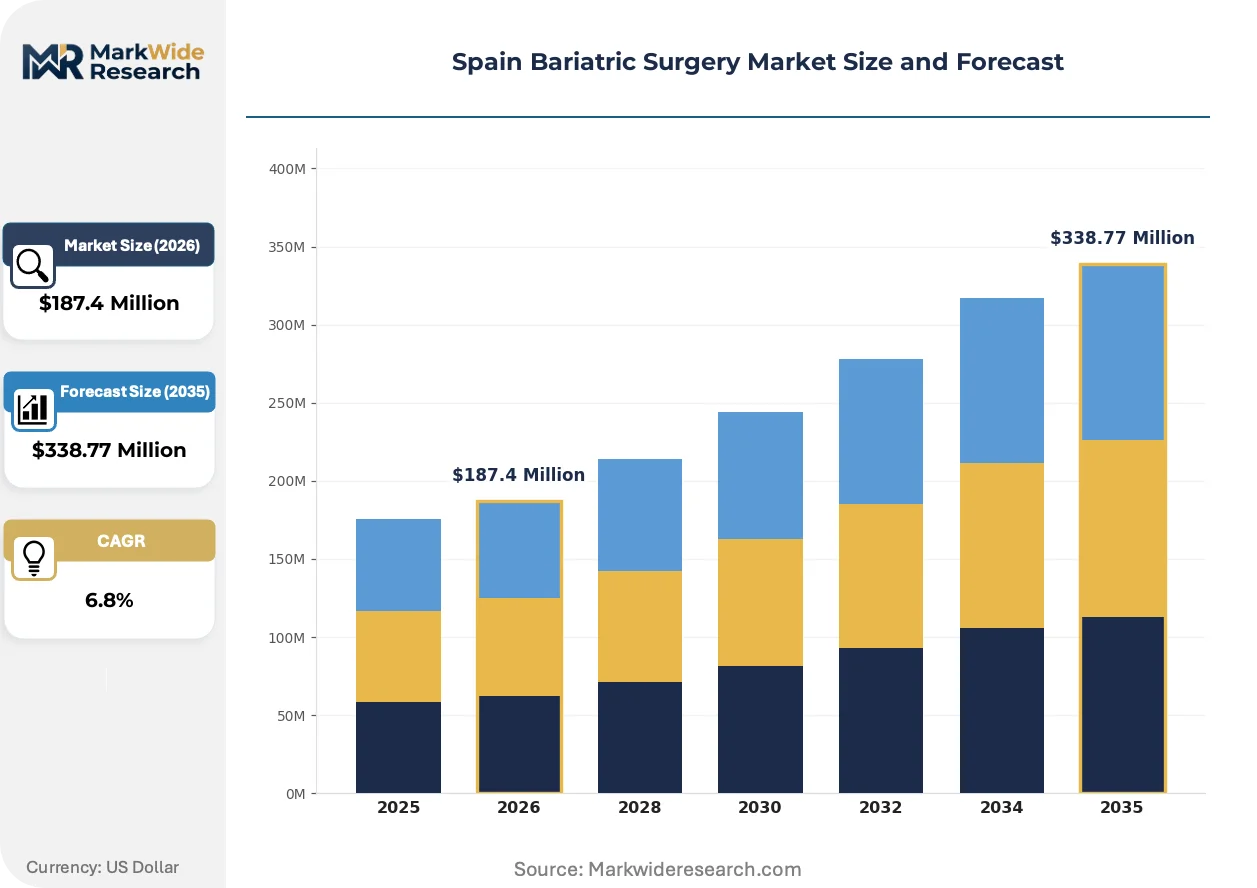
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Laparoscopic, Robotic-Assisted, Endoscopic, Traditional Open Surgery Patient Demographics: Adolescents, Adults, Seniors, Obese Individuals |
| Companies Covered | Medtronic, Apollo Endosurgery, Teleflex, Intuitive Surgical, Spatz FGIA, TransEnterix, USGI Medical, Johnson & Johnson, Olympus Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Bariatric Surgery Market Evolving Landscape
Spain's bariatric surgical landscape is converging toward precision instrumentation, intelligent energy platforms, and reconfigured care delivery models that compress length-of-stay while expanding procedure access.
Single-use advanced energy devices with integrated tissue-sensing algorithms are rendering obsolete reusable electrosurgical platforms that require sterilization infrastructure and carry cross-contamination liability. Public hospitals in Madrid are standardizing on these disposable systems for sleeve gastrectomy programs, compressing operative setup times and reducing central sterilization department throughput constraints.
AEMPS enforcement of EU Medical Device Regulation post-market surveillance obligations is intensifying adverse event documentation requirements for implantable and capital surgical equipment. Manufacturers must now maintain systematic vigilance databases that feed into centralized European repositories, with non-compliance triggering market withdrawal procedures that affect entire product families.
Patient selection protocols are tightening around multidisciplinary team evaluation mandates that require endocrinology, nutrition, and psychology clearance prior to surgical authorization. This behavioral shift is lengthening pre-operative pathways in public hospital networks while creating parallel private-channel demand for streamlined assessment programs in Barcelona and Madrid metropolitan areas.
Spain Bariatric Surgery Market Segmentation
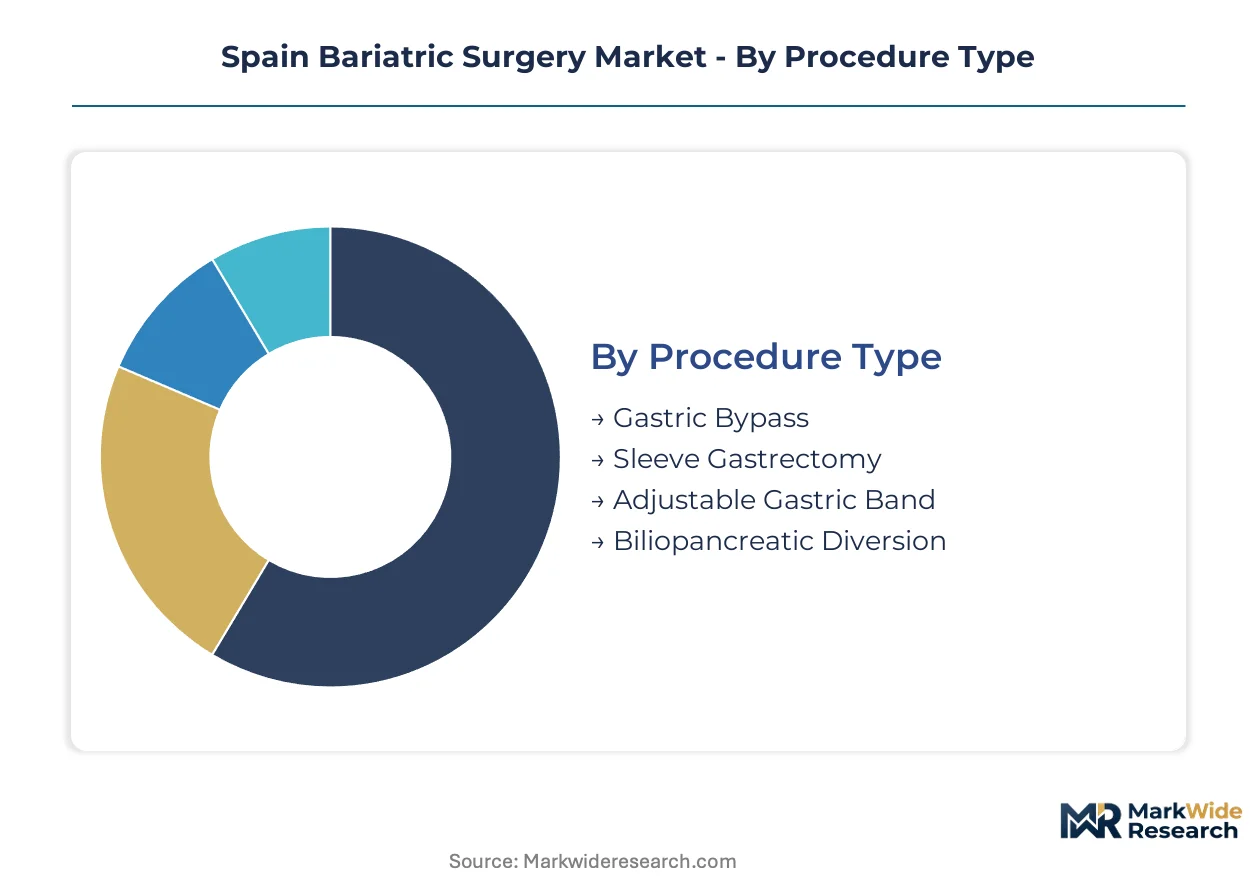
Procedure mix and technology modality choices in Spain's bariatric surgery market determine capital allocation cycles, consumable replenishment rates, and service contract structures across autonomous communities. Segmentation reveals where robotic platforms displace laparoscopic baselines and which patient cohorts drive volume concentration in Madrid and Barcelona's tertiary centers.
Procedure Type:
Sleeve gastrectomy turns over fastest in public hospital networks due to standardized operative workflows and shorter anesthesia times, while biliopancreatic diversion cycles slowest given complexity and selective patient candidacy.
- Sleeve Gastrectomy:Resection of the gastric fundus creates a tubular stomach remnant with preserved pyloric function. Demand concentrates in Catalonia's public hospital consortia where regional health authorities prioritize shorter length-of-stay metrics over malabsorptive alternatives.
- Gastric Bypass:Roux-en-Y reconstruction combines restrictive and malabsorptive mechanisms through gastrojejunal anastomosis. Madrid's specialized obesity units capture dominant volume for diabetic patients seeking metabolic remission beyond weight reduction alone.
- Adjustable Gastric Band:Silicone prosthesis with subcutaneous port enables postoperative restriction adjustment. Declining utilization in Spanish public hospitals reflects long-term complication profiles and explantation trends.
- Biliopancreatic Diversion:Duodenal switch variant with significant malabsorptive component. Reserved for super-obese cases in Barcelona's referral centers with dedicated nutritional support infrastructure.
Sleeve gastrectomy dominates installed base. Gastric bypass is where expansion concentrates for metabolic syndrome indications.
End User:
Capital intensity and reimbursement eligibility separate high-volume hospital networks from emerging ambulatory channels, with cost tier determining access to robotic platform contracts.
- Hospitals:Tertiary and secondary acute care facilities with 24-hour emergency coverage and intensive care capability. Andalusia's regional health services anchor procurement volume through centralized metabolic surgery program accreditation.
- Ambulatory Surgical Centers:Licensed day-surgery facilities with enhanced recovery protocol certification. Valencia's private surgical networks are expanding selective sleeve gastrectomy capacity outside traditional hospital infrastructure.
- Specialty Clinics:Obesity-focused private practices with multidisciplinary team staffing. Concentrated in Madrid and Barcelona metropolitan corridors for preoperative assessment and long-term follow-up.
- Research Institutions:Academic medical centers with clinical trial authorization for device evaluation and procedure innovation. AEMPS vigilance reporting obligations shape their adverse event documentation systems.
Hospitals dominate installed base. Ambulatory surgical centers are where expansion concentrates for streamlined patient pathways.
Technology:
Volume concentration and margin structure diverge sharply between mature laparoscopic baselines and capital-intensive robotic adoption curves across Spanish autonomous communities.
- Robotic-Assisted:Telemanipulation platforms with wristed instrumentation and three-dimensional visualization. Catalonia's bundled service agreements with Intuitive Surgical are displacing conventional laparoscopic programs in high-volume centers.
- Laparoscopic:Minimally invasive abdominal access through trocar placement with insufflation. Andalusia maintains dominant installed base where budget constraints delay robotic transition timelines.
- Endoscopic:Transoral approaches without abdominal wall penetration including intragastric balloons and sleeve gastroplasty. Emerging in private Barcelona clinics for lower-BMI patients outside surgical eligibility thresholds.
- Traditional Open Surgery:Laparotomy with direct visualization for revision cases and complex reoperations. Reserved for Madrid's tertiary referral centers managing failed prior interventions.
Laparoscopic platforms dominate installed base. Robotic-assisted systems are where expansion concentrates as regional consortia negotiate system-wide deployments.
Patient Demographics:
Clinical indication breadth and reimbursement authorization rigidity vary across age cohorts, with volume scaling fastest among metabolically compromised adults.
- Adults:Patients aged 18-64 with BMI thresholds and comorbidity profiles meeting National Health System criteria. Madrid and Barcelona public hospitals concentrate volume for type 2 diabetes remission protocols.
- Adolescents:Patients under 18 requiring endocrinology clearance and growth plate assessment. Limited program availability in specialized pediatric centers constrains addressable volume.
- Seniors:Patients over 65 with cardiovascular risk stratification requirements. Valencia's enhanced recovery programs are selectively expanding surgical candidacy beyond traditional age cutoffs.
- Obese Individuals:Super-obese cohorts with BMI exceeding 50 requiring intensive care coordination. Referred to Barcelona's tertiary units with bariatric surgery-specific anesthesia and nursing protocols.
Adults dominate installed base. Seniors are where expansion concentrates as enhanced recovery protocols extend surgical eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's autonomous communities consume bariatric surgical capacity at sharply divergent intensities, with Madrid and Catalonia operating specialized obesity units at maximum throughput while Andalusia and Valencia still rely on general surgery departments for metabolic procedures.
Madrid
Spain's capital concentrates the highest per-capita bariatric procedure volume through its network of tertiary public hospitals and private specialty clinics. The Ministry of Health's updated National Health System reimbursement protocols channel diabetic patients toward metabolic surgery programs here. Hospital Universitario La Paz and Hospital Clínico San Carlos anchor robotic-assisted sleeve gastrectomy capacity with dedicated bariatric anesthesia teams.
Catalonia
Barcelona's metropolitan corridor drives innovation adoption through bundled service contracts for advanced surgical platforms. The Catalan Health Service negotiates system-wide agreements that displace conventional laparoscopic baselines in high-volume centers. Hospital de la Santa Creu i Sant Pau and Hospital Clínic de Barcelona operate at maximum capacity with multidisciplinary obesity units.
Andalusia
Seville and Málaga are scaling metabolic surgery programs to address rising obesity-related diabetes prevalence across southern Spain. Regional health authority procurement consolidation favors suppliers with national service capabilities. Hospital Universitario Virgen del Rocío in Seville anchors public network expansion with enhanced recovery protocol certification.
Valencia
The Valencian Community is pioneering ambulatory surgical center penetration for selective sleeve gastrectomy cases outside traditional hospital infrastructure. Private surgical networks here compress length-of-stay requirements through licensed day-surgery facilities. Hospital Clínico Universitario de Valencia extends surgical eligibility to senior cohorts beyond traditional age cutoffs.
Basque Country
Bilbao and San Sebastián maintain specialized obesity units with robotic console deployments negotiated through regional procurement frameworks. The Basque Health Service integrates metabolic surgery into diabetes remission protocols with endocrinology clearance mandates. Hospital Universitario Cruces in Barakaldo manages super-obese referrals with intensive care coordination.
Spain Bariatric Surgery Market Competitive Landscape
Capability concentration sits with integrated surgical ecosystem providers; scale advantage sits with diversified medical technology conglomerates. The vendor base structures around three tiers: capital-intensive robotic platform specialists, comprehensive surgical device portfolios, and focused metabolic procedure innovators. Consolidation pressures intensify as regional health services negotiate bundled contracts replacing discrete device purchasing. Dominant competitive moves include integrated service contracting and cross-autonomous community procurement aggregation.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson occupy positions spanning stapling, energy devices, and suture platforms. Intuitive Surgical anchors the premium robotic-assisted tier through da Vinci system placements in tertiary referral centers. Apollo Endosurgery exemplifies the focused metabolic innovation archetype with specialized endoluminal technologies. These three represent the strategic positioning spectrum: ecosystem integration, diversified breadth, and procedural specialization.
| Leading Market Players |
|---|
| Medtronic |
| Apollo Endosurgery |
| Teleflex |
| Intuitive Surgical |
| Spatz FGIA |
| TransEnterix |
| USGI Medical |
| Johnson & Johnson |
| Olympus Corporation |
| Others |
Value Network & Pricing Analysis
The Barcelona-Valencia freight corridor's rising logistics costs compress margins for disposable surgical device shipments while amplifying price differentiation between Madrid's premium robotic service contracts and Andalusia's standard laparoscopic procurement tiers. Regional health authority purchasing power concentrates supply relationships, with bundled platform agreements displacing transactional device pricing across autonomous communities.
Pricing Analysis
Madrid commands price premiums of 15-25 percent above Seville for identical robotic-assisted procedure bundles due to tertiary hospital density and specialized anesthesia team availability. Three-tier pricing structure across premium robotic, standard laparoscopic, and economy open-surgery levels stratifies procurement across public hospital networks. Pricing pressure stems from Interterritorial Council volume aggregation favoring national-scale suppliers over regional distributors. Community hospitals in secondary cities exhibit highest price sensitivity, while Barcelona's specialized obesity units prioritize technology access over per-procedure cost minimization.
Supply Chain Analysis
Contract manufacturing for advanced energy devices concentrates with Flex and Jabil facilities in Ireland and Poland serving European medical device OEMs under MDR-compliant quality systems. Component sourcing draws from German precision instrumentation suppliers, Swiss sensor manufacturers, and Chinese raw material processors for surgical-grade polymers. Single-source vulnerability persists for robotic console optical assemblies produced in California. Distribution runs through regional health service central warehouses in each autonomous community, with consignment inventory models at high-volume Madrid and Barcelona hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's bariatric surgery market sits in early-cycle expansion as robotic platform penetration accelerates from tertiary centers toward secondary cities, with AEMPS MDR harmonization clearing registration pathways for qualified device manufacturers.
For Market Incumbents: Entrench market position through exclusive service contracts with Catalan and Andalusian regional health consortia while acquiring CE marking certification for next-generation energy platforms before MDR transition deadlines expire. Counter emerging endoluminal competitors by embedding stapling and energy devices into hospital accreditation standards. Prioritize vertical integration into single-use device manufacturing to capture margin compression from sterilization infrastructure elimination. For New Entrants and Emerging Players: Ambulatory surgical centers in Valencia and Seville represent the most penetrable entry point for streamlined sleeve gastrectomy devices outside established hospital supply relationships. Target private specialty clinics in Madrid's metropolitan corridor with direct-to-facility sales models bypassing regional procurement frameworks. Differentiate through per-procedure leasing structures that bundle capital equipment, disposables, and maintenance under unified contracts. For Investors and Strategic Acquirers: EU Medical Device Regulation full enforcement reshapes the acquisition landscape toward targets with completed technical documentation migrations and established AEMPS vigilance reporting systems. Position for consolidation plays across the 5-10 year window as Interterritorial Council purchasing aggregation eliminates sub-scale distributors. Monitor quarterly AEMPS adverse event disclosure patterns as early indicators of product family vulnerability or competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance unlocks access to Catalonia's bundled robotic procurement contracts. |
| Hospital System Partnership | Andalusia's regional health authority accreditation creates exclusive supply relationships. |
| Software Companion Development | Integrated tissue-sensing algorithms differentiate energy platforms in Madrid's premium tier. |
| Reimbursement Strategy | Alignment with National Health System diabetes remission protocols expands addressable volume. |
| Geographic Expansion | Valencia's ambulatory surgical center licensing opens day-surgery revenue streams. |
Research Methodology
The analysis maps robotic-assisted platforms, laparoscopic instrumentation, endoluminal devices, and open surgery equipment, each validated through metabolic surgeons, hospital purchasing committee members, biomedical engineers, and regional health authority procurement directors. Primary fieldwork combined structured interviews with secondary validation against AEMPS device registration databases, EU Medical Device Regulation implementation timelines, and National Health System reimbursement protocol updates. Bottom-up procedure volume modeling triangulated against top-down regional health spending allocations across Spain's seventeen autonomous communities.
Assumptions held fixed include current National Health System eligibility criteria, MDR transition timelines, and regional health authority spending autonomy frameworks; variables tested included robotic platform adoption curves, ambulatory surgical center licensing expansion, and cross-autonomous community procurement consolidation speed. Segmentation dimensions modeled encompass procedure type, technology modality, end-user facility tier, and patient demographic cohort across the projection horizon. CAGRs derived from procedure volume trajectories weighted by device intensity per intervention type and capital equipment replacement cycles.
Macroeconomic conditions sit as an overlay; deviation in regional health budget allocations, EU medical device regulatory enforcement intensity, or robotic console utilization rates would shift the trajectory. Forecasts incorporate documented assumptions regarding reimbursement stability and workforce training pipeline expansion. Quarterly review of AEMPS vigilance reporting trends and Interterritorial Council procurement framework updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market