
 Canada Senior Living Market | 2026-2036
Canada Senior Living Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Senior Living Market Insights
Registered nurse availability across prairie provinces is reorganizing expansion timelines for several operators. Chartwell Retirement Residences leverages its Ontario concentration to sustain occupancy premiums in the Greater Toronto Area. Sienna Senior Living anchors its portfolio with purpose-built memory care assets in British Columbia. Revera Inc. competes through government contract density in provinces with higher public funding ratios.
Canada senior living encompasses purpose-built residential environments delivering custodial care, clinical oversight, and lifestyle programming to adults aged sixty-five and older, with facility designs typically incorporating barrier-free architecture, emergency response systems, and medication management protocols. The sector exists to bridge the gap between independent domestic living and acute hospitalization for a demographically expanding population. Independent living commands the largest current revenue pool, though memory care segments are attracting capital at faster rates due to clinical complexity premiums. Private pay service models concentrate margin generation in major metropolitan corridors, while Medicare-funded streams dominate volume in Quebec and Atlantic Canada.
Health Canada sets national guidelines for long-term care facility standards, while provincial ministries of health administer licensing and funding allocation through instruments like Ontario's Fixing Long-Term Care Act. CMHC's mortgage insurance programs for retirement housing construction shape developer access to construction capital. Health Canada guidelines influence staffing ratio mandates that directly determine operating cost structures. Stakeholders must track how provincial election cycles alter reimbursement schedules and capital grant availability.
Market Dynamics
Provincial reimbursement rate compression is forcing operators to restructure staffing models while simultaneously absorbing elevated construction costs for purpose-built memory care assets. Health Canada's Long-Term Care Standards rollout is accelerating capital deployment toward infection control infrastructure and single-occupancy room conversions.
Growth Catalysts
- Ontario's Fixing Long-Term Care Act:Mandated staffing ratios and capital improvement timelines are channeling public and private investment toward facility modernization and capacity expansion.
- Home-based care technology integration:Remote patient monitoring platforms and telehealth infrastructure are extending service reach into rural Saskatchewan and Manitoba communities previously underserved by brick-and-mortar facilities.
- Baby boomer demographic wave:The seventy-five-plus cohort concentration in British Columbia's Lower Mainland and Vancouver Island is generating sustained demand for assisted living and memory care beds.
Market Restraints
- Construction cost escalation:Lumber volatility and skilled trades shortages in Quebec and Atlantic Canada are extending development timelines and compressing project yields.
- Registered nurse supply concentration:Prairie provinces face acute clinical staffing deficits that limit expansion feasibility regardless of capital availability or demographic demand.
- Interprovincial funding disparity:Public reimbursement rate gaps between Ontario and Quebec create operational complexity for multi-provincial operators and distort investment allocation.
Strategic Opportunities
- Northern Ontario and rural Quebec penetration:Underserved markets outside major metropolitan corridors present first-mover advantages for operators willing to accept lower density economics.
- Technology-enabled aging-in-place:Integration of AI-powered fall detection and predictive health analytics is opening subscription-based revenue streams outside traditional facility models.
- Provincial capital grant programs:Ontario's Accelerated Build Pilot and similar instruments in British Columbia are de-risking greenfield development for qualified applicants.
Industry Challenges
- Personal support worker retention:Wage compression relative to acute care alternatives and burnout from pandemic-era working conditions are destabilizing frontline staffing.
- Legacy system integration:Electronic health record interoperability between provincial health networks and private operator platforms remains technically fragmented and compliance-intensive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Senior Living Market |
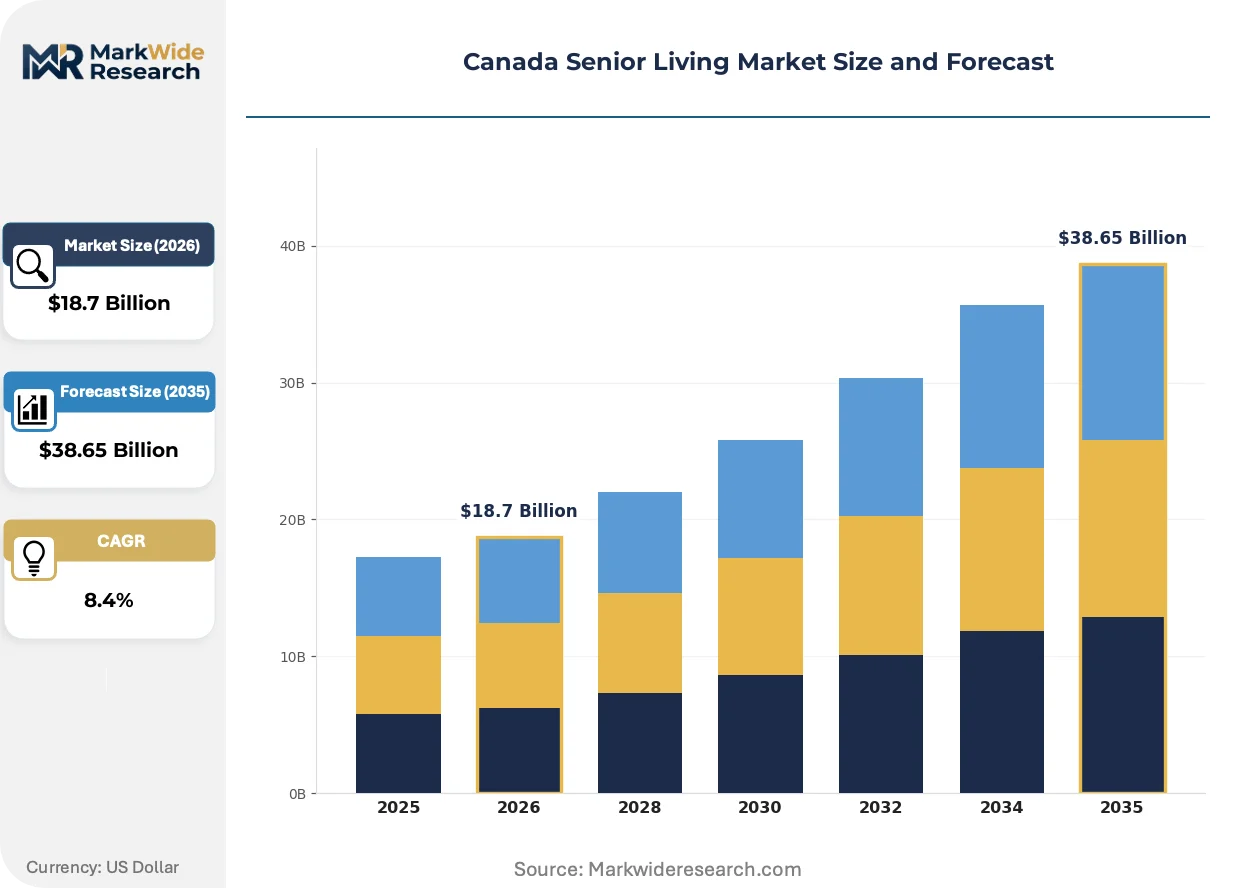
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Independent Living, Assisted Living, Memory Care, Skilled Nursing Service Model: Private Pay, Medicare, Medicaid, Managed Care End User: Seniors, Caregivers, Family Members, Healthcare Professionals Payment Channel: Direct Billing, Insurance, Grants, Personal Savings |
| Companies Covered | Chartwell Retirement Residences, Sienna Senior Living, Revera Inc., Extendicare Inc., Atria Senior Living, Amica Mature Lifestyles, Le Groupe Maurice, Shannex, Cogir, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Senior Living Market Trends and Innovations
Technology-enabled care delivery and regulatory modernization are converging to reshape how senior living services are provisioned, priced, and consumed across Canadian provinces. Operators are repositioning around data infrastructure and workforce flexibility.
Sensor-based ambient monitoring systems are displacing traditional periodic check-in protocols in memory care units. Operators in British Columbia and Ontario are deploying pressure-sensitive flooring and wearable devices to detect wandering, falls, and sleep disturbances in real time. This shift is displacing overnight staffing ratios as the primary risk management mechanism and enabling smaller-scale residential models.
Health Canada's updated Long-Term Care Standards are mandating enhanced infection control, air quality, and single-occupancy room provisions. Facility operators face substantial capital obligations to achieve compliance timelines, with Ontario's Ministry of Long-Term Care administering provincial verification protocols. The regulatory pressure is concentrating renovation spending among larger portfolio holders with balance sheet capacity.
Family-driven procurement of senior living services is compressing traditional referral channel dominance. Adult children are conducting independent digital research, touring multiple operators, and negotiating directly rather than relying exclusively on hospital discharge planners or geriatric care managers. This behavioral shift is most pronounced in Toronto, Vancouver, and Calgary metropolitan corridors where private-pay concentration supports competitive comparison.
Canada Senior Living Market Segmentation
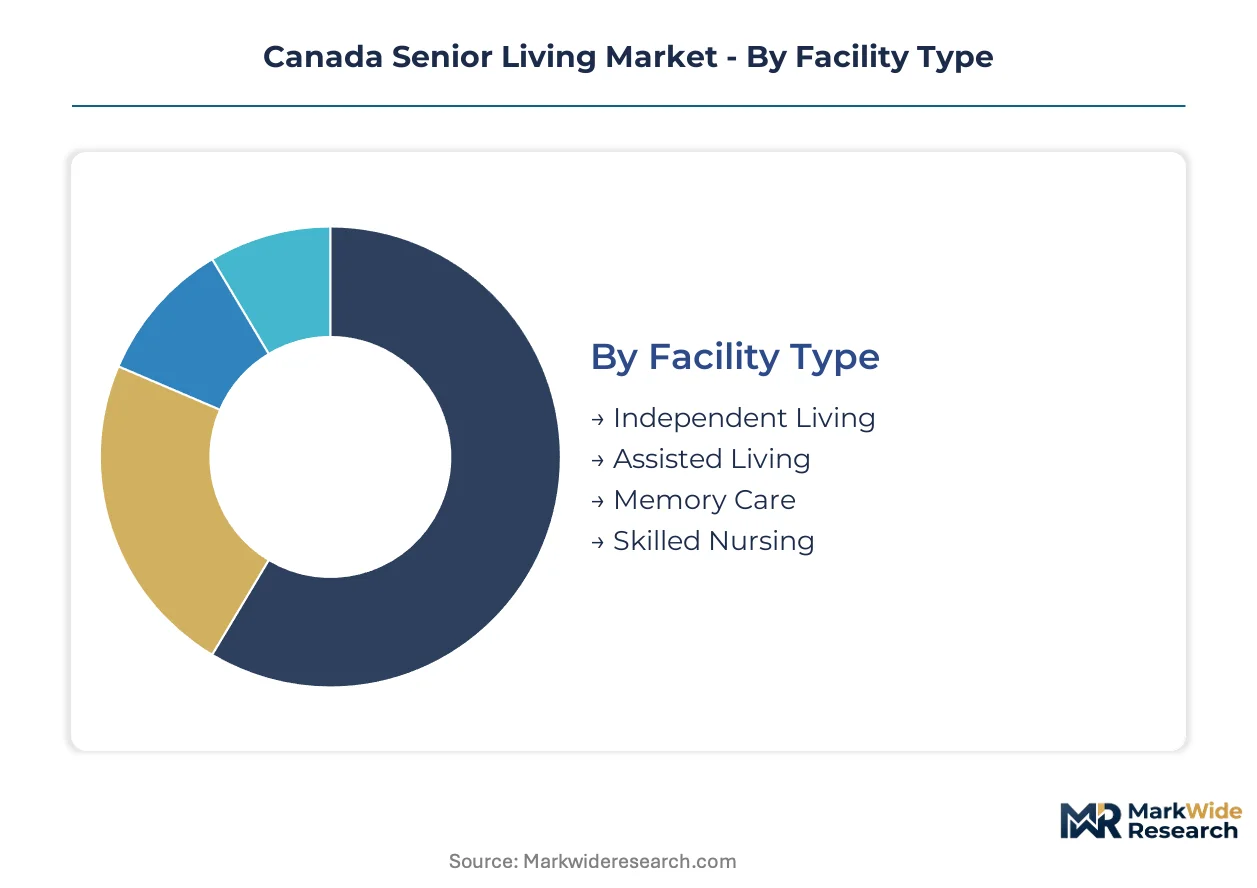
Segmentation in Canadian senior living reveals how capital allocation and regulatory pressure fragment across service intensity levels and funding mechanisms. Understanding these divides clarifies where operators can extract margin premiums versus where volume economics dominate.
Facility Type:
Margin pools concentrate in clinical complexity tiers where staffing ratios and specialized infrastructure justify rate premiums above standard accommodation fees.
- Independent Living:Purpose-built residential units with barrier-free architecture and emergency response systems but no daily personal care services. Demand concentrates in British Columbia's Lower Mainland and Vancouver Island where affluent retirees self-fund lifestyle amenities, though this segment faces pressure from aging-in-place technology alternatives.
- Memory Care:Secure residential environments with specialized programming for dementia and Alzheimer's patients, incorporating wandering prevention systems and sensory design. Ontario's Greater Toronto Area absorbs disproportionate investment attention as Health Canada's Long-Term Care Standards accelerate single-occupancy room conversions and infection control infrastructure.
- Assisted Living:Intermediate care facilities providing medication management, personal support services, and 24-hour supervision without full nursing coverage.
- Skilled Nursing:Highest-acuity residential care with registered nurse oversight, rehabilitation services, and post-hospitalization transitional beds.
Independent Living holds installed capacity. Memory Care is rotating up the share rankings.
Service Model:
Payment source determines operational flexibility, with privately funded streams offering pricing power and public programs anchoring occupancy stability.
- Private Pay:Out-of-pocket funding by residents or families, typically in major metropolitan corridors where household assets support premium rate structures. Toronto, Vancouver, and Calgary concentrate this revenue pool as family-driven procurement displaces traditional hospital discharge referrals.
- Medicare:Federal health insurance program covering specific clinical services and short-term rehabilitation stays in approved facilities. Quebec and Atlantic Canada show higher dependency ratios on this stream, compressing margin profiles but ensuring baseline census levels.
- Medicaid:Joint federal-provincial means-tested coverage for low-income seniors requiring long-term residential care.
- Managed Care:Coordinated funding arrangements integrating acute and post-acute services through designated provider networks.
Private Pay commands rate premiums. Medicare is expanding eligibility pathways.
End User:
Procurement authority has shifted from institutional referrers toward family decision-makers conducting independent digital research and competitive touring.
- Seniors:Primary residents whose functional status and care needs determine facility placement tier, with the seventy-five-plus cohort in Ontario and British Columbia driving assisted living and memory care absorption.
- Family Members:Adult children increasingly controlling selection, negotiation, and financial commitment, particularly in private-pay metropolitan markets where competitive comparison is feasible.
- Caregivers:Informal support providers whose burnout and employment constraints often trigger the transition from home-based to facility-based care.
- Healthcare Professionals:Geriatric care managers, hospital discharge planners, and primary care physicians whose referral influence persists in publicly funded streams.
Family Members now dominate selection authority. Healthcare Professionals retain influence in public reimbursement corridors.
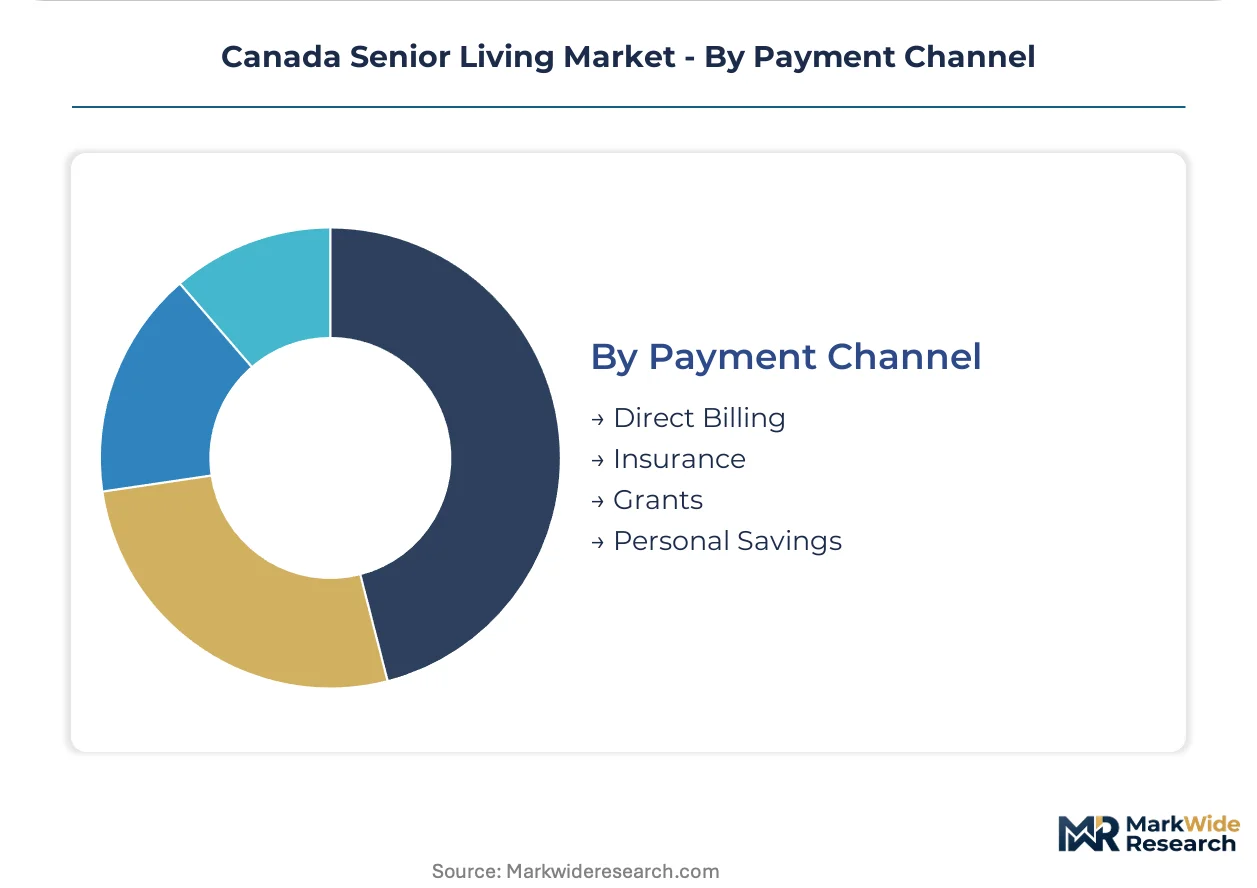
Payment Channel:
Capital access timing and administrative burden vary sharply across funding mechanisms, shaping operator working capital requirements and collection risk profiles.
- Direct Billing:Immediate payment from resident or family, minimizing receivables exposure and enabling reinvestment in service amenities or facility upgrades.
- Insurance:Private long-term care insurance policies with varying elimination periods and benefit triggers, creating administrative complexity for operators.
- Grants:Provincial capital programs like Ontario's Accelerated Build Pilot de-risking greenfield development for qualified applicants.
- Personal Savings:Asset liquidation and retirement fund drawdowns, common among middle-market seniors bridging gaps between public coverage and private-pay rates.
Direct Billing minimizes receivables risk. Grants are concentrating development capital in Ontario and British Columbia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario and British Columbia absorb premium private-pay capacity while Quebec and Atlantic Canada rely on provincial funding streams that compress margins but stabilize occupancy.
Ontario
The Greater Toronto Area concentrates Canada's highest private-pay senior living rates as affluent retirees self-fund memory care and assisted living upgrades. Ontario's Fixing Long-Term Care Act mandates staffing ratios and capital improvement timelines that channel investment toward facility modernization. Toronto and Ottawa clusters absorb disproportionate development capital under the Accelerated Build Pilot program.
British Columbia
The seventy-five-plus cohort concentration in the Lower Mainland and Vancouver Island generates sustained demand for dementia-specific beds and aging-in-place technologies. Health Canada guidelines shape provincial licensing requirements that favor operators with infection control infrastructure investments. Vancouver's urban core attracts purpose-built memory care assets at premium rate structures.
Quebec
Public reimbursement dominance creates volume economics where Medicare-funded streams anchor baseline census levels for multi-facility operators. The provincial Ministry of Health and Social Services administers funding allocation through instruments that differ from Ontario's model. Montreal's established operator base competes on government contract density rather than rate premiums.
Alberta
Calgary and Edmonton corridors concentrate private-pay demand from energy-sector retirees with asset liquidity to support premium accommodation fees. Provincial health ministry oversight of long-term care licensing creates regulatory alignment with western Canadian standards. Urban centers attract technology-enabled care delivery investments that extend service reach into surrounding rural communities.
Atlantic Canada
Demographic aging outpaces facility capacity expansion across Nova Scotia, New Brunswick, and Newfoundland and Labrador. Provincial funding ratios exceed national averages, creating dependency on public reimbursement schedules that shift with election cycles. Halifax anchors regional development activity as smaller markets face registered nurse supply constraints that limit greenfield feasibility.
Canada Senior Living Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with national portfolio operators commanding balance sheet capacity for regulatory-mandated capital upgrades while regional specialists concentrate on single-province density. The market structure favors scale in Ontario and British Columbia where private-pay premiums justify consolidation economics. Three archetypes dominate: REIT-backed national platforms, Quebec-focused integrated health systems, and family-owned regional specialists. Competitive moves center on provincial capital grant capture and technology-enabled care differentiation.
Within the national platform tier, Chartwell Retirement Residences and Sienna Senior Living exemplify REIT-backed structures positioned for Ontario and British Columbia expansion. Revera Inc. occupies a position as a government-contract-dense operator with multi-provincial reach. These three represent contrasting approaches to funding model exposure and geographic concentration.
| Leading Market Players |
|---|
| Chartwell Retirement Residences |
| Sienna Senior Living |
| Revera Inc. |
| Extendicare Inc. |
| Atria Senior Living |
| Amica Mature Lifestyles |
| Le Groupe Maurice |
| Shannex |
| Cogir |
| Others |
Pricing and Supply Chain Analysis
Sensor-based ambient monitoring systems replacing overnight staffing ratios in memory care units simultaneously concentrates equipment procurement in Ontario and British Columbia technology corridors while compressing labor-cost premiums that previously justified rate differentials. This substitution dynamic redirects capital toward single-occupancy room conversions and infection control infrastructure mandated by Health Canada's Long-Term Care Standards.
Pricing Analysis
Long-term offtake contracts between multi-provincial operators and provincial health ministries anchor pricing stability in Quebec and Atlantic Canada, while spot-market private-pay transactions in Toronto and Vancouver corridors enable rate premiums tied to barrier-free architecture quality and registered nurse coverage ratios. Price differentiation hinges on certification tier under Ontario's Fixing Long-Term Care Act compliance verification and geographic delivery cost differentials between urban clusters and rural Saskatchewan expansions. Cost compression in Medicare-funded streams is intensifying because reimbursement rate compression outpaces operating expense escalation. Family members conducting independent digital research exhibit highest price sensitivity; affluent retirees self-funding in British Columbia's Lower Mainland show lowest sensitivity.
Supply Chain Analysis
Registered nurse supply concentration in Ontario and British Columbia functions as a chokepoint that constrains expansion feasibility regardless of capital availability or demographic demand in prairie provinces. Equipment and technology sourcing draws from Canadian medical device distributors, US sensor manufacturers, and Asian electronics suppliers for wearable monitoring devices. Supply chain risk centers on single-source vulnerability for specialized dementia care furniture and wandering prevention systems. Distribution runs through provincial health ministry procurement frameworks for publicly funded beds and direct operator purchasing for private-pay capacity additions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada senior living market rewards operators who control scarce clinical workforce pipelines and balance sheet capacity for regulatory-mandated capital upgrades. Registered nurse availability constraints and construction cost escalation create asymmetric returns favoring incumbents with established provincial health ministry relationships.
For Market Incumbents: Shield occupancy premiums in Greater Toronto Area and Vancouver Island clusters by accelerating single-occupancy room conversions ahead of Health Canada compliance deadlines. Deepen backward integration into personal support worker training pipelines to offset wage compression relative to acute care alternatives. Priority lever: provincial capital grant capture under Ontario's Accelerated Build Pilot. For New Entrants and Emerging Players: Health Canada certification fast-tracks for technology-enabled aging-in-place platforms open subscription-based revenue streams outside traditional facility models. Target northern Ontario and rural Quebec penetration where first-mover advantages offset lower density economics. Go-to-market angle: AI-powered fall detection bundled with remote patient monitoring for rural Manitoba and Saskatchewan communities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors REIT-backed national platforms with Ontario and British Columbia geographic concentration. Long-term viability rests on operators who can absorb Health Canada-mandated renovation spending while sustaining private-pay rate premiums. Acquisition target archetype: regional specialists with purpose-built memory care assets in underserved metropolitan corridors. Signal to watch: provincial election cycles altering reimbursement schedules and capital grant availability.| Strategic Initiative | Industry Significance |
|---|---|
| Technology-Enabled Care Integration | Remote patient monitoring platforms extend service reach into rural Saskatchewan and Manitoba communities. |
| Provincial Capital Grant Capture | Ontario's Accelerated Build Pilot de-risks greenfield development for qualified applicants. |
| Clinical Workforce Pipeline Investment | Personal support worker training programs offset retention destabilization from pandemic-era burnout. |
| Single-Occupancy Room Conversion | Health Canada Long-Term Care Standards compliance mandates infection control infrastructure spending. |
| Memory Care Asset Specialization | Dementia-specific bed concentration in Vancouver and Toronto corridors commands clinical complexity premiums. |
Research Methodology
Initial hypotheses were tested against primary input from senior living facility operators, provincial health ministry procurement officers, registered nurse workforce planners, and construction contractors specializing in barrier-free architecture and refined through secondary validation. Primary stakeholder interviews combined with regulatory filing analysis from Health Canada and provincial ministries of health, CMHC mortgage insurance program disclosures, and long-term care facility licensing databases. Bottom-up facility capacity modeling and top-down demographic demand projections were triangulated against provincial funding allocation instruments.
Variance decomposition across facility type, service model, and geographic concentration dimensions structured the analytical framework over the projection horizon. Segmentation modeling incorporated independent living, assisted living, memory care, and skilled nursing tiers crossed with private-pay, Medicare, and Medicaid funding mechanisms. CAGRs were derived from demographic absorption rates, construction pipeline visibility, and provincial reimbursement schedule trajectories. Forecast inputs included baby boomer cohort aging patterns and home-based care technology substitution elasticities.
Decision-makers should treat outputs as directional under assumptions of stable provincial funding ratios and registered nurse supply trajectories; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as provincial election cycles and Health Canada regulatory enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
Medical Billing Outsourcing Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
Spa Services Market
Healthcare Services
EMEA Home Infusion Services Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
US Hospice Market
Healthcare Services
Contract Manufacturing Services Market
Healthcare Services
Long Term Care Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Medical Social Working Services Market
Healthcare Services
Europe Pharmaceutical Logistics Market