
 United States Bariatric Surgery Market | 2026-2036
United States Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Bariatric Surgery Market Analytics
The capital-intensity divergence between robotic platform owners and conventional laparoscopic instrument suppliers is reorganizing competitive dynamics across the United States bariatric surgery landscape. Medtronic PLC leverages its integrated surgical ecosystem to sustain high-margin recurring revenue from stapling and energy devices. Intuitive Surgical anchors the premium tier through da Vinci system placements and procedure-specific training networks. Apollo Endosurgery competes in the endoluminal space with specialized suturing and space-occupying technologies.
Bariatric surgery encompasses a spectrum of gastrointestinal procedures designed to induce weight loss through restriction, malabsorption, or neurohormonal modification, typically involving stapling, banding, or intestinal rerouting with anastomotic precision measured in millimeters. Its primary purpose is durable metabolic disease modification for patients with obesity refractory to conservative management. Sleeve gastrectomy now dominates procedural mix due to its technical simplicity and comparable efficacy to gastric bypass, while robotic-assisted technology commands expanding share in complex revisional cases where visualization depth proves decisive. Ambulatory surgical centers represent the fastest-growing end-user channel as payors push site-of-care migration and enhanced recovery protocols shorten length of stay.
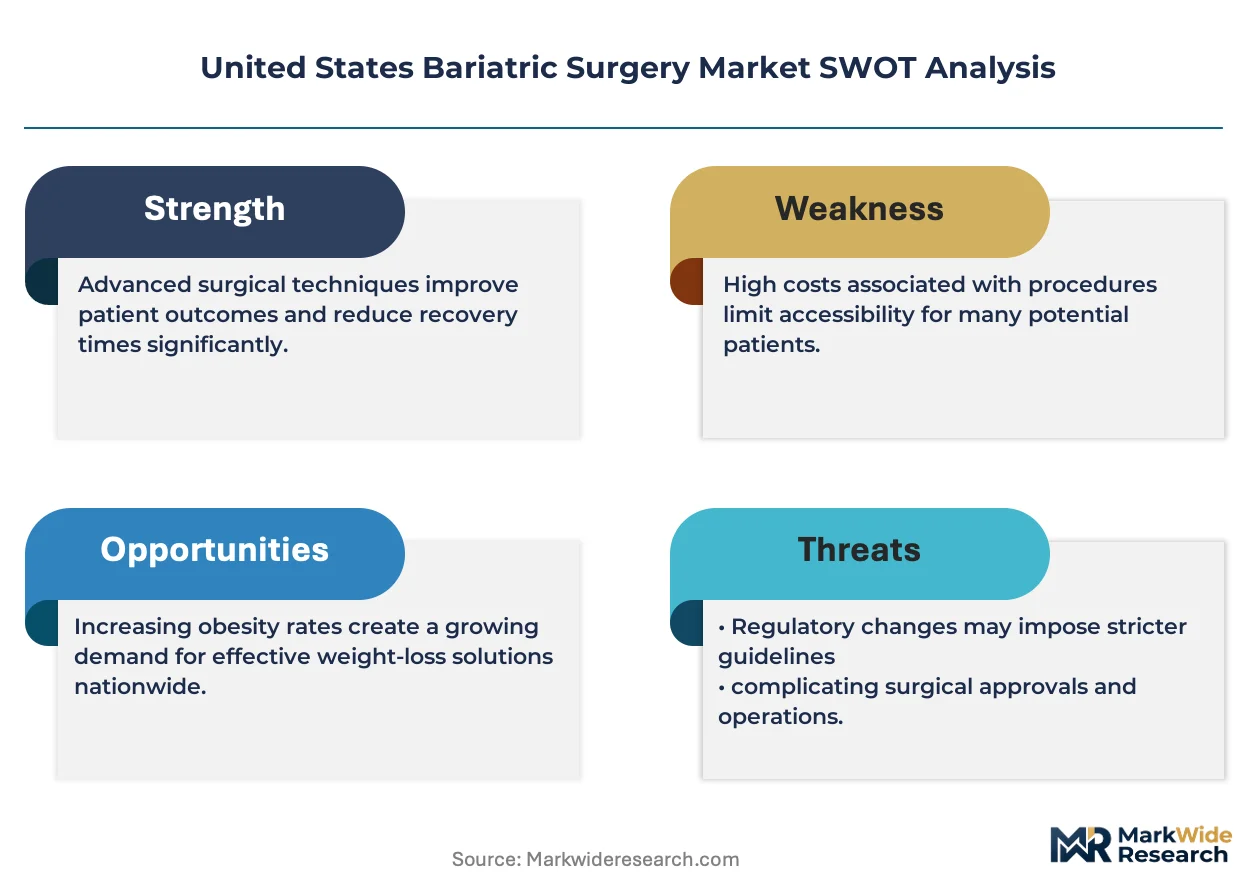
The FDA Center for Devices and Radiological Health regulates implantable devices and surgical instruments through premarket notification and approval pathways, while CMS national coverage determinations and local contractor policies directly shape patient access and provider economics. State-level certificate-of-need requirements and accreditation standards from the Metabolic and Bariatric Surgery Accreditation and Quality Improvement Program further constrain market entry and concentrate volume at designated centers of excellence. Stakeholders must monitor evolving GLP-1 pharmacotherapy guidelines and their interaction with surgical candidacy criteria, as payer preauthorization protocols increasingly require documented failure of medical management before procedural approval.
Market Dynamics
GLP-1 pharmacotherapy penetration is restructuring surgical candidacy pipelines across the United States, forcing metabolic surgery programs to recalibrate patient selection algorithms and revenue forecasting models around pharmaceutical non-responders.
Growth Catalysts
- Employer-sponsored coverage expansion:Large self-insured employers in the Southeast and Midwest are adding bariatric benefits to reduce diabetes-related medical costs, directly expanding addressable patient pools.
- Enhanced Recovery After Surgery protocols:CMS reimbursement incentives for reduced length-of-stay are accelerating ambulatory surgical center migration for low-complexity sleeve procedures.
- Robotic platform training networks:Procedure-specific credentialing programs are building surgeon capacity for complex revisional cases previously referred to academic medical centers.
Market Restraints
- Stapler cartridge cost volatility:Polymer and metal input price fluctuations compress margins for conventional laparoscopic instrument suppliers serving high-volume community hospitals.
- Certificate-of-need concentration:State-level CON requirements in 35 states restrict new center entry, entrenching volume at incumbent metabolic surgery programs with decade-long accreditation histories.
- GLP-1 substitution threshold:Payer preauthorization protocols requiring 12-month documented pharmaceutical failure before surgical approval extend sales cycles and increase patient attrition.
Strategic Opportunities
- Endoluminal technology convergence:Suturing systems combined with space-occupying devices enable incisionless metabolic intervention for BMI 30-35 populations currently excluded from reimbursement.
- Telehealth-enabled prehabilitation:Remote patient monitoring platforms expand geographic reach into rural Appalachian and Mississippi Delta markets with limited bariatric surgeon density.
- CMS innovation center waivers:Accountable Care Organization shared savings models create financial alignment for preventive metabolic surgery in prediabetic populations.
Industry Challenges
- Revisional surgery skill scarcity:Complex conversion procedures from failed gastric bands require subspecialized training that fellowship programs have not scaled to match demand.
- Accreditation timeline compression:Metabolic and Bariatric Surgery Accreditation and Quality Improvement Program certification cycles extend 18-24 months, delaying new program revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Bariatric Surgery Market |
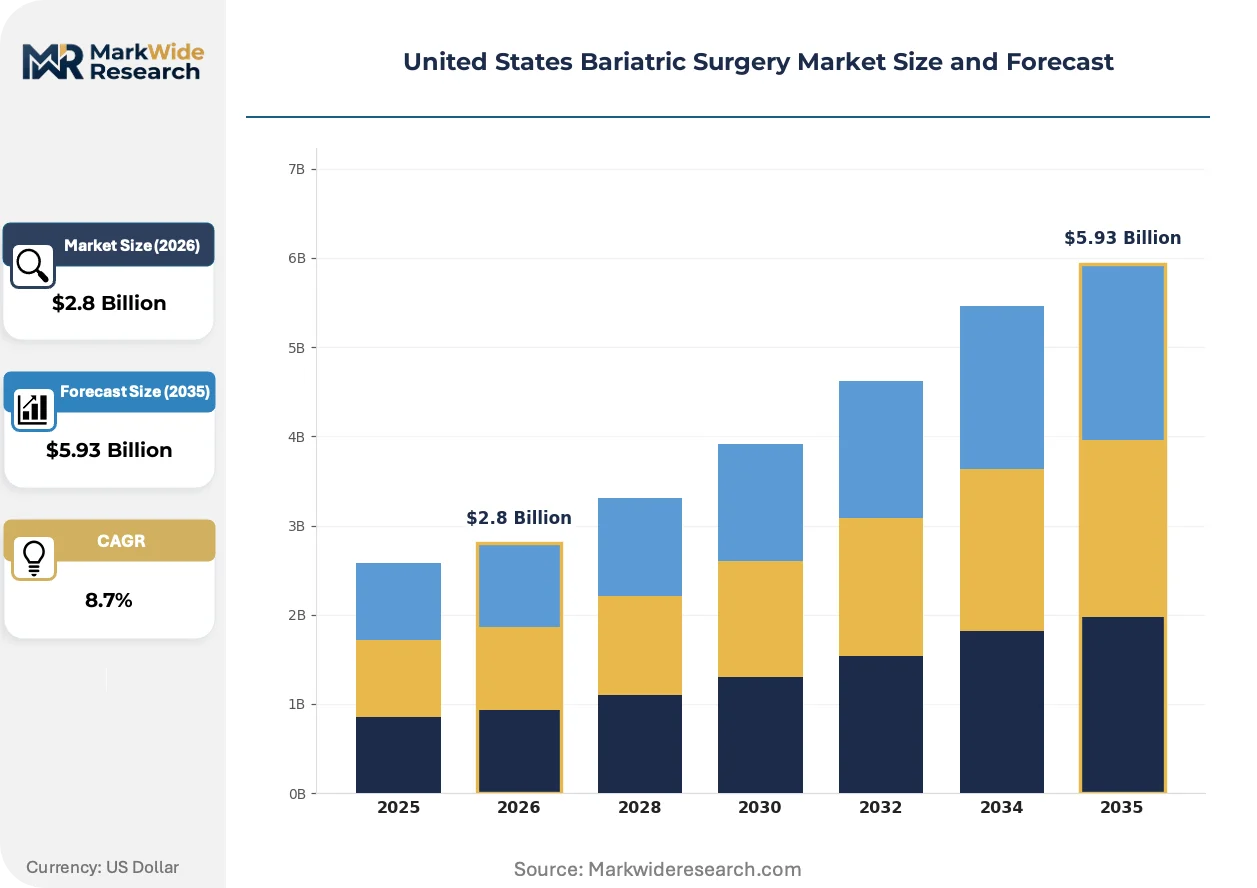
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Banding, Biliopancreatic Diversion Technology: Laparoscopic, Robotic-assisted, Open Surgery, Endoscopic End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Procedure Type: Elective Surgery, Reversal Surgery, Preventive Surgery, Complication Management |
| Companies Covered | Medtronic PLC, Johnson & Johnson, Intuitive Surgical, Apollo Endosurgery, Olympus Corporation, Boston Scientific, Aspire Bariatrics, Teleflex, Conmed, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Bariatric Surgery Market Evolving Landscape
Digital surgical planning and intraoperative navigation systems are redefining precision benchmarks in metabolic procedures, while reimbursement policy evolution and patient consumerism reshape how surgical services are packaged and purchased.
Single-port robotic platforms are fragmenting the minimally invasive surgery landscape by enabling reduced-incision sleeve gastrectomy through umbilical access. Community hospital systems in Texas and Florida are adopting these systems to differentiate against academic competitors. The technology is fragmenting procedure volume across a broader site-of-care map, compressing the traditional academic medical center referral monopoly.
FDA Center for Devices and Radiological Health breakthrough device designation pathways are compressing timelines for endoluminal metabolic technologies. Manufacturers now pursue parallel 510(k) and de novo pathways to accelerate commercial entry. The policy shift most affects suturing and gastric remodeling device categories, where sponsors are front-loading clinical evidence generation to support simultaneous regulatory and coverage submissions.
Patient-directed scheduling through direct-to-provider digital platforms is displacing traditional primary-care-referral pathways for surgical consultation. Self-pay and high-deductible plan patients in Sun Belt states increasingly book initial evaluations through practice-owned portals, bypassing gatekeeper delays. This behavioral shift concentrates in metropolitan markets with high smartphone penetration and existing telehealth infrastructure.
United States Bariatric Surgery Market Segmentation
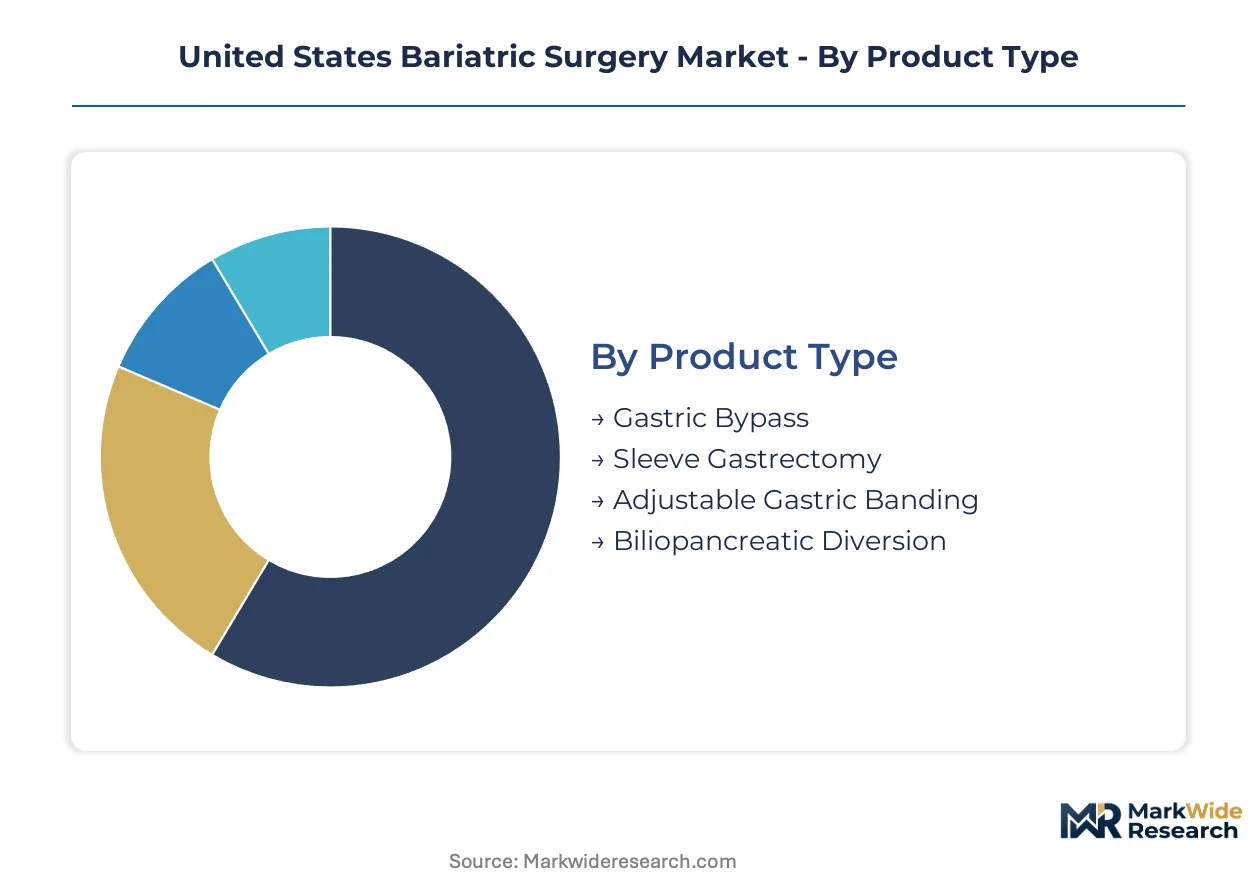
Surgical procedure mix and technology platforms fragment the United States bariatric surgery market into distinct revenue pools with diverging margin profiles and site-of-care requirements. Understanding these segment boundaries illuminates where capital equipment investments concentrate versus where consumable recurring revenue dominates.
Product Type:
Hospital systems route sleeve gastrectomy volume through ambulatory surgical centers where possible, while gastric bypass cases remain concentrated at academic medical centers with intensive care backup.
- Sleeve Gastrectomy:Partial gastric resection creates a tubular stomach remnant through stapling along the greater curvature. Demand concentrates in community hospital systems across Texas and Florida where enhanced recovery protocols enable same-day discharge for selected patients.
- Gastric Bypass:Roux-en-Y reconstruction partitions the stomach and reroutes the small intestine to induce malabsorption. Academic medical centers in the Northeast and Midwest retain volume leadership for this technically complex procedure requiring longer operative times and specialized anesthesia support.
- Adjustable Gastric Banding:Silicone band placement around the gastric cardia with subcutaneous port access for saline adjustment.
- Biliopancreatic Diversion:Extended malabsorptive procedure combining distal gastrectomy with intestinal bypass for super-obese populations.
By volume, sleeve gastrectomy leads. By growth pace, gastric bypass is climbing the fastest as revisional case complexity rises.
Technology:
Capital deployment intensity separates robotic platform adopters from conventional laparoscopic instrument purchasers, with reimbursement differentials determining break-even timelines.
- Laparoscopic:Multi-port abdominal access through 5-12mm trocars with carbon dioxide insufflation and high-definition camera visualization. Community hospitals in the Southeast deploy these systems for high-volume sleeve programs where instrument cost per case must stay below payer reimbursement floors.
- Robotic-assisted:Computer-enhanced instrumentation with wristed articulation and three-dimensional visualization. Texas Medical Center affiliates and Florida hospital networks lead platform placement for complex revisional procedures where suturing precision reduces leak rates.
- Open Surgery:Traditional laparotomy for conversion cases or patients with extensive prior abdominal surgery.
- Endoscopic:Transoral approaches without abdominal wall incision for primary or revisional intervention.
By installed base, laparoscopic dominates. By expansion trajectory, robotic-assisted is gaining share fastest in metropolitan markets.
End User:
Site-of-care economics drive patient routing decisions, with payor pressure accelerating volume migration toward lower-cost settings.
- Hospitals:Inpatient and outpatient departments with 24-hour nursing and critical care capability. Major health systems in the Midwest anchor metabolic surgery programs here for complex cases requiring multidisciplinary management of diabetes and hypertension.
- Ambulatory Surgical Centers:Same-day discharge facilities with limited overnight observation capacity. Freestanding centers in Arizona and Nevada capture growing volume as commercial payors expand site-neutral reimbursement for uncomplicated sleeve procedures.
- Specialty Clinics:Physician-owned facilities focused on preoperative evaluation and postoperative follow-up.
- Research Institutions:Academic centers with NIH-funded metabolic outcomes studies and fellowship training programs.
By procedure count, hospitals lead. By volume growth rate, ambulatory surgical centers are expanding most quickly.
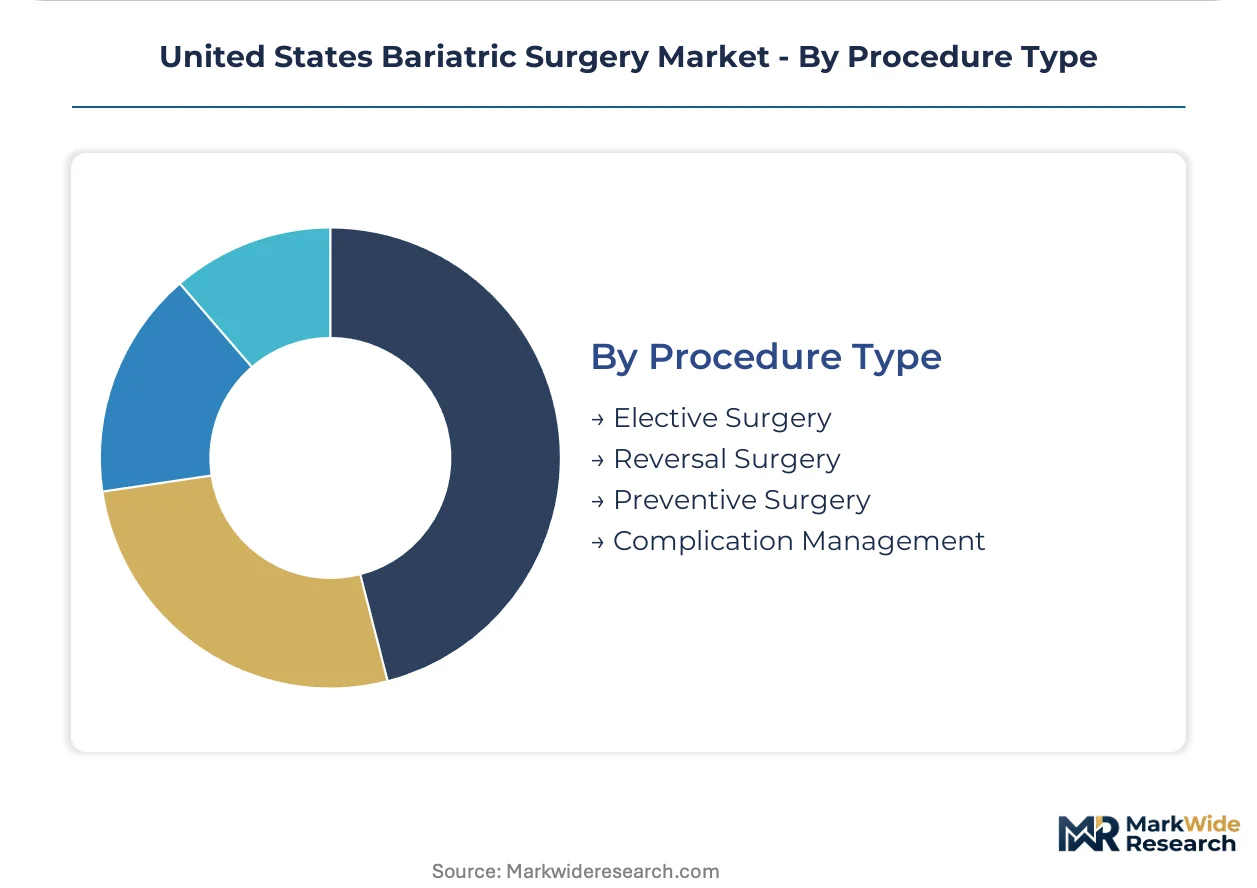
Procedure Type:
Clinical indication categories determine reimbursement coding, preauthorization requirements, and surgeon credentialing thresholds.
- Elective Surgery:Scheduled primary bariatric intervention for patients meeting BMI and comorbidity criteria. Employer-sponsored plans in the Southeast approve these cases most readily where diabetes cost-offset calculations support benefit expansion.
- Reversal Surgery:Restoration of native gastrointestinal anatomy following prior bariatric procedure. Academic referral centers concentrate this volume as community surgeons lack fellowship training in takedown and reconstruction techniques.
- Preventive Surgery:Metabolic intervention in prediabetic populations with lower BMI thresholds.
- Complication Management:Revision or conversion for staple line leaks, strictures, or nutritional deficiencies.
By annual procedures, elective surgery leads. By expansion pace, complication management is climbing the fastest as prior-decade banding volumes generate revisional demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metabolic surgery volume flows toward states with concentrated employer-sponsored coverage expansion and established accreditation infrastructure, creating distinct regional demand corridors that reshape provider economics and technology deployment patterns.
Southeast
Florida and Georgia health systems report accelerating sleeve gastrectomy volume as self-insured employers add bariatric benefits to offset diabetes-related medical costs. State Medicaid programs in the region maintain restrictive coverage criteria that concentrate commercially insured patients at designated centers of excellence. Tampa and Atlanta metropolitan areas anchor the highest robotic platform density outside academic medical centers.
Texas
The Texas Medical Center affiliates drive complex revisional case volume through fellowship-trained surgeon networks and intensive care backup capacity. State-level certificate-of-need requirements remain absent, enabling rapid ambulatory surgical center entry in Dallas-Fort Worth and Houston suburbs. Employer-sponsored coverage expansion in the energy and technology sectors directly expands addressable patient pools.
Midwest
Illinois, Michigan, and Ohio retain gastric bypass leadership through academic medical centers with multidisciplinary metabolic management programs. CMS reimbursement incentives for reduced length-of-stay accelerate enhanced recovery protocol adoption across Cleveland Clinic and Mayo Clinic referral networks. Rust Belt manufacturing employers increasingly cover bariatric procedures as diabetes cost-offset calculations mature.
Southwest
Arizona and Nevada freestanding ambulatory surgical centers capture growing commercial payor volume as site-neutral reimbursement expands for uncomplicated sleeve procedures. Phoenix and Las Vegas markets exhibit the fastest same-day discharge adoption rates nationally. Limited bariatric surgeon density in rural expanses creates telehealth-enabled prehabilitation opportunities.
Northeast
Massachusetts and New York academic centers concentrate NIH-funded metabolic outcomes research and fellowship training programs. State-level accreditation requirements from the Metabolic and Bariatric Surgery Accreditation and Quality Improvement Program extend certification timelines, entrenching volume at incumbent programs with decade-long histories. Boston and Manhattan maintain revisional surgery referral monopolies for failed prior procedures.
United States Bariatric Surgery Market Competitive Landscape
Concentration sits with integrated surgical ecosystem providers and robotic platform manufacturers that command recurring revenue from consumable attachment and instrument cartridge sales. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with stapling and energy device portfolios, pure-play robotic surgery platform developers with procedure-specific training networks, and specialized endoluminal technology firms pursuing incisionless intervention. Competitive moves center on hospital system exclusive purchasing agreements and surgeon credentialing program expansion that locks in procedural volume.
Within the diversified technology tier, Medtronic PLC and Johnson & Johnson occupy positions anchored by high-volume stapling and energy device sales to community hospital systems. Intuitive Surgical exemplifies the robotic platform archetype through da Vinci system placements and specialized training network development. Apollo Endosurgery represents the endoluminal specialization vector with suturing and space-occupying technologies targeting BMI 30-35 populations currently excluded from reimbursement.
| Leading Market Players |
|---|
| Medtronic PLC |
| Johnson & Johnson |
| Intuitive Surgical |
| Apollo Endosurgery |
| Olympus Corporation |
| Boston Scientific |
| Aspire Bariatrics |
| Teleflex |
| Conmed |
| Others |
Value Network & Pricing Analysis
Long-term exclusive purchasing agreements between hospital systems and surgical device manufacturers lock in supply access for stapling cartridges and energy platforms while anchoring price visibility across multi-year contract windows. These arrangements concentrate procurement leverage at integrated delivery networks in Texas and Florida, compressing margin flexibility for conventional laparoscopic instrument suppliers serving independent community hospitals.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the bariatric surgery device market. Price differentiation separates FDA breakthrough-designation robotic platforms from conventional laparoscopic staplers and commodity trocar systems. Cost compression in standard-tier consumables is intensifying because polymer and metal input price volatility erodes supplier margins. High-deductible plan patients and self-pay cohorts in Sun Belt metropolitan markets exhibit greatest price sensitivity, while academic medical centers with dedicated capital budgets demonstrate lowest sensitivity to per-procedure instrument costs.
Supply Chain Analysis
Strait of Hormuz transit underwrites titanium and surgical-grade stainless steel flows from Middle Eastern smelters to device manufacturing plants in the United States and Ireland. Component assembly draws from precision machining clusters in Switzerland and Germany for robotic instrument articulation mechanisms, while polymer resin sourcing rests on petrochemical feedstock from Gulf Coast refineries. Single-source vulnerability concentrates in specialized suturing needle production where two European suppliers dominate global capacity. Distribution runs through GPO-contracted medical-surgical distributors with regional warehousing networks serving hospital systems and ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fellowship-trained revisional surgeon scarcity constrains program expansion velocity, creating a structural bottleneck where demand for complex conversion procedures outstrips credentialed supply. This capability gap rewards early movers who secure specialized talent pipelines before competitors exhaust limited training program output.
For Market Incumbents: Secure exclusive purchasing agreements with emerging ambulatory surgical center chains in Arizona and Nevada before competitors establish footholds in site-neutral reimbursement corridors. Defend margin position by backward integration into polymer compounding for stapler cartridge housings, reducing exposure to commodity resin price swings. Monitor GLP-1 pharmacotherapy non-responder identification protocols as a demand-forecasting input for revisional case volume planning. For New Entrants and Emerging Players: Telehealth-enabled prehabilitation services represent a service-layer gap where incumbent hospital systems under-serve rural Appalachian and Mississippi Delta markets with limited bariatric surgeon density. Target these geographies with remote patient monitoring platforms that expand procedural candidacy pipelines without capital-intensive facility buildout. Pursue direct-to-patient digital scheduling channels that bypass traditional primary-care referral gatekeepers in high-smartphone-penetration Sun Belt metropolitan areas. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among robotic platform manufacturers with instrument cartridge attachment rates and specialized training network subscription models. Long-term viability across the analysis window favors targets with FDA breakthrough device designations in endoluminal suturing categories, where parallel regulatory and coverage submission strategies accelerate commercial entry. Watch for CMS innovation center waiver announcements for prediabetic metabolic surgery as an inflection signal for preventive procedure reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Exclusive purchasing agreements with Texas Medical Center affiliates lock in robotic platform placement and consumable volume. |
| FDA Submission | Breakthrough device designation for endoluminal suturing systems compresses premarket review timelines for BMI 30-35 populations. |
| Reimbursement Strategy | CMS national coverage determination advocacy shapes patient access for incisionless metabolic interventions. |
| Software Companion Development | Digital surgical planning platforms differentiate robotic-assisted procedures in complex revisional cases. |
| CE Marking Pathway | European regulatory clearance enables revenue diversification for U.S.-based endoluminal device manufacturers. |
Research Methodology
A spread of perspectives from bariatric surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions driving procedure volume and technology adoption trajectories. Primary interview insights combined with secondary validation from FDA 510(k) and de novo clearance databases, CMS national coverage determination records, and hospital procurement databases. Bottom-up facility-level procedure counts triangulated against top-down payer claims data across the analysis window.
Segmentation dimensions modeled include surgical procedure type, technology platform, end-user site of care, and regional regulatory cluster. CAGRs were derived from logistic adoption curves fitted to historical procedure volumes and projected payer coverage expansion patterns. Forecast inputs incorporated GLP-1 pharmacotherapy penetration scenarios and ambulatory surgical center migration rates by procedure complexity tier.
Forecasts assume regulatory continuity in FDA Center for Devices and Radiological Health review timelines and CMS reimbursement policy; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as state-level certificate-of-need requirements and employer-sponsored benefit design evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market