
 Bariatric Transport Wheelchairs Market | 2026-2036
Bariatric Transport Wheelchairs Market Size, Share, and Industry Trends Forecast 2026-2036
Bariatric Transport Wheelchairs Market Outlook
China is fragmenting as domestic manufacturers scale aluminum-frame production for export markets. Invacare Corporation leverages its North American distribution network to sustain hospital procurement contracts. Medline Industries anchors its position through private-label supply agreements with integrated delivery networks. Sunrise Medical competes on European design certification while extending its reclining wheelchair portfolio across rehabilitation channels.
Bariatric transport wheelchairs are reinforced mobility devices engineered to support patient weights exceeding standard thresholds, typically constructed from aluminum or steel alloys with welded cross-bracing and anti-tip mechanisms designed for attendant-propelled transit in clinical and residential environments. Heavy-duty wheelchairs dominate hospital procurement due to durability requirements under continuous institutional use, while transport wheelchairs capture margin pools in home care where lightweight collapsible frames reduce caregiver strain. Aluminum material grades lead unit volume for indoor-outdoor versatility, though composite frames represent the fastest-growing segment as manufacturers reduce overall chair weight without sacrificing load ratings.
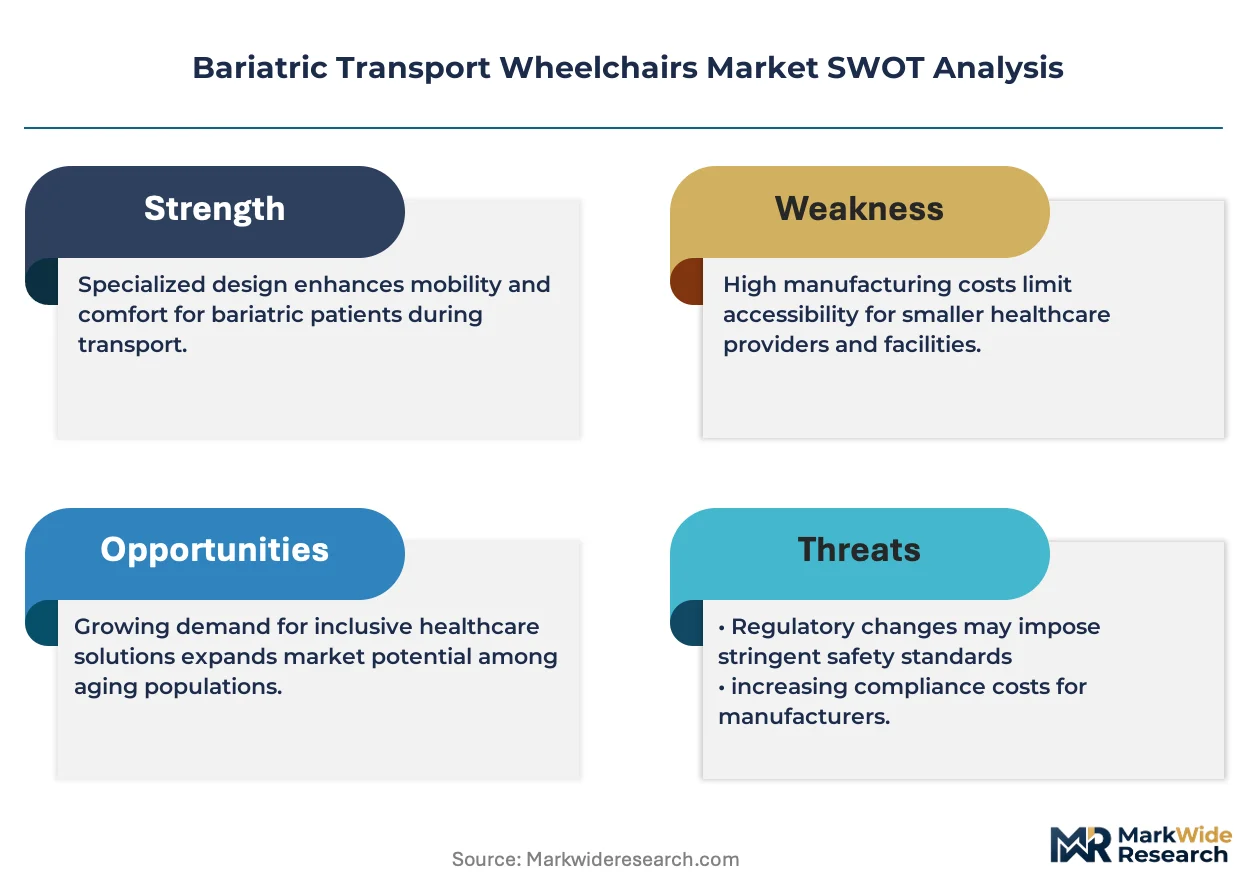
FDA 510(k) premarket notification and ISO 7176-8 standards govern frame testing and stability requirements, compelling manufacturers to document fatigue-cycle performance before commercial release. The EU Medical Device Regulation imposes additional clinical evaluation obligations on imported wheelchairs, reshaping market access timelines for non-European producers. Stakeholders must monitor evolving CMS durable medical equipment fee schedules and state-level Medicaid bariatric coverage expansions to anticipate reimbursement-driven demand shifts.
Market Dynamics
Home care agencies now drive the fastest demand acceleration as aging-in-place policies redirect reimbursement toward community-based mobility solutions, compressing traditional hospital procurement timelines and forcing manufacturers to reconfigure distribution networks for residential fulfillment.
Growth Catalysts
- Aluminum alloy innovation:Advanced 6061-T6 and 7005 aluminum grades enable lighter frame construction without sacrificing load ratings, expanding indoor-outdoor versatility for bariatric users.
- Medicare Advantage expansion:US private Medicare plans increasingly classify bariatric wheelchairs as preventive care investments, broadening reimbursement eligibility beyond traditional durable medical equipment carve-outs.
- Composite material adoption:Carbon fiber reinforced polymer frames reduce caregiver strain through weight reduction while maintaining structural integrity under continuous institutional use.
Market Restraints
- Steel price volatility:Heavy-duty welded frames remain dependent on high-tensile steel alloys, exposing margins to commodity fluctuations in global metallurgical markets.
- FDA 510(k) tightening:Enhanced Class II medical device scrutiny around frame integrity testing extends premarket notification timelines and elevates documentation burdens for new entrants.
- Manual attendant limitation:Transport wheelchair dependence on caregiver propulsion creates ceiling effects in severely obese patient populations where powered mobility substitutes offer independent operation.
Strategic Opportunities
- China domestic scale:Indigenous aluminum-frame manufacturers fragmenting export markets create white space for quality-tier positioning in North American and European channels.
- EU MDR compliance arbitrage:Clinical evaluation obligations imposed on imported wheelchairs delay non-European producers, rewarding early certification investments with sustained market access advantages.
- Rehabilitation channel extension:Reclining wheelchair portfolio expansion addresses post-surgical bariatric patient needs in skilled nursing facilities and outpatient rehabilitation centers.
Industry Challenges
- Welding certification scarcity:Frame integrity demands specialized aluminum and steel welding expertise that outpaces vocational training pipeline output in manufacturing regions.
- ISO 7176-8 fatigue testing:Stability and cycle-performance documentation requirements compress product development calendars and strain R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bariatric Transport Wheelchairs Market |
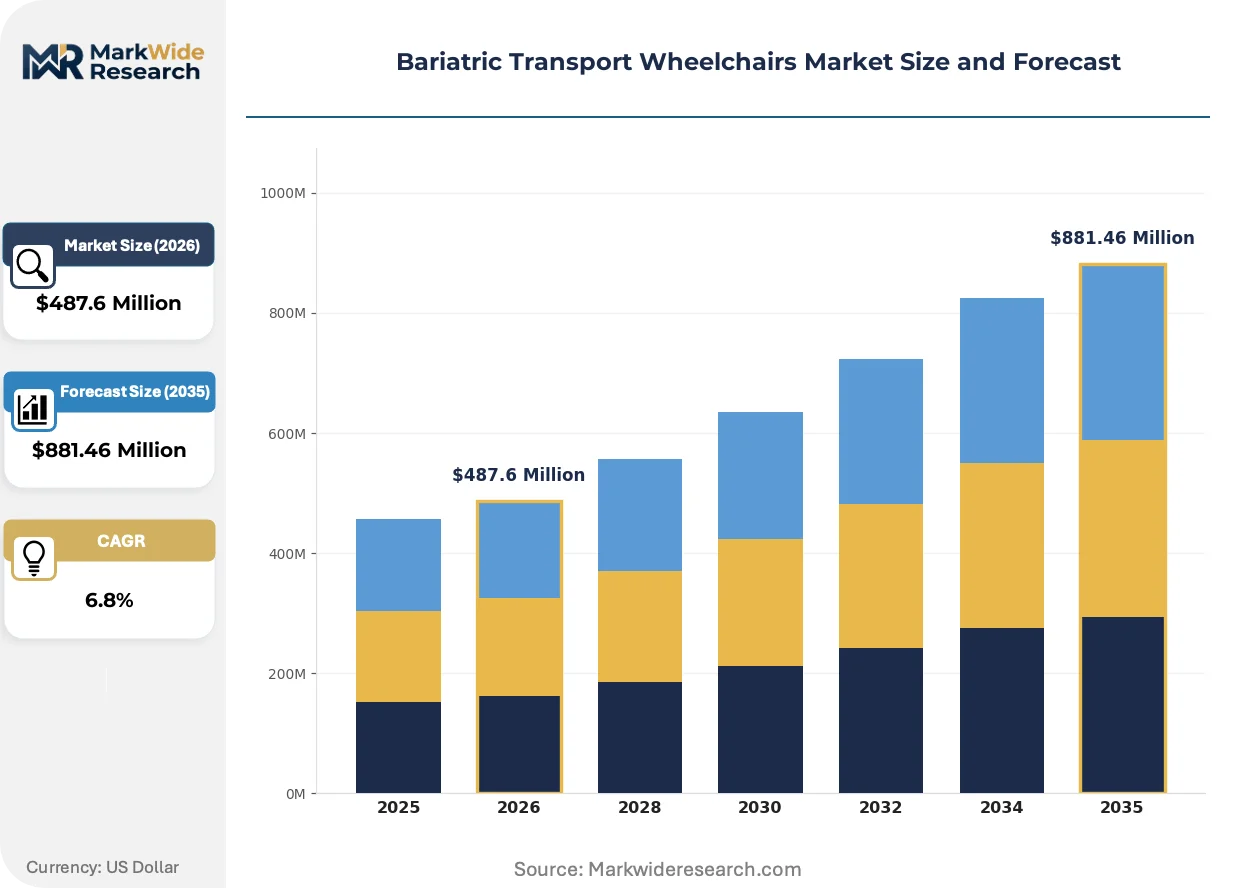
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Wheelchairs, Heavy-Duty Wheelchairs, Reclining Wheelchairs, Transport Wheelchairs Material: Aluminum, Steel, PVC, Composite Weight Capacity: 300 lbs, 400 lbs, 500 lbs, 600 lbs End User: Hospitals, Rehabilitation Centers, Home Care, Nursing Facilities |
| Companies Covered | Invacare Corporation, Medline Industries, Sunrise Medical, Drive Medical Design and Manufacturing, Karman Healthcare, GF Health Products, Pride Mobility Products, Ottobock, 21st Century Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bariatric Transport Wheelchairs Market Strategic Shifts
Material science convergence with regulatory pressure is compressing traditional product lifecycles and forcing simultaneous weight reduction and load-rating enhancement across all price tiers.
Composite frame technology is hybridizing aluminum substructures with carbon fiber reinforcement to achieve sub-20-kilogram transport weights while maintaining 450-pound capacity ratings. Rehabilitation centers and home care agencies are adopting these hybrid constructions fastest where caregiver injury prevention drives procurement criteria. The technology is hybridizing competitive positioning by enabling premium pricing in previously commoditized lightweight segments.
EU Medical Device Regulation clinical evaluation mandates are reshaping import compliance architecture for non-European wheelchair producers. The regulation forces documented biocompatibility and fatigue-cycle evidence that extends market access timelines by 12-18 months. North American and Asian manufacturers are responding through EU-based authorized representative partnerships and accelerated ISO 13485 quality system adoption.
Caregiver ergonomics now dominate residential purchase decisions as home care agencies institutionalize occupational safety metrics into equipment selection protocols. Hospital discharge planners and aging-in-place coordinators are displacing traditional durable medical equipment dealers as primary specification influencers. This behavioral pivot is most visible in US Medicare Advantage networks where star-rating incentives align provider and patient mobility outcomes.
Bariatric Transport Wheelchairs Market Segmentation
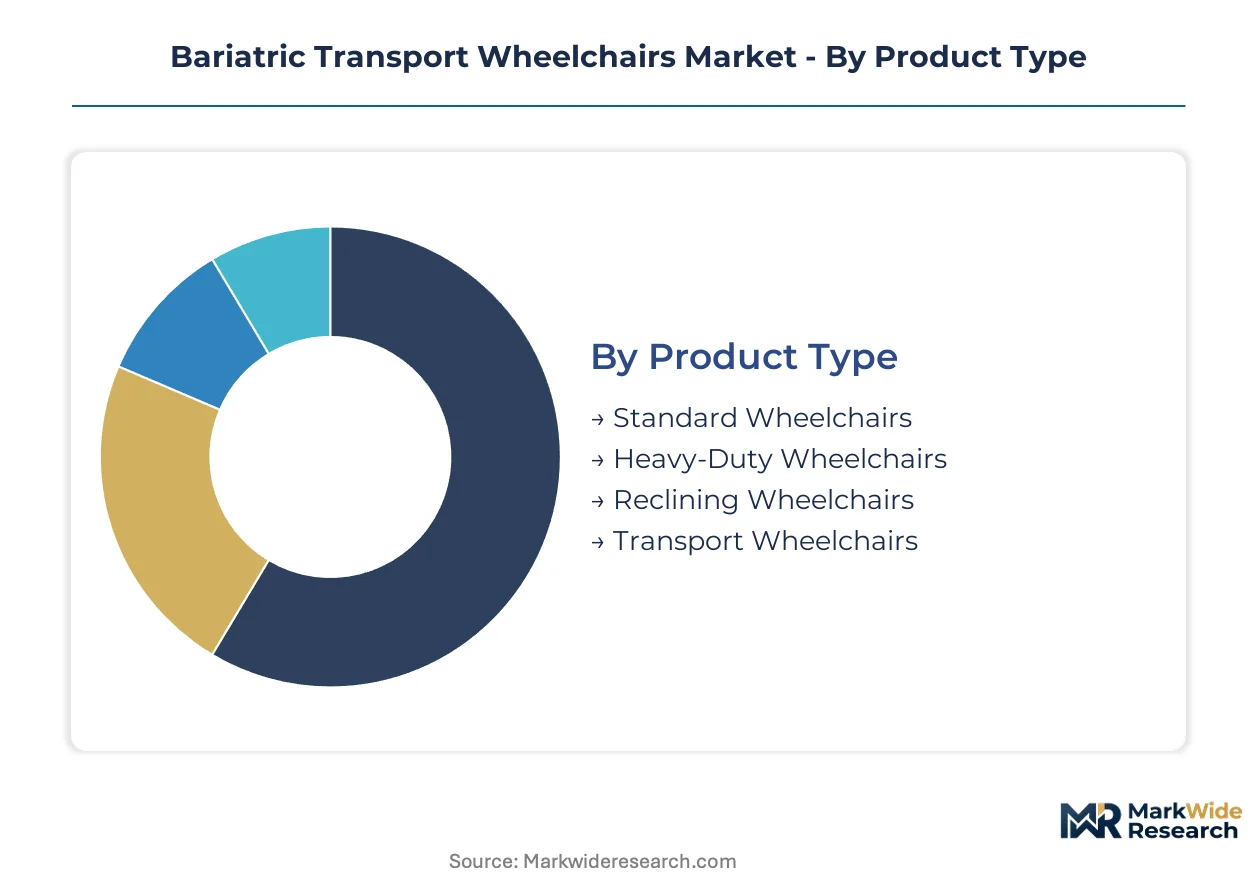
Segmentation in the bariatric transport wheelchairs market reveals distinct procurement patterns across clinical and residential channels. Each dimension—product construction, material grade, load specification, and care setting—carries unique reimbursement implications and caregiver workflow constraints that reshape manufacturer priorities.
Product Type:
The use-case spectrum spans permanent mobility solutions for independent users to attendant-propelled devices optimized for clinical transfer protocols.
- Heavy-Duty Wheelchairs:Reinforced steel or aluminum frames with welded cross-bracing support continuous institutional use. Hospital procurement contracts in the United States concentrate demand here due to durability requirements under 24-hour operational cycles.
- Transport Wheelchairs:Lightweight collapsible frames reduce caregiver strain during vehicle loading and residential navigation. Home care agencies across Medicare Advantage networks are accelerating purchases as aging-in-place policies redirect reimbursement toward community-based mobility solutions.
- Standard Wheelchairs:Baseline construction for bariatric users with moderate weight thresholds and intermittent use patterns.
- Reclining Wheelchairs:Articulating backrest mechanisms address post-surgical positioning needs in skilled nursing facilities.
The dominant share belongs to Heavy-Duty Wheelchairs, while Transport Wheelchairs is closing the gap fastest.
Material:
Cost tiers separate premium lightweight constructions from economy steel alternatives, with reimbursement rates often dictating material selection in institutional purchasing.
- Aluminum:6061-T6 and 7005 grades enable indoor-outdoor versatility without sacrificing load ratings. United States home care providers favor aluminum for its balance of durability and caregiver ergonomics.
- Composite:Carbon fiber reinforced polymer frames achieve sub-20-kilogram transport weights while maintaining 450-pound capacity ratings. Rehabilitation centers are adopting these constructions fastest where occupational safety metrics drive procurement criteria.
- Steel:High-tensile welded alloys dominate heavy-duty institutional specifications despite commodity price volatility exposure.
- PVC:Limited applications in non-structural components and seating surfaces for moisture-resistant configurations.
Aluminum commands the largest installed base, though Composite is expanding most quickly in premium channels.
Weight Capacity:
Volume concentrates in mid-range thresholds where Medicare reimbursement aligns with standard bariatric definitions, while extreme ratings serve specialized clinical populations.
- 500 lbs:The clinical standard for severe obesity management, supporting post-surgical bariatric patients and long-term care residents. Nursing facilities in the United States specify this threshold for liability coverage compliance.
- 400 lbs:Entry-level bariatric classification capturing overweight patients approaching surgical intervention. Home care agencies prefer this rating for cost-efficient aging-in-place equipment deployment.
- 300 lbs:Transitional threshold overlapping with reinforced standard wheelchair specifications.
- 600 lbs:Extreme-capacity construction for super-obese populations requiring custom frame engineering and reinforced wheel assemblies.
The 500 lbs rating holds the dominant position, while 400 lbs is gaining share fastest among residential purchasers.
End User:
Customer type determines specification rigor, with institutional buyers enforcing ISO 7176-8 fatigue testing and residential channels prioritizing weight reduction.
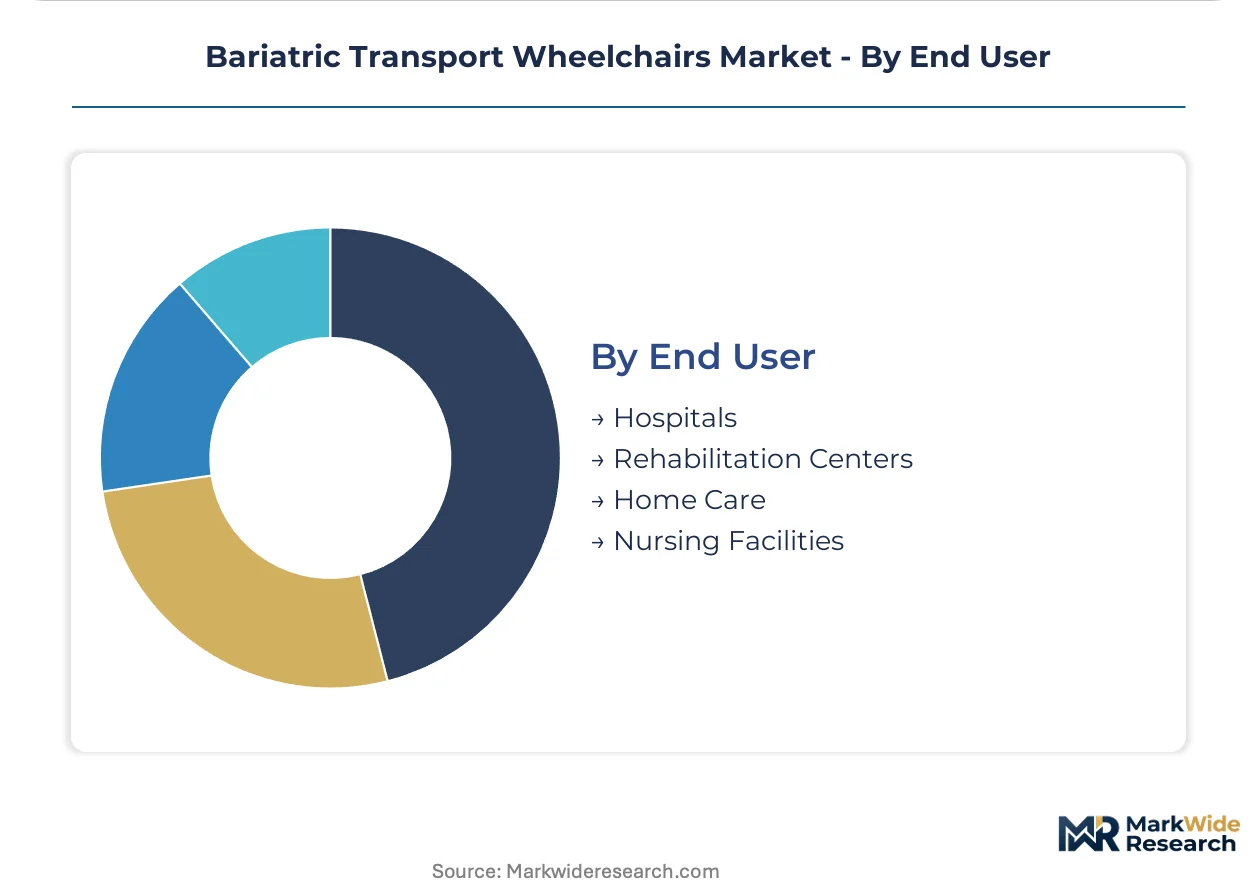
- Home Care:Aging-in-place coordinators and hospital discharge planners now specify equipment directly, displacing traditional durable medical equipment dealers. Medicare Advantage star-rating incentives align provider and patient mobility outcomes in United States markets.
- Hospitals:Central supply departments enforce frame integrity documentation under FDA 510(k) Class II medical device requirements. Continuous-use durability specifications exceed all other channel requirements.
- Rehabilitation Centers:Outpatient and skilled nursing facilities prioritize reclining configurations for post-surgical positioning protocols.
- Nursing Facilities:Long-term care operators balance acquisition cost against pressure injury prevention and staff injury reduction metrics.
Hospitals retain the largest procurement volume, yet Home Care is climbing the fastest as reimbursement shifts toward community-based delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance requirements for Class II medical devices establish the regulatory benchmark that shapes procurement standards across developed markets. Demand concentrates in the United States, where Medicare Advantage plans increasingly cover bariatric mobility equipment as preventive care investments. China fragments as domestic manufacturers scale aluminum-frame production for export markets.
United States
Medicare Advantage star-rating incentives align provider and patient mobility outcomes across 3,800 county-level markets. CMS durable medical equipment fee schedules govern reimbursement rates for bariatric wheelchairs in home care and institutional channels. The Great Lakes manufacturing corridor anchors heavy-duty steel frame production, with Ohio and Michigan facilities supplying hospital procurement contracts nationwide.
Germany
EU Medical Device Regulation clinical evaluation obligations reshape market access timelines for imported wheelchairs, extending premarket pathways by 12-18 months. Baden-Württemberg hosts precision welding clusters that serve ISO 7176-8 fatigue testing requirements for frame integrity documentation. Stuttgart-area engineering consultancies specialize in aluminum alloy specification for indoor-outdoor versatility ratings.
China
Domestic manufacturers exploit 6061-T6 aluminum grade availability to undercut premium-channel pricing in North American and European export markets. The national medical products regulator enforces GB standards for medical device registration that diverge from FDA and EU MDR frameworks. Yangtze River Delta fabrication clusters in Jiangsu and Zhejiang provinces concentrate export-oriented wheelchair assembly capacity.
Japan
Ministry of Economy, Trade and Industry (METI) guidelines promote carbon fiber reinforced polymer adoption in assistive devices to reduce caregiver injury incidence. JIS standards govern structural testing protocols that exceed baseline ISO requirements for institutional procurement. Osaka-Kobe industrial corridors specialize in composite material integration for sub-20-kilogram transport wheelchair constructions.
United Kingdom
National Health Service continuing healthcare budgets compress acquisition timelines for home care agencies specifying bariatric transport equipment. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining domestic market access pathways. Midlands manufacturing regions retain steel frame welding expertise serving NHS supply chain contracts.
Bariatric Transport Wheelchairs Market Competitive Environment
Integrated distribution networks and private-label supply agreements split the market between institutional contract holders and residential channel specialists. The vendor base concentrates around three strategic archetypes: North American hospital procurement incumbents, European design-certification leaders, and Asian export-scale fabricators. M&A activity targets rehabilitation channel extension capabilities, while strategic partnerships accelerate EU MDR compliance arbitrage for non-European producers.
Among North American contract holders, Invacare Corporation exemplifies the hospital procurement incumbent archetype through its durable medical equipment distribution infrastructure. Medline Industries occupies a position within the private-label supply tier, anchoring integrated delivery network relationships. Sunrise Medical represents the European design-certification vector, leveraging reclining wheelchair portfolio extension across rehabilitation channels.
| Leading Market Players |
|---|
| Invacare Corporation |
| Medline Industries |
| Sunrise Medical |
| Drive Medical Design and Manufacturing |
| Karman Healthcare |
| GF Health Products |
| Pride Mobility Products |
| Ottobock |
| 21st Century Scientific |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Yangtze River Delta aluminum-frame fabrication is compressing export pricing power while forcing contract manufacturers toward premium-channel differentiation. This utilization dynamic simultaneously erodes margin buffers in commoditized transport wheelchair tiers and rewards early EU MDR certification investments with pricing premiums.
Pricing Analysis
Chinese export pricing undercuts North American domestic production by certification-grade spreads, with unmarked aluminum frames trading at steep discounts to FDA 510(k)-cleared equivalents. Three-tier pricing structure across premium, standard, and economy levels separates composite-reinforced hybrid constructions from basic steel alternatives. Pricing pressure stems from Medicare Advantage reimbursement compression and home care agency volume consolidation. Hospital procurement committees demonstrate lowest price sensitivity due to liability-driven specification rigor, while independent durable medical equipment dealers face acute margin compression.
Supply Chain Analysis
Jiangsu and Zhejiang contract manufacturers hold dominant export assembly capacity, with secondary concentration in Ohio and Michigan for heavy-duty steel frame production. Raw material flows draw from 6061-T6 aluminum billet suppliers in China, high-tensile steel alloy mills in the United States, and carbon fiber prepeg sources from Japan. Single-source vulnerability concentrates in precision welding certification pipelines that lag frame integrity demand. Distribution runs through integrated delivery networks for institutional contracts and direct-to-agency fulfillment for residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Medicare Advantage network consolidation and integrated delivery network procurement centralization, fragmenting traditional dealer intermediaries.
For Market Incumbents: Build regulatory-certification moats through accelerated EU MDR authorized representative partnerships and ISO 13485 quality system adoption. Deepen backward integration into aluminum alloy specification to secure 6061-T6 supply commitments against Yangtze River Delta export competition. Prioritize rehabilitation channel control through reclining wheelchair portfolio extension. For New Entrants and Emerging Players: Build out private-label supply agreements with home care agencies bypassing traditional durable medical equipment dealer networks. Target the 400-pound weight capacity segment where Medicare Advantage reimbursement creates specification white space. Lead with caregiver ergonomics messaging anchored to occupational safety metrics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across composite-frame hybrid manufacturing due to carbon fiber prepeg curing equipment requirements. Acquisition targets should demonstrate EU MDR technical documentation completion and established authorized representative relationships. Watch FDA 510(k) clearance timeline extensions as inflection signal for regulatory-barrier value capture.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Authorized Representative Partnership | Accelerates market access timelines by 12-18 months for non-European producers. |
| Composite Frame Hybrid Manufacturing Scale-Up | Captures premium pricing in sub-20-kilogram transport wheelchair segments. |
| Hospital System Direct Procurement Contract | Locks out dealer intermediaries through integrated delivery network agreements. |
| Reimbursement Strategy Development | Aligns product specifications with Medicare Advantage preventive care carve-outs. |
| Precision Welding Certification Pipeline Investment | Addresses ISO 7176-8 fatigue testing documentation bottlenecks. |
Study Parameters
A spread of perspectives from hospital purchasing committees, home care agency procurement directors, biomedical engineers, and GPO contracts managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, CMS durable medical equipment fee schedules, hospital procurement contract disclosures, and ISO 7176 certification records. Bottom-up unit demand modeling and top-down reimbursement flow analysis were triangulated.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling across product construction type, material grade, weight capacity threshold, and care setting. CAGRs were derived from reimbursement trajectory analysis and aluminum alloy cost curve projections. Industry-specific forecast inputs included Medicare Advantage enrollment shifts and EU MDR implementation pace.
Stress conditions across steel commodity volatility, FDA premarket notification timeline variance, and caregiver ergonomics specification adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding aging-in-place policy durability and CMS reimbursement stability. Quarterly review of Medicare Advantage star-rating incentive adjustments and EU MDR clinical evaluation obligation interpretations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
Canada Bariatric Surgery Market