
 North America Bariatric Surgery Devices Market | 2026-2036
North America Bariatric Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bariatric Surgery Devices Market Insights
Modular platform configurations in stapling and energy devices is shifting how hospital procurement committees evaluate capital outlays against per-procedure economics. Medtronic leverages its integrated surgical ecosystem to anchor premium positioning across integrated delivery networks. Johnson & Johnson competes through broad instrument portfolios that span open, laparoscopic, and robotic access modalities. Intuitive Surgical dominates robotic bariatric installations, with its system placements creating captive demand for proprietary consumables.
Bariatric surgery devices encompass implants, surgical instruments, accessory equipment, and consumables designed to alter gastrointestinal anatomy for weight reduction, typically constructed from biocompatible polymers, titanium alloys, and stainless steel with precision tolerances measured in millimeters for anastomotic integrity. Gastric bypass and sleeve gastrectomy devices command the largest revenue pools given procedure volume concentration, while robotic surgery instrumentation represents the fastest-expanding procedure type as capital-conversion cycles accelerate. Hospitals absorb the dominant share of end-user spending due to inpatient infrastructure requirements, though surgical centers capture margin-rich outpatient sleeve cases where payer authorization permits.
FDA 510(k) clearance pathways and CMS national coverage determinations govern market access timelines and reimbursement viability for novel bariatric technologies across the United States. Health Canada and the FDA coordinate on post-market surveillance protocols for implantable obesity devices, creating dual-jurisdiction compliance burdens for manufacturers serving cross-border health systems. Stakeholders must monitor evolving CMS technology add-on payment decisions and state-level Medicaid bariatric coverage expansions to anticipate demand inflection points before competitors lock in contracting relationships.
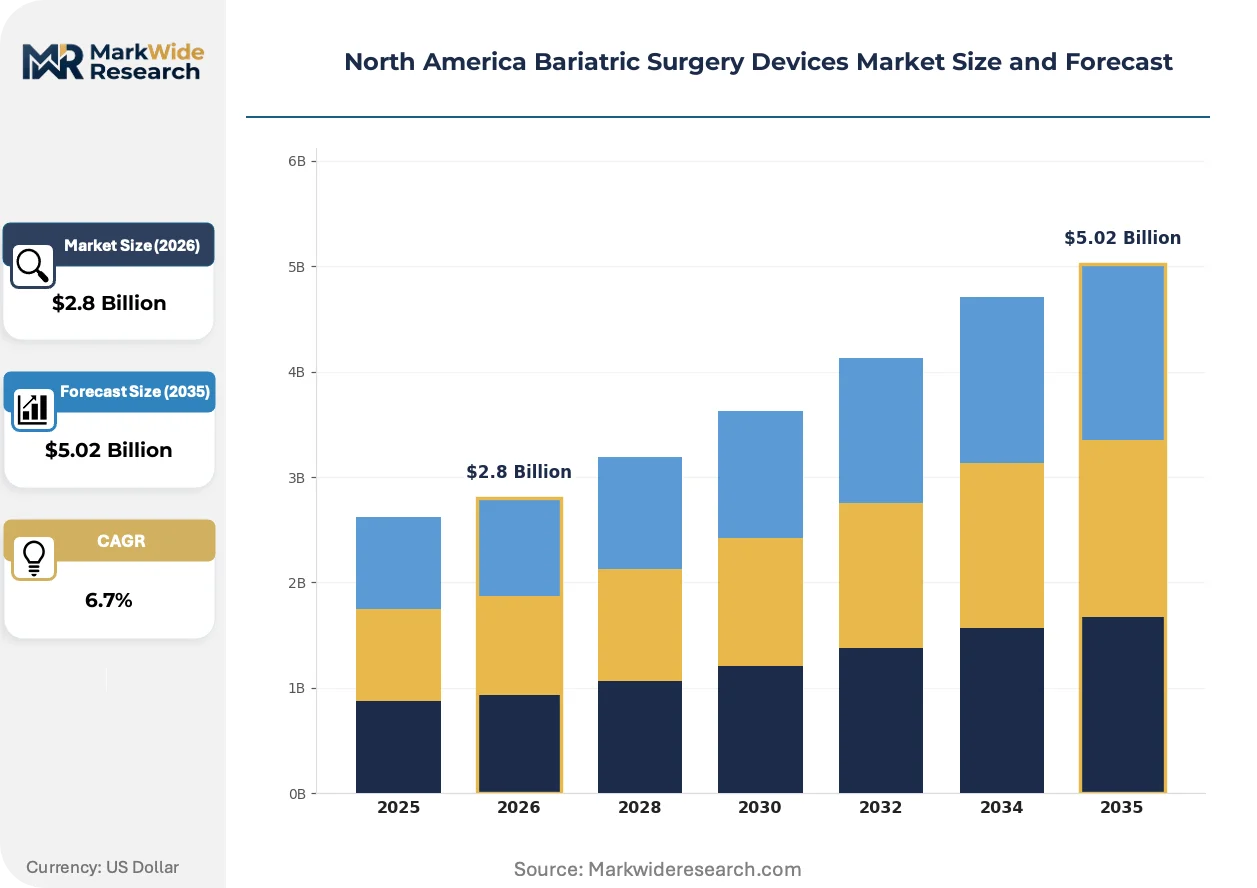
Market Dynamics
CMS reimbursement compression and site-of-service payment differentials are restructuring how bariatric programs allocate capital between inpatient suites and ambulatory surgical centers across the United States and Canada.
Growth Catalysts
- Medicaid Expansion:State-level coverage authorizations for metabolic surgery in Texas and Florida are unlocking previously uninsured patient volumes.
- Staple Line Reinforcement Materials:Synthetic buttressing technologies are reducing anastomotic leak rates and extending revision-free intervals.
- ASMBS Accreditation Standards:Comprehensive center certification requirements are mandating minimum device inventory thresholds that expand procurement volumes.
Market Restraints
- Titanium Alloy Concentration:Raw material sourcing dependence on specialized Japanese and Chinese metallurgical suppliers creates input cost volatility.
- FDA 510(k) Pathway Friction:Substantial equivalence determinations for novel anastomotic devices extend commercialization timelines by 18-24 months.
- Non-Surgical GLP-1 Therapeutics:Semaglutide and tirzepatide prescriptions are capturing pre-surgical candidates who previously converted to procedural intervention.
Strategic Opportunities
- Canadian Provincial Procurement:Ontario and Quebec health system consolidations are creating single-buyer contracting vehicles for multi-hospital device agreements.
- Endoluminal Sleeve Systems:Transoral incisionless platforms are opening outpatient metabolic intervention to BMI 30-35 populations previously excluded from reimbursement.
- Robotic-Assisted Revision Surgery:Convergence of haptic feedback instrumentation with 3D anatomical mapping is enabling complex redo procedures in community hospital settings.
Industry Challenges
- Bariatric Surgery Fellowship Pipeline:ACGME-accredited training position scarcity limits qualified surgeon supply in Mountain West and Great Plains metropolitan corridors.
- Legacy EMR Integration:Proprietary data formats from Intuitive Surgical and Medtronic platforms complicate quality registry reporting to MBSAQIP databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bariatric Surgery Devices Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion End User: Hospitals, Surgical Centers, Outpatient Clinics, Research Institutions Procedure Type: Laparoscopic Surgery, Open Surgery, Robotic Surgery, Endoscopic Surgery Component: Implants, Surgical Instruments, Accessory Equipments, Consumables |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific, Intuitive Surgical, Olympus Corporation, Conmed Corporation, Teleflex, Karl Storz, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bariatric Surgery Devices Market Trends and Innovations
Device architecture is pivoting from standalone instruments toward ecosystem-locked consumables that tether recurring revenue to initial capital placement decisions.
Powered stapling platforms with integrated tissue sensing algorithms are automating compression force calibration across variable gastric wall thickness. Academic medical centers in California and Illinois are deploying these systems in high-volume sleeve gastrectomy programs. The technology is automating subjective surgeon judgment during staple firing, reducing staple line bleeding events and associated transfusion costs.
FDA breakthrough device designation pathways and parallel Health Canada priority review streams are compressing premarket timelines for implantable gastric stimulation systems. Manufacturers with dual-jurisdiction regulatory strategies are securing synchronized approvals that prevent competitive arbitrage across the US-Canada border. Metabolic device startups are responding by establishing early-stage quality management systems that satisfy both FDA QSR and ISO 13485 requirements simultaneously.
Hospital value analysis committees are consolidating vendor relationships around single-source agreements that bundle capital equipment, disposables, and service contracts. Integrated delivery networks in Texas and Florida are displacing fragmented multi-vendor purchasing with system-wide standardization mandates. This concentration is most visible in metropolitan surgical corridors where three-hospital networks command sufficient volume to extract performance guarantees on leak rate outcomes.
North America Bariatric Surgery Devices Market Segmentation
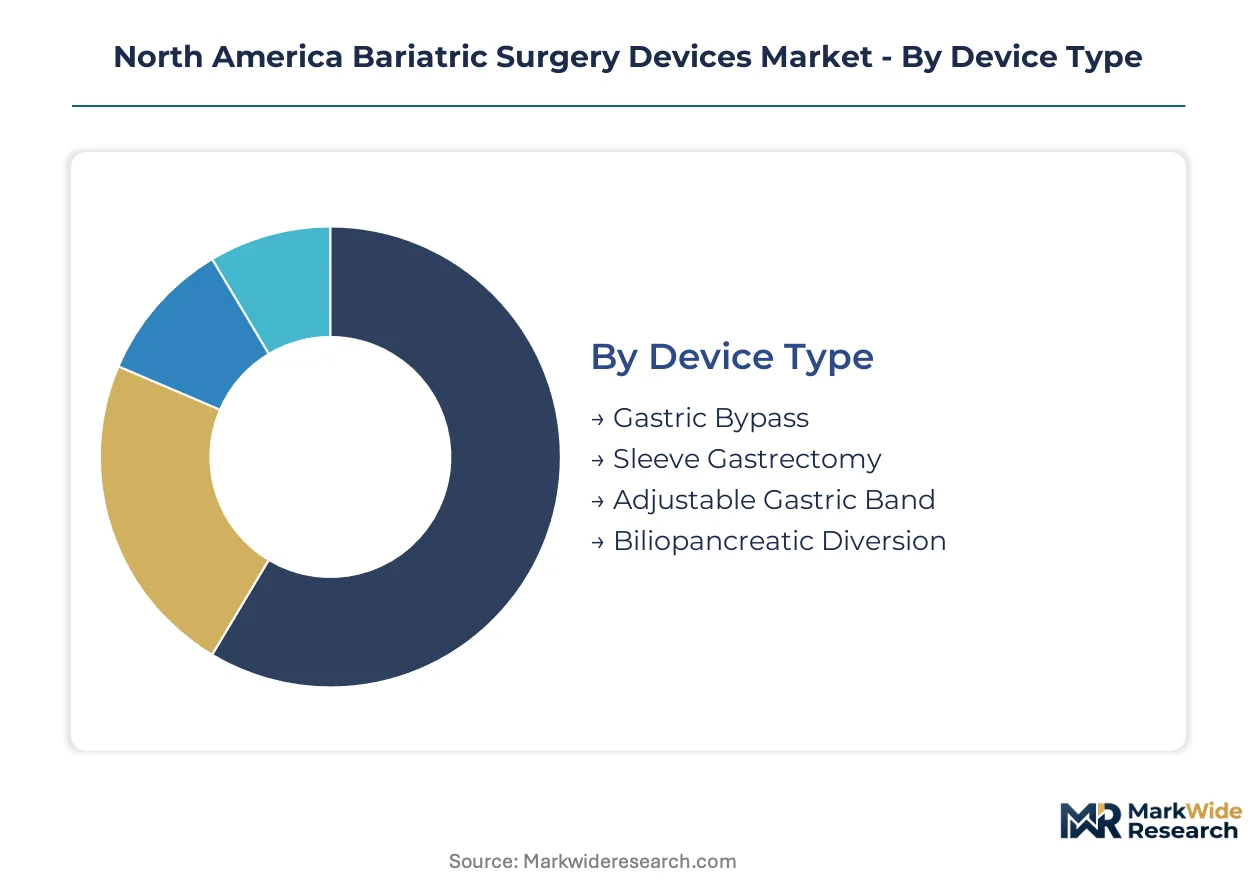
Device segmentation in bariatric surgery determines procurement workflows, reimbursement coding, and capital allocation across integrated delivery networks. Category boundaries increasingly blur as manufacturers bundle implants with robotic platforms and stapling systems into single-source contracts.
Device Type:
Customization intensity varies from standardized band systems to patient-matched bypass configurations requiring intraoperative anatomical adaptation.
- Gastric Bypass:Roux-en-Y configurations utilize titanium alloy staples and linear cutters to create gastrojejunal anastomoses with 12-15 mm diameter specifications. Demand concentrates in Texas and Florida hospital systems where Medicaid expansion has unlocked previously uninsured patient volumes, though revision surgery rates elevate long-term consumable attach rates.
- Sleeve Gastrectomy:Longitudinal gastric resection along the greater curvature employs powered stapling platforms with integrated tissue sensing. California and Illinois academic medical centers deploy these systems in high-volume programs, automating compression force calibration across variable gastric wall thickness to reduce staple line bleeding.
- Adjustable Gastric Band:Silicone elastomer devices with subcutaneous port systems for saline adjustment.
- Biliopancreatic Diversion:Malabsorptive procedures requiring specialized limb-length measurements and anastomotic stapling.
Most installed capacity flows through sleeve gastrectomy systems. Expansion is steepest in gastric bypass configurations as metabolic surgery indications broaden.
End User:
Site-of-service economics separate high-fixed-cost inpatient infrastructure from margin-focused ambulatory alternatives.
- Hospitals:Inpatient suites absorb dominant spending share due to ICU backup requirements, blood bank access, and emergency conversion capabilities for anastomotic leak management. Texas metropolitan surgical corridors concentrate demand where three-hospital networks extract performance guarantees.
- Surgical Centers:Freestanding facilities capture outpatient sleeve gastrectomy cases where payer authorization permits, operating at lower fixed cost bases with same-day discharge protocols. Florida health system consolidations are creating single-buyer contracting vehicles.
- Outpatient Clinics:Endoluminal sleeve delivery and preoperative consultation services.
- Research Institutions:Academic medical centers in California and Illinois piloting powered stapling automation.
Hospital procurement committees dominate capital outlay decisions. Surgical centers are gaining share fastest in Florida and Texas where site-neutral payment differentials favor outpatient migration.
Procedure Type:
Technology maturity spans decades-old open techniques to capital-intensive robotic installations with ecosystem-locked consumables.
- Laparoscopic Surgery:Multi-port and single-incision approaches utilizing reusable trocars and hand instruments with 5-12 mm shaft diameters. Community hospitals across the Mountain West and Great Plains rely on laparoscopic suites given fellowship-trained surgeon scarcity limiting robotic program launches.
- Robotic Surgery:Da Vinci system placements create captive demand for proprietary EndoWrist instruments and vessel sealers. Capital-conversion cycles accelerate as integrated delivery networks standardize platform choices, with Texas and Florida networks mandating system-wide vendor consolidation.
- Open Surgery:Reserved for revision cases and super-obese patients exceeding laparoscopic port limitations.
- Endoscopic Surgery:Transoral incisionless platforms targeting BMI 30-35 populations previously excluded from reimbursement.
Laparoscopic capacity dominates procedure volumes. Robotic-assisted platforms are climbing the fastest as haptic feedback instrumentation enables complex redo procedures in community settings.
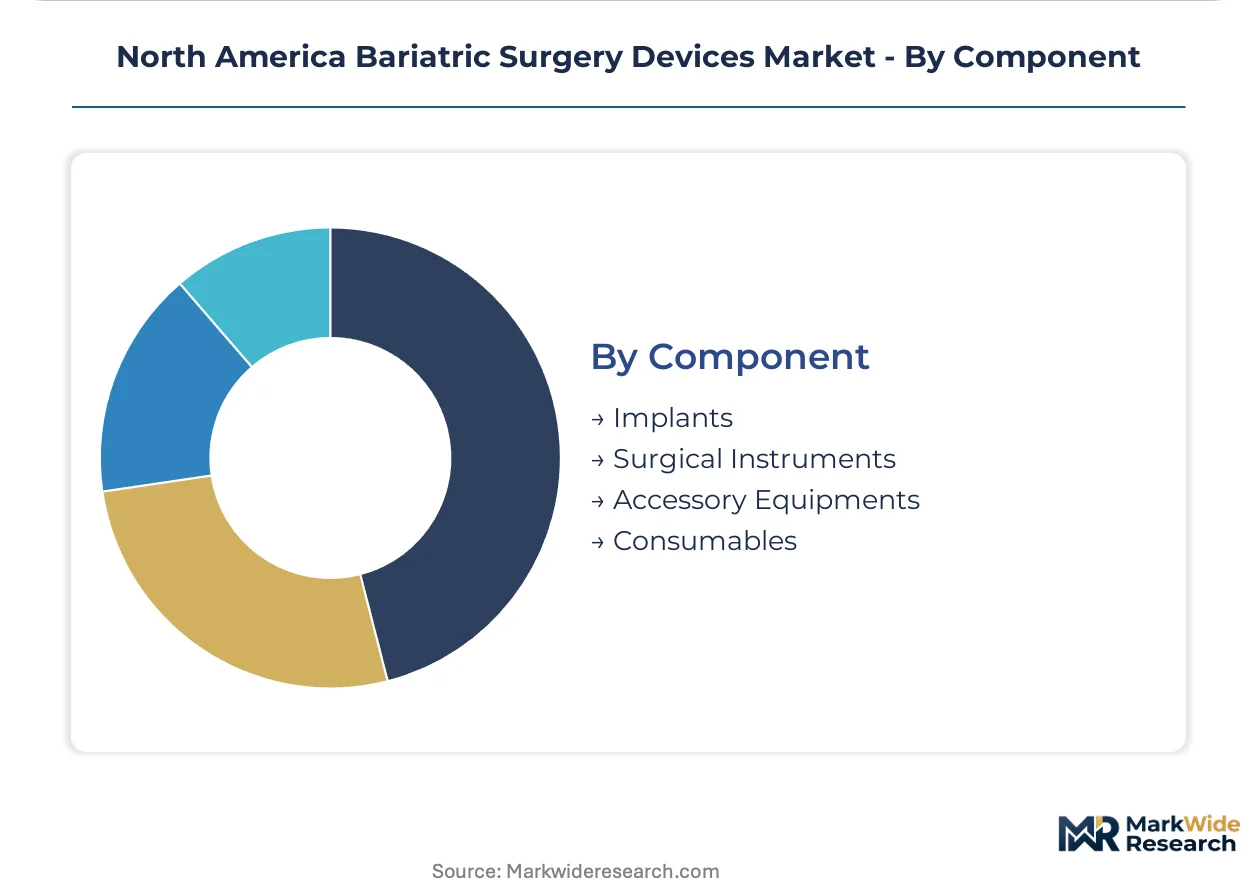
Component:
Margin structure separates high-volume consumables from lumpy capital equipment with extended replacement cycles.
- Implants:Gastric bands, electrical stimulation devices, and intragastric balloons constructed from biocompatible polymers and medical-grade silicone. FDA breakthrough device designations and parallel Health Canada priority reviews compress premarket timelines for novel stimulation systems.
- Consumables:Staple cartridges, energy device tips, and trocar seals generate recurring revenue tethered to initial capital placement. Integrated delivery networks in Texas bundle these into single-source agreements spanning capital, disposables, and service contracts.
- Surgical Instruments:Reusable graspers, retractors, and needle drivers with sterilization durability requirements.
- Accessory Equipments:Insufflators, irrigation pumps, and specimen retrieval systems.
Consumable flows dominate recurring procurement volumes. Implant categories are expanding most quickly as endoluminal and neurostimulation platforms enter reimbursement pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bariatric surgery device manufacturing originated in the United States during the 1990s with the commercialization of laparoscopic adjustable gastric band systems, establishing North America as the foundational market for metabolic surgical technology.
United States
Texas and Florida metropolitan surgical corridors concentrate sleeve gastrectomy volume as Medicaid expansion unlocks previously uninsured patient populations. FDA 510(k) clearance pathways and CMS national coverage determinations govern commercialization timelines for novel anastomotic technologies. California academic medical centers in Los Angeles and San Francisco deploy powered stapling platforms with tissue sensing automation in high-volume programs.
Canada
Ontario and Quebec health system consolidations create single-buyer contracting vehicles for multi-hospital device agreements spanning capital equipment and consumables. Health Canada coordinates post-market surveillance protocols with FDA for implantable obesity devices, imposing dual-jurisdiction compliance burdens on cross-border suppliers. Toronto and Montreal surgical centers capture outpatient sleeve cases where provincial authorization permits same-day discharge protocols.
Mexico
Medical tourism corridors in Tijuana and Mexico City attract bariatric patients from the United States seeking cost-differentiated sleeve gastrectomy procedures. COFEPRIS regulatory pathways for medical devices create parallel approval requirements for manufacturers serving private hospital chains. Guadalajara and Monterrey metropolitan areas concentrate accredited bariatric centers serving domestic insured populations and cross-border referral networks.
North America Bariatric Surgery Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with integrated surgical ecosystems rather than standalone device specialists. Three to five multinational corporations capture dominant revenue share through bundled capital and consumable offerings. Strategic archetypes separate platform-integrated players from instrument portfolio generalists and robotic system specialists. Competitive moves concentrate on single-source contracting mandates across integrated delivery networks and ecosystem lock-in through proprietary consumable tethering.
Among diversified medical technology conglomerates, Medtronic plc, Johnson & Johnson, and Intuitive Surgical, Inc. exemplify contrasting strategic positions. Medtronic leverages its integrated surgical ecosystem to anchor premium positioning across hospital procurement committees. Johnson & Johnson competes through broad instrument portfolios spanning multiple access modalities. Intuitive Surgical occupies a distinct position through robotic platform placements that generate captive demand for proprietary consumables. These three entities represent the dominant competitive anchors shaping vendor consolidation dynamics in Texas and Florida health system networks.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific |
| Intuitive Surgical |
| Olympus Corporation |
| Conmed Corporation |
| Teleflex |
| Karl Storz |
| Stryker |
| Others |
Pricing and Supply Chain Analysis
Titanium alloy feedstock from Japanese and Chinese metallurgical suppliers flows through three pricing tiers before reaching hospital procurement committees, with raw material volatility compressing margins at the consumables level while integrated delivery networks extract performance guarantees at the capital equipment tier.
Pricing Analysis
Three-tier pricing structure across premium robotic platforms, standard powered stapling systems, and economy laparoscopic instrument sets governs vendor negotiations. Price differentiation hinges on FDA breakthrough device designation status and bundled service contract scope. Cost compression in the standard tier is intensifying because GPOs are consolidating contract vehicles around single-source mandates. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while academic medical centers prioritize outcome guarantees over per-unit economics.
Supply Chain Analysis
ISO 13485 and FDA QSR dual certification requirements gate supplier entry, with qualified vendors concentrated in the United States, Germany, and Japan for precision-machined stapling components. Raw material sourcing draws from Chinese titanium sponge producers, Japanese alloy processors, and domestic polymer compounders in Ohio and Texas. Single-source vulnerability persists for tissue-sensing algorithm chipsets sourced from Taiwanese semiconductor foundries. Distribution runs through manufacturer-direct sales forces serving integrated delivery networks, with regional distribution centers in Dallas and Chicago managing consumable replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
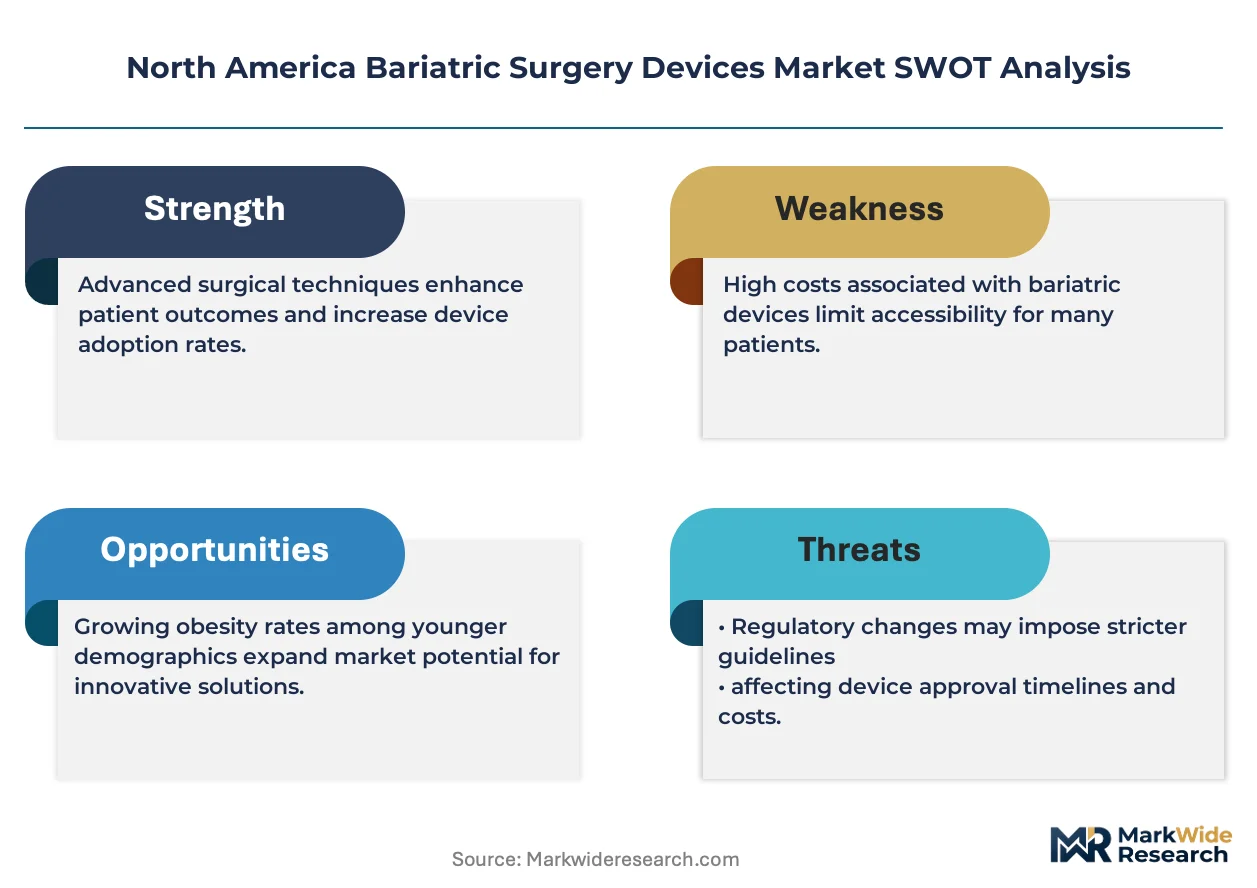
Margin expansion in this market rests on converting capital placements into captive consumable revenue streams, with powered stapling automation and robotic platform tethering shifting procurement economics toward recurring revenue models.
For Market Incumbents: Acquire endoluminal sleeve technology platforms to preempt GLP-1 therapeutic displacement of traditional surgical volumes. Fortify positions by embedding predictive maintenance algorithms into capital equipment, creating switching costs that resist GPO standardization mandates. Deepen backward integration into titanium alloy processing to insulate margins from East Asian supply volatility. For New Entrants and Emerging Players: The premium-to-economy price gap in robotic consumables opens white-space opportunity for compatible instrument alternatives. Target community hospital systems in the Mountain West and Great Plains where fellowship-trained surgeon scarcity limits robotic program launches. Pursue FDA 510(k) clearance for powered stapling platforms with simplified tissue-sensing architectures to undercut ecosystem-locked incumbents on per-procedure economics. For Investors and Strategic Acquirers: Consolidation pressure builds where metabolic device startups hold parallel FDA-Health Canada regulatory filings but lack hospital system contracting relationships. Five-to-ten-year viability favors platforms with demonstrated anastomotic leak rate reductions and established MBSAQIP registry integration. Watch for CMS technology add-on payment decisions as inflection indicators for novel implantable stimulation systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates commercialization timelines for novel anastomotic stapling platforms in high-volume sleeve programs. |
| Hospital System Partnership | Locks in multi-year single-source agreements across Texas and Florida integrated delivery networks. |
| Software Companion Development | Enables predictive maintenance revenue and complicates competitive displacement for capital equipment. |
| Reimbursement Strategy | Secures CMS national coverage determinations and state Medicaid expansion authorizations for device categories. |
| CE Marking Pathway | Facilitates cross-border Canadian market access through Health Canada priority review coordination. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with bariatric surgeons, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineering directors were cross-validated against secondary sources including FDA 510(k) clearance databases, CMS Medicare claims data, hospital procurement registries, and ASMBS accreditation records. Triangulation between demand-side consumption patterns and supply-side production disclosures ensures dimensional consistency across segmentation estimates.
Input-output matrices map procedure volume projections through device utilization rates, average selling price assumptions, and replacement cycle dynamics across the analysis window. Segmentation dimensions span device type, end-user facility category, procedure modality, and component margin structure. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns, with robotic-assisted platform penetration and Medicaid expansion eligibility serving as key forecast sensitivities.
Caveats apply where GLP-1 therapeutic efficacy improvements or CMS site-of-service payment recalibrations could materially shift the outlook. Forecasts reflect assumptions regarding regulatory clearance timelines, reimbursement stability, and raw material supply continuity. A model refresh is warranted upon material change in FDA breakthrough device designation throughput or provincial Canadian health system consolidation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
Chile Bariatric Surgery Market