
 Fecal Occult Testing Market | 2026-2036
Fecal Occult Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Fecal Occult Testing Market Intelligence
CLIA certification is bifurcating the competitive landscape for fecal occult testing manufacturers and service providers. Abbott Laboratories leverages its diagnostic automation infrastructure to sustain high-throughput laboratory relationships across North America. Eiken Chemical Co. Ltd. anchors its position through specialized immunochemical reagent production with deep penetration in Asian clinical markets.
Fecal occult testing encompasses laboratory and point-of-care methods designed to detect trace hemoglobin or altered DNA in stool specimens, typically achieving sensitivity thresholds of 50 ng hemoglobin per milliliter for immunochemical formats. These tests serve as primary non-invasive screening tools for colorectal neoplasia in asymptomatic populations. The immunochemical test segment commands the dominant share due to superior specificity and elimination of dietary restrictions, while stool DNA testing represents the fastest-expanding category as molecular techniques achieve broader reimbursement acceptance. Hospitals retain the largest end-user footprint, though home care collection models are gaining structural traction through direct-to-patient distribution channels.
The FDA regulates fecal occult blood devices as in vitro diagnostics under 21 CFR 864, while the Centers for Medicare & Medicaid Services governs national coverage determination for screening intervals. The Clinical Laboratory Improvement Amendments establish personnel and quality standards that directly constrain which laboratories may offer high-complexity stool DNA analysis. Stakeholders must monitor evolving USPSTF grade recommendations and parallel EMA in vitro diagnostic regulation implementation timelines to anticipate reimbursement and market access shifts.
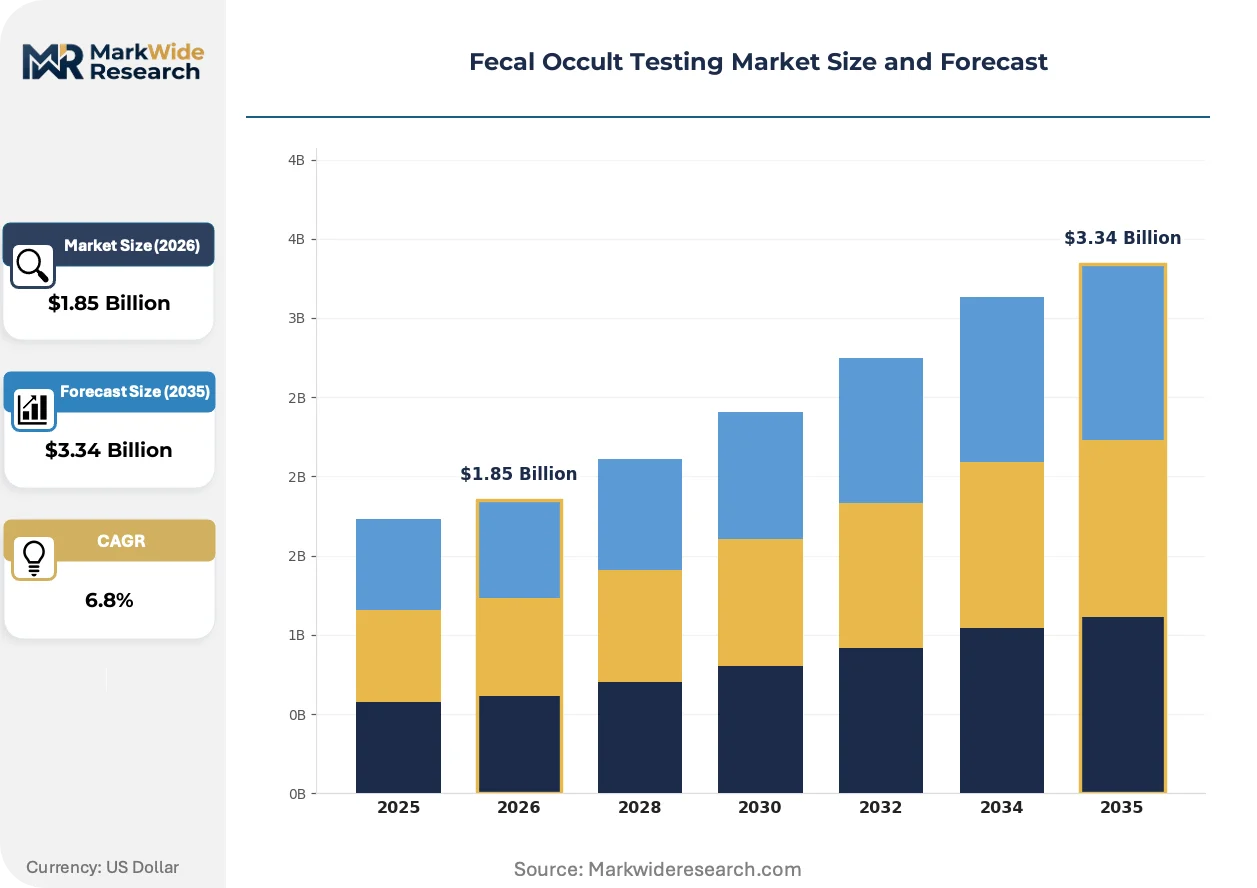
Market Dynamics
The fecal occult testing market is undergoing a fundamental transition from guaiac-based chemical detection to immunochemical and molecular methodologies, driven by reimbursement structures that now favor quantitative hemoglobin measurement and DNA biomarker panels with superior sensitivity thresholds.
Growth Catalysts
- Medicare national coverage determination:The CMS decision to cover annual FIT screening and triennial stool DNA testing for average-risk beneficiaries aged 45-75 is expanding addressable patient populations across United States outpatient networks.
- Immunochemical reagent automation:High-throughput clinical analyzers from diagnostic platforms now process 300-plus specimens hourly, eliminating manual sample handling and reducing laboratory technician burden.
- Japan's population aging curve:METI-backed cancer screening mandates targeting 50% participation rates by 2030 are institutionalizing fecal occult testing within municipal health checkup programs.
Market Restraints
- CLIA high-complexity certification barriers:Stool DNA analysis requires specialized personnel qualifications and quality control protocols that limit laboratory participation to tertiary medical centers and reference laboratories.
- Guaiac reagent supply concentration:Hemoccult and similar chemical-based tests rely on resin-impregnated paper manufacturing concentrated in limited North American production facilities.
- Colonoscopy substitution threat:Direct-to-consumer colonoscopy scheduling platforms and virtual colonoscopy CT protocols compete for the same asymptomatic screening cohort.
Strategic Opportunities
- India's tier-2 city laboratory networks:Diagnostic chains expanding beyond Mumbai, Delhi, and Bangalore into Surat, Indore, and Coimbatore present unserved demand for affordable FIT protocols.
- EMA IVDR implementation timeline:The 2027 full enforcement deadline for in vitro diagnostic medical device regulation creates first-mover advantage for manufacturers with notified body certification already secured.
- Telehealth-integrated home collection:Direct-to-patient sample logistics paired with virtual result consultation is bypassing traditional primary care gatekeeper relationships.
Industry Challenges
- Molecular diagnostics talent scarcity:CLIA-certified laboratory directors with stool DNA assay validation experience command premium compensation in tight regional labor markets.
- FDA 510(k) predicate device pathway congestion:Novel biomarker combinations lacking established predicates face elongated review timelines and additional clinical validation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fecal Occult Testing Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Guaiac Test, Immunochemical Test, Hybrid Test, Stool DNA Test End User: Hospitals, Diagnostic Laboratories, Home Care, Clinics Distribution Channel: Direct Sales, Online Stores, Pharmacies, Medical Supply Distributors Technology: Enzyme Immunoassay, Lateral Flow Test, ELISA, Molecular Techniques |
| Companies Covered | Abbott Laboratories, Quidel Corporation, Eiken Chemical Co. Ltd., Danaher Corporation, Quest Diagnostics Incorporated, Siemens Healthcare GmbH, Biohit Oyj, Epigenomics AG, Exact Sciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fecal Occult Testing Market Strategic Shifts & Innovations
Automation and biomarker multiplexing are compressing the cost-per-test economics of fecal occult screening while expanding the clinical information content extracted from single specimens.
Quantitative fecal immunochemical testing is displacing qualitative guaiac-based methods across United States health systems. Hospital laboratories and commercial reference chains are adopting automated FIT platforms that report exact hemoglobin concentrations rather than binary positive-negative results. This shift enables risk-stratified colonoscopy referral protocols and is compressing the volume of unnecessary diagnostic procedures.
EMA's In Vitro Diagnostic Medical Devices Regulation is forcing manufacturers to revalidate existing assays under stricter clinical evidence requirements. The 2027 enforcement deadline is accelerating consolidation among smaller IVD producers lacking notified body relationships. European hospital procurement committees are now demanding MDR technical documentation as a precondition for contract renewal.
Direct-to-consumer distribution models are disrupting traditional physician-mediated screening pathways. United States consumers now order FIT kits through employer wellness platforms and pharmacy retail channels, bypassing clinic-based sample collection. This channel shift concentrates volume with logistics-integrated laboratories capable of at-home kit fulfillment and digital result delivery.
Fecal Occult Testing Market Segmentation
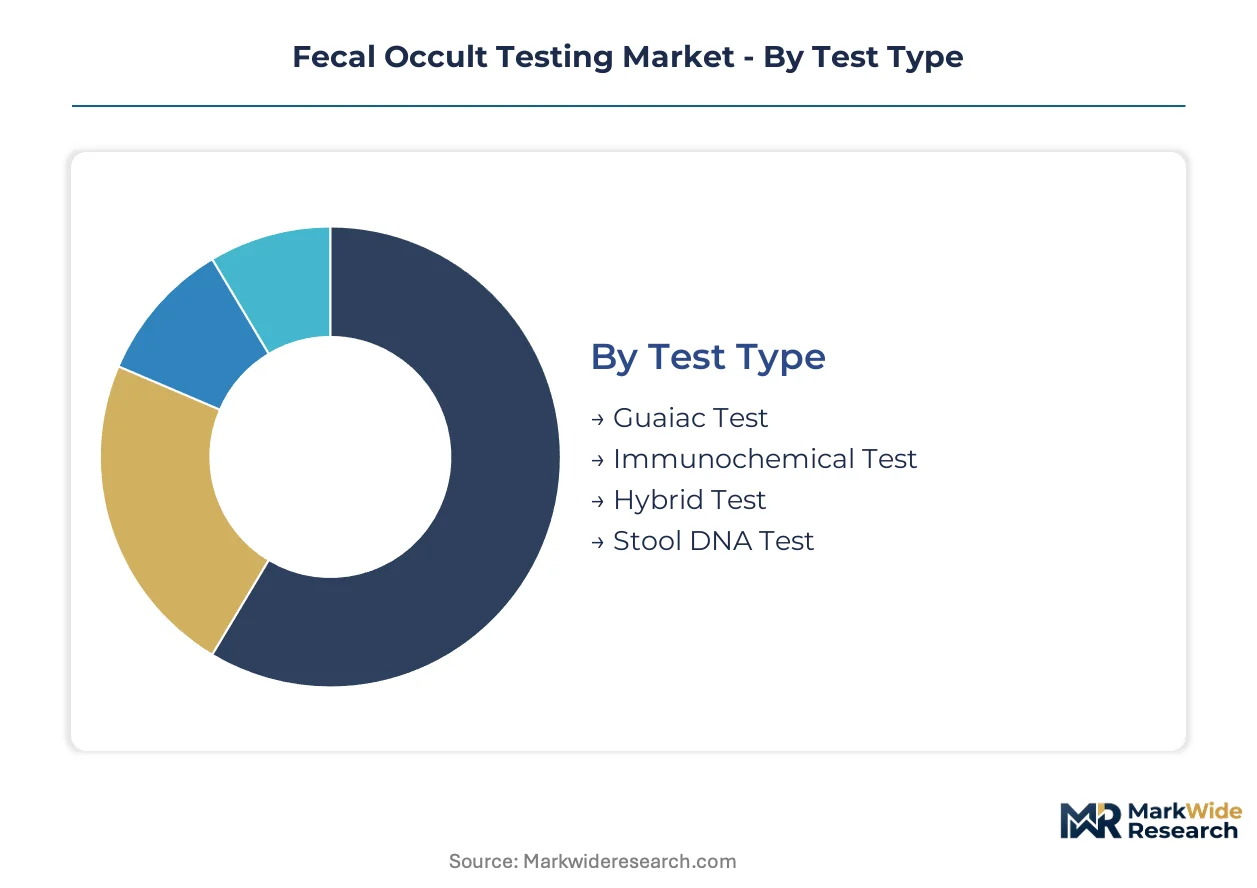
Fecal occult testing spans multiple technical formats and access points that determine reimbursement pathways and patient compliance rates. Channel configuration and technology selection directly influence laboratory throughput economics and screening program reach.
Test Type:
Channel mix varies sharply by test format, with immunochemical and stool DNA protocols flowing through CLIA-certified laboratories while guaiac formats retain pharmacy and direct-to-consumer presence.
- Guaiac Test:Resin-impregnated paper chemistry detects peroxidase activity from hemoglobin and dietary sources. Demand concentrates in resource-constrained settings and legacy screening programs where cost minimization overrides specificity requirements.
- Immunochemical Test:Antibody-based detection of intact human hemoglobin achieves 50 ng/mL sensitivity thresholds without dietary restrictions. United States Medicare reimbursement for annual FIT screening drives volume through hospital outpatient laboratories and commercial reference chains.
- Hybrid Test:Combined chemical and immunochemical detection layers aim to balance cost and accuracy. Emerging markets with mixed infrastructure utilize hybrid formats for municipal health screening expansion.
- Stool DNA Test:Multitarget molecular panels detect KRAS mutations, BMP3 methylation, and hemoglobin simultaneously. Tertiary medical centers with high-complexity CLIA certification dominate access as CMS covers triennial screening for average-risk beneficiaries.
By volume, immunochemical testing leads. By growth pace, stool DNA testing is climbing the fastest.
End User:
Cost tier stratification separates institutional purchasers with automated infrastructure from decentralized collection models emphasizing patient convenience.
- Hospitals:Integrated health systems deploy high-throughput analyzers processing 300-plus specimens hourly. Centralized laboratory economies of scale support risk-stratified colonoscopy referral protocols.
- Diagnostic Laboratories:Commercial reference chains compete on turnaround time and digital result integration with electronic health records. Quest Diagnostics and LabCorp infrastructure shapes regional market access patterns.
- Home Care:Direct-to-patient sample collection bypasses traditional primary care gatekeepers. Employer wellness platforms and pharmacy retail channels concentrate volume with logistics-integrated laboratories.
- Clinics:Point-of-care settings utilize rapid immunochemical devices for same-visit result delivery. Federally qualified health centers leverage simplified workflows for underserved population outreach.
By installed base, hospitals retain dominance. By expansion trajectory, home care distribution is gaining share fastest.
Distribution Channel:
Volume concentration tracks procurement sophistication, with direct sales commanding institutional accounts and digital channels fragmenting consumer access.
- Direct Sales:Manufacturer field organizations negotiate multi-year service contracts with health system laboratory directors. Analyzer placement agreements lock in reagent exclusivity and maintenance revenue streams.
- Online Stores:E-commerce platforms enable patient-initiated screening without physician intermediation. Amazon and specialized health retailers fulfill FIT kits with prepaid return logistics.
- Pharmacies:CVS Health and Walgreens retail locations stock over-the-counter guaiac and immunochemical products. Pharmacist counseling drives compliance with sample collection protocols.
- Medical Supply Distributors:Cardinal Health and McKesson networks reach independent physician offices and small laboratories. Inventory management services reduce stockout risk for high-volume screening periods.
By revenue contribution, direct sales leads. By channel momentum, online stores are expanding most quickly.
Technology:
Maturity gradients separate established enzyme and lateral flow platforms from molecular techniques requiring specialized personnel and capital investment.
- Enzyme Immunoassay:Conjugate-based signal amplification enables quantitative hemoglobin reporting on automated clinical chemistry analyzers. Beckman Coulter and Roche platforms standardize result comparability across networks.
- Lateral Flow Test:Immunochromatographic strips deliver qualitative results without instrumentation. Point-of-care deployment suits resource-limited settings and rapid screening campaigns.
- ELISA:Microplate-based enzyme-linked formats support batch processing in research and low-throughput clinical environments. Academic medical centers retain ELISA capacity for assay development and validation.
- Molecular Techniques:PCR and next-generation sequencing platforms detect epigenetic and genetic biomarkers with single-digit copy sensitivity. Exact Sciences Cologuard exemplifies FDA-cleared stool DNA commercialization.
By test volume, enzyme immunoassay dominates. By capability investment, molecular techniques show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and diagnostic laboratory chains concentrate purchasing power in markets with mature reimbursement infrastructure. Medicare coverage decisions and national cancer screening programs determine volume allocation across territories.
United States
CMS national coverage determination for annual FIT screening and triennial stool DNA testing drives demand through hospital outpatient laboratories. The FDA regulates devices under 21 CFR 864 while CLIA certification requirements constrain high-complexity molecular testing to tertiary centers. Laboratory concentration clusters around Boston, Research Triangle Park, and San Diego biotech corridors.
Japan
METI-backed cancer screening mandates targeting 50% municipal participation rates institutionalize fecal occult testing in health checkup programs. PMDA oversight aligns with international harmonization initiatives for in vitro diagnostics. Manufacturing and clinical validation activity concentrates in the Kansai region around Osaka and Kyoto.
Germany
Statutory health insurance reimbursement for immunochemical screening protocols sustains diagnostic laboratory volume. EMA IVDR implementation timelines and notified body certification requirements reshape competitive entry conditions. Industrial activity clusters in Baden-Württemberg and North Rhine-Westphalia around established IVD manufacturing infrastructure.
India
Diagnostic chains expanding into tier-2 cities generate unserved demand for affordable FIT protocols. CDSCO medical device rules and state-level laboratory licensing govern market access. Commercial laboratory networks concentrate in Maharashtra, Karnataka, and Delhi-NCR with emerging presence in Gujarat and Tamil Nadu.
United Kingdom
NHS bowel cancer screening programme procurement drives volume through centralized laboratory contracts. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards. Diagnostic service consolidation centers on London, Manchester, and Birmingham laboratory hubs.
Fecal Occult Testing Market Key Industry Players
Player mix skews toward diversified diagnostic conglomerates with automation infrastructure and specialized reagent manufacturers with regional clinical penetration. Market structure exhibits tiered consolidation with three to five dominant participants controlling high-throughput analyzer placements and long-term service contracts. Strategic archetypes separate platform-integrated multinationals from reagent-specialized regional suppliers and molecular diagnostics pure-plays. Competitive moves concentrate on analyzer placement agreements with exclusivity lock-ins and CLIA laboratory certification partnerships for stool DNA assay validation.
Among diversified diagnostic conglomerates, Abbott Laboratories and Danaher Corporation exemplify platform-integrated archetypes with automation infrastructure spanning clinical chemistry and immunochemistry workflows. Eiken Chemical Co. Ltd. occupies a position within the specialized reagent manufacturer tier, anchoring regional supply relationships in Asian clinical markets. Exact Sciences Corporation represents the molecular diagnostics pure-play archetype, sitting within the stool DNA testing segment where CLIA high-complexity certification requirements limit laboratory participation.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Quidel Corporation |
| Eiken Chemical Co. Ltd. |
| Danaher Corporation |
| Quest Diagnostics Incorporated |
| Siemens Healthcare GmbH |
| Biohit Oyj |
| Epigenomics AG |
| Exact Sciences Corporation |
| Others |
Cost & Logistics Intelligence
Analyzer placement agreements with multi-year reagent exclusivity lock in both supply access and price visibility for institutional laboratory customers across United States health systems. These contracts bundle capital equipment, consumables, and maintenance into predictable per-test economics that shield high-throughput facilities from spot market volatility in immunochemical reagent supply.
Pricing Analysis
Cost-plus contracts with raw material indexation to resin and antibody feedstock costs dominate procurement between diagnostic conglomerates and hospital laboratory networks. Three-tier pricing structure across premium, standard, and economy levels separates automated FIT platforms with quantitative reporting from manual guaiac formats and point-of-care lateral flow devices. Pricing pressure stems from Medicare reimbursement compression for screening tests, which squeezes margins on high-volume institutional contracts. Federally qualified health centers and municipal screening programs exhibit the highest price sensitivity, while tertiary medical centers with integrated health system bargaining power negotiate least sensitive terms.
Supply Chain Analysis
Monoclonal antibody production concentration in the United States, Germany, and Japan constrains global immunochemical reagent availability for fecal occult testing manufacturers. Supply chains draw from resin-impregnated paper substrates, purified hemoglobin antibodies, and specialized collection device polymers as critical inputs. Single-source vulnerability in CLIA-certified laboratory capacity for stool DNA assay validation creates bottleneck risk for molecular test expansion. Distribution runs through direct sales organizations for institutional accounts, with medical supply distributors reaching independent physician offices and pharmacy retail networks capturing direct-to-consumer volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fecal occult testing market operates as a defensive-moat story where CLIA high-complexity certification requirements create regulatory entrenchment that protects incumbent laboratory relationships from rapid competitive displacement.
For Market Incumbents: Secure exclusive multi-year analyzer placement agreements with integrated health systems to lock in reagent pull-through revenue and block competitor access to high-throughput laboratory networks. Deepen backward integration into monoclonal antibody production to reduce feedstock cost exposure and insulate margins from supplier concentration risk. The priority defensive lever rests on channel control through service contract renewals timed to coincide with EMA IVDR compliance deadlines. For New Entrants and Emerging Players: Anchor in India's tier-2 city laboratory networks where diagnostic chain expansion into Surat, Indore, and Coimbatore generates unserved demand for affordable FIT protocols. The most penetrable white-space target sits with telehealth-integrated home collection models that bypass traditional primary care gatekeeper relationships through direct-to-patient sample logistics. A specific go-to-market angle pairs employer wellness platform partnerships with digital result delivery to capture screening compliance volume outside institutional procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward molecular diagnostics pure-plays with validated stool DNA assays and existing CLIA high-complexity laboratory certification, as these assets command scarcity premiums in tight regional labor markets. Long-term viability across the analysis window hinges on reimbursement expansion for multitarget molecular panels beyond triennial screening intervals. The signal to watch as inflection indicator centers on FDA 510(k) clearance timelines for novel biomarker combinations lacking established predicate devices.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Certification Partnership | Validates stool DNA assay performance for CMS reimbursement eligibility in tertiary medical centers. |
| Automated Analyzer Platform Integration | Beckman Coulter and Roche chemistry analyzers standardize quantitative FIT result comparability across networks. |
| Direct-to-Consumer Distribution Launch | Amazon and pharmacy retail channels bypass physician intermediation for patient-initiated screening compliance. |
| EMA IVDR Notified Body Certification | MDR technical documentation satisfies European hospital procurement preconditions for contract renewal. |
| Reimbursement Strategy Expansion | USPTF grade recommendation shifts drive Medicare national coverage determination for screening intervals. |
Research Approach
Initial hypotheses were tested against primary input from hospital laboratory directors, CLIA-certified molecular diagnostics specialists, GPO contracts managers, and diagnostic supply chain procurement leads and refined through secondary validation against FDA 510(k) device filings, CMS Medicare coverage determination documents, EMA IVDR implementation guidance, and hospital procurement database records. Bottom-up test volume modeling by facility type and geography was triangulated against top-down market sizing from reagent manufacturer revenue disclosures and installed base estimates for automated analyzer platforms.
Variance decomposition across test type, end-user facility tier, distribution channel, and technology platform maturity drove segment-level growth attribution throughout the projection horizon. CAGRs were derived from logistic diffusion curves fitted to screening program participation targets and reimbursement expansion scenarios. Industry-specific forecast inputs incorporated METI-backed cancer screening mandate compliance trajectories in Japan and CDSCO medical device rule implementation timelines in India.
Decision-makers should treat outputs as directional under stable Medicare reimbursement and EMA IVDR enforcement assumptions; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as USPTF colorectal cancer screening grade recommendations and parallel EMA regulatory implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
US C-Reactive Protein Testing Market