
 Bariatric Medical Chairs Market | 2026-2036
Bariatric Medical Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Bariatric Medical Chairs Market Analytics
Modular configuration packages that pair adjustable weight-rated frames with interchangeable upholstery and mobility kits is rebalancing how procurement teams evaluate total cost of ownership. Stryker Corporation leverages its acute-care installed base to bundle seating with patient-handling workflows. GF Health Products, Inc. anchors its position through distribution depth across long-term care channels. Hill-Rom Holdings, Inc. differentiates via integrated scale and positioning technology embedded directly into chair architecture.
Bariatric medical chairs are reinforced seating systems engineered to safely support patients exceeding standard weight thresholds, typically constructed with welded steel or aluminum frames rated from 300 lbs to 600 lbs and incorporating pressure-relief cushioning, powered positioning actuators, and lockable casters for clinical transfer safety. Their primary purpose is to reduce caregiver injury risk while maintaining patient dignity during extended treatment, diagnostic, or recovery sessions. Mobile chairs with powered lift and recline functions capture the strongest demand trajectory as hospitals seek to minimize sling-lift dependency, while static chairs in steel construction remain the mature margin pool where volume procurement contracts dominate. Hygiene chairs with open-frame designs and antimicrobial fabric coatings are gaining traction in wound-care and bariatric surgery recovery protocols where infection control protocols intensify.
FDA 510(k) clearance processes govern device classification and predicate selection for powered positioning models, while ISO 13485 quality management standards shape supplier qualification for institutional contracts. The EU Medical Device Regulation imposes stricter clinical evidence requirements on higher-risk powered seating configurations, extending certification timelines for manufacturers without established notified-body relationships. Stakeholders must monitor how CMS durable medical equipment competitive bidding redesigns affect reimbursement thresholds for home-care bariatric seating categories.
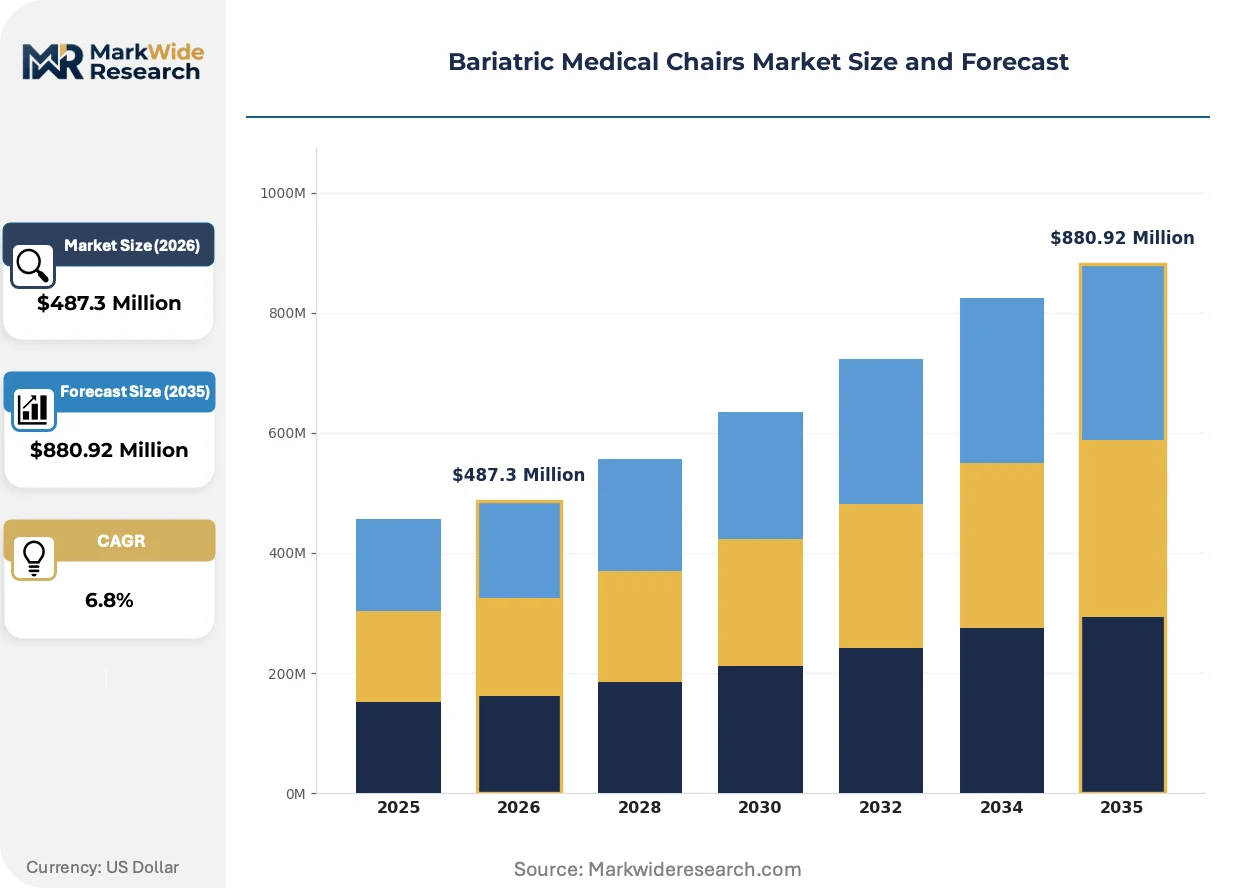
Market Dynamics
CMS competitive bidding redesigns for durable medical equipment are compressing reimbursement timelines and forcing manufacturers to accelerate value-engineering cycles on powered positioning systems.
Growth Catalysts
- Home care patient acuity:Rising obesity prevalence outside institutional settings drives procurement of higher-capacity seating with powered lift functions.
- FDA 510(k) pathway clarity:Predicate device frameworks for powered positioning models reduce regulatory uncertainty for institutional contract bids.
- Welded steel frame durability:Extended replacement cycles in acute-care environments support premium pricing for 600-lb rated configurations.
Market Restraints
- Aluminum alloy input volatility:Raw material price swings compress margin stability for lightweight frame manufacturers.
- EU MDR clinical evidence requirements:Stricter notified-body scrutiny extends certification timelines for powered seating configurations entering European markets.
- Manual transfer sling substitution:Lower-cost patient handling equipment retains share in budget-constrained long-term care facilities.
Strategic Opportunities
- Rural home care penetration:Underserved Medicare Advantage populations in non-metropolitan counties present white space for rental-based distribution models.
- Antimicrobial coating convergence:Open-frame hygiene chairs with embedded copper-ion fabric treatments address intensified infection control protocols in wound-care settings.
- ISO 13485 supplier qualification:Quality management certification gaps among regional distributors create consolidation openings for integrated device-service bundling.
Industry Challenges
- Biomedical technician specialization:Shortage of trained personnel for powered actuator maintenance extends equipment downtime in home care deployments.
- Legacy EHR integration:Embedded scale and positioning data streams require custom API development for seamless hospital information system connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bariatric Medical Chairs Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Chairs, Static Chairs, Reclining Chairs, Hygiene Chairs Material: Steel, Aluminum, Plastic, Fabric End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Weight Capacity: 300 lbs, 400 lbs, 500 lbs, 600 lbs |
| Companies Covered | Stryker Corporation, GF Health Products, Inc., Hill-Rom Holdings, Inc., K Care Healthcare Solutions, Kwalu, Invacare Corporation, Drive DeVilbiss Healthcare, Winco Mfg., LLC, Medline Industries, LP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bariatric Medical Chairs Market Evolving Landscape
Pressure-relief cushioning systems are converging with sensor-based patient monitoring, redefining how clinical seating captures real-time biometric data during extended treatment sessions.
Powered lift actuators with battery-backed emergency lowering are converging with wireless fleet management platforms. Acute-care facilities are adopting these configurations to reduce sling-lift dependency and track equipment utilization across decentralized patient rooms. This convergence is compressing the traditional separation between seating hardware and patient-handling workflow software.
EU Medical Device Regulation clinical evidence requirements are tightening predicate device eligibility for powered positioning chairs. Manufacturers without established notified-body relationships face extended certification timelines. Higher-risk seating configurations with integrated diagnostic sensors are most affected, with several firms pivoting toward modular architectures that separate powered base frames from detachable monitoring accessories.
Hospital procurement teams are unbundling after-sales service contracts from initial equipment purchases. Third-party biomedical service providers are capturing maintenance revenue previously retained by original equipment manufacturers. This behavioral shift is most visible in United States health systems with centralized capital equipment committees negotiating multi-year vendor-agnostic service agreements.
Bariatric Medical Chairs Market Segmentation
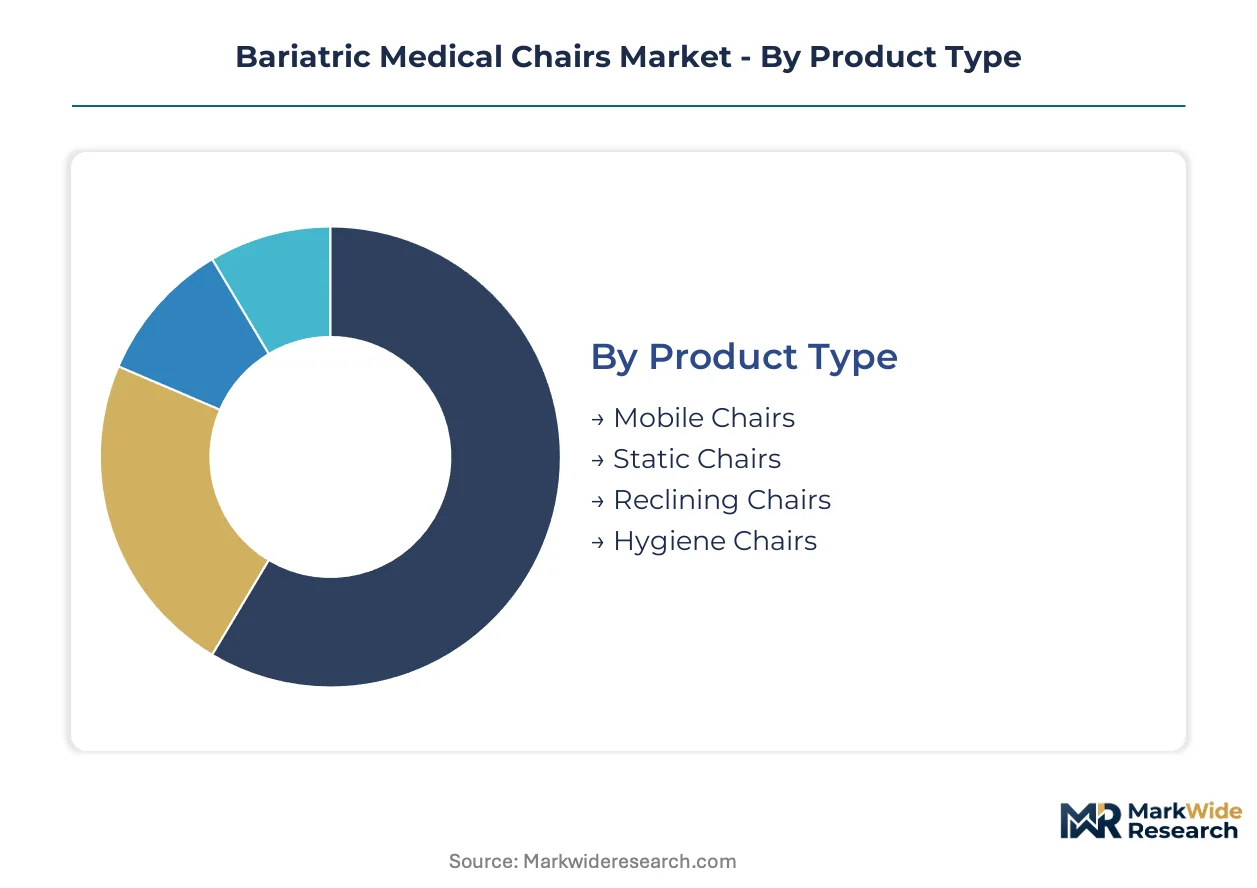
Segmentation in bariatric medical chairs reveals how procurement criteria diverge across care settings. Product architecture, material selection, and weight-rated specifications each command distinct evaluation frameworks depending on whether deployment occurs in acute facilities or decentralized home environments.
Product Type:
Standalone seating systems dominate acute-care procurement budgets, while embedded workflow integration shapes premium tier selection.
- Mobile Chairs:Powered lift and recline actuators with battery-backed emergency lowering reduce sling-lift dependency in hospital patient-handling protocols. Demand concentrates in United States acute-care networks seeking to minimize caregiver injury claims while tracking equipment utilization through wireless fleet management platforms.
- Static Chairs:Welded steel frames without powered components serve as the mature volume base where extended replacement cycles support institutional procurement contracts. Volume concentrates in budget-constrained long-term care facilities prioritizing durability over positioning flexibility.
- Reclining Chairs:Manual or powered backrest articulation supports extended treatment sessions in dialysis and infusion centers.
- Hygiene Chairs:Open-frame designs with antimicrobial fabric coatings address intensified infection control in wound-care and post-surgical recovery protocols.
Volume placements concentrate in Static Chairs; the faster expansion belongs to Mobile Chairs.
Material:
Cost tier positioning separates premium institutional contracts from economy home-care procurement.
- Steel:Welded carbon or stainless steel construction delivers 600-lb rated durability for acute-care replacement cycles exceeding ten years. United States hospitals anchor demand through Medicare reimbursement pathways supporting premium capital equipment acquisition.
- Aluminum:Lightweight alloy frames reduce transport burden for mobile configurations in home-care deployment. Raw material price volatility constrains margin stability for manufacturers serving rental-based distribution models.
- Plastic:Injection-molded components enable cost-engineered seating for temporary or disposable-use scenarios.
- Fabric:Upholstery materials span pressure-relief cushioning to copper-ion antimicrobial treatments.
Steel captures institutional volume leadership; aluminum climbs fastest in home-care penetration.
End User:
Application intensity determines whether seating requires powered positioning or static durability.
- Hospitals:Acute-care networks deploy integrated scale and positioning technology embedded directly into chair architecture for patient-handling workflow efficiency. FDA 510(k) clearance requirements shape product development timelines for powered models entering institutional contracts.
- Home Care:Rising patient acuity outside institutional settings drives procurement of higher-capacity seating with powered lift functions. Medicare reimbursement pathways and bariatric surgery volume in the United States support consistent replacement cycles.
- Clinics:Outpatient facilities balance cost constraints with treatment session duration requirements.
- Rehabilitation Centers:Extended therapy protocols demand pressure-relief cushioning and adjustable positioning for patient dignity maintenance.
Hospitals retain the volume anchor; home care gains share fastest as acuity shifts beyond institutional walls.
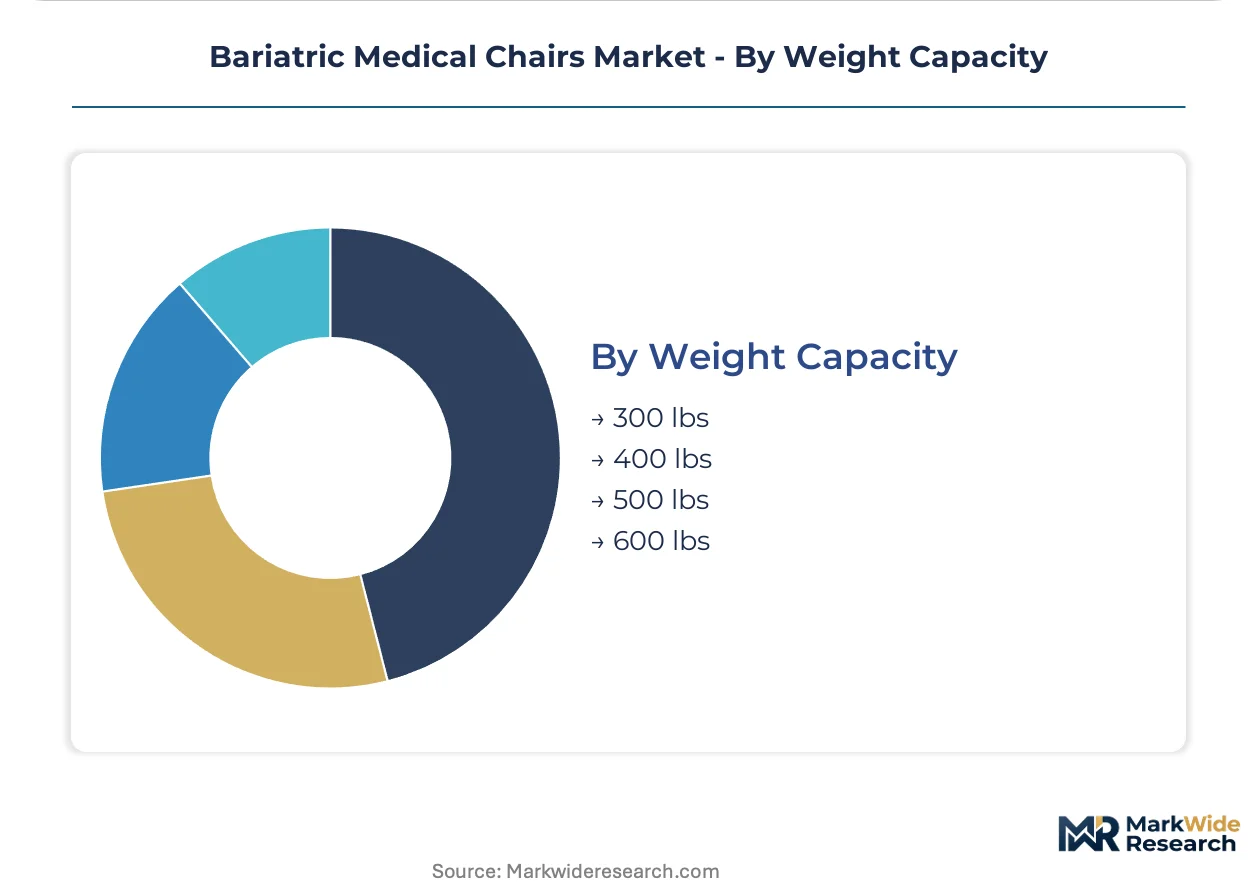
Weight Capacity:
Margin tier stratification follows load-rating certification thresholds.
- 600 lbs:Maximum-rated configurations with reinforced welded frames and expanded seat dimensions serve the highest-acuity bariatric surgery recovery protocols. Premium pricing persists in United States acute-care environments where extended replacement cycles justify capital investment.
- 500 lbs:Mid-tier ratings capture growing home-care demand as obesity prevalence expands beyond institutional settings.
- 400 lbs:Standard elevated capacity serves mainstream long-term care facility requirements.
- 300 lbs:Entry-level threshold accommodates lighter bariatric classifications and budget-constrained procurement.
500-600 lb configurations command premium placement volume; 300-400 lb ratings expand fastest in price-sensitive channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in North American and European industrial clusters, while demand spreads across aging populations in developed economies and emerging markets building bariatric care infrastructure. Production capacity leans toward welded steel fabrication in legacy manufacturing zones, with final assembly and distribution networks extending into high-need patient populations.
United States
Medicare reimbursement pathways and bariatric surgery volume sustain consistent replacement cycles for 600-lb rated acute-care seating. FDA 510(k) clearance requirements shape product development timelines for powered positioning models entering institutional contracts. Cleveland Clinic and Mayo Clinic procurement networks in Ohio and Minnesota anchor demand for integrated scale and positioning technology.
Germany
EU Medical Device Regulation imposes stricter clinical evidence requirements on higher-risk powered seating configurations, extending certification timelines for manufacturers without established notified-body relationships. BfArM oversight converges with DIN standards for medical device quality management. Industrial fabrication clusters in North Rhine-Westphalia supply welded steel frame components across European institutional contracts.
Japan
PMDA regulatory frameworks govern powered medical device classification, with JIS standards shaping supplier qualification for hospital procurement. METI industrial policy supports domestic manufacturing of precision actuator systems for patient-handling equipment. Osaka-based medical device clusters specialize in compact powered lift configurations for space-constrained acute-care facilities.
United Kingdom
NHS capital equipment frameworks prioritize total cost of ownership evaluations for bariatric seating procurement in aging care infrastructure. MHRA post-Brexit device regulations maintain alignment with EU MDR evidence standards while streamlining national approval pathways. Greater Manchester and West Midlands hospital trusts drive demand for mobile chairs with wireless fleet management integration.
Australia
TGA medical device regulations require conformity assessment for powered positioning chairs entering aged care and hospital procurement channels. National Disability Insurance Scheme funding expansion supports home-care bariatric seating acquisition outside institutional settings. Sydney and Melbourne medical device distribution hubs coordinate Pacific region supply for 500-600 lb capacity configurations.
Bariatric Medical Chairs Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. Acute-care networks favor integrated device-service bundling from established hospital equipment suppliers, while home-care rental markets fragment across regional distributors. Three archetypes dominate: diversified medical technology conglomerates with acute-care installed bases, specialized seating fabricators with long-term care channel depth, and contract manufacturers serving private-label procurement. Consolidation pressure intensifies through third-party biomedical service providers capturing maintenance revenue, and ISO 13485 certification gaps forcing distributor consolidation.
Among diversified medical technology conglomerates, Stryker Corporation and Hill-Rom Holdings, Inc. occupy positions anchoring premium-tier institutional contracts through integrated patient-handling workflow bundling. GF Health Products, Inc. exemplifies the specialized fabricator archetype with distribution depth across long-term care channels. These three companies represent the competitive spectrum from acute-care technology integration to channel-focused volume positioning.
| Leading Market Players |
|---|
| Stryker Corporation |
| GF Health Products, Inc. |
| Hill-Rom Holdings, Inc. |
| K Care Healthcare Solutions |
| Kwalu |
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| Winco Mfg., LLC |
| Medline Industries, LP |
| Others |
Value Network & Pricing Analysis
Powered actuator miniaturization and battery-backed emergency lowering systems are simultaneously compressing manufacturing cost curves and concentrating component sourcing among ISO 13485-certified precision electromechanical suppliers in Germany and Japan. This dual shift is reshaping how procurement teams evaluate total cost of ownership across acute-care and home-care deployment scenarios.
Pricing Analysis
Margin tightening in mid-tier 500-lb rated configurations reflects aluminum alloy input volatility and CMS competitive bidding compression on durable medical equipment reimbursement. Three-tier pricing structure across premium integrated-scale models, standard powered positioning chairs, and economy static steel frames dominates institutional procurement. Price differentiation hinges on FDA 510(k) clearance tier and after-sales service bundling. Home care rental channels exhibit highest price sensitivity; acute-care networks with centralized capital committees show lowest sensitivity due to extended replacement cycle accounting.
Supply Chain Analysis
ISO 13485 certification gating concentrates welded steel frame fabrication in United States industrial clusters and North Rhine-Westphalia manufacturing zones, with precision actuator assembly tethered to Osaka-based electromechanical specialists. Raw material dependencies span medical-grade aluminum alloys, antimicrobial copper-ion fabric treatments, and battery cell configurations. Single-source vulnerability persists in powered lift actuator supply. Distribution runs through GPO contracts for institutional procurement and regional biomedical equipment distributors for home care rental networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bariatric medical chairs market is consolidating around ISO 13485-certified manufacturers with established notified-body relationships, as EU MDR clinical evidence requirements and CMS reimbursement compression force regional distributors and uncertified fabricators toward exit or acquisition.
For Market Incumbents: Extend patient-handling workflow software integration to capture maintenance revenue streams being diverted toward third-party biomedical service providers. Deepen backward integration into precision actuator manufacturing to offset aluminum input volatility. Lock in multi-year GPO contracts before competitive bidding redesigns accelerate.
For New Entrants and Emerging Players: Home care rental distributors in rural Medicare Advantage counties represent the most penetrable channel gap. Target white space in 500-lb capacity mobile chairs with wireless fleet management for non-metropolitan health systems. Pursue ISO 13485 qualification gaps among regional distributors as acquisition entry points.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized seating fabricators possessing long-term care channel depth given consolidation pressure on uncertified regional distributors. Long-term viability favors integrated device-service bundling capabilities over pure hardware manufacturing. Watch FDA 510(k) clearance backlogs as inflection signal for regulatory capacity constraints affecting competitive timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Predicate device selection accelerates institutional contract eligibility for powered positioning configurations. |
| Hospital System Partnership | GPO contract anchoring secures volume placement in acute-care networks with centralized procurement committees. |
| Software Companion Development | Wireless fleet management integration captures utilization data for patient-handling workflow optimization. |
| CE Marking Pathway | EU MDR clinical evidence investment opens premium-tier European institutional procurement channels. |
| Reimbursement Strategy | Medicare durable medical equipment coding alignment enables home care rental model expansion. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineer surveys, and GPO contract database analysis underwrites the qualitative findings. Primary fieldwork engaged clinicians, procurement managers at Cleveland Clinic and Mayo Clinic networks, long-term care facility administrators, and third-party biomedical service technicians. Secondary validation drew from FDA 510(k) predicate device databases, CMS durable medical equipment competitive bidding records, hospital capital expenditure disclosures, and ISO 13485 certification registries. Bottom-up unit economics triangulated against top-down reimbursement pathway analysis.
Rate-of-change decomposition across the projection horizon separates volume growth from pricing dynamics and mix shift toward higher-capacity configurations. Segmentation modeling incorporated product architecture, material selection, weight-rated specifications, and end-user care setting intensity. CAGRs derived from replacement cycle analysis, bariatric surgery volume trajectories, and home care patient acuity shifts. Forecast inputs included Medicare reimbursement pathway redesigns and EU MDR certification timeline extensions.
Several conditions sit outside the modeled scope, including unannounced regulatory pathway changes, raw material supply disruptions, and novel patient-handling technology substitution. Forecasts reflect documented assumptions about reimbursement stability and certification timeline norms. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
North America Bariatric Surgery Devices Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
United Kingdom Bariatric Surgery Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
Canada Bariatric Surgery Market