
 Global Bacterial Cell Culture Market | 2026-2036
Global Bacterial Cell Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bacterial Cell Culture Market Foresight
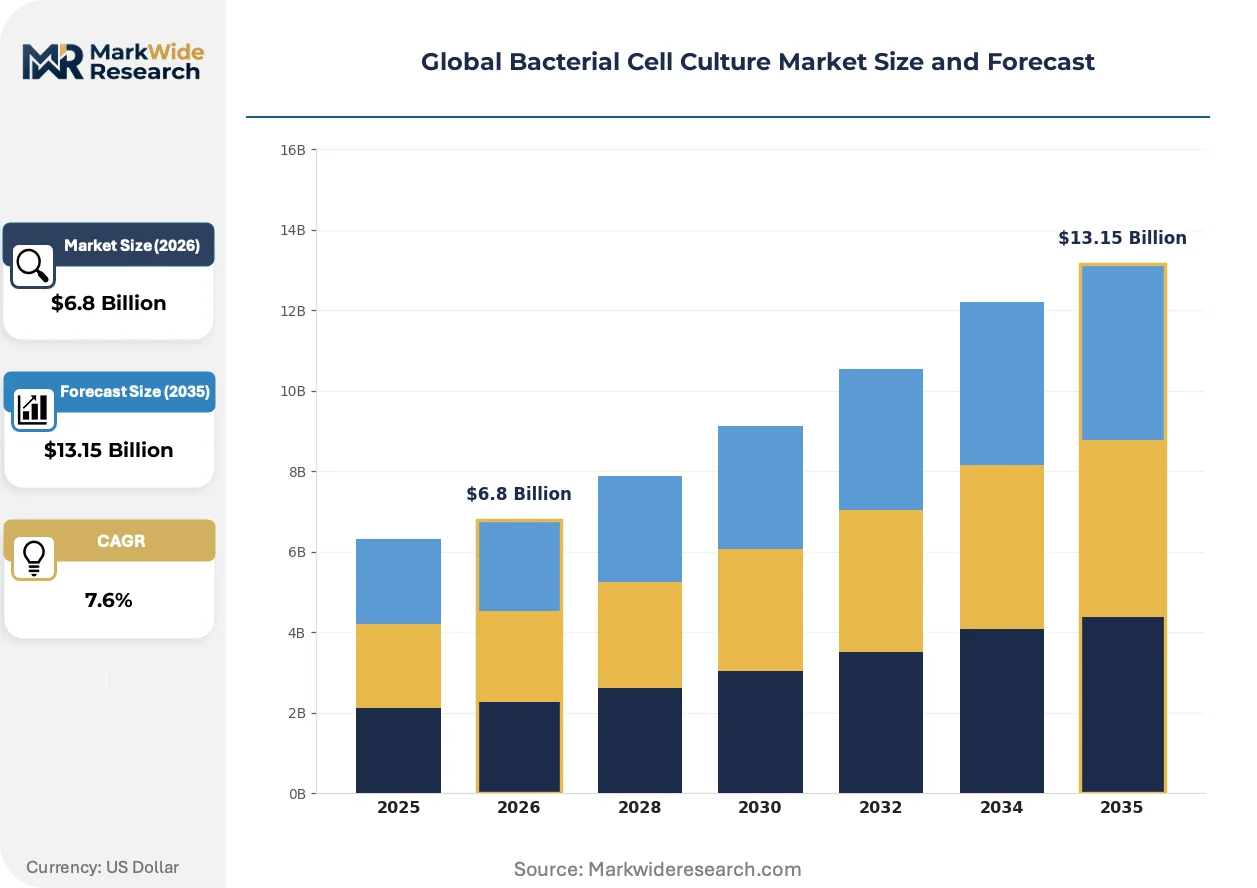
The EU Green Deal is expanding the market for chemically defined, animal-component-free media across European bioproduction facilities. Thermo Fisher Scientific leverages its Gibco brand portfolio to dominate serum-free bacterial media supply chains. Danaher Corporation sustains competitive pressure through Beckman Coulter's automated culture monitoring systems. Merck KGaA anchors its position with EMprove program-qualified raw materials for GMP-compliant fermentation.
Bacterial cell culture encompasses the controlled propagation of prokaryotic microorganisms in laboratory or industrial bioreactors using defined liquid media or solid substrates, typically maintained at 37°C with precise pH and dissolved oxygen control to achieve cell densities exceeding 10^9 CFU per milliliter for protein expression or metabolite harvesting. Growth media formulations command the largest product type revenue pool due to recurring consumable demand in high-throughput screening operations, while fed-batch culture methods generate premium pricing from pharmaceutical clients requiring optimized yield curves for monoclonal antibody precursor production. Contract manufacturing organizations represent the fastest-expanding end user segment as biopharma sponsors outsource microbial fermentation capacity to control capital deployment.
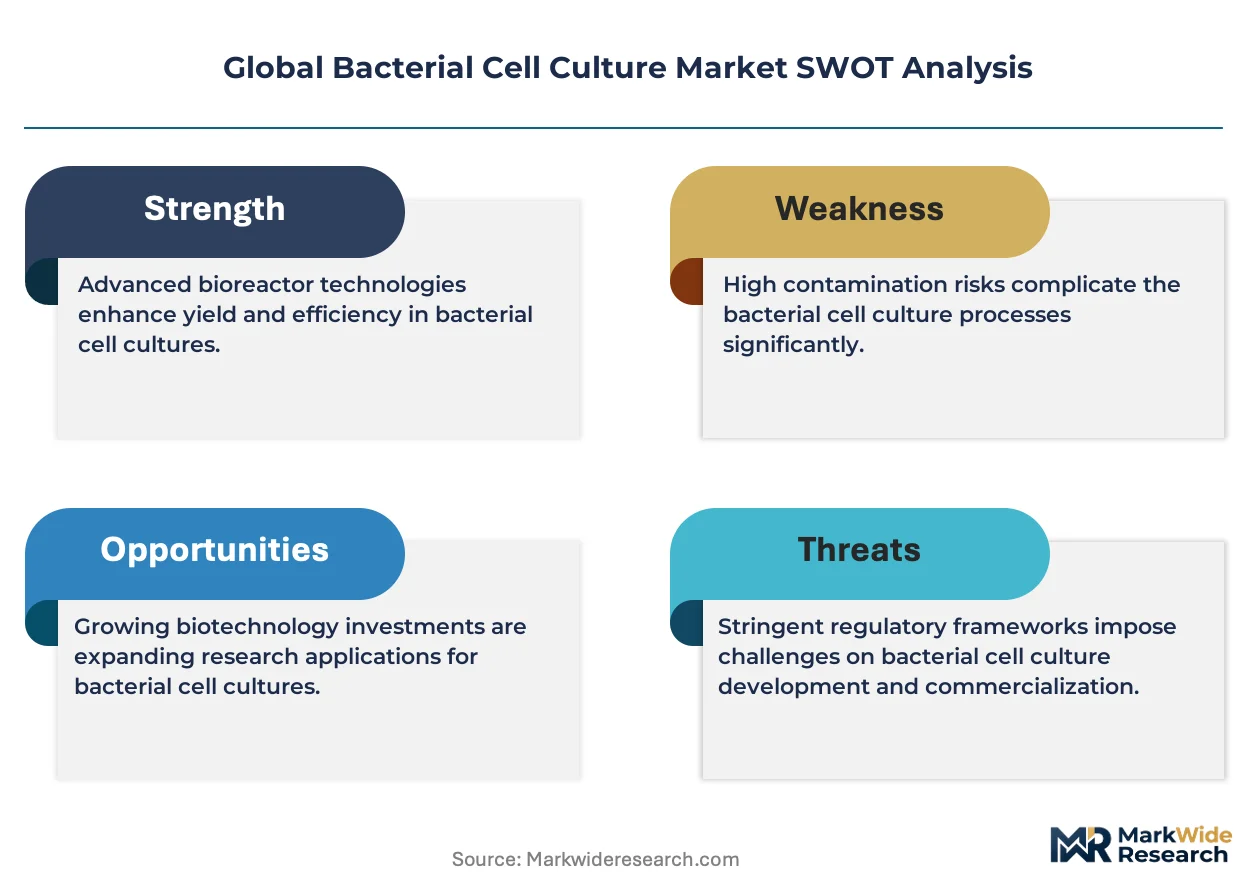
FDA's Points to Consider guidance and EMA's GMP Annex 1 revisions are tightening environmental monitoring requirements for aseptic processing, compelling facilities to validate culture-based detection methods with enhanced specificity. India's CDSCO and China's NMPA are converging toward ICH Q5D-derived standards for microbial host cell characterization, creating compliance complexity for multi-territory suppliers. Stakeholders must decide whether to consolidate media manufacturing regionally or absorb cross-border qualification costs as regulatory divergence persists.
Market Dynamics
The EU Green Deal is compressing formulation timelines for animal-component-free media as biopharmaceutical manufacturers race to validate chemically defined alternatives ahead of regulatory deadlines.
Growth Catalysts
- Recombinant protein demand:Biopharma sponsors are expanding microbial expression capacity for monoclonal antibody precursors, pulling fermentation infrastructure investment.
- EMA GMP Annex 1 revisions:Tightened environmental monitoring mandates are forcing facilities to upgrade culture-based detection specificity, creating consumable pull-through.
- German fermentation clusters:Specialized infrastructure around Heidelberg and Munich is concentrating contract manufacturing demand, driving regional media volume.
Market Restraints
- Peptone supply concentration:Soy and yeast-derived nitrogen sources face price volatility from agricultural commodity swings, squeezing margin on economy-grade formulations.
- Single-use bioreactor dependency:Polypropylene and film supply bottlenecks from concentrated Asian resin producers create equipment availability risk.
- Fed-batch technical ceiling:Oxygen transfer limitations in high-cell-density E. coli cultures cap yield improvements for legacy stainless-steel installations.
Strategic Opportunities
- India CDSCO convergence:Alignment toward ICH Q5D-derived standards creates qualification pathway for media suppliers seeking multi-territory positioning.
- Continuous processing adoption:Perfusion bacterial culture methods offer yield curve optimization for high-value recombinant protein contracts.
- Digital twin integration:Convergence of bioprocess modeling with real-time analytics is unifying predictive control over pH and dissolved oxygen parameters.
Industry Challenges
- Fermentation specialist scarcity:Industrial microbiology and bioprocess engineering talent pools are thinning as academic programs pivot toward cell therapy.
- Cross-border qualification costs:Divergent raw material dossier requirements between FDA and EMA are extending GMP validation timelines for multi-site suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bacterial Cell Culture Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Media, Nutrient Broths, Agar Plates, Selective Media Culture Method: Batch Culture, Fed-Batch Culture, Continuous Culture, Immobilized Cell Culture Application: Pharmaceuticals, Food Safety Testing, Environmental Monitoring, Biofuel Production, Agricultural Research End User: Biotechnology Firms, Research Laboratories, Contract Manufacturing Organizations, Academic Institutions |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, Merck KGaA, bioMerieux SA, Bio-Rad Laboratories, Inc., HiMedia Laboratories Pvt. Ltd., Neogen Corporation, ScienCell Research Laboratories, Inc., Eiken Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bacterial Cell Culture Market Shifts & Advancements
Automation and definition are converging to reshape how bacterial cultures are monitored, formulated, and validated across pharmaceutical and industrial biotechnology applications.
Single-use sensor arrays is unifying dissolved oxygen and pH measurement into continuous wireless telemetry, eliminating probe sterilization downtime. Contract manufacturing organizations are adopting these systems fastest in high-throughput screening operations. The technology is unifying process analytical technology compliance with reduced manual sampling labor.
REACH restrictions on animal-derived raw materials are forcing reformulation of complex media toward chemically defined alternatives. European suppliers are accelerating soy peptone and recombinant albumin substitution programs. German GMP fermentation facilities are absorbing the highest qualification burden as they serve EMA-regulated biologics production.
Consolidated procurement of raw materials is compressing supplier bases as large biopharma sponsors seek single-source media qualification. Distributor networks are losing share to direct manufacturer relationships for high-volume contracts. This pattern is most visible in North American and European CMO clusters where sponsor audit requirements favor integrated supply chains.
Global Bacterial Cell Culture Market Segmentation
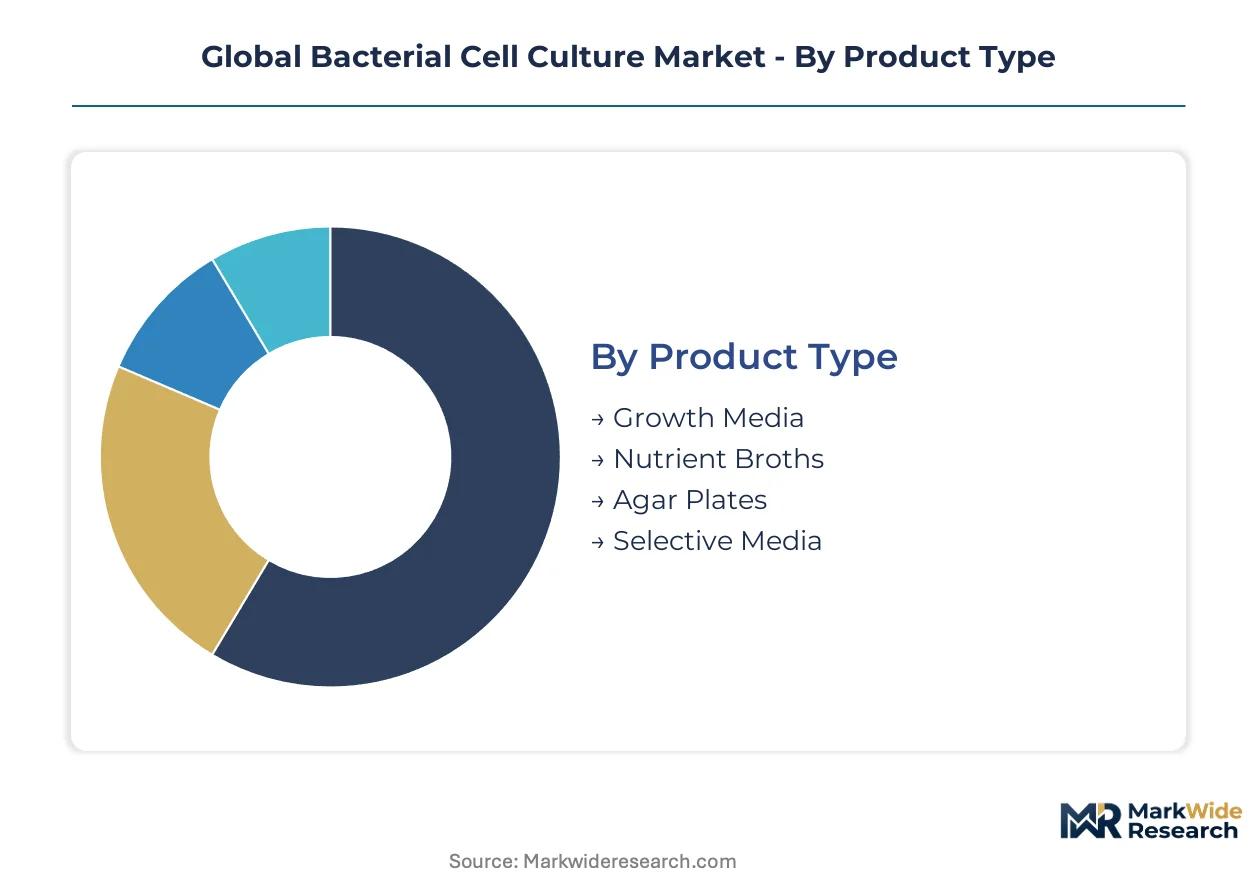
Bacterial cell culture segmentation reveals how upgrade cycles and qualification requirements concentrate purchasing power across consumables, equipment, and services. Suppliers must align portfolio depth with the specific compliance and throughput demands of each buyer category.
Product Type:
Replacement cycles for liquid media formulations accelerate as facilities validate chemically defined alternatives to animal-derived peptones under EU Green Deal timelines.
- Growth Media:Liquid formulations combining carbon sources, nitrogen, and trace minerals support high-density E. coli propagation in bioreactors. German fermentation clusters around Heidelberg and Munich absorb the largest procurement volumes as contract manufacturing organizations scale recombinant protein capacity.
- Nutrient Broths:Standardized liquid preparations enable rapid bacterial resuscitation and preliminary expansion before bioreactor inoculation. Research laboratories in the United States and Germany drive steady demand for pre-mixed, quality-certified broths that reduce preparation variability.
- Agar Plates:Solid-phase culture substrates deliver isolated colony formation for purity testing and strain characterization.
- Selective Media:Formulations incorporating antibiotics or indicator compounds enable targeted isolation of recombinant clones or pathogenic species.
Volume placements concentrate in Growth Media; the faster expansion belongs to Selective Media as environmental monitoring and clone screening intensify.
Culture Method:
Capital deployment patterns favor methods that extend oxygen transfer limits and compress batch turnaround times in high-value protein production.
- Fed-Batch Culture:Controlled nutrient addition sustains exponential growth phases and pushes E. coli densities past oxygen transfer ceilings in legacy stainless-steel installations. Pharmaceutical sponsors in Germany and Switzerland pay premium pricing for optimized yield curves in monoclonal antibody precursor manufacturing.
- Continuous Culture:Perfusion systems maintain steady-state operation with real-time cell harvest, maximizing volumetric productivity for high-value recombinant proteins. Biotechnology firms in Denmark and the Netherlands are piloting these systems fastest as they seek to displace batch inefficiencies.
- Batch Culture:Closed-system operation with fixed nutrient loading remains the default for screening and low-complexity production.
- Immobilized Cell Culture:Entrapment or surface attachment methods enable repeated use of biocatalysts in metabolite conversion processes.
Capital commitments flow heaviest into Fed-Batch Culture; Continuous Culture is climbing the fastest as perfusion engineering matures.
Application:
Regulatory enforcement intensity and production economics determine which applications absorb the most sophisticated culture infrastructure.
- Pharmaceuticals:Recombinant protein expression and vaccine antigen production demand GMP-qualified media, validated aseptic processing, and comprehensive host cell characterization. Facilities in Germany, Switzerland, and the United States anchor procurement as EMA and FDA tighten environmental monitoring mandates.
- Food Safety Testing:Pathogen detection and enumeration protocols require standardized culture media with documented batch consistency. Regulatory laboratories across France, Italy, and Spain are expanding capacity under EU-wide food safety surveillance programs.
- Environmental Monitoring:Culture-based detection of indicator organisms supports wastewater and pharmaceutical facility compliance.
- Biofuel Production:Engineered bacterial strains convert lignocellulosic feedstocks to advanced biofuels in pilot and demonstration scale.
- Agricultural Research:Plant-microbe interaction studies and biocontrol agent development utilize specialized culture conditions.
Equipment and media spending concentrates in Pharmaceuticals; Food Safety Testing is gaining share fastest as surveillance networks expand.
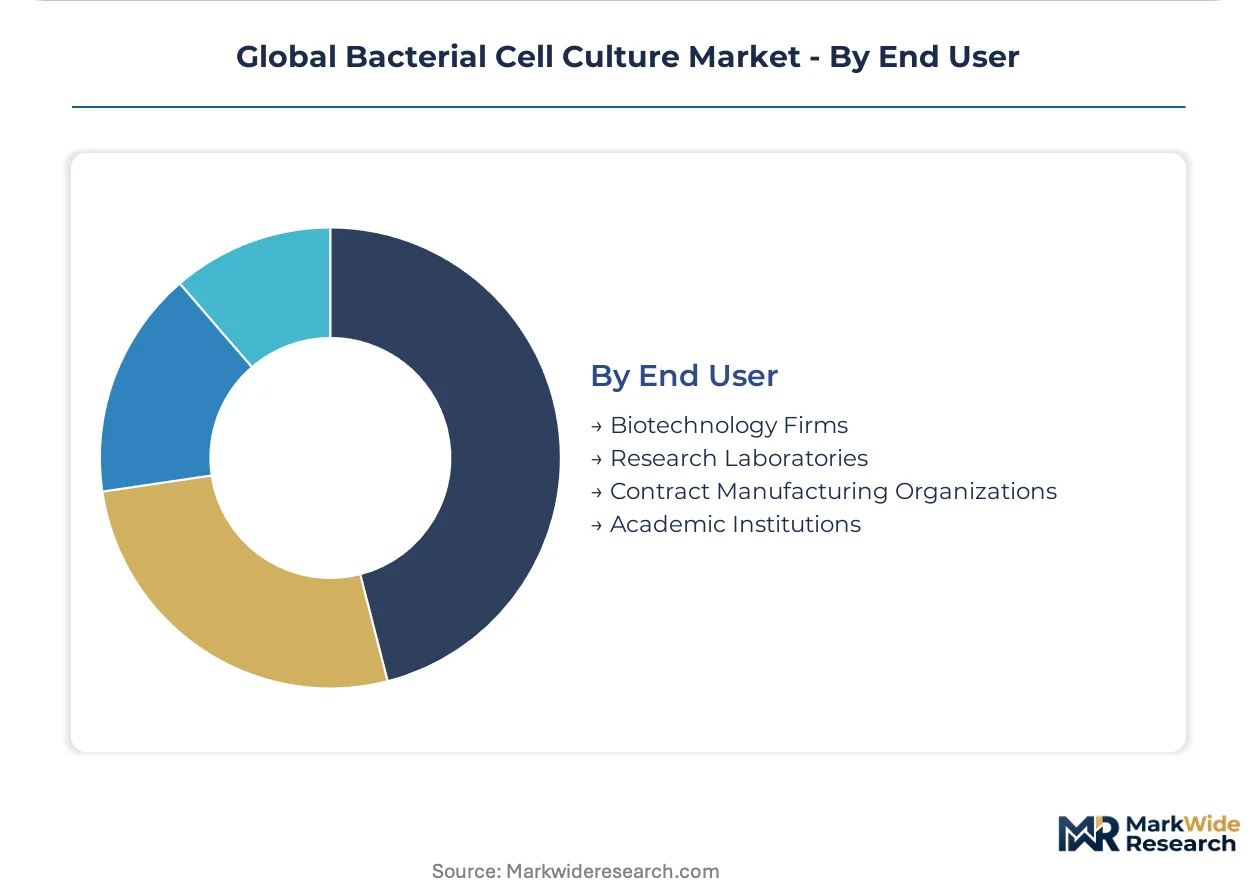
End User:
Procurement sophistication and audit requirements separate high-volume qualified buyers from price-sensitive research consumers.
- Contract Manufacturing Organizations:Dedicated fermentation capacity serves biopharma sponsors seeking to avoid capital deployment and regulatory qualification burdens. German CMO clusters around Munich and Heidelberg command the largest media volumes as they scale microbial expression for recombinant protein contracts.
- Biotechnology Firms:Integrated discovery-to-early-development operations require flexible culture formats spanning screening to pilot scale. Firms in the United States and Denmark are consolidating supplier relationships to reduce qualification overhead.
- Research Laboratories:Screening and strain engineering operations prioritize throughput and format flexibility over GMP documentation.
- Academic Institutions:Budget-constrained basic research drives demand for economy-grade formulations and open-source protocols.
Qualified media volumes concentrate in Contract Manufacturing Organizations; Biotechnology Firms are expanding their culture infrastructure most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg and Munich anchor the densest concentration of contract manufacturing fermentation capacity serving EMA-regulated biologics production across Europe.
United States
FDA's Points to Consider guidance is tightening environmental monitoring requirements for aseptic processing facilities in Massachusetts and North Carolina biotech corridors. CDER enforcement actions are accelerating validation of culture-based detection methods with enhanced specificity. Greater Boston hosts the largest cluster of microbial expression contract research organizations scaling recombinant protein infrastructure.
Germany
EU Green Deal deadlines are compressing formulation timelines for animal-component-free media across Baden-Württemberg pharmaceutical manufacturing sites. EMA GMP Annex 1 revisions mandate upgraded culture-based detection specificity in Heidelberg fermentation clusters. Munich-area contract manufacturing organizations are absorbing the highest media procurement volumes as they scale microbial expression capacity.
Switzerland
Swissmedic's convergence with ICH Q5D-derived standards is streamlining multi-territory qualification pathways for Basel-area biologics manufacturers. Cantonal pharmaceutical regulators are enforcing stringent raw material dossier requirements for GMP-compliant fermentation. The Basel-Liestal corridor concentrates specialized media validation expertise serving global biopharma sponsors.
India
CDSCO alignment toward ICH Q5D-derived standards is creating qualification pathways for media suppliers targeting multi-territory positioning from Hyderabad and Bengaluru biotech parks. The national pharmaceutical regulator is tightening microbial host cell characterization requirements for export-oriented manufacturers. Maharashtra's Thane-Belapur industrial belt is emerging as a fermentation infrastructure hub serving contract manufacturing demand.
China
NMPA's adoption of ICH Q5D-aligned standards is extending GMP validation timelines for media suppliers navigating cross-border qualification costs. The national medical products regulator is intensifying environmental monitoring mandates for biologics manufacturing in Shanghai and Suzhou. Yangtze River Delta fermentation facilities are consolidating procurement relationships with chemically defined media providers.
Global Bacterial Cell Culture Market Competitive Landscape
Premium-margin players sit above commodity-margin players across media formulation complexity and GMP qualification depth. The vendor base stratifies between diversified life science conglomerates with integrated raw material supply chains and specialized fermentation media manufacturers serving regional CMO clusters. Three archetypes dominate: full-stack platform providers bundling equipment and consumables, formulation specialists with EMprove-equivalent qualification programs, and regional distributors absorbing qualification overhead for emerging market access. Competitive moves concentrate on direct manufacturer relationships displacing distributor networks and backward integration into recombinant protein and chemically defined additive production.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions exemplifying platform breadth across bacterial culture workflows. Merck KGaA anchors the European qualification-intensive segment through its Darmstadt-based chemicals and life science operations. These three entities represent the dominant competitive anchors shaping procurement consolidation patterns among German and North American contract manufacturing organizations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Merck KGaA |
| bioMerieux SA |
| Bio-Rad Laboratories, Inc. |
| HiMedia Laboratories Pvt. Ltd. |
| Neogen Corporation |
| ScienCell Research Laboratories, Inc. |
| Eiken Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Contract manufacturing organization procurement concentration in German fermentation clusters anchors value-based pricing tied to batch yield outcomes and GMP compliance certification. EMA GMP Annex 1 revision deadlines compress supplier negotiation timelines as facilities prioritize qualified media over cost minimization.
Pricing Analysis
Yield-curve optimization contracts command premium positioning as pharmaceutical sponsors price media formulations against recombinant protein output per liter. Pricing stratifies across GMP-qualified, research-grade, and bulk economy tiers with differentiation resting on EMprove-equivalent documentation depth and animal-component-free certification. Cost compression in economy-grade soy peptone formulations is intensifying because agricultural commodity volatility squeezes margin on non-specialized nitrogen sources. Academic laboratories exhibit highest price sensitivity while EMA-regulated CMOs absorb premium qualification costs without volume elasticity.
Supply Chain Analysis
Direct-to-CMO channels handle high-volume qualified media demand while distributor networks serve fragmented research laboratory procurement across North American and European markets. Raw material sourcing draws from Chinese soy processing, Indian yeast extract production, and German recombinant additive manufacturing. Supply chain risk centers on single-source vulnerability for polypropylene film used in single-use bioreactor construction. Distribution runs through integrated manufacturer relationships displacing traditional distributor networks in high-volume sponsor audit environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous perfusion bacterial culture methods are displacing legacy fed-batch installations as biotechnology firms pursue yield curve optimization and reduced batch turnaround times.
For Market Incumbents: Anticipate consolidation pressure from sponsor demands for single-source media qualification by deepening backward integration into recombinant albumin and chemically defined additive production. Defend position against emerging formulation specialists through accelerated EMprove-equivalent program expansion serving EMA-regulated Heidelberg and Munich fermentation clusters. Channel control over direct CMO relationships represents the critical retention lever as distributor networks lose share. For New Entrants and Emerging Players: Chemically defined media formulation expertise offers entry positioning into the fastest-expanding animal-component-free segment driven by EU Green Deal compliance deadlines. White-space concentration appears in Indian CDSCO-aligned qualification pathways serving Hyderabad and Bengaluru export-oriented manufacturers. Go-to-market execution should prioritize direct technical sales engagement with mid-tier CMOs bypassing established distributor relationships. For Investors and Strategic Acquirers: The window for entry favors specialized fermentation media manufacturers with captive recombinant protein additive production and existing EMprove-equivalent qualification infrastructure. Long-term viability hinges on regulatory convergence toward ICH Q5D-derived standards across FDA, EMA, and emerging market jurisdictions. Watch for CDSCO and NMPA inspection capacity expansion as inflection signal for multi-territory qualification demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recombinant Additives | Captive supply of chemically defined components insulates margin from agricultural commodity swings. |
| EMprove-Equivalent Qualification Program Expansion | GMP-compliant raw material dossiers reduce sponsor audit burden and accelerate procurement decisions. |
| Direct CMO Relationship Consolidation | Integrated supply chains satisfy biopharma sponsor audit requirements displacing distributor intermediaries. |
| Continuous Perfusion Technology Adoption | Steady-state bacterial culture methods optimize volumetric productivity for high-value protein contracts. |
| Single-Use Sensor Array Integration | Wireless telemetry for dissolved oxygen and pH eliminates probe sterilization downtime in high-throughput screening. |
Research Methodology
Document review covered EMA GMP Annex 1 revision texts, FDA Points to Consider guidance, and ICH Q5D implementation timelines, complemented by interviews with bioprocess engineering directors, fermentation facility managers, regulatory affairs leads at media suppliers, and procurement officers at German CMO clusters. Secondary validation drew from CDSCO circulars, NMPA biologics manufacturing directives, and EU Green Deal regulatory impact assessments. Bottom-up media volume modeling triangulated against top-down biopharmaceutical fermentation capacity expansion data.
Segment-level value outputs across the projection horizon reflect product type, culture method, application, and end user dimensions with regional regulatory cluster differentiation. CAGRs were derived from facility investment pipelines, sponsor outsourcing trends, and media formulation replacement cycle analysis. Forecast inputs incorporated EU Green Deal compliance deadline acceleration, single-use bioreactor adoption curves, and continuous processing engineering maturity timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained polypropylene supply disruption or accelerated REACH restriction expansion beyond animal-derived raw materials. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Microbial API Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Microbial Cell Banking Market