
 Microbial Cell Banking Market | 2026-2036
Microbial Cell Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Cell Banking Market Analytics
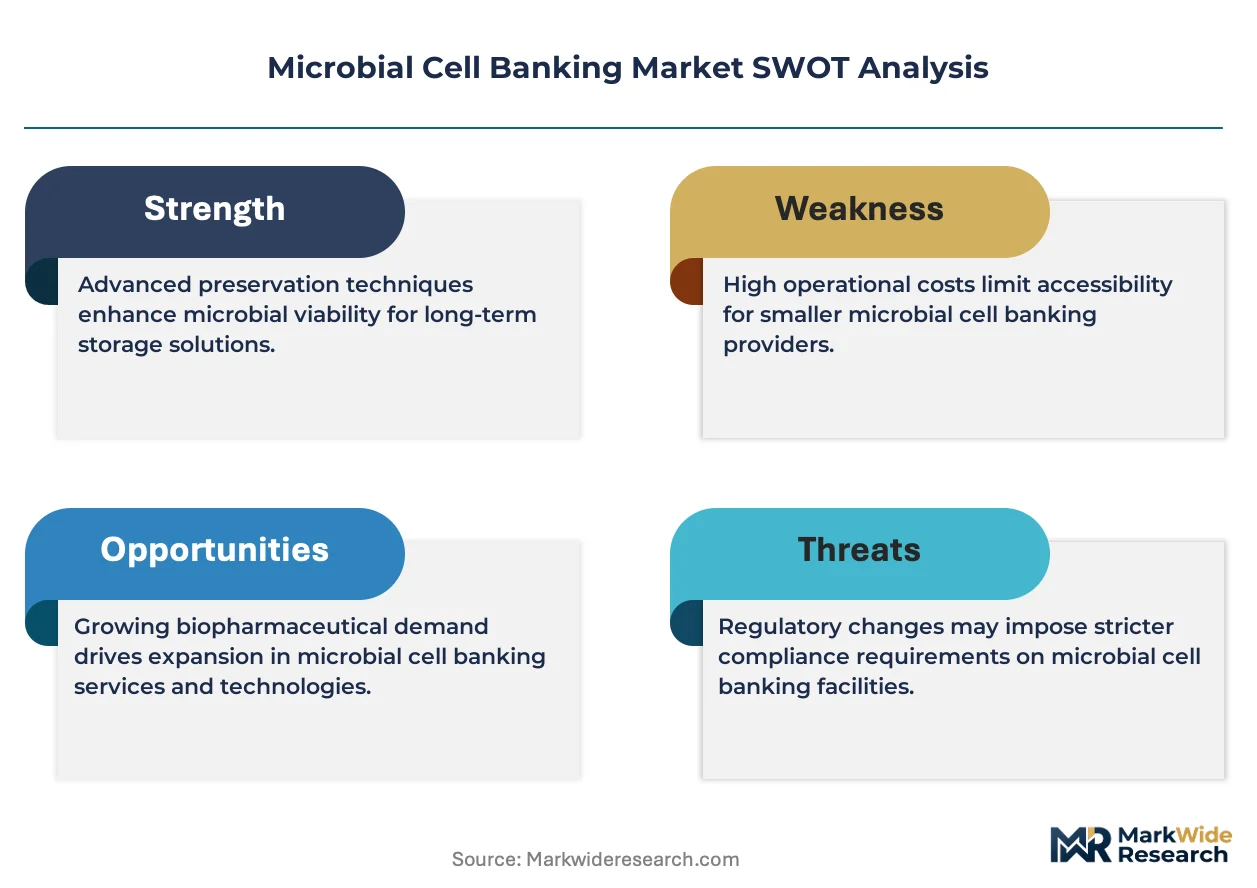
Buyer concentration in microbial cell banking is decoupling from traditional pharmaceutical giants toward mid-sized biotech firms and specialized CDMOs. Merck KGaA leverages its integrated life science tools portfolio to anchor European banking infrastructure. Lonza Group sustains manufacturing-scale dominance through captive bioproduction networks. Charles River Laboratories differentiates via specialized pathogen-free strain qualification protocols.
Microbial cell banking encompasses the systematic cryopreservation, characterization, and distribution of bacteria, yeast, fungi, and algae under documented quality conditions to ensure genetic stability and phenotypic consistency across production campaigns. Working cell banks typically derive from master cell banks through defined passage limits, with viability thresholds monitored via colony-forming unit assays and genomic fingerprinting. Bacterial strains occupy the largest product segment due to entrenched Escherichia coli and Bacillus subtilis expression platforms in insulin and enzyme manufacturing. Biopharmaceutical applications generate the fastest expansion as gene therapy vectors and mRNA production require rigorously documented microbial substrates. Yeast strains command premium positioning in biosimilar and vaccine adjuvant production where post-translational modification capabilities exceed bacterial systems.
FDA guidance on characterization and qualification of cell substrates shapes U.S. banking demand through mandatory genetic stability documentation and adventitious agent testing protocols. EMA's GMP Annex 1 revisions for sterile manufacturing and REACH chemical registration requirements for cryopreservatives constrain European operational flexibility. ISO 20387 biobanking standards and WHO TRS 978 cell substrate recommendations establish cross-border harmonization baselines for international material transfer. Stakeholders must monitor evolving regulatory divergence between FDA accelerated pathway expectations and EMA quality-by-design enforcement to align banking investment with jurisdiction-specific approval timelines.
Market Dynamics
Biopharmaceutical contract manufacturers now drive expanded adoption of microbial cell banking services as they scale recombinant protein production. The FDA's enhanced guidance on cell substrate characterization pushes facilities toward higher compliance investment.
Growth Catalysts
- Biologics manufacturing scale-up:CDMOs expanding Escherichia coli and Bacillus subtilis production lines for insulin and enzyme manufacturing require rigorously documented master and working cell banks to maintain genetic stability across campaigns.
- FDA substrate guidance:Mandatory genetic stability documentation and adventitious agent testing protocols under FDA cell substrate rules compel facilities to invest in qualified banking infrastructure.
- Gene therapy vector demand:mRNA production and viral vector manufacturing require microbial substrates with full characterization traceability, pulling specialized banking services into upstream supply chains.
Market Restraints
- Cryopreservative chemical costs:REACH registration requirements for dimethyl sulfoxide and glycerol-based cryoprotectants constrain European operational flexibility and elevate input expenses.
- Master cell bank lead times:Extended viability testing and genomic fingerprinting protocols create 12-18 month qualification timelines that delay production campaign starts.
- Specialized facility concentration:GMP-compliant banking capacity clusters in Boston and San Francisco biotech corridors, creating geographic supply bottlenecks for distributed manufacturers.
Strategic Opportunities
- Yeast strain premium positioning:Post-translational modification capabilities in Pichia pastoris and Saccharomyces cerevisiae command higher margins in biosimilar and vaccine adjuvant production where bacterial systems fall short.
- ISO 20387 harmonization:Cross-border biobanking standards enable international material transfer agreements that reduce redundant testing for multi-site manufacturers.
- Algae banking expansion:Photosynthetic microbial platforms for recombinant protein production remain underdeveloped relative to bacterial and yeast dominance, offering first-mover positioning.
Industry Challenges
- Genomic stability verification:Next-generation sequencing protocols for detecting low-frequency mutations require specialized bioinformatics capacity that strains mid-sized banking facilities.
- Pathogen-free certification:Charles River Laboratories and specialized qualifiers maintain proprietary strain qualification protocols that create certification bottlenecks for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Cell Banking Market |
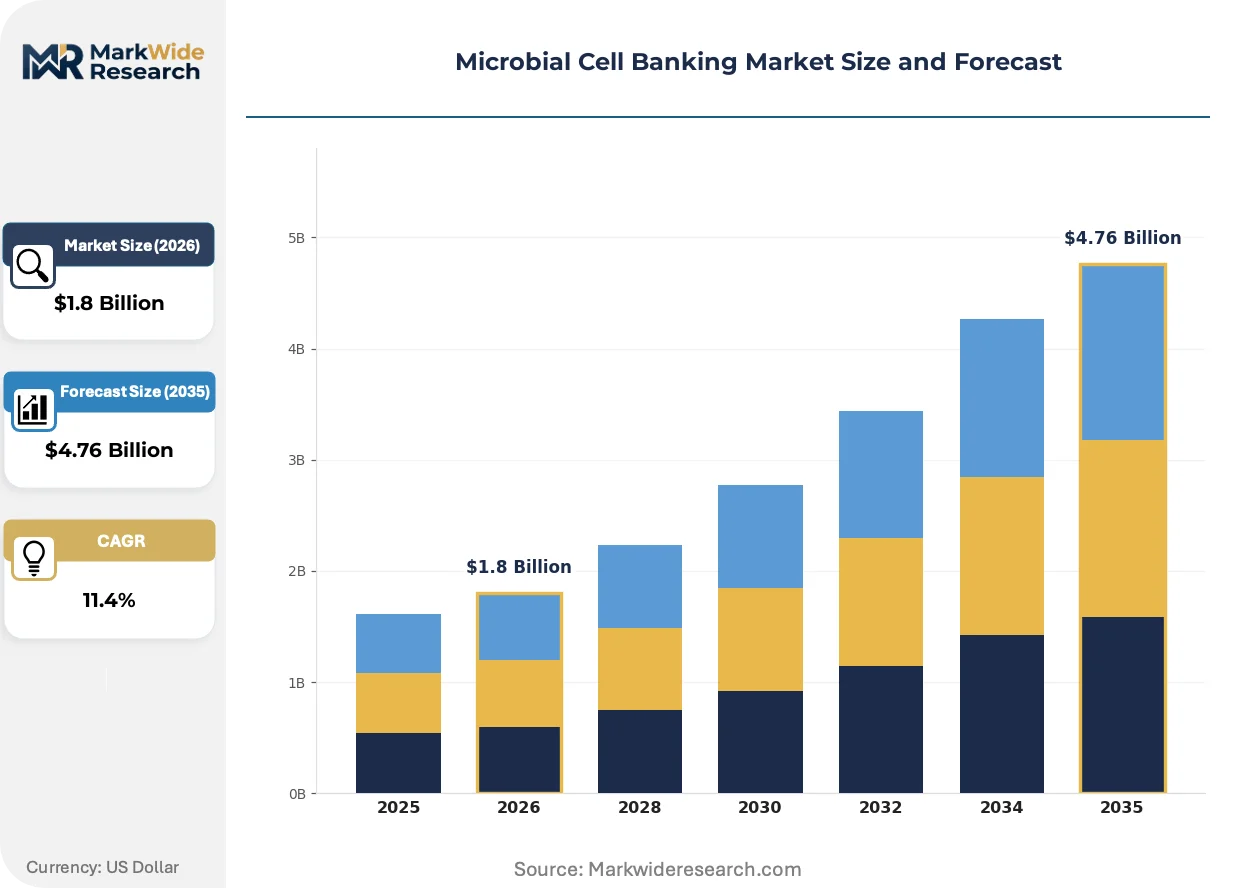
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Strains, Fungal Strains, Yeast Strains, Algal Strains Application: Biopharmaceuticals, Industrial Biotechnology, Food Production, Agricultural Biotechnology End User: Pharmaceutical Companies, Research Institutions, Biotech Firms, Food Manufacturers Storage Method: Liquid Nitrogen, Deep Freezing, Lyophilization, Cryopreservation |
| Companies Covered | Merck KGaA, Eurofins Scientific, Lonza Group, Cryo-Cell International, SGS Life Sciences, Charles River Laboratories, Thermo Fisher Scientific, BSL Bioservice, WuXi AppTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Cell Banking Market Evolving Landscape
Single-use bioprocessing technologies and automated cryopreservation systems are compressing cell bank production timelines while elevating contamination control standards. These shifts favor facilities with integrated quality systems over fragmented service providers.
Next-generation sequencing for master cell bank characterization is rewriting genetic stability verification protocols. CDMOs adopting whole-genome sequencing at bank establishment reduce downstream adventitious agent surveillance burdens. The technology is compressing qualification timelines from months to weeks for facilities with in-house sequencing capacity.
EMA's GMP Annex 1 revisions for sterile manufacturing impose stricter environmental monitoring on open-process banking operations. European facilities must demonstrate closed-system cryopreservation or justify exceptions through enhanced contamination risk assessments. Yeast strain banking operations with post-translational modification requirements face the steepest compliance elevation under these rules.
Buyer concentration is decoupling from traditional pharmaceutical giants toward mid-sized biotech firms and specialized CDMOs. These emerging buyers demand modular banking packages with unbundled characterization services rather than comprehensive master cell bank contracts. The shift is most visible in United States biotech clusters where venture-backed firms prioritize capital-efficient outsourcing models.
Microbial Cell Banking Market Segmentation
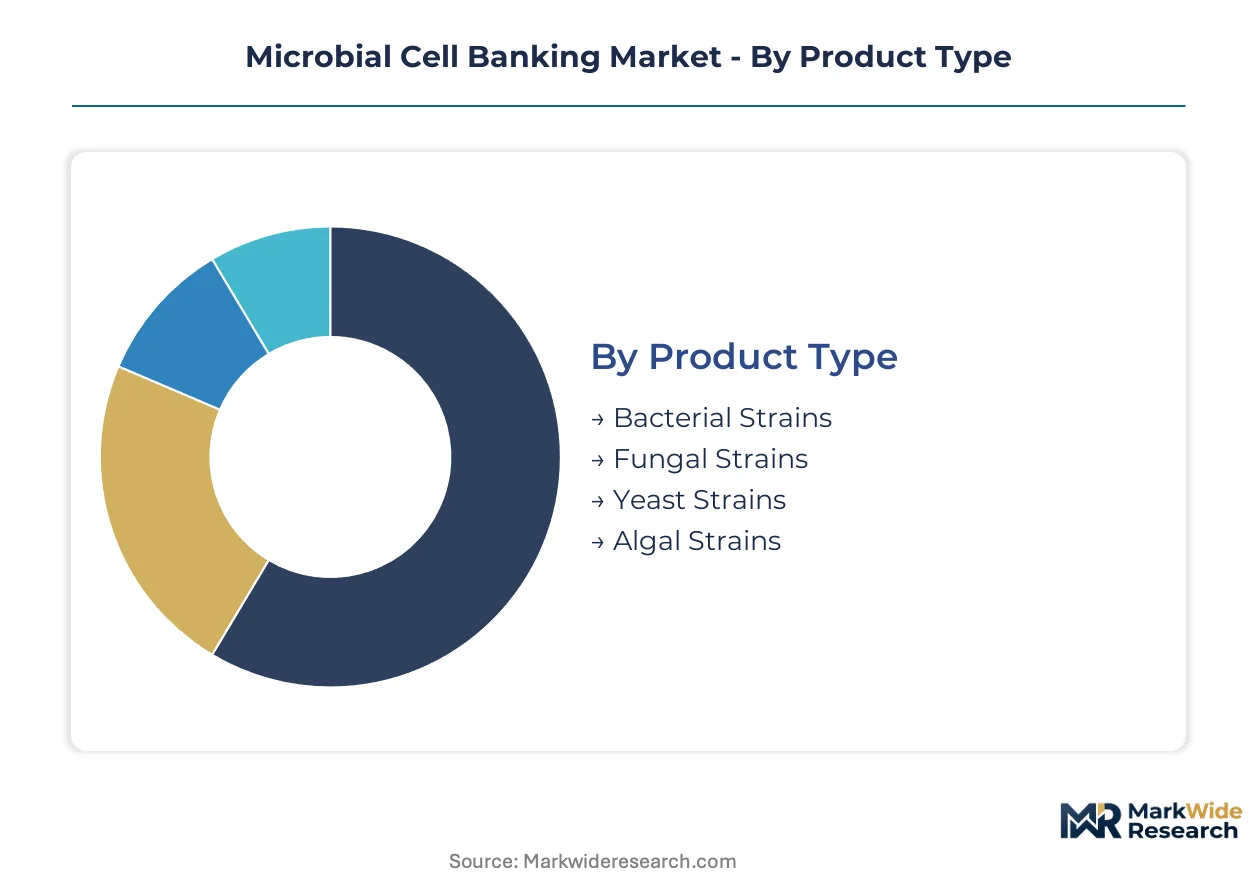
Microbial cell banking segmentation reveals how technical specifications, application requirements, and storage infrastructure shape procurement decisions across biopharmaceutical and industrial value chains. Each dimension carries distinct regulatory obligations and capital intensity profiles that determine vendor selection criteria.
Product Type:
Replacement cycles for master cell banks accelerate as next-generation sequencing verification becomes standard practice, forcing facilities to retire legacy banks lacking genomic fingerprint documentation.
- Bacterial Strains:Escherichia coli and Bacillus subtilis expression platforms dominate recombinant protein manufacturing with well-established genetic stability protocols. CDMOs in Boston and San Francisco corridors drive sustained demand for rigorously documented master banks supporting insulin and enzyme campaigns.
- Yeast Strains:Pichia pastoris and Saccharomyces cerevisiae systems enable post-translational modifications unavailable in bacterial hosts. Biosimilar and vaccine adjuvant manufacturers in Germany and Switzerland pay premiums for qualified yeast banks with glycosylation verification.
- Fungal Strains:Filamentous fungi such as Aspergillus and Trichoderma serve industrial enzyme production with complex secretion capabilities.
- Algal Strains:Photosynthetic platforms including Chlamydomonas and Spirulina remain underdeveloped for recombinant protein applications despite metabolic engineering advances.
Volume placements concentrate in bacterial strains; the faster expansion belongs to yeast strains.
Application:
Cost tier differentiation separates GMP-compliant biopharmaceutical banking from research-grade industrial applications, with certification requirements driving 3-5x pricing spreads.
- Biopharmaceuticals:Gene therapy vectors and mRNA production require full characterization traceability under FDA cell substrate guidance. Facilities must document genetic stability and adventitious agent testing across master and working cell bank generations.
- Industrial Biotechnology:Enzyme and biofuel applications prioritize high-titer strain performance over exhaustive regulatory documentation. European REACH compliance for cryopreservatives adds operational cost layers distinct from pharmaceutical GMP burdens.
- Food Production:Probiotic and fermentation starter cultures demand pathogen-free certification with shorter qualification timelines than drug substrates.
- Agricultural Biotechnology:Biofertilizer and biocontrol strain banking operates with reduced characterization requirements compared to human therapeutic applications.
Revenue concentration sits with biopharmaceuticals; industrial biotechnology is climbing the fastest as biofuel scale-up accelerates.
End User:
Customer type fragmentation splits between integrated pharmaceutical manufacturers outsourcing banking functions and specialized CDMOs building captive strain repositories.
- Pharmaceutical Companies:Large integrated manufacturers maintain internal master cell banks for core products while outsourcing specialized strain development to contract providers.
- Biotech Firms:Venture-backed mid-sized companies in United States clusters favor modular banking packages with unbundled characterization services to preserve capital efficiency.
- Research Institutions:Academic biobanks under ISO 20387 standards support fundamental microbiology research with limited GMP compliance requirements.
- Food Manufacturers:Fermentation facilities prioritize rapid working cell bank turnaround over exhaustive master bank documentation typical of pharmaceutical applications.
Procurement volume clusters with biotech firms; pharmaceutical companies are gaining share fastest as gene therapy pipelines mature.
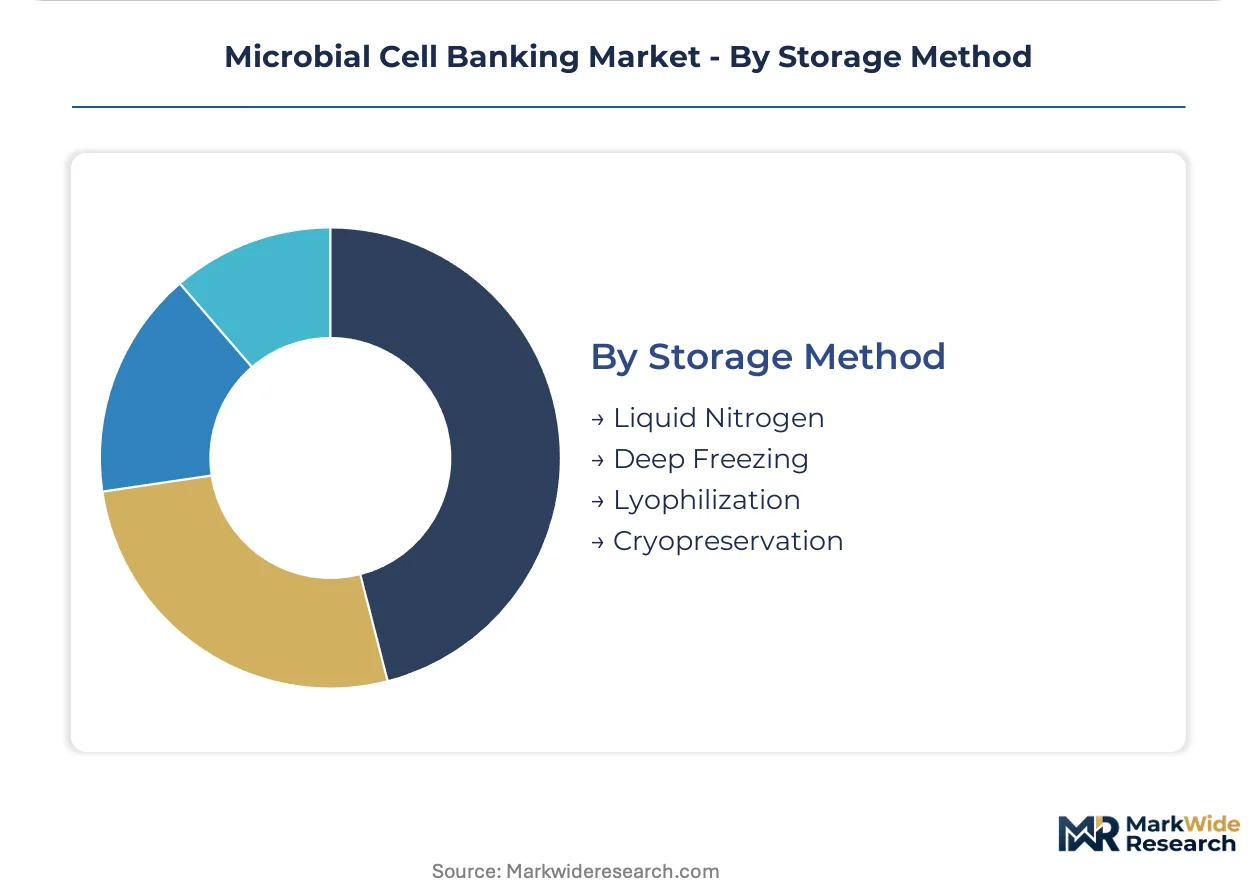
Storage Method:
Supply concentration in liquid nitrogen infrastructure creates geographic bottlenecks, with distributed manufacturers facing transport viability risks for temperature-sensitive materials.
- Liquid Nitrogen:Ultra-low temperature vapor-phase storage at minus 196 degrees Celsius preserves long-term viability for master cell banks with decades-long intended use horizons.
- Cryopreservation:Controlled-rate freezing with dimethyl sulfoxide or glycerol cryoprotectants balances viability retention with operational accessibility for working cell banks.
- Deep Freezing:Mechanical freezer storage at minus 80 degrees Celsius serves short-term working cell bank applications with reduced infrastructure investment.
- Lyophilization:Freeze-drying enables ambient-temperature distribution of stable microbial preparations, particularly for agricultural and food applications with less stringent viability thresholds.
Installed capacity concentrates in liquid nitrogen; lyophilization is expanding most quickly for distributed supply chain requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical contract manufacturing demand concentrates in the United States, where Boston and San Francisco biotech clusters anchor specialized banking capacity. Germany and Switzerland sustain premium yeast strain banking for biosimilar production. China and India expand CDMO infrastructure to capture recombinant protein manufacturing migration.
United States
FDA enhanced guidance on cell substrate characterization compels facilities toward higher compliance investment. Boston and San Francisco biotech corridors concentrate GMP-compliant banking capacity for distributed manufacturers. Gene therapy vector and mRNA production requirements pull specialized banking services into upstream supply chains.
Germany
Biosimilar and vaccine adjuvant manufacturers pay premiums for qualified yeast banks with glycosylation verification. EMA GMP Annex 1 revisions for sterile manufacturing impose stricter environmental monitoring on open-process banking operations. Bavaria and Baden-Württemberg host integrated life science tools portfolios anchoring European banking infrastructure.
Switzerland
Manufacturing-scale dominance through captive bioproduction networks sustains premium positioning. Swissmedic alignment with EMA quality-by-design enforcement shapes banking investment timelines. Basel and Zurich clusters concentrate pathogen-free strain qualification protocols for specialized applications.
China
CDMOs expanding Escherichia coli production lines for insulin manufacturing require rigorously documented master cell banks. NMPA biologics manufacturing standards push facilities toward ISO 20387 harmonization for cross-border material transfer. Yangtze River Delta biotech parks attract banking infrastructure investment for export-oriented recombinant protein campaigns.
India
Venture-backed mid-sized biotech firms favor modular banking packages with unbundled characterization services. CDSCO alignment with WHO TRS 978 cell substrate recommendations establishes baseline documentation requirements. Karnataka and Maharashtra biotech corridors develop captive strain repositories for cost-efficient outsourcing models.
Microbial Cell Banking Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue algae banking and automated cryopreservation systems. The market structures around integrated life science conglomerates, specialized CDMOs, and regional contract service providers. Three archetypes dominate: full-service banking with captive manufacturing networks, modular characterization specialists, and pathogen-free qualification experts. Consolidation pressures favor facilities with integrated quality systems; M&A activity targets sequencing-enabled verification capabilities.
Within the integrated conglomerate tier, Merck KGaA and Thermo Fisher Scientific exemplify life science tools portfolios that anchor regional banking infrastructure. Lonza Group occupies a position among manufacturing-scale specialists sustaining dominance through captive bioproduction networks. Charles River Laboratories represents the pathogen-free qualification archetype, with specialized strain protocols creating certification standards for market entrants.
| Leading Market Players |
|---|
| Merck KGaA |
| Eurofins Scientific |
| Lonza Group |
| Cryo-Cell International |
| SGS Life Sciences |
| Charles River Laboratories |
| Thermo Fisher Scientific |
| BSL Bioservice |
| WuXi AppTec |
| Others |
Value Network & Pricing Analysis
Dimethyl sulfoxide and glycerol-based cryoprotectant costs cascade through microbial cell banking tiers, with REACH-registered chemical inputs elevating European operational expenses above United States and Asian benchmarks. CDMOs in Boston and San Francisco corridors absorb premium liquid nitrogen infrastructure costs that concentrate pricing power among integrated facility operators.
Pricing Analysis
Volume placements concentrate in bacterial master cell banks with compressed margins, while yeast strain banking with glycosylation verification commands premium positioning. Three-tier pricing structure across GMP-certified, research-grade, and industrial-application levels separates biopharmaceutical clients from food and agricultural buyers. Pricing pressure stems from extended 12-18 month master cell bank qualification timelines that delay revenue recognition. Mid-sized biotech firms in United States clusters exhibit highest price sensitivity, prioritizing modular unbundled services over comprehensive contracts.
Supply Chain Analysis
Regional distribution centers in Boston, San Francisco, and Basel anchor hub-and-spoke patterns for temperature-sensitive master cell bank materials. Supply concentrates in the United States, Germany, and Switzerland for GMP-compliant banking infrastructure. Raw material dependencies include liquid nitrogen infrastructure, dimethyl sulfoxide cryoprotectants, and next-generation sequencing reagents. Single-source vulnerability characterizes pathogen-free strain qualification capacity held by specialized providers. Distribution runs through captive bioproduction networks for integrated pharmaceutical manufacturers and contract service arrangements for distributed CDMOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial cell banking is consolidating around sequencing-enabled verification capabilities, with FDA genetic stability documentation requirements forcing facilities lacking in-house bioinformatics capacity toward acquisition or exit.
For Market Incumbents: To counter genomic stability verification bottlenecks, expand in-house next-generation sequencing capacity to compress qualification timelines from months to weeks. Secure captive liquid nitrogen infrastructure in Yangtze River Delta and Karnataka corridors to preempt emerging CDMO competition. Backward integration into cryoprotectant supply buffers REACH registration cost volatility. For New Entrants and Emerging Players: The premium-to-economy pricing gap in yeast strain banking with glycosylation verification offers white-space entry below established Swiss and German providers. Algal strain banking for photosynthetic recombinant protein production remains underdeveloped relative to bacterial dominance. Target modular characterization service contracts with venture-backed United States biotech firms seeking capital-efficient outsourcing. For Investors and Strategic Acquirers: ISO 20387 harmonization announcements from national biobanking authorities are the leading indicator that cross-border material transfer agreements will reshape competitive positioning. Facilities with automated cryopreservation systems and integrated quality systems represent priority acquisition archetypes. Watch for CDMO consolidation signals in China and India as NMPA and CDSCO alignment with international standards accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Next-Generation Sequencing Integration | In-house genomic verification compresses master cell bank qualification timelines for CDMOs. |
| Automated Cryopreservation Deployment | Closed-system automation elevates contamination control under EMA GMP Annex 1 revisions. |
| Yeast Strain Glycosylation Certification | Post-translational modification documentation commands premium pricing from biosimilar manufacturers. |
| Algal Banking Infrastructure Buildout | Photosynthetic platform investment captures first-mover positioning in recombinant protein applications. |
| ISO 20387 Cross-Border Harmonization | International material transfer agreements reduce redundant testing for multi-site manufacturers. |
Research Methodology
Document review covered FDA guidance documents, EMA GMP Annex 1 revisions, ISO 20387 biobanking standards, and WHO TRS 978 recommendations, complemented by interviews with biopharmaceutical contract manufacturing executives, regulatory affairs specialists, and quality assurance directors at master cell banking facilities. Secondary validation drew from SEC filings of publicly traded life science tools providers, clinical trial registry data for gene therapy vector programs, and customs records for cryopreservative chemical trade flows. Bottom-up segment sizing and top-down market triangulation were cross-referenced against facility capacity announcements and CDMO expansion disclosures.
Historical growth patterns were cross-referenced against panel input from industry participants to construct analytical frameworks across bacterial strain, yeast strain, fungal strain, and algal strain product categories; biopharmaceutical, industrial biotechnology, food production, and agricultural biotechnology applications; and liquid nitrogen, cryopreservation, deep freezing, and lyophilization storage methods. CAGRs were derived from regression analysis of segment penetration rates and capacity expansion trajectories. Forecast inputs included gene therapy pipeline maturation timelines, mRNA manufacturing scale-up announcements, and regulatory harmonization milestones.
Inputs from primary interviews and regulatory document repositories were available through the study window; gaps in real-time CDMO contract pricing and proprietary strain qualification protocol details introduce uncertainty bands around segment share estimates. Forecasts reflect documented assumptions regarding FDA enforcement consistency, EMA implementation timelines, and ISO standard adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Microbial Bioreactors Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Salinomycin Market
Industrial Microbiology
Microbial Seed Treatment Market