
 Real Time Continuous Microbiological Monitoring Systems Market | 2026-2036
Real Time Continuous Microbiological Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Real Time Continuous Microbiological Monitoring Systems Market Analytics
Capital-intensity divergence between laser-based optical platforms and legacy fluorescence systems is collapsing as solid-state photonics costs fall. Thermo Fisher Scientific leverages integrated mass spectrometry workflows to anchor premium positioning in pharmaceutical quality control. Danaher competes through Beckman Coulter life sciences subsidiaries with automated flow cytometry pipelines for environmental monitoring.
Real time continuous microbiological monitoring systems deploy in-line sensors detecting viable particles through light scattering, impedance, or ATP bioluminescence with sensitivity thresholds below one colony-forming unit per cubic meter. These instruments serve sterile manufacturing, potable water distribution, and cleanroom certification by replacing delayed culture-based enumeration with instantaneous contamination alerts. Automated systems command the dominant installed base where 24/7 pharmaceutical operations require uninterrupted data streams, while biosensor technology captures the fastest expansion as electrochemical and optical transducer miniaturization enables point-of-use deployment. Food safety applications sustain premium pricing through pathogen-specific assay cartridges validated against ISO 16140 reference methods.
FDA process analytical technology guidelines and EU GMP Annex 1 revision on contamination control strategy compel pharmaceutical manufacturers to demonstrate continuous environmental monitoring coverage. EMA inspections now cite absence of real-time viable particle detection as critical deficiencies in aseptic filling suites. Stakeholders must weigh optical detection platform standardization against biosensor modularity as regulatory harmonization between FDA, EMA, and WHO prequalification programs crystallizes over the coming decade.
Market Dynamics
Pharmaceutical manufacturers face relentless pressure from EU GMP Annex 1 contamination control mandates, forcing immediate sensor deployment across aseptic filling lines where batch release depends on continuous viable particle verification.
Growth Catalysts
- FDA Process Analytical Technology Guidelines:The framework compels sterile drug manufacturers to embed real-time detection within quality-by-design protocols, accelerating capital allocation toward continuous monitoring infrastructure.
- Solid-state photonics cost collapse:Falling prices for laser diodes and CMOS detectors are collapsing the capital gap between optical platforms and legacy fluorescence systems, democratizing access across mid-tier pharmaceutical operations.
- Rhine-Main biopharma cluster:Germany's sterile injectable production hub drives sensor density requirements, with fill-finish facilities demanding sub-CFU-per-cubic-meter sensitivity thresholds that only continuous systems deliver.
Market Restraints
- Validation timeline compression:EMA inspection cycles demand six-to-twelve-month qualification periods for alternative microbiological methods, delaying revenue realization despite technical readiness.
- Single-source photonics supply:High-precision laser modules concentrate among German and Japanese component suppliers, exposing instrument manufacturers to allocation risk during semiconductor demand surges.
- Culture-based method entrenchment:Pharmacopeial compendia still reference plate enumeration as the arbitration standard, forcing parallel validation burdens that inflate total cost of ownership.
Strategic Opportunities
- Point-of-use biosensor deployment:Electrochemical transducer miniaturization enables distributed sensing architectures within water-for-injection loops and personnel airlocks, bypassing centralized sampling infrastructure.
- Food safety pathogen cartridges:ISO 16140-validated assay formats for Listeria and Salmonella command premium pricing in ready-to-eat meat processing, extending pharmaceutical-grade technology into adjacent regulated industries.
- EMA-WHO regulatory harmonization:Convergence between European inspection protocols and WHO prequalification standards creates unified certification pathways for instruments serving emerging market vaccine manufacturing.
Industry Challenges
- Metrology talent scarcity:Cross-functional expertise spanning microbiology, photonics, and GMP compliance remains concentrated among senior practitioners near retirement, constraining deployment velocity.
- Legacy Building Management System integration:BACnet and Modbus protocol mismatches between new optical sensors and existing environmental monitoring infrastructure demand costly middleware development.
- ATP bioluminescence specificity gaps:Enzymatic detection cannot distinguish viable from non-viable cellular material, generating false-positive alerts that erode operator trust and trigger unnecessary line interventions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real Time Continuous Microbiological Monitoring Systems Market |
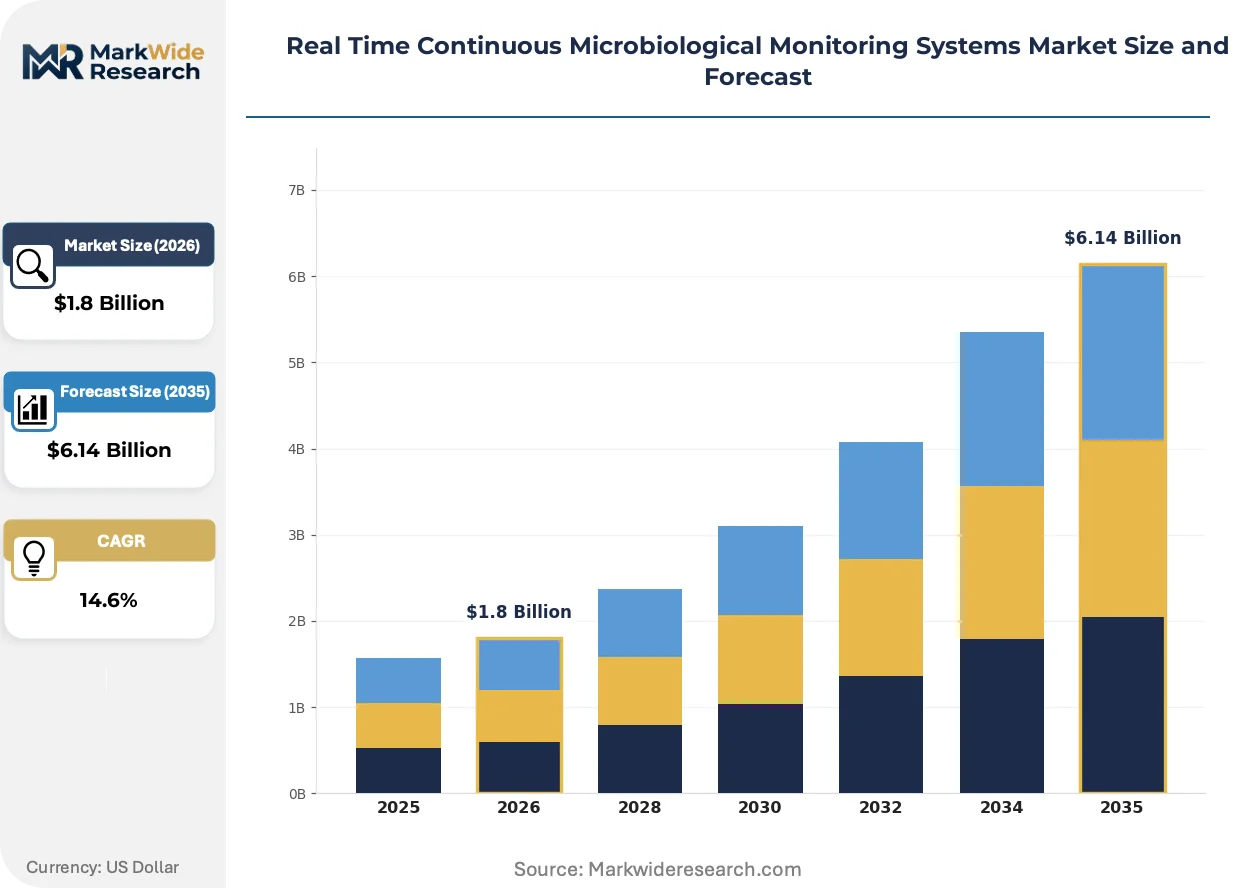
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Automated Systems, Data Loggers, Microbial Sensors Technology: Optical Detection, PCR, Flow Cytometry, Biosensors Application: Food Safety, Water Quality, Pharmaceutical, Biotechnology End User: Food Manufacturers, Environmental Agencies, Research Labs, Hospitals |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher, bioMérieux, Becton Dickinson and Company, Mettler Toledo, Bio-Rad Laboratories, Inc., QIAGEN, BioVigilant, Alpha Controls & Instrumentation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real Time Continuous Microbiological Monitoring Systems Market Evolving Landscape
Sensor architectures are fragmenting across three distinct innovation vectors: photonic miniaturization, regulatory method harmonization, and procurement model restructuring. Each vector carries distinct competitive implications for instrument vendors and end-user facilities.
Impedance-based cytometry is miniaturizing through lab-on-chip electrode arrays that detect microbial metabolism via electrical signature changes. Contract manufacturing organizations in Ireland and Singapore are adopting these platforms for portable environmental monitoring, bypassing fixed installation constraints. The technology is miniaturizing quality control from central laboratories to production floor decision points, compressing response latency from hours to minutes.
EU GMP Annex 1 revision on contamination control strategy now mandates continuous viable particle detection as a critical element of aseptic process qualification. Pharmaceutical manufacturers must demonstrate uninterrupted environmental coverage across Grade A and Grade B zones, with EMA inspections citing absence of real-time systems as critical deficiencies. German and Swiss sterile fill-finish operations are responding by consolidating vendor relationships around platforms offering integrated data integrity and audit trail functionality.
Service unbundling is fragmenting traditional instrument procurement, with pharmaceutical quality departments separating hardware acquisition from validation support and reagent supply. Third-party metrology specialists in the Netherlands and Massachusetts are capturing recurring revenue streams through independent qualification services, displacing captive vendor service organizations. This pattern is most visible among mid-cap generic injectable manufacturers seeking operational flexibility without long-term capital commitments.
Real Time Continuous Microbiological Monitoring Systems Market Segmentation
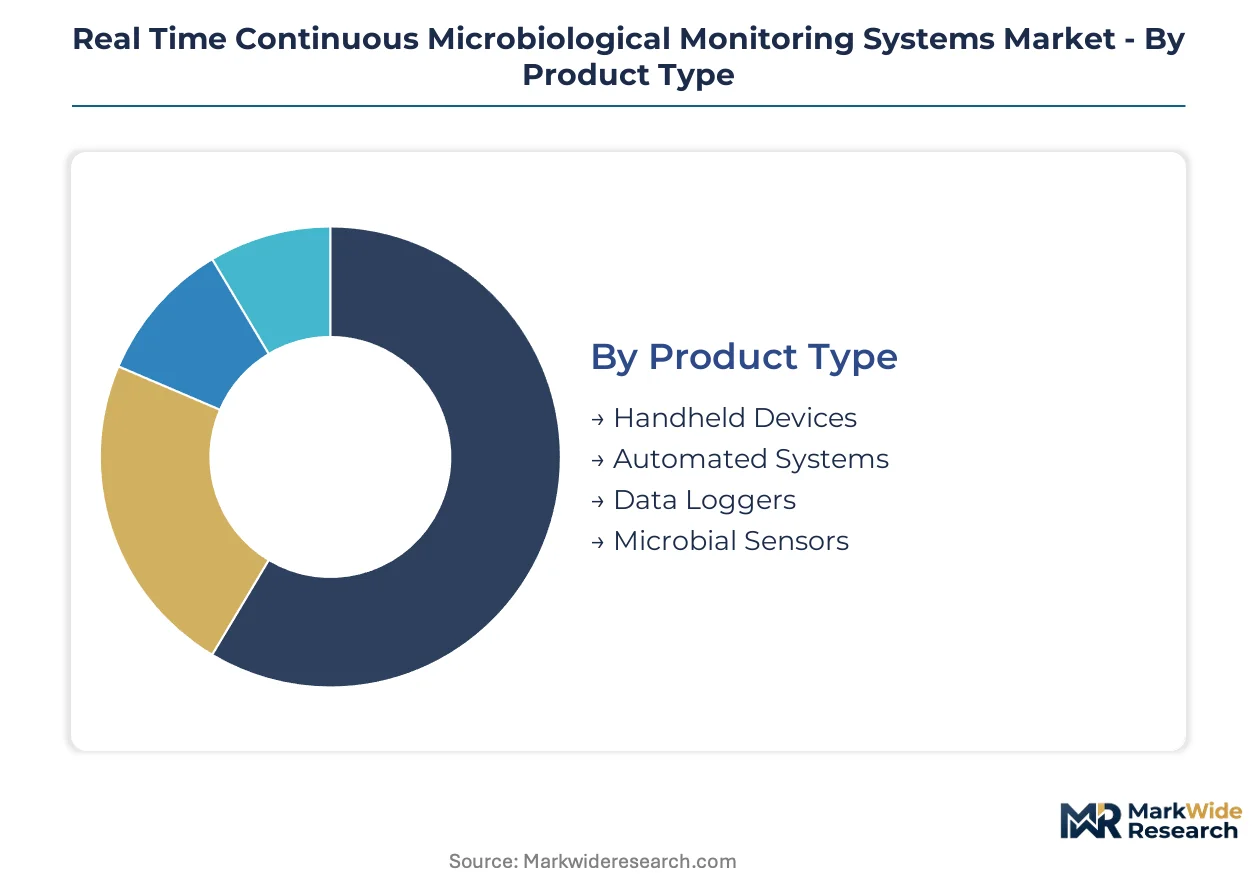
Segmentation in real-time microbiological monitoring reveals divergent margin structures across hardware platforms and detection modalities. Pharmaceutical-grade automation commands premium pricing, while portable biosensors penetrate adjacent regulated industries through modular assay formats.
Product Type:
Margin pools concentrate in automated systems serving 24/7 aseptic operations, where data integrity requirements sustain service-anchored revenue models.
- Automated Systems:These platforms integrate in-line sensors with centralized data management for continuous environmental monitoring across Grade A and Grade B cleanrooms. Demand concentrates in Germany's Rhine-Main sterile injectable cluster, where EMA Annex 1 compliance mandates uninterrupted viable particle verification with sub-CFU-per-cubic-meter sensitivity thresholds.
- Microbial Sensors:Solid-state photonic and electrochemical transducers detect metabolic activity through light scattering or impedance changes without culture delays. Water-for-injection loops in Irish and Singaporean contract manufacturing facilities drive point-of-use deployment, bypassing centralized sampling infrastructure through miniaturized form factors.
- Handheld Devices:Portable ATP bioluminescence meters serve rapid surface monitoring in food processing environments requiring ISO 16140-validated pathogen detection.
- Data Loggers:Environmental parameter recorders aggregate temperature, humidity, and viable particle streams for batch release documentation in GMP-regulated operations.
Automated systems hold installed capacity. Microbial sensors are rotating up the share rankings.
Technology:
Cost tier stratification separates capital-intensive optical platforms from emerging biosensor alternatives as solid-state component prices collapse.
- Optical Detection:Laser-based light scattering and fluorescence systems identify viable particles through morphometric analysis with single-cell resolution. Thermo Fisher Scientific anchors premium positioning in pharmaceutical quality control through integrated mass spectrometry workflows, while falling laser diode and CMOS detector costs democratize access across mid-tier operations.
- Biosensors:Electrochemical and optical transducers convert biological recognition events into quantifiable signals without amplification steps. Danaher's Beckman Coulter subsidiaries compete through automated flow cytometry pipelines, capturing fastest expansion as transducer miniaturization enables distributed sensing architectures within personnel airlocks and WFI distribution networks.
- PCR:Nucleic acid amplification enables species-level identification of slow-growing or non-culturable organisms in biotechnology process validation.
- Flow Cytometry:Impedance-based cytometry miniaturizes through lab-on-chip electrode arrays detecting metabolic electrical signatures, compressing response latency from hours to minutes at production floor decision points.
Optical detection holds installed capacity. Biosensors are climbing the fastest.
Application:
Volume concentration in pharmaceutical sterile manufacturing contrasts with pricing power in food safety pathogen detection.
- Pharmaceutical:Aseptic filling suites require continuous viable particle coverage across Grade A zones, with FDA process analytical technology guidelines embedding real-time detection within quality-by-design protocols. EMA inspections cite absence of continuous monitoring as critical deficiencies, forcing immediate sensor deployment where batch release depends on environmental verification.
- Food Safety:Pathogen-specific assay cartridges for Listeria and Salmonella command premium pricing in ready-to-eat meat processing. ISO 16140 validation against reference methods extends pharmaceutical-grade technology into adjacent regulated industries with less stringent GMP infrastructure requirements.
- Water Quality:Potable water distribution networks deploy continuous monitoring for fecal indicator organisms and emerging contaminants in municipal treatment facilities.
- Biotechnology:Cell culture process monitoring requires rapid sterility testing to prevent batch loss in monoclonal antibody production.
Pharmaceutical holds installed capacity. Food safety is gaining share fastest.
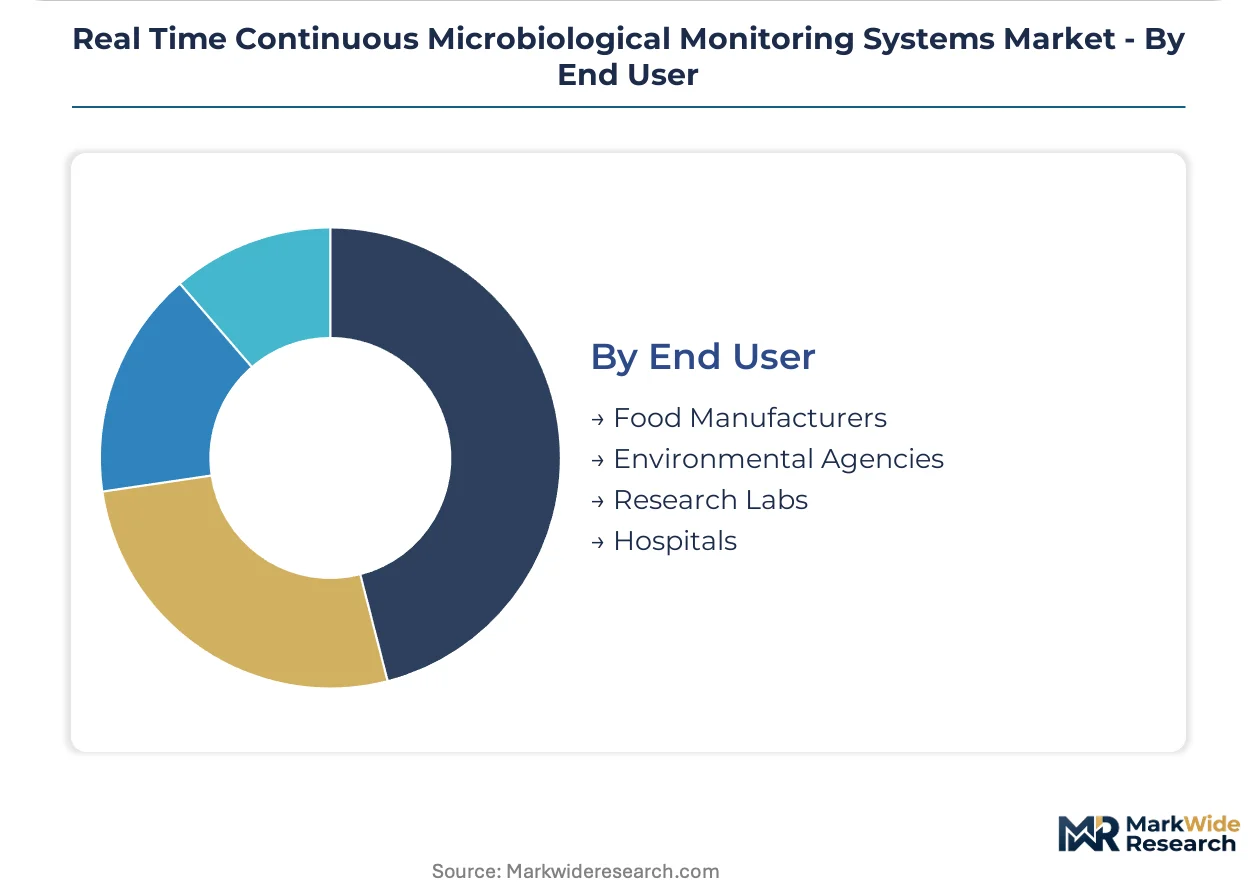
End User:
Customer type determines procurement model fragmentation, with pharmaceutical quality departments unbundling hardware from validation services.
- Food Manufacturers:Ready-to-eat processing facilities adopt pathogen-specific biosensors for HACCP verification, with ISO 16140-validated formats sustaining premium cartridge pricing through regulatory audit requirements.
- Environmental Agencies:Municipal water authorities deploy continuous monitoring for compliance with national drinking water standards and recreational water quality criteria.
- Research Labs:Academic and government research facilities utilize handheld ATP meters and portable cytometry for field microbiology applications with flexible funding constraints.
- Hospitals:Healthcare facilities monitor water systems for Legionella and other opportunistic pathogens in immunocompromised patient environments.
Food manufacturers hold installed capacity. Environmental agencies are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys real-time microbiological monitoring systems primarily for sterile injectable verification, while the United States concentrates investment in multi-modal pharmaceutical quality control and Singapore accelerates point-of-use biosensor adoption in contract manufacturing.
United States
FDA Process Analytical Technology guidelines compel sterile drug manufacturers to embed continuous detection within quality-by-design protocols. The agency's inspection data identifies absence of real-time viable particle coverage as a recurring citation in aseptic filling suites. Greater Boston's biopharma corridor drives sensor density requirements, with fill-finish facilities demanding sub-CFU-per-cubic-meter sensitivity thresholds.
Germany
The Rhine-Main biopharma cluster sustains Europe's densest concentration of continuous monitoring installations. EU GMP Annex 1 revision mandates uninterrupted environmental coverage across Grade A and Grade B zones, with EMA inspections citing real-time system absence as critical deficiencies. Hesse-based sterile injectable producers are consolidating vendor relationships around platforms with integrated data integrity functionality.
Switzerland
Swissmedic's alignment with EMA inspection protocols accelerates alternative microbiological method qualification timelines. The country's precision manufacturing heritage supports demand for laser-based optical platforms with single-cell resolution capabilities. Basel's pharmaceutical headquarters cluster drives premium-tier instrument procurement for monoclonal antibody production facilities.
Singapore
Contract manufacturing organizations adopt miniaturized impedance-based cytometry for portable environmental monitoring, bypassing fixed installation constraints. The national pharmaceutical regulator harmonizes with WHO prequalification standards, creating unified certification pathways for emerging market vaccine manufacturing. Tuas Biomedical Park facilities deploy distributed sensing architectures within water-for-injection loops.
India
CDSCO's phased alignment with ICH Q5A guidelines pressures domestic sterile manufacturers toward continuous monitoring adoption. The country's injectable export growth to regulated markets necessitates EMA-comparable environmental verification systems. Hyderabad's vaccine manufacturing cluster integrates real-time viable particle detection to satisfy WHO prequalification audit requirements.
Real Time Continuous Microbiological Monitoring Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in real-time microbiological monitoring systems. Thermo Fisher Scientific and Danaher occupy positions with extensive life sciences portfolios spanning mass spectrometry workflows and automated flow cytometry pipelines. Mid-scale optical specialists and electrochemical biosensor developers compete through modular point-of-use formats. Strategic moves concentrate on validation service unbundling and solid-state photonics cost reduction.
Among diversified laboratory technology conglomerates, Thermo Fisher Scientific Inc. and Danaher exemplify integrated platform strategies spanning detection hardware through data management software. BioMérieux occupies a position within the microbial identification specialist tier, while Becton Dickinson and Company represents the medical-technology-to-diagnostics convergence archetype. These three entities anchor competitive positioning across pharmaceutical quality control and adjacent regulated industries.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher |
| bioMérieux |
| Becton Dickinson and Company |
| Mettler Toledo |
| Bio-Rad Laboratories, Inc. |
| QIAGEN |
| BioVigilant |
| Alpha Controls & Instrumentation Inc. |
| Others |
Value Network & Pricing Analysis
EU GMP Annex 1 revision gates both supplier qualification and price differentiation simultaneously, forcing instrument vendors to absorb validation service costs while pharmaceutical buyers demand integrated data integrity functionality as table stakes rather than premium features. This regulatory threshold collapses the traditional hardware-software pricing boundary, compressing margins on standalone sensors while elevating bundled platform pricing.
Pricing Analysis
Long-term service contracts dominate procurement, with pharmaceutical quality departments unbundling hardware acquisition from independent validation support and reagent supply. Three-tier pricing structure across premium, standard, and economy levels separates laser-based optical platforms with mass spectrometry integration from miniaturized biosensors and handheld ATP meters. Cost compression in mid-tier optical systems is intensifying because solid-state photonics costs are falling faster than vendors can differentiate through feature expansion. Generic injectable manufacturers exhibit highest price sensitivity, while monoclonal antibody producers prioritize sensitivity thresholds over unit economics.
Supply Chain Analysis
Germany and Japan anchor high-precision laser module production, with specialized foundries in Hesse and Osaka prefectures supplying single-mode diodes and CMOS detector arrays that instrument manufacturers source for optical detection platforms. Solid-state photonics, electrochemical transducer substrates, and ISO 16140-validated assay reagents constitute critical input dependencies. Single-source vulnerability concentrates in German laser component suppliers, exposing allocation risk during semiconductor demand surges. Distribution runs through direct vendor relationships with fill-finish facilities, supplemented by third-party metrology specialists capturing recurring qualification service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time microbiological monitoring represents high-growth disruption as EU GMP Annex 1 mandates transform continuous viable particle detection from competitive advantage to operational necessity. FDA process analytical technology guidelines compound this inflection, embedding real-time detection within quality-by-design protocols.
For Market Incumbents: Secure validation service revenue streams through independent qualification partnerships, displacing captive vendor organizations that pharmaceutical buyers increasingly reject. Deepen backward integration into solid-state photonics supply to mitigate single-source laser module exposure from German and Japanese component suppliers. Anchor premium positioning through integrated mass spectrometry workflows that emerging electrochemical biosensor developers cannot replicate.
For New Entrants and Emerging Players: FDA alternative microbiological method qualification fast-track offers entry pathway for miniaturized impedance-based cytometry platforms targeting contract manufacturing organizations in Singapore and Ireland. Food safety pathogen detection presents most penetrable segment, with ISO 16140-validated Listeria and Salmonella cartridges commanding premium pricing in ready-to-eat meat processing with less stringent GMP infrastructure requirements than pharmaceutical applications. Pursue point-of-use deployment model bypassing centralized sampling infrastructure.
For Investors and Strategic Acquirers: EMA-WHO regulatory harmonization reshapes the acquisition landscape, creating unified certification pathways for instruments serving emerging market vaccine manufacturing. Five-to-ten-year viability centers on platforms demonstrating sub-CFU-per-cubic-meter sensitivity with integrated audit trail functionality. Target acquisition archetype: electrochemical biosensor developers with lab-on-chip electrode arrays and existing ISO 16140 validation. Signal to monitor: CDSCO alignment pace with ICH Q5A guidelines pressuring Indian sterile manufacturers toward continuous monitoring adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Method Harmonization | EMA-WHO convergence creates unified certification pathways for emerging market vaccine manufacturing. |
| Point-of-Use Biosensor Deployment | Electrochemical transducer miniaturization enables distributed sensing within water-for-injection loops. |
| Validation Service Unbundling | Third-party metrology specialists capture recurring revenue through independent qualification services. |
| Solid-State Photonics Integration | Falling laser diode and CMOS detector costs democratize optical platform access across mid-tier operations. |
| Food Safety Pathogen Cartridges | ISO 16140-validated assay formats extend pharmaceutical-grade technology into adjacent regulated industries. |
Research Methodology
Operator-level perspectives from pharmaceutical quality control directors, regulatory affairs leads at sterile injectable manufacturers, GMP compliance officers, and third-party metrology specialists anchored the qualitative base. Primary interviews combined with secondary validation against FDA warning letter databases, EMA inspection deficiency reports, ISO 16140 reference method documentation, and SEC filings from diversified laboratory technology conglomerates. Bottom-up sensor deployment estimates across Rhine-Main and Greater Boston biopharma clusters triangulated against top-down market sizing from instrument vendor revenue disclosures.
Sensitivity analysis tested forecast robustness across alternative regulatory alignment scenarios and solid-state photonics cost decline trajectories. Segmentation dimensions modeled include detection modality, automation level, application vertical, and end-user procurement model. CAGRs derived from instrument replacement cycles, regulatory enforcement intensity, and biosensor miniaturization adoption curves. Industry-specific inputs incorporated EMA inspection citation patterns and WHO prequalification audit requirements for emerging market vaccine facilities.
Underlying assumptions cover EU GMP Annex 1 enforcement consistency, laser module supply stability, and alternative microbiological method qualification timeline compression, with deviation risk concentrated in pharmacopeial compendia revision pace and semiconductor allocation volatility. Recalibration cycles align with material shifts in regulatory harmonization milestones and solid-state component pricing inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Microbial Lipase Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Global Microbial Testing Market