
 Bacterial Antigens Market | 2026-2036
Bacterial Antigens Market Size, Share, and Industry Trends Forecast 2026-2036
Bacterial Antigens Market Analytics
The bacterial antigens supply base is realigning around a sharp split between premium recombinant grades and commodity polyclonal extracts. Bio-Rad Laboratories leverages its chromatography and quality-control infrastructure to sustain premium positioning across diagnostic and research channels. Creative Diagnostics competes on breadth, offering custom conjugation and species-specific variants that anchor its catalog business. Microbix Biosystems dominates infectious-disease antigen manufacturing through cGMP-compliant bioreactor operations that extend its reach into vaccine-development partnerships.
Bacterial antigens are purified or recombinant protein preparations derived from pathogenic or commensal bacteria, typically characterized by molecular weight, endotoxin levels below specified thresholds, and immunoreactivity against target antibodies; they serve as critical reagents for serological assay development, vaccine immunogenicity testing, and therapeutic antibody discovery. Recombinant antigens lead product-type revenue due to batch-to-batch consistency and scalable E. coli or yeast expression systems that reduce dependence on live-pathogen cultivation. Diagnostic laboratories represent the fastest-expanding end-user segment as automated immunoassay platforms at hospital networks and reference labs multiply test volumes for sepsis, Lyme disease, and tuberculosis detection.
The FDA enforces stringent lot-release criteria for in vitro diagnostic components, while the EMA's In Vitro Diagnostic Regulation mandates performance documentation that shapes how antigen suppliers structure clinical-validation investments. India's CDSCO applies import-registration requirements that filter which overseas manufacturers can supply diagnostic reagents to its expanding network of NABL-accredited laboratories. Stakeholders must monitor how evolving pharmacopeial standards for endotoxin and host-cell protein limits reshape supplier qualification timelines and capital allocation across production facilities.
Market Dynamics
The bacterial antigens market is undergoing a structural pivot driven by regulatory tightening of endotoxin specifications, which is forcing manufacturers to abandon legacy polyclonal extraction methods and migrate toward GMP-compliant recombinant production platforms.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Performance documentation mandates are accelerating clinical-validation investments by antigen suppliers seeking CE-marked access to European diagnostic laboratories.
- Automated immunoassay platforms:Hospital networks and reference laboratories are multiplying test volumes for sepsis and tuberculosis detection, pulling through higher-grade antigen procurement.
- India's CDSCO import-registration requirements:Domestic biotech firms are scaling recombinant antigen output to capture share from filtered overseas competitors in NABL-accredited laboratory supply chains.
Market Restraints
- Live-pathogen cultivation dependency:Polysaccharide and whole-cell antigen production remains tethered to biosafety-level containment facilities with limited geographic distribution.
- Chromatography resin cost volatility:Protein A and affinity resin supply concentration in North American and European chemical manufacturers squeezes margin structures for mid-scale producers.
- Host-cell protein detection limits:Pharmacopeial standards for residual E. coli or yeast proteins are tightening faster than analytical method standardization can accommodate.
Strategic Opportunities
- CDSCO-registered contract manufacturing:Indian export-oriented producers can bridge supply gaps for European and North American vaccine developers seeking dual-source antigen security.
- Synthetic peptide antigen convergence:Solid-phase peptide synthesis combined with computational epitope mapping is opening therapeutic antibody discovery applications previously served only by recombinant proteins.
- Point-of-care diagnostic expansion:Lateral flow and cartridge-based platforms in Southeast Asian and African health systems are creating demand for stabilized, lyophilized antigen formulations.
Industry Challenges
- GMP bioreactor operator scarcity:Qualified personnel for aseptic mammalian and microbial cell culture operations are concentrated in established pharmaceutical clusters, constraining facility expansion timelines.
- Lot-release certification delays:FDA and EMA backlog in endotoxin and sterility testing documentation is extending supplier qualification cycles for new antigen entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacterial Antigens Market |
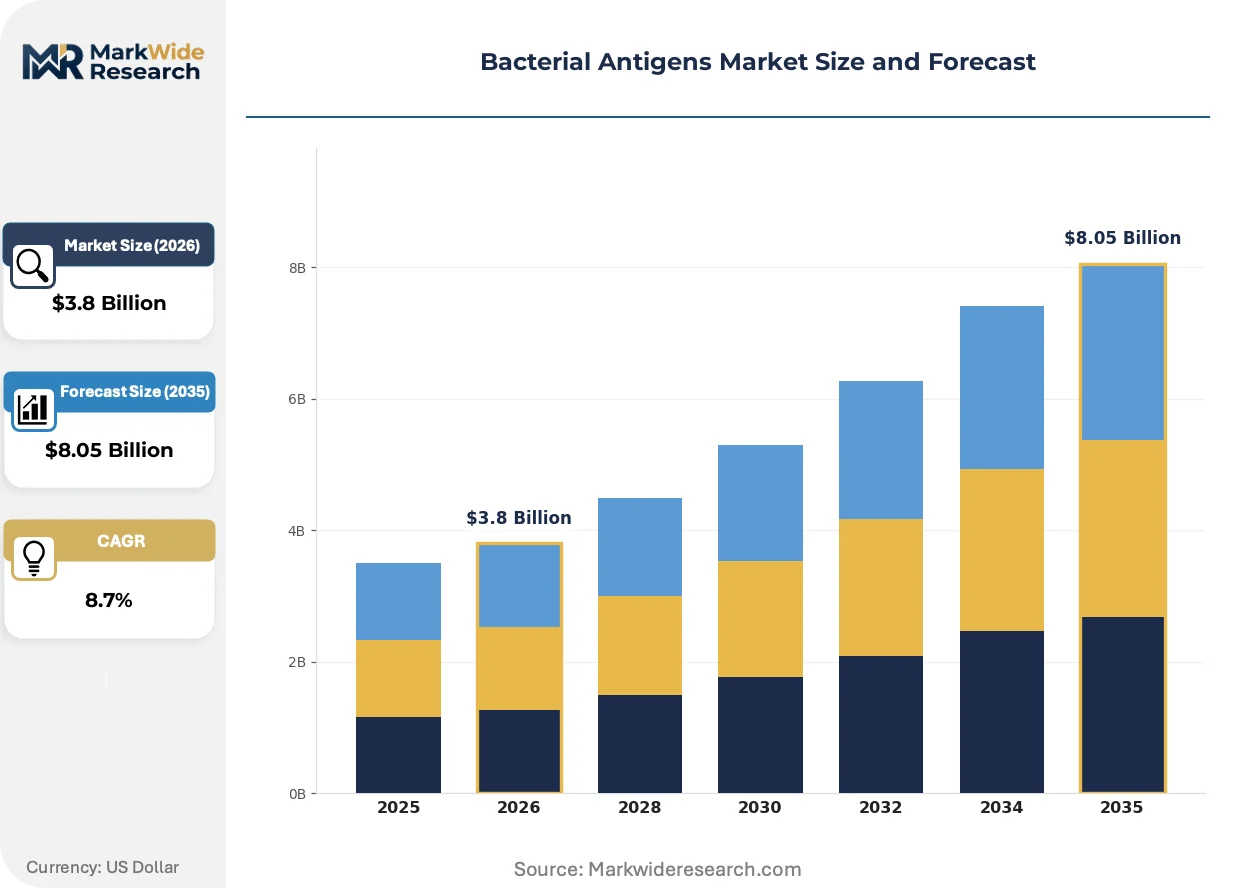
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Recombinant Antigens, Synthetic Peptides Application: Diagnosis, Vaccine Development, Research, Therapeutic Use End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Biotech Firms Delivery Mode: Injectable, Oral, Intranasal, Transdermal |
| Companies Covered | Bio-Rad Laboratories, The Native Antigen Company, Creative Diagnostics, Microbix Biosystems, Ross Southern Laboratories, Enzo Life Sciences, SERION Immunologics, Jena Bioscience GmbH, QED Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacterial Antigens Market Evolving Landscape
Recombinant expression technologies are compressing the competitive moat between research-grade and diagnostic-grade antigen suppliers, while regulatory documentation requirements are reshaping how manufacturers structure clinical-validation investments.
Cell-free protein synthesis is consolidating as an alternative platform for rapid antigen prototyping and small-batch production of toxic or unstable bacterial proteins. Vaccine developers at early-stage biotech firms are adopting E. coli and wheat germ lysate systems to compress lead times from gene sequence to purified antigen. This distributed production model is consolidating control over intellectual property and batch records within sponsor organizations rather than contract manufacturing networks.
The FDA's tightened lot-release criteria for in vitro diagnostic components are mandating expanded stability and immunoreactivity documentation from antigen suppliers. Manufacturers must now submit accelerated degradation studies and cross-reactivity panels that previously fell outside predicate device pathways. Diagnostic reagent kit assemblers in the United States are responding by consolidating supplier bases to partners with established FDA master files and quality agreement templates.
Hospital network procurement offices are consolidating antigen purchasing through centralized reference laboratory contracts rather than distributed department-level ordering. This buyer concentration is compressing price negotiation cycles and privileging suppliers with multi-product catalogs and conjugation service capabilities. The shift is most visible in North American integrated delivery networks where sepsis and Lyme disease testing volumes have scaled rapidly.
Bacterial Antigens Market Segmentation
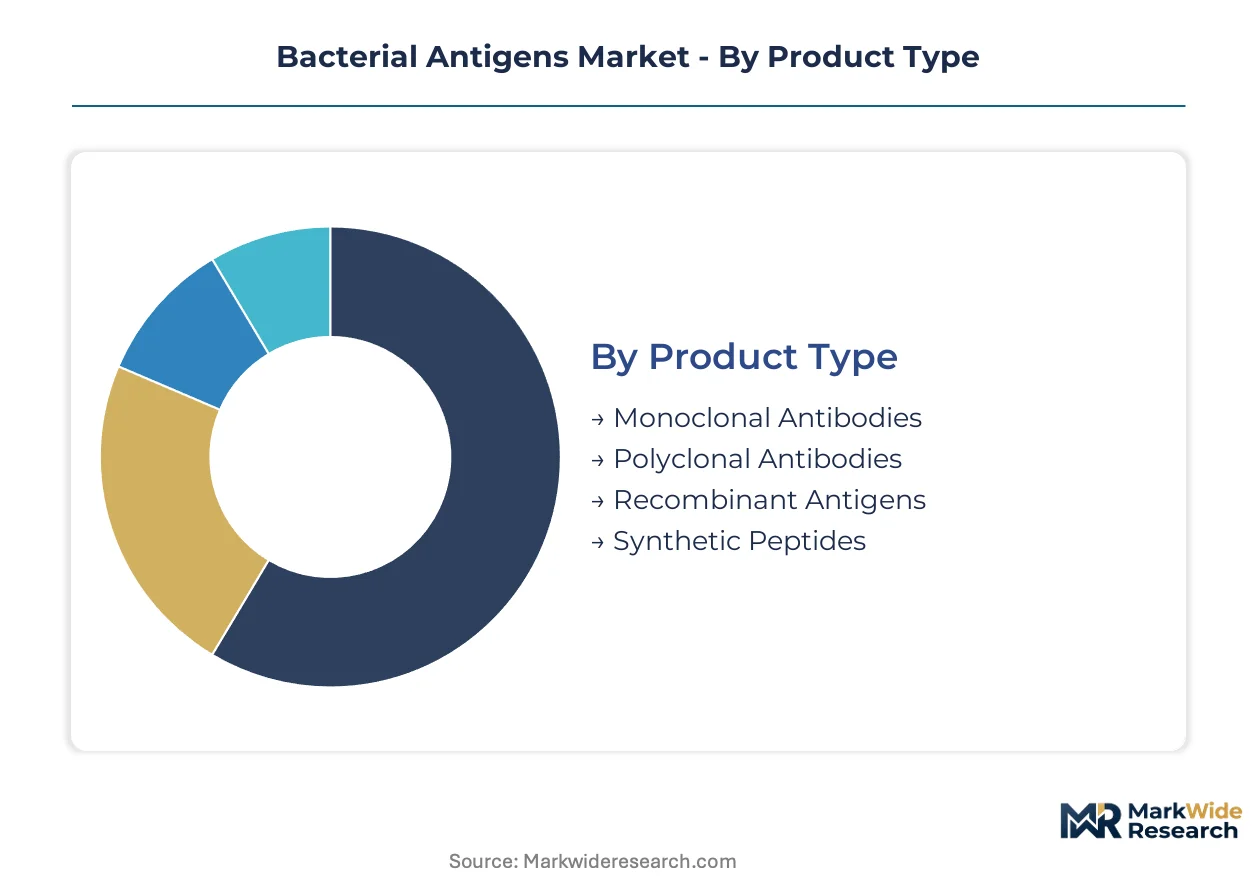
Segmentation in bacterial antigens reveals how supply chain configuration and end-use requirements fragment procurement patterns. Manufacturers must align production platforms with the divergent purity, scale, and documentation demands of diagnostic, vaccine, and research channels.
Product Type:
Supply concentration for bacterial antigens varies sharply across expression platforms, with recombinant and synthetic production consolidating among GMP-certified manufacturers while polyclonal extraction remains geographically dispersed.
- Recombinant Antigens:Purified protein preparations expressed in E. coli, yeast, or mammalian systems with defined endotoxin thresholds and batch-to-batch consistency. Hospital network laboratories in the United States and Germany are standardizing procurement around recombinant grades to meet FDA and EMA diagnostic-grade specifications, displacing legacy polyclonal extracts in automated immunoassay platforms.
- Synthetic Peptides:Solid-phase synthesized epitope sequences with computational design for defined immunoreactivity profiles. Early-stage biotech firms in India and Switzerland are adopting synthetic peptides for therapeutic antibody discovery, compressing lead times from sequence identification to purified reagent compared to recombinant workflows.
- Monoclonal Antibodies:Hybridoma-derived or recombinant single-epitope binders requiring dedicated cell culture infrastructure and extended development timelines.
- Polyclonal Antibodies:Multi-epitope serum preparations from immunized animals, constrained by lot variability and biosafety-level containment requirements for live-pathogen immunization.
Recombinant Antigens absorb the bulk of installed capacity; Synthetic Peptides is expanding most quickly.
Application:
Application segmentation tracks how regulatory documentation requirements and volume scales reshape manufacturer-customer relationships across diagnostic, vaccine, and research channels.
- Diagnosis:Serological assay development for infectious disease detection including sepsis, Lyme disease, and tuberculosis. Reference laboratories in India and the United States are scaling automated immunoassay volumes, pulling through higher-grade antigen procurement with accelerated stability documentation.
- Vaccine Development:Immunogenicity testing and adjuvant formulation studies for preclinical and clinical candidate evaluation. CDSCO-registered contract manufacturers in India are capturing vaccine developer partnerships from European and North American sponsors seeking dual-source antigen security.
- Research:Fundamental immunology and pathogenesis studies with lower documentation burdens and smaller batch requirements.
- Therapeutic Use:Active immunotherapy and tolerization approaches still in early clinical validation with limited commercial antigen procurement.
Diagnosis commands the largest procurement volumes; Vaccine Development is climbing the fastest as mRNA and subunit platforms multiply immunogenicity testing requirements.
End User:
End user segmentation reflects how buyer concentration and technical specifications filter supplier qualification across institutional categories.
- Diagnostic Laboratories:Hospital networks and reference labs running automated immunoassay platforms at scale. North American integrated delivery networks are consolidating antigen purchasing through centralized contracts, privileging suppliers with multi-product catalogs and conjugation services.
- Pharmaceutical Companies:Large vaccine and therapeutic developers with internal antigen production or dedicated supplier relationships governed by quality agreements and FDA master files.
- Research Institutes:Academic and government laboratories with fragmented purchasing and lower purity requirements.
- Biotech Firms:Early-stage developers adopting cell-free synthesis and distributed production models to retain intellectual property control.
Diagnostic Laboratories represent the dominant revenue channel; Biotech Firms are gaining share fastest through distributed production adoption.
Delivery Mode:
Delivery mode segmentation captures formulation and stability requirements that differentiate supply chains for parenteral versus non-invasive antigen applications.
- Injectable:Liquid or lyophilized formulations for intramuscular, subcutaneous, or intravenous administration with stringent sterility and endotoxin specifications. Vaccine developers in Europe and North America dominate procurement, requiring GMP-compliant production with extensive lot-release documentation.
- Oral:Encapsulated or adjuvanted formulations for mucosal immunization with specialized stability requirements for gastrointestinal transit.
- Intranasal:Aerosolized or droplet formulations targeting nasal mucosa with device-dependent compatibility constraints.
- Transdermal:Microneedle or patch-based delivery systems with emerging demand from point-of-care diagnostic platforms in Southeast Asian health systems.
Injectable formulations retain the majority of manufacturing investment; Transdermal is expanding most quickly alongside point-of-care platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad's Genome Valley anchors the most concentrated bacterial antigen manufacturing corridor outside North America and Europe, with CDSCO-registered facilities supplying recombinant proteins to diagnostic kit assemblers across three continents.
United States
Hospital networks in Boston and the Research Triangle are consolidating antigen procurement through centralized reference laboratory contracts, displacing fragmented department-level purchasing. The FDA's tightened lot-release criteria for in vitro diagnostic components mandate expanded stability documentation that filters supplier qualification. San Diego's biotech cluster hosts early-stage vaccine developers adopting cell-free synthesis platforms to compress lead times from gene sequence to purified antigen.
Germany
Automated immunoassay volumes at Munich and Berlin hospital networks are scaling rapidly, pulling through higher-grade recombinant antigen procurement with accelerated endotoxin certification. The EMA's In Vitro Diagnostic Regulation mandates performance documentation that shapes how antigen suppliers structure clinical-validation investments for CE-marked market access. Heidelberg's life sciences corridor concentrates quality agreement negotiations between diagnostic reagent kit assemblers and GMP-compliant antigen producers.
India
Domestic biotech firms in Bangalore and Hyderabad are scaling recombinant antigen output to capture share from filtered overseas competitors in NABL-accredited laboratory supply chains. CDSCO import-registration requirements constrain which foreign manufacturers can supply diagnostic reagents to India's expanding hospital network. Pune's contract manufacturing cluster is capturing vaccine developer partnerships from European and North American sponsors seeking dual-source antigen security.
United Kingdom
Research institutes in Cambridge and Oxford are adopting synthetic peptide antigens for therapeutic antibody discovery, compressing workflows compared to recombinant protein timelines. The Medicines and Healthcare products Regulatory Agency aligns with EMA documentation standards for diagnostic-grade antigen importation. London's reference laboratory networks are consolidating supplier bases to partners with established quality agreement templates and multi-product catalogs.
Switzerland
Early-stage biotech firms in Basel and Zurich are converging on solid-phase peptide synthesis combined with computational epitope mapping for defined immunoreactivity profiles. Swissmedic maintains pharmacopeial standards for endotoxin and host-cell protein limits that reshape supplier qualification timelines. The country's precision manufacturing base supports stabilized, lyophilized antigen formulations for point-of-care diagnostic platforms targeting Southeast Asian and African health systems.
Bacterial Antigens Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the bacterial antigens supply base. GMP-compliant bioreactor operators maintain premium positioning through chromatography infrastructure and quality-control documentation, while catalog specialists compete on breadth and custom conjugation velocity. Three archetypes dominate: integrated diagnostic reagent suppliers, contract manufacturing organizations with regulatory registrations, and research-grade catalog distributors. Competitive moves concentrate on strategic partnerships for dual-source security and portfolio diversification into synthetic peptide capabilities.
Within the integrated diagnostic tier, Bio-Rad Laboratories and Microbix Biosystems exemplify capital-intensive positioning through chromatography and cGMP infrastructure. Creative Diagnostics occupies the catalog-specialist vector, competing on custom conjugation breadth. The Native Antigen Company and Jena Bioscience GmbH represent European-origin suppliers navigating EMA documentation requirements. SERION Immunologics and Enzo Life Sciences sit within the research-to-diagnostic bridge segment, where batch-to-batch consistency investments separate premium grades from commodity extracts.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| The Native Antigen Company |
| Creative Diagnostics |
| Microbix Biosystems |
| Ross Southern Laboratories |
| Enzo Life Sciences |
| SERION Immunologics |
| Jena Bioscience GmbH |
| QED Bioscience |
| Others |
Value Network & Pricing Analysis
Captive bioreactor operations at Hyderabad's CDSCO-registered facilities anchor both supply security and pricing power for recombinant bacterial antigens, compressing margin structures for competitors dependent on outsourced chromatography and third-party endotoxin testing. This integration pattern privileges manufacturers with in-house E. coli expression systems and affinity purification infrastructure, while forcing asset-light catalog distributors toward custom conjugation services to defend price positioning.
Pricing Analysis
Yield-based pricing anchors recombinant antigen contracts, with diagnostic-grade lots commanding premiums tied to batch-to-batch consistency metrics and automated immunoassay throughput guarantees. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified bioreactor output from research-grade extracts and commodity polyclonal sera. Cost compression in standard-grade recombinant production is intensifying because chromatography resin supply concentrates among North American and European chemical manufacturers. Hospital network procurement offices exhibit lowest price sensitivity due to consolidated reference laboratory contracts, while early-stage biotech firms drive hardest bargain negotiation for small-batch research grades.
Supply Chain Analysis
Regional distribution centers in Hyderabad, Boston, and Basel operate hub-and-spoke patterns for temperature-controlled antigen shipments, with lyophilized formulations enabling extended shelf-life inventory positioning closer to end-user laboratories. Manufacturing concentrates in India, the United States, and Germany, with CDSCO-registered facilities drawing from domestic E. coli strain banks and imported affinity resin stocks. Raw material dependencies center on protein A chromatography media, endotoxin-free water systems, and defined yeast extract formulations. Single-source vulnerability in chromatography resin supply creates concentration risk for mid-scale producers lacking multi-year supplier agreements. Distribution runs through diagnostic reagent kit assemblers and direct hospital network contracts rather than fragmented research-catalog channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory documentation burdens for FDA master files and EMA performance validation are forcing consolidation, eliminating antigen suppliers lacking capital for clinical-grade quality systems.
For Market Incumbents: Cement chromatography infrastructure advantages through backward integration into resin regeneration capabilities and captive endotoxin testing laboratories, defending against emerging cell-free synthesis platforms that threaten recombinant production timelines. Expand CDSCO-registered capacity in India to capture dual-source security contracts from European vaccine developers facing EMA supply-chain diversification mandates. For New Entrants and Emerging Players: Enter via synthetic peptide antigen specialization for therapeutic antibody discovery workflows, where solid-phase synthesis equipment requires lower capital than bioreactor infrastructure and computational epitope mapping creates differentiation against established recombinant catalogs. Target Swiss and Indian early-stage biotech firms with distributed production models seeking intellectual property control over batch records. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated diagnostic reagent suppliers seeking conjugation service capabilities and multi-product antigen catalogs. Long-term viability favors manufacturers with GMP-compliant bioreactor operations and established FDA quality agreements over research-grade catalog distributors facing margin compression. Watch for inflection when cell-free protein synthesis achieves cost parity with E. coli expression for sub-gram antigen batches.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Bioreactor Scale-Up | CDSCO-registered expansion in India captures European vaccine developer dual-source contracts. |
| Synthetic Peptide Capability Buildout | Solid-phase synthesis platforms serve Basel biotech firms compressing antibody discovery timelines. |
| Chromatography Infrastructure Integration | Captive resin regeneration reduces dependency on North American chemical manufacturers. |
| Point-of-Care Formulation Development | Lyophilized antigen stabilization opens Southeast Asian lateral flow diagnostic markets. |
| Regulatory Documentation Investment | FDA master file establishment qualifies suppliers for hospital network consolidated procurement. |
Research Methodology
Document review covered FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, and CDSCO import-registration databases, complemented by interviews with diagnostic reagent kit assemblers, GMP bioreactor operations managers, hospital procurement directors, and vaccine development executives. Secondary validation drew from SEC 10-K disclosures of listed antigen suppliers, NABL accreditation records, and pharmacopeial standards documentation. Bottom-up triangulation across production facility capacities and top-down reconciliation against end-user procurement volumes anchored market sizing.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across product type, application, end user, and delivery mode segmentation dimensions. CAGRs were derived from modeled annual growth increments across the projection horizon, with recombinant antigen batch consistency metrics and automated immunoassay platform deployment rates serving as key forecast inputs alongside regulatory documentation timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated cell-free synthesis adoption or sudden chromatography resin supply disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Lactic Acid Bacteria Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Antibiotic Resistance Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Global Microbiome Therapeutics Market