
 Global Microbial Testing Market | 2026-2036
Global Microbial Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microbial Testing Market Analysis
Aftermarket service revenue for microbial testing platforms is rewriting profit expectations across the diagnostic supply chain. bioMérieux leverages its installed base of automated culture systems to sustain recurring consumable income. Thermo Fisher Scientific anchors its position through backward integration into reagent manufacturing. Eurofins Scientific competes by extending its laboratory network into emerging biopharma clusters.
Microbial testing encompasses the detection, enumeration, and identification of bacteria, fungi, viruses, and other microorganisms in clinical, environmental, and industrial samples using cultural, molecular, immunological, or rapid methodological platforms. The practice relies on ATP bioluminescence thresholds, PCR cycle thresholds, and colony-forming unit counts to determine contamination levels against regulatory baselines. Reagents and consumables capture the dominant margin pool due to per-test disposability and formulation complexity, while molecular techniques represent the fastest-expanding technology segment as multiplex PCR and next-generation sequencing shorten turnaround times. Instruments remain a mature, capital-intensive category where placement strategies prioritize long-term reagent lock-in over hardware margins.
FDA sterility testing requirements under 21 CFR 610.12, EMA's Good Manufacturing Practice Annex 1 revisions, and ISO 11135 sterilization validation standards collectively elevate compliance spending across pharmaceutical and medical device supply chains. China's NMPA has tightened microbiological limits for imported biologics, forcing foreign manufacturers to establish local testing partnerships or captive laboratory capacity. Stakeholders must monitor regulatory divergence between FDA rapid-method validation pathways and EMA's more conservative equivalence demonstration requirements when allocating R&D budgets across geographies.
Market Dynamics
Regulatory divergence between FDA rapid-method validation pathways and EMA's equivalence demonstration requirements is fragmenting R&D allocation strategies across multinational diagnostic suppliers. This structural tension forces platform developers to maintain dual validation tracks or accept geographic market exclusion.
Growth Catalysts
- EMA Annex 1 Revisions:The updated Good Manufacturing Practice standards mandate enhanced environmental monitoring in sterile manufacturing facilities across European pharmaceutical production sites.
- Multiplex PCR Platforms:Clinical laboratories in the United States are replacing single-target assays with syndromic panels that detect 15-20 pathogens per respiratory sample simultaneously.
- China's NMPA Biologics Import Rules:Tightened microbiological limits for imported therapeutics compel foreign manufacturers to establish captive testing capacity or local laboratory partnerships.
Market Restraints
- Specialized Reagent Supply Concentration:Lyophilized PCR master mixes and sterile culture media depend on a limited supplier base concentrated in Germany and the United States.
- Capital Intensity of Automated Platforms:High-throughput microbial identification systems require seven-figure instrument investments that freeze out mid-sized contract testing laboratories.
- Validation Timeline Friction:FDA's comparability protocol requirements for rapid sterility methods extend time-to-market by 18-24 months versus traditional pharmacopeial approaches.
Strategic Opportunities
- India's Biopharma Manufacturing Expansion:CDSCO's tightening of microbiological standards for export-oriented facilities creates demand for local rapid testing infrastructure.
- Cell and Gene Therapy Ancillary Testing:Raw material qualification and in-process monitoring for viral vector production require specialized mycoplasma and adventitious agent detection services.
- Point-of-Use Environmental Monitoring:ATP bioluminescence systems are penetrating food processing lines in Brazil and Mexico where ANVISA enforcement is intensifying.
Industry Challenges
- Multidisciplinary Talent Scarcity:Platform developers struggle to hire professionals fluent in both bioinformatics pipeline construction and classical microbiology methodology.
- Legacy LIMS Integration Complexity:Molecular testing platforms must interface with decade-old laboratory information management systems that lack API connectivity.
- Proficiency Testing Participation Costs:CAP and UK NEQAS external quality assessment programs impose recurring fees that strain smaller diagnostic service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microbial Testing Market |
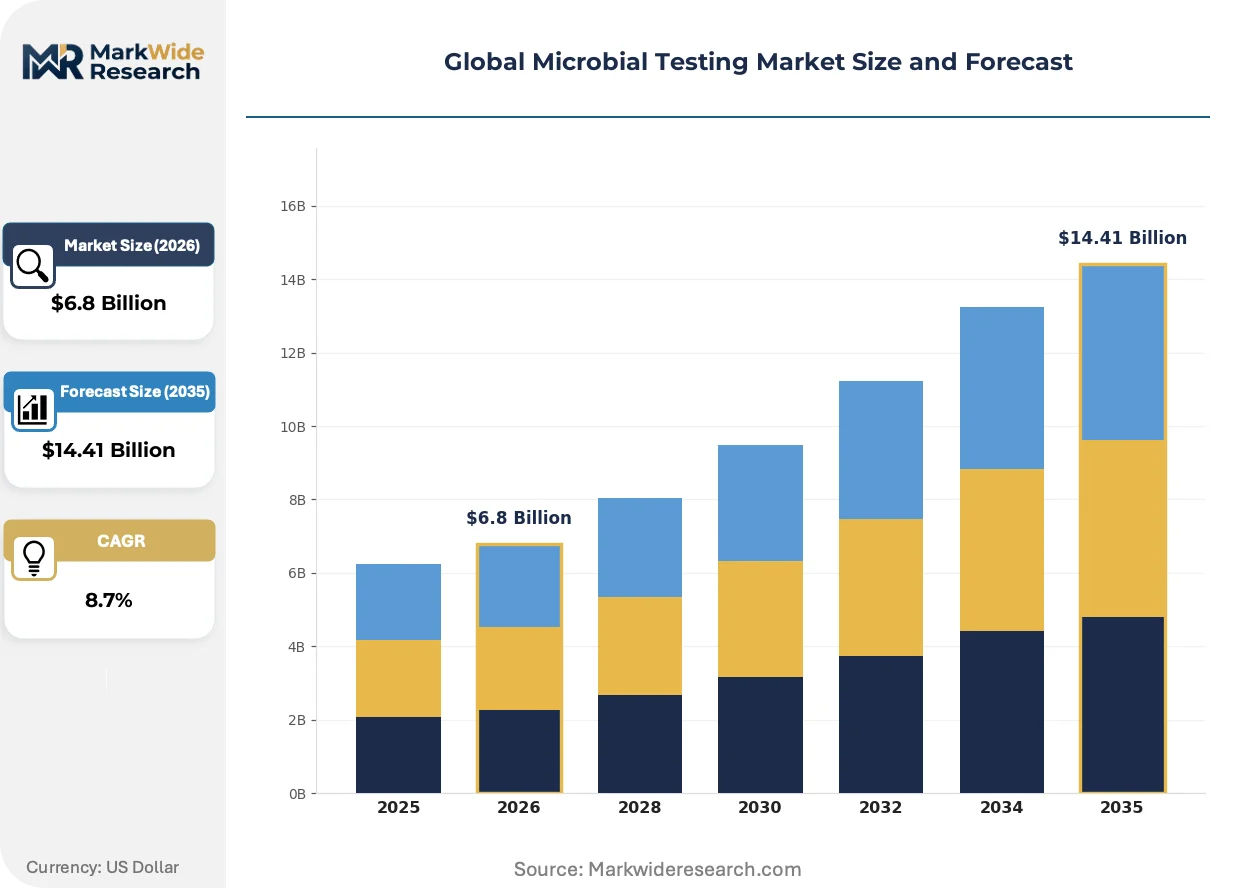
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Consumables, Software Application: Food Safety, Water Quality, Pharmaceutical Testing, Environmental Monitoring End User: Clinical Laboratories, Research Institutions, Agriculture, Food and Beverage Industry Technology: Cultural Techniques, Molecular Techniques, Immunological Techniques, Rapid Testing Methods |
| Companies Covered | TUV SUD, bioMérieux, SGS, Thermo Fisher Scientific, Danaher Corporation, Eurofins Scientific, ALS Limited, Sartorius, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microbial Testing Market Emerging Trajectories
Next-generation sequencing is collapsing the traditional taxonomy of microbial identification by delivering species-level resolution without culture-based isolation. This technological inflection is redrawing competitive boundaries between instrument manufacturers and bioinformatics service providers.
Whole-genome sequencing platforms are collapsing the turnaround time for outbreak investigation from weeks to days. Public health laboratories in the United States and United Kingdom are adopting this technology for foodborne pathogen surveillance. The compression of epidemiological response timelines is forcing culture-based reference laboratories to reposition toward niche applications.
FDA's 2023 guidance on validation of rapid microbiological methods is accelerating adoption of growth-based automated systems that reduce sterility testing from 14 days to 5-7 days. Pharmaceutical manufacturers are submitting comparability protocols to justify method replacement in stability and release testing programs. European facilities face slower adoption due to EMA's insistence on extensive side-by-side equivalence studies.
Consolidated procurement of testing services by multinational food retailers is displacing fragmented relationships with local laboratories. Chains operating across Germany, France, and Spain are mandating centralized data dashboards for supplier microbiological monitoring. This concentration is squeezing independent testing laboratories while rewarding Eurofins and SGS for their continental network density.
Global Microbial Testing Market Segmentation
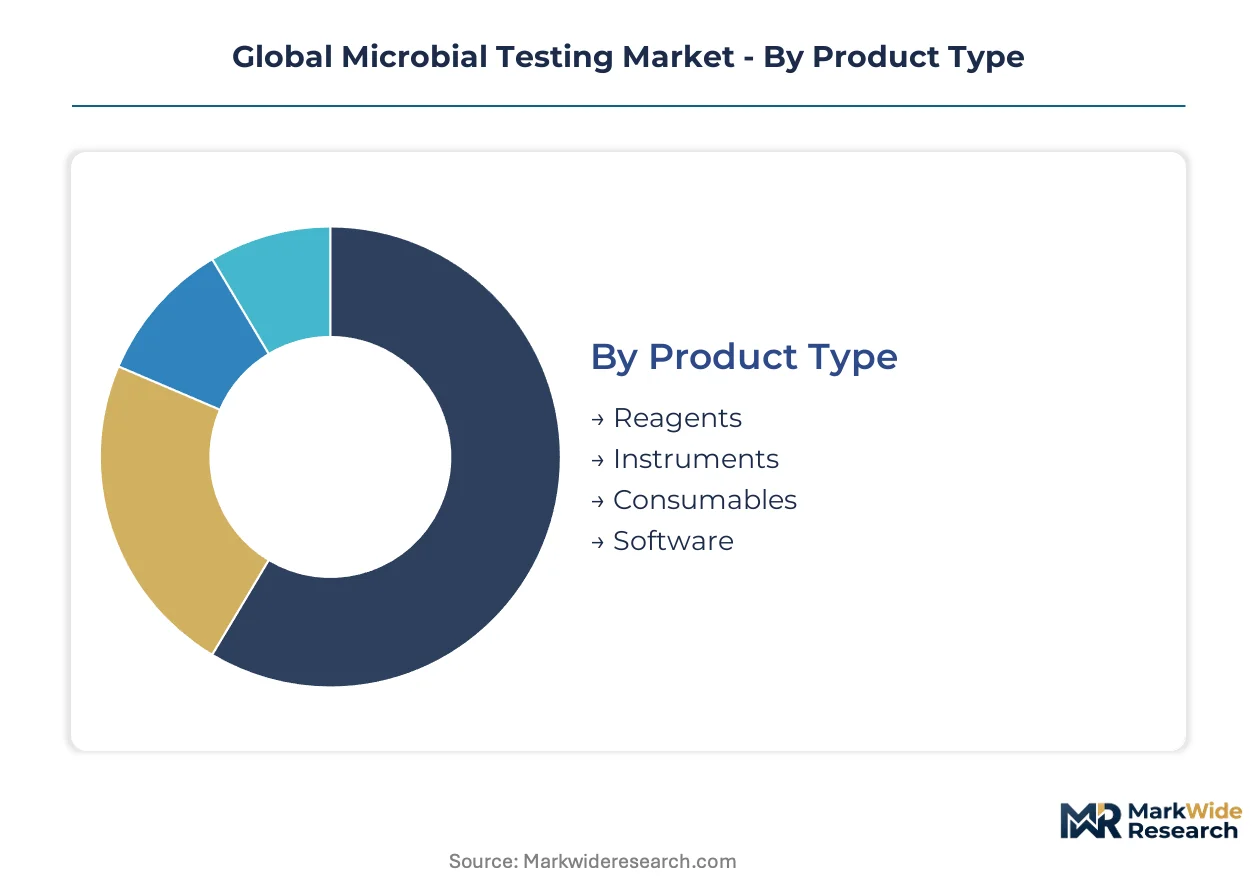
Microbial testing vendors engineer portfolio depth around recurring revenue intensity and capital deployment cycles. Product mix decisions balance instrument placement strategies against consumable pull-through economics across regulated end-use environments.
Product Type:
Reagents and consumables turn over in weeks, instruments amortize over seven to ten years, and software renews annually—creating divergent cash flow profiles across the supplier base.
- Reagents:Lyophilized PCR master mixes, selective culture media, and staining solutions constitute the highest-margin category due to formulation complexity and cold-chain dependency. Pharmaceutical manufacturers in Germany and the United States lock in multi-year supply agreements to secure lot-to-lot consistency for FDA and EMA compliance programs.
- Instruments:Automated culture systems, MALDI-TOF mass spectrometers, and flow cytometry platforms represent capital-intensive placements where vendors prioritize reagent lock-in over hardware margins. China's NMPA biologics import rules are accelerating instrument installations in Shanghai and Suzhou biopharma clusters.
- Consumables:Petri dishes, pipette tips, and collection swabs generate volume-driven revenue with lower per-unit margins but predictable replacement cycles.
- Software:Laboratory information management modules and bioinformatics pipelines for sequencing data interpretation capture recurring license fees.
Reagents dominate installed base economics. Instruments are where expansion concentrates for vendors seeking captive reagent demand.
Application:
Regulatory enforcement intensity varies sharply across use cases, with pharmaceutical and food safety applications commanding premium pricing for validated methods.
- Food Safety:Pathogen detection in meat, dairy, and produce supply chains relies on rapid ATP bioluminescence and PCR screening. ANVISA enforcement intensification across Brazilian processing facilities is displacing traditional culture-based approaches.
- Pharmaceutical Testing:Sterility testing, endotoxin detection, and mycoplasma screening for biologics production command the highest method validation standards. EMA Annex 1 revisions mandate enhanced environmental monitoring across European sterile manufacturing sites.
- Water Quality:Drinking water and wastewater analysis for coliforms and Legionella follows EPA and WHO guidelines with standardized cultural methods.
- Environmental Monitoring:Cleanroom validation and industrial hygiene testing support pharmaceutical and medical device production facilities.
Pharmaceutical testing commands premium pricing tiers. Food safety is climbing fastest on regulatory enforcement expansion.
End User:
Procurement sophistication diverges between centralized hospital networks and fragmented agricultural testing points.
- Clinical Laboratories:Hospital and reference labs in the United States drive multiplex PCR adoption for syndromic respiratory panels. Consolidated procurement by health systems is squeezing independent service providers.
- Food and Beverage Industry:Multinational retailers mandate centralized data dashboards across German, French, and Spanish supplier networks. Eurofins and SGS capture volume through continental network density.
- Research Institutions:Academic and government labs prioritize grant-funded instrument acquisitions with open reagent compatibility.
- Agriculture:Seed and soil testing for plant pathogens serves fragmented regional markets with price-sensitive demand.
Clinical laboratories anchor instrument placements. Food and beverage testing is where vendor consolidation accelerates.
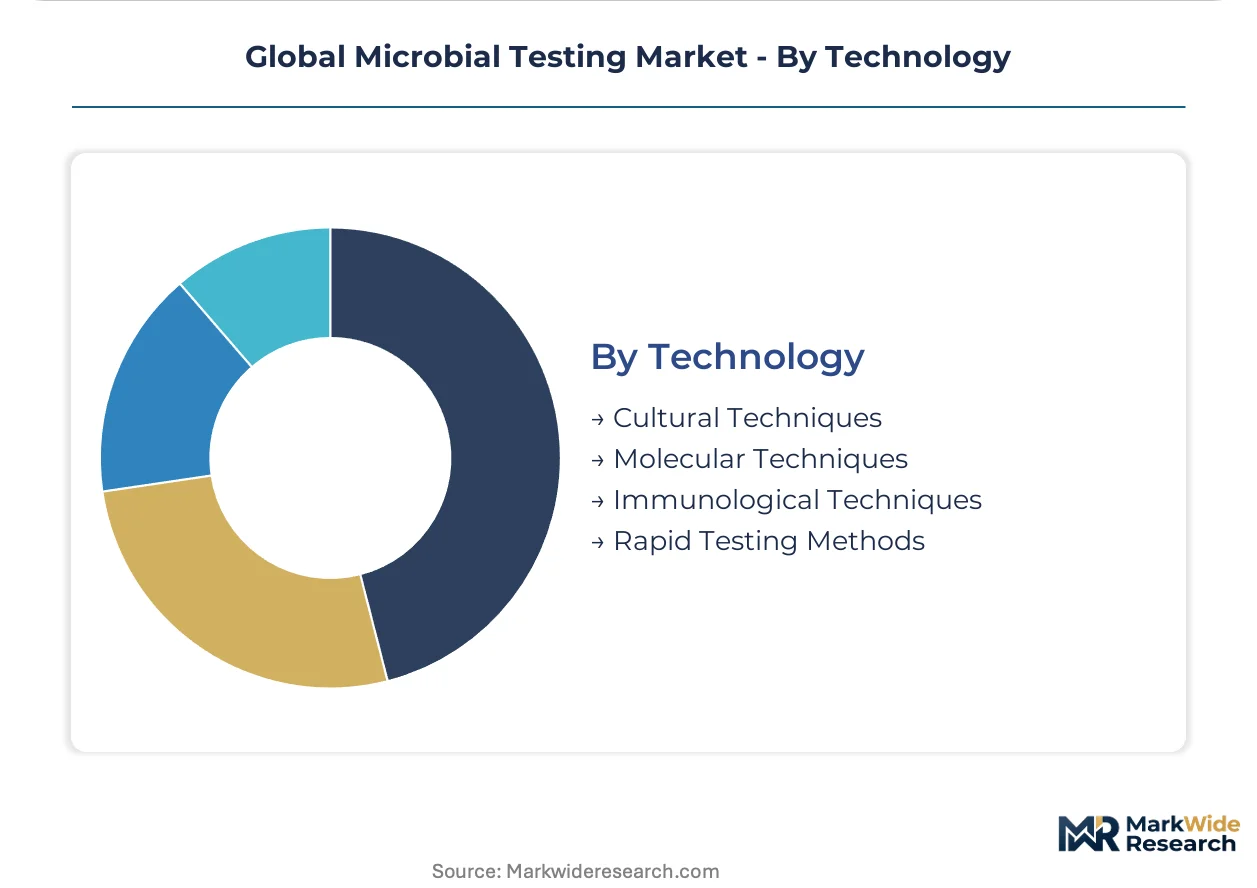
Technology:
Method selection trades turnaround time against regulatory acceptance, with molecular techniques expanding fastest where validation frameworks permit.
- Molecular Techniques:Multiplex PCR and next-generation sequencing deliver species-level resolution without culture isolation. FDA rapid-method validation pathways are accelerating adoption in United States pharmaceutical release testing.
- Rapid Testing Methods:ATP bioluminescence and immunoassay strips provide same-day results for environmental monitoring and food processing lines. Brazil and Mexico are penetrating fastest where ANVISA enforcement timelines compress.
- Cultural Techniques:Colony-forming unit counts and biochemical identification remain reference standards for regulatory submissions despite 14-day turnaround cycles.
- Immunological Techniques:ELISA and lateral flow assays serve niche applications where antibody specificity matches target pathogen profiles.
Cultural techniques dominate regulatory reference standards. Molecular techniques are expanding most quickly on validation pathway alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturers and reagent suppliers cluster in Germany, the United States, and China where regulatory enforcement creates captive demand for validated testing infrastructure. Quality control spending concentrates in jurisdictions with harmonized pharmacopeial standards and active biopharma manufacturing expansion.
United States
Multiplex PCR adoption accelerates in clinical laboratories serving consolidated health systems across the Northeast and California. FDA rapid-method validation pathways under 21 CFR 610.12 compress sterility testing timelines for pharmaceutical release programs. Boston and San Diego biopharma clusters drive demand for mycoplasma and adventitious agent detection services.
Germany
EMA Annex 1 revisions mandate enhanced environmental monitoring across sterile manufacturing facilities in Baden-Württemberg and Bavaria. German pharmaceutical exporters lock in multi-year reagent supply agreements to secure lot-to-lot consistency for global compliance programs. The Rhine-Main and Upper Bavaria regions anchor automated culture system installations serving contract manufacturing organizations.
China
NMPA tightening of microbiological limits for imported biologics compels foreign manufacturers to establish captive testing capacity in Shanghai and Suzhou. Domestic CDMO expansion in the Yangtze River Delta drives instrument placements for rapid sterility and endotoxin detection. Beijing-Tianjin-Hebei pharmaceutical corridors concentrate demand for environmental monitoring validation services.
India
CDSCO enforcement of microbiological standards for export-oriented biopharma facilities creates demand for rapid testing infrastructure in Hyderabad and Bengaluru. Contract research organizations in Maharashtra and Gujarat upgrade from traditional culture-based methods to ATP bioluminescence and PCR platforms. The Genome Valley cluster anchors specialized mycoplasma detection service expansion.
Brazil
ANVISA intensification of food processing facility inspections accelerates ATP bioluminescence penetration in São Paulo and Minas Gerais meat and dairy operations. Multinational retailers mandate centralized microbiological monitoring dashboards across their Brazilian supplier networks. The São Paulo state industrial corridor concentrates rapid environmental testing platform deployments.
Global Microbial Testing Market Vendor Landscape
Full-service testing conglomerates and specialized diagnostic platform developers split the market along the fault line of captive laboratory networks versus instrument-reagent ecosystems. The vendor base organizes into three strategic archetypes: multinational laboratory networks with continental coverage, integrated life science conglomerates with backward reagent manufacturing control, and focused instrument manufacturers pursuing reagent lock-in through placement strategies. Consolidation pressures intensify as food retailers centralize procurement and pharmaceutical manufacturers demand single-source validation accountability.
Within the full-service laboratory tier, Eurofins Scientific and SGS exemplify network-density competitive positioning through continental European and Latin American facility footprints. bioMérieux and Thermo Fisher Scientific occupy the integrated platform-developer segment, leveraging installed bases of automated systems to sustain recurring consumable revenue streams. Danaher Corporation sits within the life science tools conglomerate archetype, anchoring diversified exposure across diagnostic and bioprocessing applications.
| Leading Market Players |
|---|
| TUV SUD |
| bioMérieux |
| SGS |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Eurofins Scientific |
| ALS Limited |
| Sartorius |
| Intertek Group |
| Others |
Supply Flow & Price Mechanics
Shanghai and Suzhou biopharma clusters concentrate instrument manufacturing capacity for automated culture systems, translating upstream supply control into downstream pricing leverage for vendors serving NMPA-compliant facilities. Foreign manufacturers establishing captive testing laboratories in these zones absorb premium placement costs to secure long-term reagent lock-in contracts.
Pricing Analysis
Aftermarket consumable revenue streams dominate lifetime value economics across microbial testing platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation grade and regulatory certification tier. Cost compression in economy-tier reagents is intensifying because contract manufacturers in India and Brazil negotiate volume-scale discounts. Mid-sized contract testing laboratories exhibit highest price sensitivity, while multinational pharmaceutical manufacturers prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for lyophilized PCR master mixes and sterile culture media. Manufacturing concentrates in Germany, the United States, and China, with formulation expertise anchored in Rhine-Main and Boston biotech corridors. Raw material sourcing draws from specialty chemical suppliers in Switzerland and Japan for chromogenic substrates and fluorescent dyes. Distribution runs through cold-chain logistics networks serving pharmaceutical manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
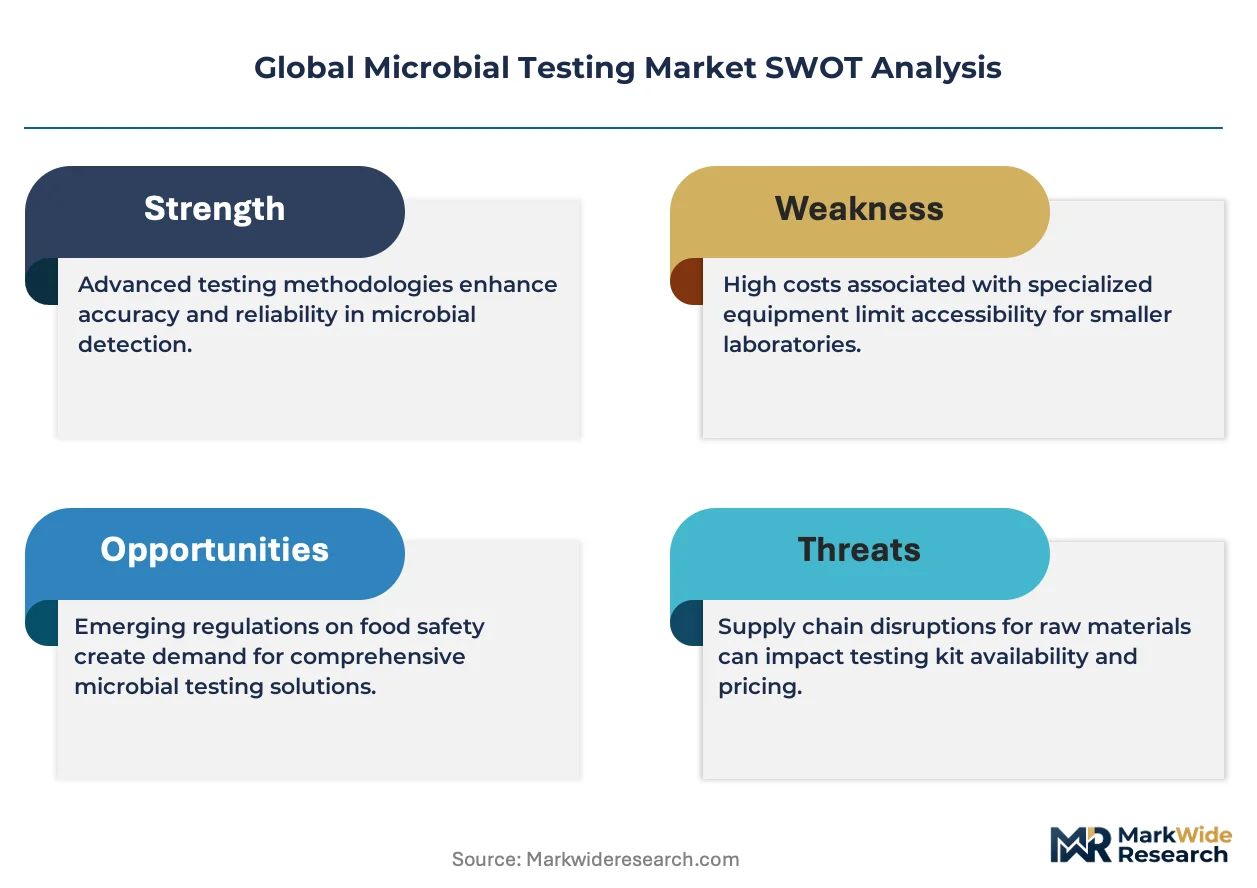
This market functions as a defensive-moat story. Regulatory entrenchment creates sticky customer relationships where validation protocol switching costs exceed platform replacement economics.
For Market Incumbents: Pre-empt emerging molecular platform entrants by accelerating backward integration into proprietary reagent manufacturing. Expand instrument placement density in Hyderabad and Bengaluru CDSCO-regulated facilities before local competitors achieve validation equivalence. Certification investment in dual FDA-EMA comparability protocols preserves geographic optionality against regulatory divergence. For New Entrants and Emerging Players: Point-of-use environmental monitoring in Brazilian and Mexican food processing lines represents the most penetrable entry point. ATP bioluminescence systems for ANVISA-inspected meat and dairy operations face lower capital barriers than pharmaceutical sterility platforms. Partner with regional distributors possessing established relationships with multinational retailer procurement committees. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because consumable pull-through economics compound across seven-to-ten-year instrument lifecycles. Acquisition targets should display dense installed bases of automated platforms with locked-in reagent supply agreements. Monitor FDA rapid-method validation submission volumes as inflection indicator for molecular technique adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Manufacturing Backward Integration | Captures margin pool from lyophilized PCR master mixes and selective culture media formulations. |
| Dual Regulatory Validation Investment | Secures market access across FDA rapid-method pathways and EMA equivalence demonstration requirements. |
| Geographic Expansion into India Biopharma Clusters | Positions for CDSCO enforcement tightening across Hyderabad and Bengaluru export-oriented facilities. |
| Point-of-Use Environmental Monitoring Launch | Penetrates Brazilian and Mexican food processing lines where ANVISA enforcement compresses testing timelines. |
| Cell and Gene Therapy Ancillary Testing Partnership | Captures mycoplasma and adventitious agent detection demand from viral vector production workflows. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with diagnostic platform developers, contract laboratory operations directors, and pharmaceutical quality control executives; and secondary validation through FDA 21 CFR filings, EMA GMP Annex 1 revision documents, and NMPA biologics import rule publications. Bottom-up triangulation across instrument placement databases and reagent shipment records intersected with top-down spending estimates from pharmacopeial compliance budget surveys.
Forecast inputs span product type segmentation, application intensity across pharmaceutical and food safety verticals, technology adoption curves for molecular versus cultural methods, and end-user procurement sophistication tiers. Modeled CAGRs derive from regression analysis of historical instrument installation rates and consumable pull-through coefficients. Regulatory enforcement timelines and biopharma manufacturing expansion trajectories in China and India serve as demand-side anchor inputs.
Practitioners should monitor FDA rapid-method validation submission volumes, EMA equivalence study completion rates, and NMPA biologics import inspection intensity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Microbial Lipase Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Mycoplasma Plate Antigens Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Microbial Biosurfactants Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Industrial Bioprocessing Market
Industrial Microbiology
Molecular Microbiology Market