
 Industrial Microbiology Market | 2026-2036
Industrial Microbiology Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Microbiology Market Intelligence
Buyer concentration is rebalancing as mid-sized biotechnology firms fragment demand previously held by top-ten pharmaceutical houses. Thermo Fisher Scientific leverages its analytical tools portfolio to serve this expanding mid-market tier. Danaher Corporation anchors its position through fermentation technology instrumentation. bioMérieux SA specializes in rapid microbial detection systems for quality-conscious contract manufacturers.
Industrial microbiology applies microbial physiology, genetic engineering, and bioprocess engineering to cultivate bacteria, yeast, and filamentous fungi at scales from laboratory flasks to stirred-tank bioreactors exceeding 10,000 liters, primarily to manufacture enzymes, vaccines, and active pharmaceutical ingredients. Bioprocessing equipment commands the largest installed base while synthetic biology platforms capture the fastest expansion in R&D spending. Quality control applications in pharmaceuticals and food safety generate the deepest margin pools due to regulatory compliance mandates.
The FDA enforces sterility assurance and microbial limits testing through current Good Manufacturing Practice guidelines, while the EMA's Annex 1 revision tightens contamination control expectations for European manufacturers. ISO 17025 accreditation requirements for microbiology laboratories shape vendor selection criteria across both regions. Stakeholders must monitor how synthetic biology standards evolve to determine capital allocation between traditional fermentation and cell-free production platforms.
Market Dynamics
The FDA's updated guidance on rapid microbial methods is compressing technology replacement cycles across pharmaceutical quality control laboratories, forcing capital reallocation toward automated detection platforms and away from traditional compendial methods.
Growth Catalysts
- EMA Annex 1 Revision:The tightened contamination control expectations for sterile manufacturing are mandating environmental monitoring upgrades across European biopharmaceutical facilities.
- Cell and Gene Therapy Expansion:Advanced therapy medicinal products require specialized microbial safety testing protocols that exceed standard pharmacopeial requirements.
- Munich-Heidelberg Corridor Concentration:Germany's biopharmaceutical cluster is generating concentrated demand for contract microbiology testing services.
Market Restraints
- Specialized Media Cost Volatility:Chromogenic and selective culture media formulations depend on petrochemical-derived substrates subject to input price swings.
- Single-Source Reagent Dependency:Critical enzymes and reference strains for molecular microbial identification concentrate with limited qualified suppliers.
- Validation Timeline Friction:FDA's comparability protocol requirements for alternative microbiological methods extend implementation cycles beyond typical capital planning horizons.
Strategic Opportunities
- India CDMO Penetration:Contract development and manufacturing organizations in Hyderabad and Bengaluru are building microbiology capabilities to serve export markets.
- ISO 17025 Accreditation Tailwind:Third-party laboratory certification mandates in food safety and environmental testing are expanding addressable market for qualified service providers.
- AI-Enabled Colony Counting Convergence:Machine vision algorithms integrated with automated plate handling systems are reducing analyst subjectivity in quality control workflows.
Industry Challenges
- Microbial Taxonomist Shortage:Specialized expertise in phenotypic and genotypic identification methods is contracting as academic training programs pivot to molecular biology.
- GMP Facility Retrofit Intensity:Containment upgrades for Biosafety Level 2-plus operations require significant cleanroom infrastructure investment.
- Legacy LIMS Integration Complexity:New rapid microbial detection platforms must interface with validated laboratory information management systems through custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Microbiology Market |
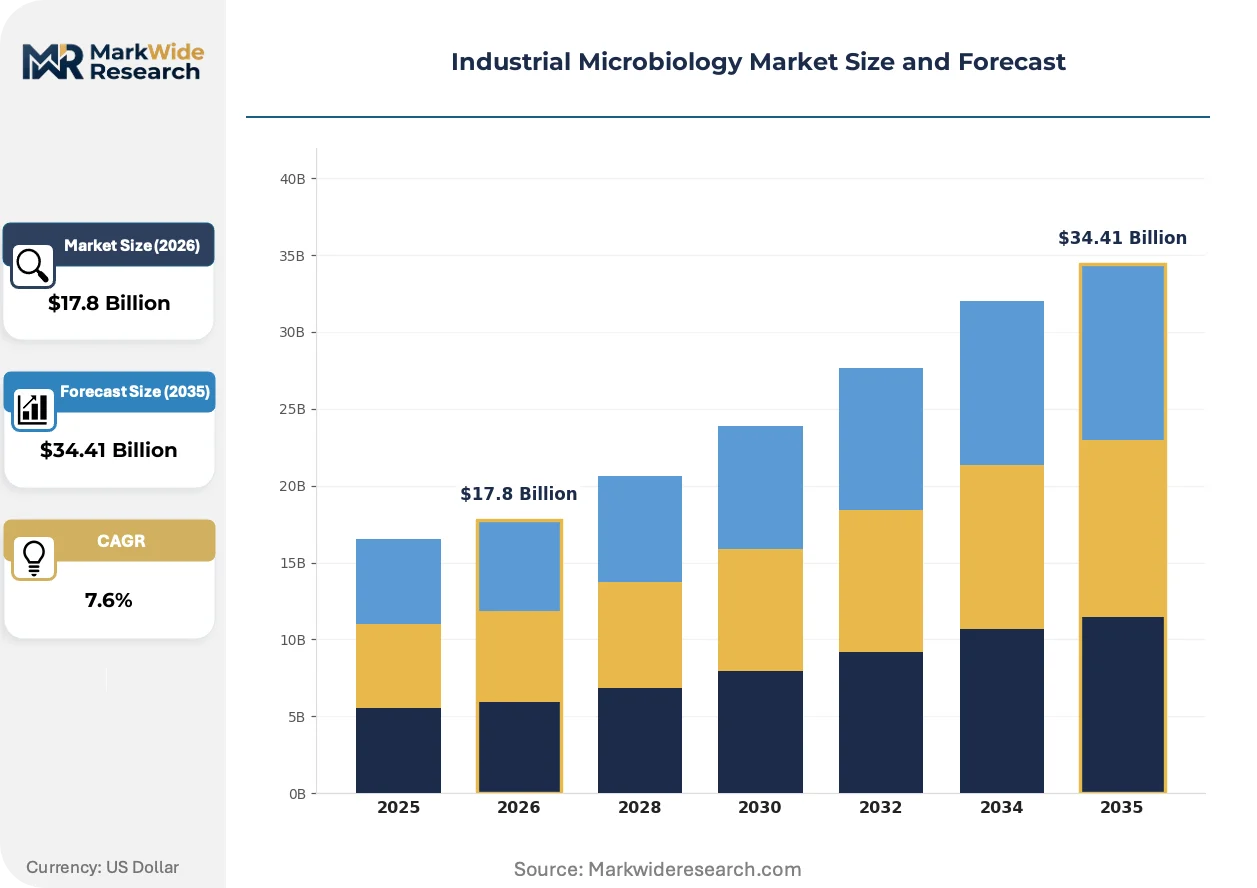
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $34.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioprocessing, Fermentation Technology, Cell Culture, Analytical Tools End User: Pharmaceuticals, Food & Beverage, Biotechnology, Agriculture Application: Bioproduction, Waste Management, Biofuels, Quality Control Technology: Genetic Engineering, Synthetic Biology, Microbial Analysis, Bioreactor Systems |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, bioMérieux SA, Becton Dickinson and Company, Bio-Rad Laboratories Inc., Sartorius AG, Merck KGaA, 3M Company, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Microbiology Market Strategic Shifts & Innovations
Automation and digitalization are converging to transform microbial detection from manual benchwork into integrated, data-rich workflows that compress release timelines and reduce human error in regulated environments.
Next-generation sequencing platforms for microbial identification are unifying taxonomic resolution with strain-level characterization in a single analytical run. Pharmaceutical quality control laboratories are adopting these systems for environmental monitoring and contamination investigation. This capability consolidation is compressing the timeline from detection to root-cause determination.
EMA's Annex 1 revision on sterile medicinal products is mandating proactive contamination control strategies rather than reactive testing regimes. Manufacturers must now implement continuous environmental monitoring with alert and action limits based on trend analysis. Aseptic processing facilities in Ireland, Belgium, and the Netherlands are investing in real-time viable particle counters to satisfy the new expectation.
Service unbundling is fragmenting the traditional full-service laboratory model. Biopharmaceutical sponsors are separating method development, routine testing, and regulatory submission support across specialized providers. This procurement pattern is most pronounced among mid-sized biotechnology firms in the Boston and San Diego clusters seeking flexibility without captive laboratory investment.
Industrial Microbiology Market Segmentation
Technology replacement cycles and regulatory compliance mandates are fragmenting procurement patterns across industrial microbiology segments. Pharmaceutical quality control laboratories now source specialized capabilities from distinct vendor tiers rather than consolidated full-service providers.
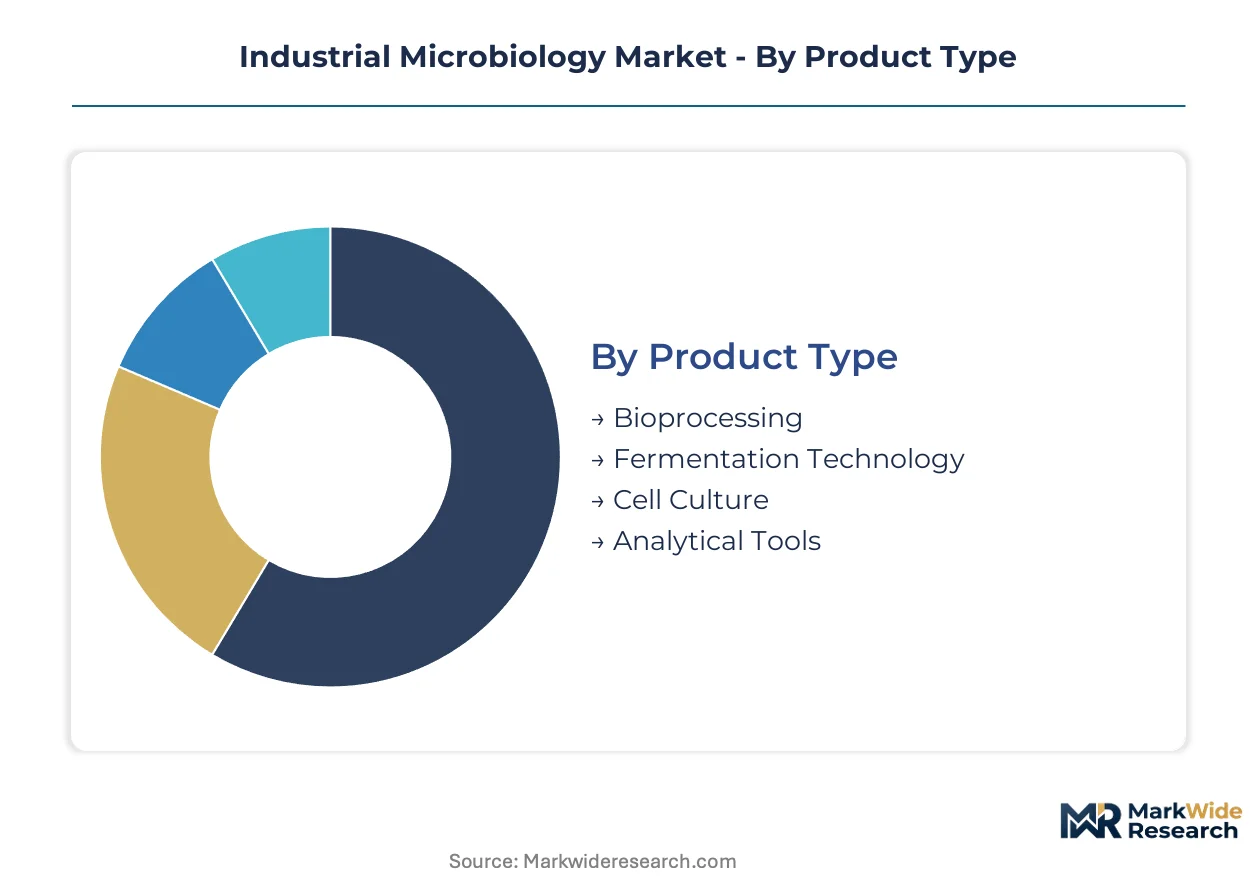
Product Type:
Upgrade intensity varies sharply across equipment categories as facilities balance automation gains against validation burdens.
- Bioprocessing:Stirred-tank and single-use bioreactor systems form the production backbone for enzymes and active pharmaceutical ingredients. Demand concentrates in Germany's Munich-Heidelberg corridor where contract manufacturers are expanding microbial production capacity for export markets.
- Fermentation Technology:Instrumentation for aerobic and anaerobic cultivation spans laboratory scale through industrial volumes exceeding 10,000 liters. Danaher Corporation anchors this segment through process analytical technology integration, with buyers prioritizing real-time biomass monitoring to compress batch release timelines.
- Cell Culture:Mammalian and microbial cultivation media systems support therapeutic protein manufacturing.
- Analytical Tools:Spectroscopy and chromatography platforms enable metabolite quantification and purity verification.
Bioprocessing sits at the top of the volume ranking, with fermentation technology climbing the fastest.
End User:
Customer scale determines procurement sophistication, with mid-tier biotechnology firms fragmenting demand patterns previously dominated by top-ten pharmaceutical houses.
- Pharmaceuticals:Sterile manufacturing and vaccine production drive the deepest margin pools through FDA-enforced current Good Manufacturing Practice compliance. Quality control applications command premium pricing as manufacturers replace traditional compendial methods with rapid microbial detection platforms.
- Food & Beverage:Pathogen detection and spoilage organism monitoring operate under ISO 17025 accreditation mandates. Third-party laboratory certification requirements in the European Union are expanding addressable market for qualified service providers.
- Biotechnology:Cell and gene therapy developers require specialized microbial safety testing protocols.
- Agriculture:Biofertilizer and biocontrol product developers utilize microbial strain screening capabilities.
Pharmaceuticals captures the largest revenue concentration, with biotechnology expanding most quickly.
Application:
Regulatory scrutiny intensity separates margin tiers, with compliance-mandated testing commanding structural premiums over discretionary R&D applications.
- Bioproduction:Microbial cultivation for enzyme, vaccine, and therapeutic protein manufacturing operates at scales from laboratory flasks to industrial bioreactors. Synthetic biology platforms are capturing the steepest expansion trajectory in R&D spending as developers optimize strain performance.
- Quality Control:Environmental monitoring and contamination detection for sterile manufacturing facilities face tightened EMA Annex 1 revision requirements. Irish and Belgian aseptic processing sites are investing in real-time viable particle counters to satisfy proactive contamination control mandates.
- Waste Management:Bioremediation and anaerobic digestion applications utilize specialized consortia.
- Biofuels:Algal and bacterial systems for renewable fuel production require strain optimization.
Quality Control dominates margin capture, with bioproduction gaining share fastest.
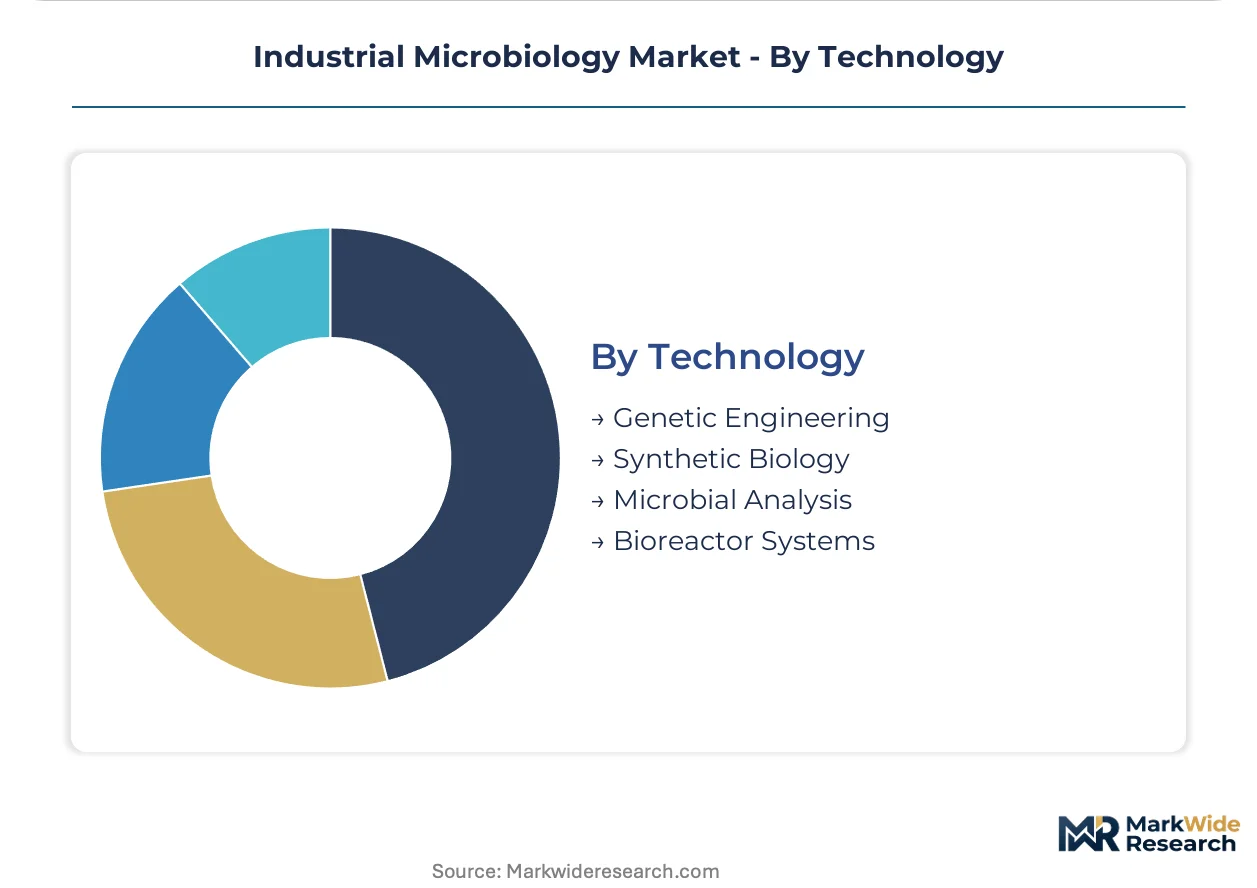
Technology:
Capability convergence is unifying previously separate analytical workflows while creating integration complexity with legacy laboratory information management systems.
- Genetic Engineering:CRISPR-based strain optimization and metabolic pathway engineering accelerate product yield improvements. Academic training program pivots toward molecular biology are contracting specialized microbial taxonomist availability.
- Microbial Analysis:Next-generation sequencing platforms unify taxonomic resolution with strain-level characterization in single analytical runs. Pharmaceutical quality control laboratories in the United States are adopting these systems to compress contamination investigation timelines.
- Synthetic Biology:Cell-free production platforms and automated design-build-test cycles.
- Bioreactor Systems:Process control automation and scale-up modeling software.
Microbial analysis leads installed base expansion, with synthetic biology posting the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates bioprocessing demand through its Munich-Heidelberg corridor while the United States drives rapid microbial method adoption through FDA regulatory pressure. India and China are expanding contract manufacturing capabilities to capture export market share.
United States
Pharmaceutical quality control laboratories are replacing traditional compendial methods with automated detection platforms under FDA rapid microbial methods guidance. The agency's comparability protocol requirements extend validation timelines but accelerate technology replacement cycles. Boston and San Diego biotechnology clusters fragment procurement patterns across specialized service providers.
Germany
The Munich-Heidelberg biopharmaceutical corridor generates concentrated demand for fermentation technology instrumentation and contract microbiology testing services. EMA Annex 1 revision mandates proactive contamination control strategies with continuous environmental monitoring. Aseptic processing facilities in Ireland and Belgium are investing in real-time viable particle counters to satisfy tightened expectations.
India
Contract development and manufacturing organizations in Hyderabad and Bengaluru are building microbiology capabilities to serve European and North American export markets. The country's national pharmaceutical regulator enforces current Good Manufacturing Practice compliance for sterile manufacturing exports. ISO 17025 accreditation requirements are expanding third-party laboratory certification mandates in food safety testing.
China
Synthetic biology platforms are capturing expanded R&D spending as developers optimize microbial strain performance for enzyme and therapeutic protein production. The national medical products administration oversees sterility assurance requirements for biopharmaceutical manufacturing. Yangtze River Delta biopharmaceutical clusters are integrating next-generation sequencing platforms for environmental monitoring applications.
Japan
Cell and gene therapy developers require specialized microbial safety testing protocols that exceed standard pharmacopeial requirements. The Pharmaceuticals and Medical Devices Agency regulates advanced therapy medicinal products through dedicated guidance frameworks. Kanto and Kansai pharmaceutical manufacturing regions are adopting process analytical technology integration for real-time biomass monitoring.
Industrial Microbiology Market Key Industry Players
United States producers anchor the analytical tools and rapid detection tier; European specialists hold fermentation technology and quality control instrumentation positions. The vendor base separates into consolidated full-service conglomerates, mid-market technology integrators, and niche rapid detection specialists. Three archetypes dominate: diversified life science conglomerates with broad analytical portfolios, precision fermentation instrumentation houses, and rapid microbial detection pure-plays. Competitive moves center on portfolio diversification through analytical capability acquisition and geographic expansion into Indian and Chinese contract manufacturing markets.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify the integrated analytical-to-bioprocessing archetype, while bioMérieux SA occupies a position within rapid microbial detection specialization. These three entities represent distinct strategic postures across the technology replacement cycle: conglomerate breadth, fermentation process control depth, and quality control automation focus.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| bioMérieux SA |
| Becton Dickinson and Company |
| Bio-Rad Laboratories Inc. |
| Sartorius AG |
| Merck KGaA |
| 3M Company |
| QIAGEN |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between ISO 17025-accredited laboratories and uncertified testing providers manifests in pricing premiums exceeding standard analytical services while concentrating supply relationships with qualified reagent manufacturers in Germany and the United States. This bifurcation shapes procurement patterns as pharmaceutical quality control laboratories prioritize validated supply chains over cost minimization.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard culture media and consumables while premium rapid microbial detection platforms maintain pricing power through FDA validation requirements. Pricing stratifies across validated rapid methods, automated compendial systems, and manual bench procedures based on regulatory acceptance tier and integration complexity with legacy LIMS infrastructure. Cost compression in commodity reagents is intensifying because contract manufacturers in Hyderabad and Bengaluru are expanding in-house production capabilities. Mid-sized biotechnology firms in Boston and San Diego clusters demonstrate highest price sensitivity, whereas top-ten pharmaceutical houses prioritize compliance assurance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with chromogenic substrate suppliers in Germany and reference strain repositories in the United States, creating concentration risk for critical quality control inputs. Manufacturing of specialized fermentation instrumentation draws from precision engineering clusters in Germany, Switzerland, and Japan, while petrochemical-derived culture media substrates feed from integrated chemical producers in the United States and Belgium. Regulatory restriction risk centers on EMA Annex 1 revision compliance requirements that disqualify non-validated supply sources. Distribution runs through authorized distributor networks for analytical instrumentation and direct procurement channels for consumables and reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as EMA Annex 1 revision mandates drive demand-shift toward continuous environmental monitoring systems with proactive contamination control specifications.
For Market Incumbents: Anticipate substitution pressure from AI-enabled colony counting platforms by accelerating middleware development for legacy LIMS integration and securing exclusive supply agreements with chromogenic substrate manufacturers. Defensive consolidation through acquisition of rapid microbial detection pure-plays preserves positioning against automated platform entrants. Certification investment in ISO 17025-accredited service capabilities anchors channel control for European pharmaceutical quality control procurement. For New Entrants and Emerging Players: Begin with specialized microbial safety testing protocols for cell and gene therapy developers in the Boston cluster, where service unbundling fragments procurement across method development, routine testing, and regulatory submission support. The most penetrable white-space sits with mid-sized biotechnology firms seeking flexibility without captive laboratory investment. A go-to-market angle emphasizing compressed contamination investigation timelines through next-generation sequencing platforms differentiates against established compendial method providers. For Investors and Strategic Acquirers: Consolidation pressure builds where validation timeline friction extends beyond typical capital planning horizons, stranding smaller rapid detection specialists without FDA comparability protocol expertise. Long-term viability favors precision fermentation instrumentation houses with process analytical technology integration capabilities and quality control automation specialists with EMA Annex 1 revision-ready product portfolios. The signal to watch is synthetic biology platform R&D spending trajectories as developers optimize strain performance, determining capital allocation between traditional fermentation and cell-free production systems.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA comparability protocol submission accelerates rapid microbial method adoption in pharmaceutical quality control laboratories. |
| Backward Integration | In-house chromogenic substrate production reduces petrochemical-derived input price volatility exposure for culture media manufacturers. |
| Platform Integration | Machine vision algorithms integrated with automated plate handling systems reduce analyst subjectivity in environmental monitoring workflows. |
| Acquisition of Specialist Firm | Rapid microbial detection pure-plays with validated LIMS middleware capture premium positioning in technology replacement cycles. |
| Geographic Expansion | Contract microbiology testing capabilities in Hyderabad and Bengaluru serve European and North American export market demand. |
Research Approach
Coverage spans the United States, Germany, India, China, and Japan, with primary inputs from each region combining structured interviews with regulatory affairs leads at pharmaceutical manufacturers, quality control laboratory directors, fermentation technology procurement managers, and contract manufacturing organization executives with secondary validation. Sources include FDA guidance documents, EMA Annex 1 revision texts, ISO 17025 accreditation records, and customs trade data for bioprocessing equipment. Bottom-up and top-down triangulation cross-validates segment-level demand against aggregate market sizing.
Rate-of-change decomposition separates volume expansion from value capture across the analysis window, modeling technology replacement intensity, regulatory compliance mandate timing, and synthetic biology R&D trajectory. Segmentation dimensions include product type tier, end-user scale archetype, application regulatory scrutiny level, and technology capability convergence. CAGRs derive from installed base evolution, upgrade cycle compression factors, and pricing power persistence in quality control applications. Industry-specific forecast inputs incorporate EMA Annex 1 implementation timelines and FDA rapid microbial methods guidance adoption curves.
Caveats apply where synthetic biology standards evolution or cell-free production platform maturation could materially shift capital allocation between traditional fermentation and alternative bioproduction systems, revisiting demand assumptions for stirred-tank and single-use bioreactor installed base expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Microbial API Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Automated Microbiology Market