
 Microbial Protein Used in Feed Market | 2026-2036
Microbial Protein Used in Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Protein Used in Feed Market Foresight
Denmark's industrial fermentation cluster is reshaping supply geography for bacterial protein used in European aquafeed. Calysta, Inc. leverages its methane-to-protein platform to anchor production scale in the North American market. ENOUGH (3F Bio Ltd.) sustains integrated fermentation and downstream processing capabilities that differentiate its fungal protein offerings. Nutreco N.V. competes through controlled distribution channels linking microbial protein directly into compound feed formulations.
Microbial protein used in feed comprises dried biomass of bacteria, yeast, fungi, or algae cultivated via submerged fermentation or gas fermentation, typically containing 50-80% crude protein with favorable amino acid profiles for monogastric and ruminant nutrition. Its primary commercial purpose is to displace conventional protein sources such as fishmeal, soybean meal, and rendered animal proteins in formulated feeds. Single cell protein dominates volume due to established fermentation infrastructure and consistent nutritional standardization across poultry and swine rations. Aquafeed represents the fastest-growing end use as salmon and shrimp producers face mounting fishmeal substitution pressures. Dry powder form leads margin pools because of extended shelf stability and lower logistics costs relative to liquid alternatives.
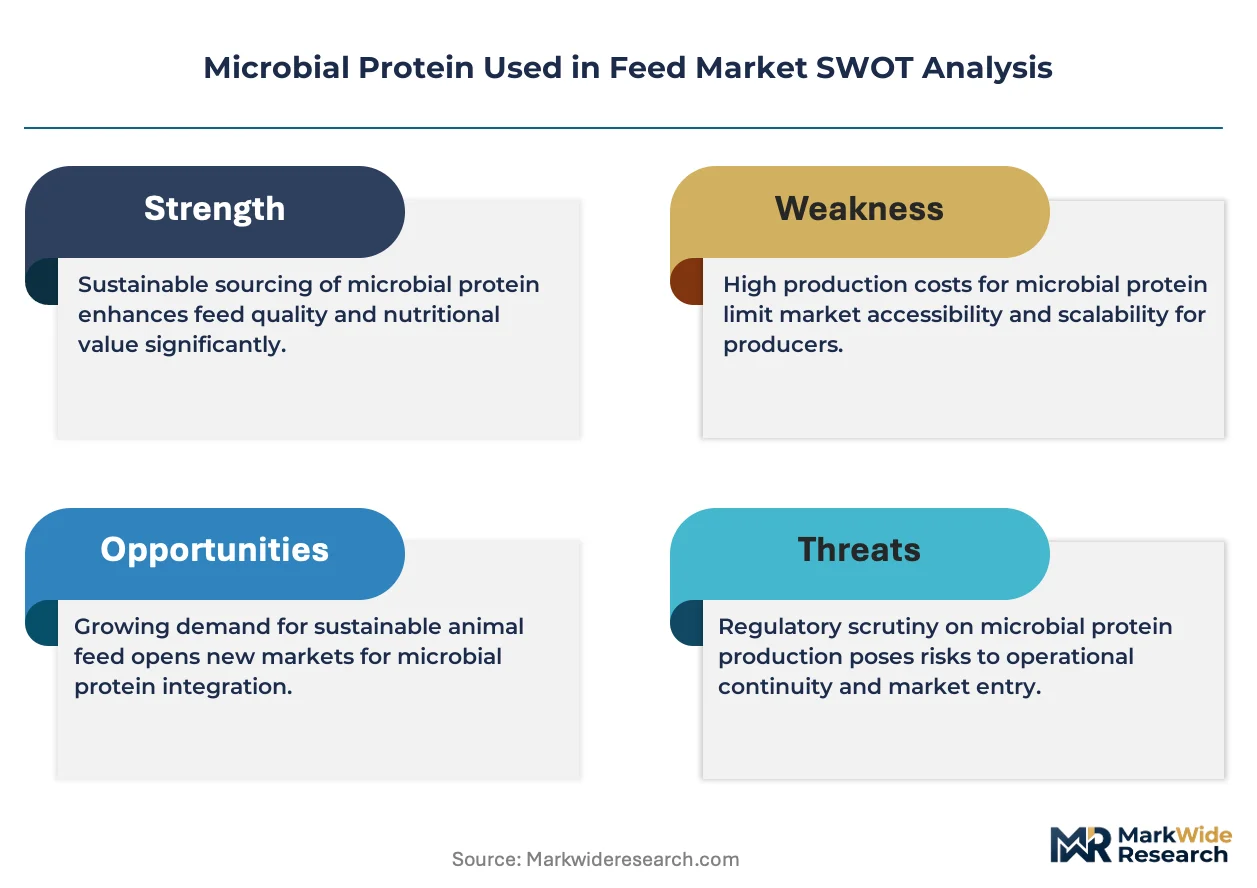
The EU Green Deal and F-Gas Regulation shape microbial protein demand by incentivizing low-carbon feed ingredients and restricting conventional protein sourcing emissions. EFSA novel food and feed approval pathways determine market access timelines for bacterial and fungal protein strains entering European supply chains. FDA and USDA oversight in the United States governs fermentation substrate safety and labeling for microbial protein in livestock and aquaculture feeds. Stakeholders must monitor regulatory divergence between jurisdictions as a decisive factor for cross-border product registration and capital deployment sequencing.
Market Dynamics
Fishmeal substitution mandates from aquafeed buyers are compressing protein sourcing timelines and forcing fermentation capacity expansion along coastal industrial corridors. This structural pressure is redrawing supply geography toward methane-rich industrial zones and nitrogen-accessible port infrastructure.
Growth Catalysts
- EU Green Deal protein autonomy targets:Binding domestic production quotas for alternative proteins are accelerating capital deployment into bacterial fermentation facilities across Denmark, Norway, and the Netherlands.
- Salmon aquaculture feed reformulation:Norwegian and Chilean producers are systematically replacing marine ingredients with single-cell protein to meet ASC certification standards and retailer procurement specifications.
- Methane-to-protein platform maturation:Gas fermentation economics are improving as industrial biogas infrastructure scales, enabling bacterial protein production at price points competitive with soybean meal in poultry rations.
Market Restraints
- Natural gas price volatility:Methane substrate costs constitute 35-50% of bacterial protein production economics, exposing margins to European energy market fluctuations.
- EFSA novel feed approval timelines:Strain-by-strain safety assessments for bacterial and fungal proteins create 18-36 month market access delays for new fermentation entrants.
- Fishmeal price cyclicality:Periodic crashes in Peruvian anchovy harvests and subsequent fishmeal price collapses temporarily erode the economic case for microbial protein substitution.
Strategic Opportunities
- Shrimp aquaculture in Southeast Asia:Thailand, Vietnam, and Indonesia represent underpenetrated demand pools where bacterial protein can displace fishmeal and soy protein concentrate in grow-out feeds.
- Carbon credit monetization:EU Emissions Trading System integration and voluntary carbon markets allow fermentation operators to capture additional revenue streams from methane capture and protein production.
- Precision fermentation for high-value ingredients:Convergence of synthetic biology and downstream processing is enabling production of tailored amino acid profiles for premium pet nutrition and specialty aquaculture.
Industry Challenges
- Industrial microbiology talent scarcity:Fermentation scale-up expertise and strain optimization capabilities are concentrated among a limited pool of specialists in Denmark, the Netherlands, and California.
- Downstream processing capex intensity:Spray drying, cell lysis, and protein concentration equipment require substantial capital commitments that strain mid-scale fermentation operators.
- Cross-border regulatory divergence:Divergent FDA and EFSA safety assessment protocols for novel microbial strains force duplicate clinical and toxicological studies, inflating registration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Protein Used in Feed Market |
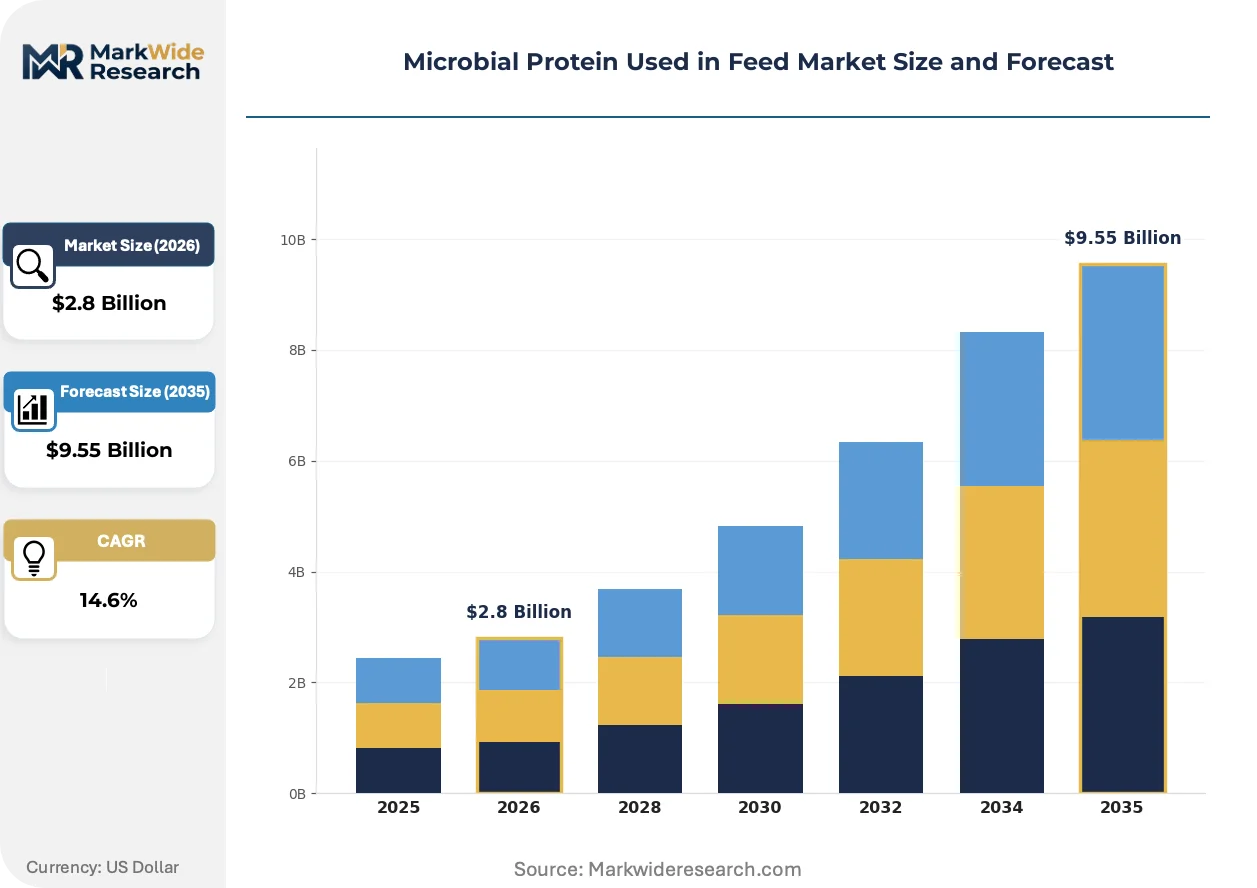
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Cell Protein, Yeast Extract, Bacterial Protein, Fungal Protein Livestock Type: Poultry, Swine, Aquaculture, Ruminants Form: Dry Powder, Liquid, Pellets, Granules End Use: Animal Nutrition, Aquafeed, Livestock Feed, Specialty Feed |
| Companies Covered | Calysta, Inc., ENOUGH (3F Bio Ltd.), KnipBio, Avecom, Arbiom, Alltech, Nutreco N.V., Lonza Group, Unibio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Protein Used in Feed Market Shifts & Advancements
Continuous fermentation systems and automated bioprocess control are compressing unit economics and enabling production scale previously unattainable with batch methods. These advances are reconfiguring competitive positioning toward technology-intensive operators with advanced process engineering capabilities.
Gas fermentation using methanotrophic bacteria is rendering obsolete conventional substrate-dependent protein production. Salmon feed formulators in Norway are adopting bacterial protein at commercial scale within 18-month procurement cycles. This technology is collapsing the historical link between agricultural land use and protein output density.
EFSA's streamlined novel food and feed approval pathways under the EU Green Deal implementation are accelerating strain registration timelines for fermentation-derived ingredients. Industrial biotechnology firms are pre-submission consulting with Parma-based assessors to align toxicology packages with evolving guidance documents. Aquafeed compounders in Scotland and Denmark are prioritizing EFSA-registered bacterial proteins to secure supply contracts with major retailers.
Compound feed manufacturers are consolidating procurement decisions at corporate headquarters, bypassing regional purchasing managers who historically selected protein ingredients based on spot pricing. This centralization is displacing fragmented spot-market sourcing with multi-year offtake agreements directly with fermentation operators. The shift is most visible in North Sea aquaculture corridors where Nutreco, BioMar, and Cargill Aquaculture Nutrition coordinate global protein procurement strategies from centralized supply chain functions.
Microbial Protein Used in Feed Market Segmentation
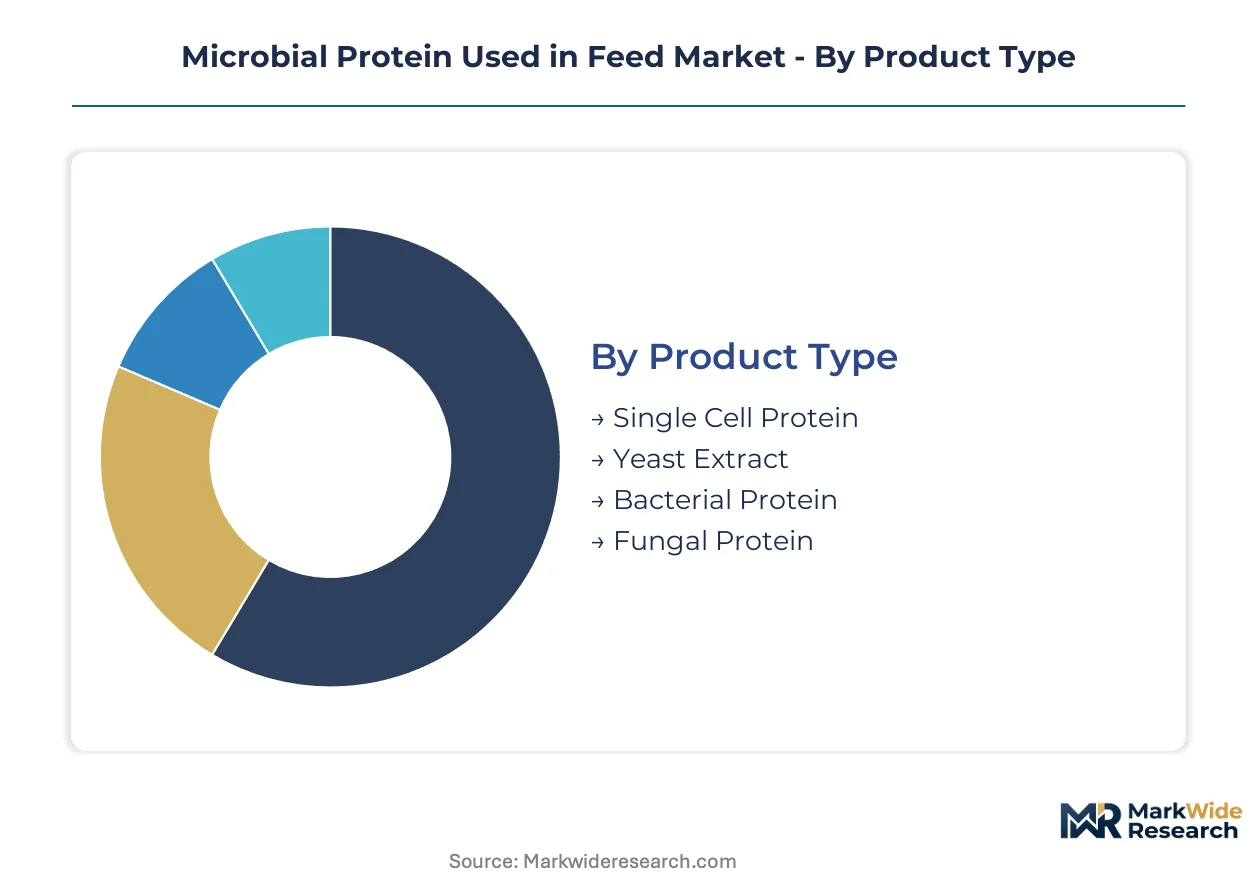
Protein source differentiation and livestock-specific formulation requirements create distinct margin pools across the microbial protein value chain. Each segmentation dimension reveals divergent capital intensity, regulatory exposure, and customer concentration patterns that shape competitive strategy.
Product Type:
Cost tier positioning separates commodity-scale fermentation outputs from premium nutritional concentrates.
- Single Cell Protein:Dried biomass from bacterial or yeast fermentation containing 50-80% crude protein with standardized amino acid profiles for compound feed integration. Poultry and swine compounders in North America and Europe dominate procurement volumes due to established nutritional databases and least-cost formulation software compatibility.
- Bacterial Protein:Methanotrophic cultivation yields protein concentrates with favorable methionine and lysine ratios for salmonid nutrition. Norwegian aquafeed manufacturers are accelerating offtake agreements to meet ASC certification requirements and reduce marine ingredient dependency.
- Yeast Extract:Autolyzed yeast fractions providing nucleotides and peptides for palatability enhancement in premium pet and specialty aquaculture diets.
- Fungal Protein:Mycelial biomass from submerged fermentation with high fiber content suited for ruminant and specialty monogastric applications.
Single Cell Protein holds installed capacity. Bacterial Protein is rotating up the share rankings.
Livestock Type:
Application-specific nutritional standards and certification requirements fragment demand across species.
- Aquaculture:Salmon and shrimp producers face binding fishmeal substitution mandates from retailers and certification bodies. Chilean and Norwegian feed compounders are reformulating grow-out diets with bacterial protein to meet marine ingredient reduction targets.
- Poultry:Broiler and layer operations integrate single cell protein into least-cost rations where amino acid density justifies price premiums over soybean meal. US integrators are testing methane-derived protein in grower-finisher phases.
- Swine:Nursery and grower diets incorporate yeast-derived fractions for gut health modulation in antibiotic-free production systems.
- Ruminants:Dairy and beef operations utilize fungal protein as bypass protein sources, though rumen degradation characteristics limit inclusion rates.
Aquaculture is gaining share fastest. Poultry retains volume leadership.
Form:
Logistics economics and shelf stability requirements determine margin capture across physical formats.
- Dry Powder:Spray-dried biomass with 12-18 month stability and bulk handling compatibility for compound feed mills. Coastal aquafeed producers in Scotland and Denmark prefer powder form for automated inclusion systems and ocean freight efficiency.
- Liquid:Live fermentation broth or concentrated suspensions requiring refrigerated distribution chains. Proximity to end-use facilities constrains viable supply radius.
- Pellets:Agglomerated protein concentrates with binders for direct feeding or on-farm mixing applications.
- Granules:Intermediate particle size for specialty feed manufacturers with limited grinding capacity.
Dry Powder commands logistics efficiency. Liquid is climbing the fastest.
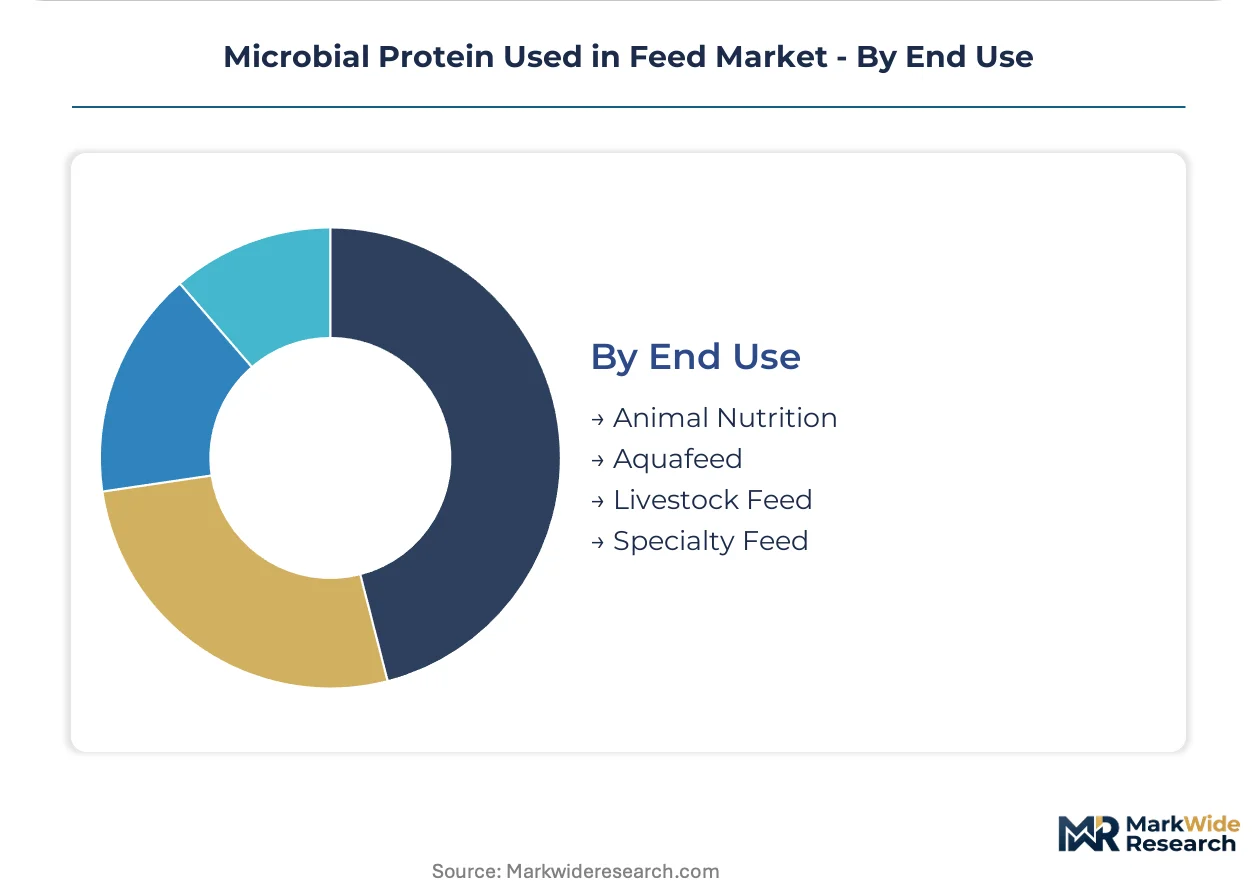
End Use:
Customer type concentration and certification intensity separate commodity feed from premium nutrition segments.
- Aquafeed:Salmon, shrimp, and marine finfish diets with strict marine ingredient reduction specifications. Scottish and Norwegian compounders are consolidating procurement at corporate level to secure EFSA-registered bacterial protein supply.
- Animal Nutrition:Broad category encompassing monogastric and ruminant compound feeds where microbial protein displaces conventional oilseed meals.
- Livestock Feed:Integrated poultry and swine operations with captive feed mills optimizing least-cost formulations.
- Specialty Feed:Premium pet nutrition and exotic animal diets requiring tailored amino acid profiles and palatability standards.
Aquafeed is expanding most quickly. Animal Nutrition holds baseline volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in Denmark, Norway, and the Netherlands are redirecting protein supply flows toward North Sea aquaculture corridors. Methane-accessible industrial zones and nitrogen-handling port infrastructure determine viable production locations.
Norway
Salmon feed compounders in Bergen and Ålesund are reformulating grow-out diets with bacterial protein to satisfy ASC certification mandates from supermarket retailers. The Norwegian Food Safety Authority coordinates with EFSA on novel feed strain approvals. Industrial biogas facilities in western fjord regions supply methane substrate to fermentation pilots.
Denmark
Integrated poultry operations near Aarhus and Odense are testing single-cell protein in broiler rations to reduce soybean meal dependency. Danish Veterinary and Food Administration enforcement of EU Green Deal protein autonomy targets accelerates domestic fermentation investments. The Kalundborg industrial symbiosis cluster hosts gas-to-protein demonstration plants.
Netherlands
Compound feed manufacturers in the Feed Valley corridor between Utrecht and Zwolle are consolidating procurement decisions at headquarters level. Dutch Authority for Consumers and Markets oversight ensures compliance with EU F-Gas Regulation emissions standards. Port of Rotterdam nitrogen handling infrastructure supports bacterial protein import and processing logistics.
Chile
Salmon producers in the Los Lagos and Aysén regions are contracting bacterial protein supply to meet marine ingredient reduction commitments. Chilean National Fisheries Service (SERNAPESCA) regulates novel feed ingredient safety assessments. Puerto Montt aquafeed manufacturing clusters coordinate directly with European fermentation operators for strain-qualified supply.
United States
Poultry integrators in the Southeast and Midwest are evaluating methane-derived protein for grower-finisher phases to diversify amino acid sourcing. FDA Center for Veterinary Medicine and USDA-APHIS jointly oversee fermentation substrate safety and labeling requirements. Houston Ship Channel petrochemical corridors provide industrial methane access for bacterial protein production scale-up.
Microbial Protein Used in Feed Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The market structure concentrates around technology-intensive operators with advanced fermentation process engineering capabilities and established regulatory approval pathways. Three archetypes dominate: methane-to-protein platform operators, integrated fermentation-downstream processors, and compound feed manufacturers with captive distribution. Capacity expansion along coastal industrial corridors and multi-year offtake agreements with aquafeed compounders constitute the primary competitive moves.
Within the platform operator tier, Calysta, Inc. and ENOUGH (3F Bio Ltd.) exemplify divergent substrate strategies. Calysta anchors North American methane-to-protein production scale. ENOUGH sustains integrated fermentation and processing capabilities across European supply chains. Nutreco N.V. occupies a position linking microbial protein directly into compound feed formulations through controlled distribution channels.
| Leading Market Players |
|---|
| Calysta, Inc. |
| ENOUGH (3F Bio Ltd.) |
| KnipBio |
| Avecom |
| Arbiom |
| Alltech |
| Nutreco N.V. |
| Lonza Group |
| Unibio |
| Others |
Supply & Pricing Matrix
The North Sea aquafeed corridor's bulk freight economics compress bacterial protein margins for suppliers distant from methane-accessible port infrastructure. EFSA novel feed approval status and EU Green Deal protein autonomy quotas create tiered buyer access that concentrates pricing power among registered fermentation operators serving Norwegian and Danish compounders.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across the microbial protein value chain. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-registered bacterial protein for ASC-certified aquafeed from unregistered strains for poultry rations and commodity yeast extracts. Cost compression in standard tiers is intensifying because natural gas price volatility feeds directly into methane substrate economics. Poultry integrators in the US Southeast exhibit highest price sensitivity, while Norwegian salmon feed compounders prioritize certification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated fermentation operators in Denmark, the Netherlands, and Norway that control both bioreactor capacity and downstream spray-drying infrastructure. Raw material dependencies draw from industrial biogas methane, nitrogen-handling port logistics, and specialized autolyzed yeast feedstocks. Single-source vulnerability runs through the Kalundborg industrial symbiosis cluster's concentrated gas-to-protein demonstration capacity. Distribution runs through multi-year offtake agreements directly linking fermentation operators to compound feed headquarters procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial microbiology talent scarcity constrains fermentation scale-up velocity, with strain optimization expertise concentrated among specialists in Denmark, the Netherlands, and California. This capability gap defines competitive durability for platform operators seeking to anchor supply contracts with North Sea aquafeed compounders.
For Market Incumbents: Build regulatory approval moats by accelerating EFSA novel feed strain registrations ahead of EU Green Deal protein autonomy quota enforcement. Secure captive methane supply through backward integration into industrial biogas infrastructure near Aarhus and Bergen. Deepen upstream control over spray-drying capacity to defend margin position against mid-scale fermentation entrants facing downstream processing capex intensity. For New Entrants and Emerging Players: Build out shrimp aquaculture penetration in Thailand and Vietnam where fishmeal substitution mandates remain underenforced and local bacterial protein supply is undeveloped. Target precision fermentation for premium pet nutrition amino acid profiles as the most penetrable segment bypassing commodity poultry and swine volume competition. Lead with carbon credit monetization narratives to differentiate methane-capture protein offerings in EU Emissions Trading System jurisdictions. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors with stranded methane assets and underutilized fermentation pilot capacity. Long-term viability hinges on operators achieving price parity with soybean meal in poultry rations while maintaining aquafeed premium positioning. Monitor EFSA approval timeline compression as the inflection signal indicating regulatory pathway maturation for bacterial protein platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Feed Strain Registration | Unlocks supply contracts with ASC-certified Norwegian salmon compounders facing retailer marine ingredient reduction mandates. |
| Methane Supply Backward Integration | Anchors production economics against European natural gas price volatility through captive industrial biogas offtake. |
| Continuous Fermentation Scale-Up | Compresses unit costs below batch-method competitors via automated bioprocess control at coastal industrial zones. |
| Multi-Year Aquafeed Offtake Agreements | Bypasses spot-market fragmentation by locking corporate procurement decisions at Nutreco and BioMar headquarters level. |
| Carbon Credit Monetization Program | Captures EU ETS revenue streams from methane capture and protein production co-benefits in Kalundborg-style clusters. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation process engineers, aquafeed formulation specialists, EFSA regulatory affairs consultants, and compound feed procurement directors and refined through secondary validation against EU F-Gas Regulation implementation documents, EFSA novel food and feed approval pathway guidance, SEC filings from publicly traded feed manufacturers, and trade data tracking fishmeal substitution trends. Bottom-up strain-by-strain production capacity estimates were triangulated against top-down protein displacement projections across poultry, swine, and aquaculture species.
Demand-supply balance modeling across the projection horizon incorporated segmentation by protein source type, livestock application, physical form, and end-use customer concentration. CAGRs were derived from least-squares fitting of annual volume trajectories adjusted for EFSA approval timeline delays and methane substrate cost scenarios. Industry-specific forecast inputs included salmon aquaculture marine ingredient reduction commitments under ASC certification and EU Green Deal protein autonomy target enforcement schedules.
Stress conditions across natural gas price bands, EFSA approval timeline distributions, and Peruvian anchovy harvest cyclicality were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of EFSA novel feed registration queue depth and North Sea aquafeed corporate procurement centralization announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Eubiotics Market
Industrial Microbiology
Lactic Acid Bacteria Market
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Specialty Cultures Market